
 Europe Textile Fabrics Market | 2026-2036
Europe Textile Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Fabrics Market Insights
Digital textile printing is fragmenting conventional dyeing and weaving workflows across European mills. Lenzing Group leverages wood-based cellulosic fiber platforms to anchor sustainable feedstock supply. BASF competes through polymer chemistry leadership in high-performance industrial yarns. AMANN Group specializes in engineered sewing threads for automotive and medical applications.
Textile fabrics encompass woven, knitted, and non-woven sheet materials constructed from natural or synthetic fibers, typically measured in grams per square meter for weight and thread count for density, serving as foundational substrates for apparel, furnishings, and industrial composites. Polyester dominates volume across apparel and home textile applications due to cost efficiency and durability. Eco-Friendly grade fabrics represent the fastest-expanding margin pool as REACH compliance and EU Green Deal targets redirect procurement toward recycled and bio-based alternatives. Premium and Luxury grades sustain higher per-unit economics in Italian fashion supply chains despite smaller absolute volumes.
EMA oversees chemical safety through REACH registration requirements that restrict hazardous substances in textile finishing. ECHA enforces SVHC disclosure obligations that reshape dye formulations and water treatment investments. The EU Green Deal's circular textile strategy mandates extended producer responsibility schemes that alter cost structures for brands and converters. Stakeholders must monitor how the EU AI Act's risk classification rules affect automated visual inspection systems deployed in quality control workflows.
Market Dynamics
Digital textile printing is collapsing conventional dyeing workflows across European mills, while REACH compliance and the EU Green Deal's circular textile strategy simultaneously restructure cost structures and feedstock sourcing priorities for converters and brands.
Growth Catalysts
- EU Green Deal circular textile mandates:Extended producer responsibility schemes redirect procurement toward recycled and bio-based fiber alternatives, expanding addressable margin pools for sustainable-grade converters.
- Automotive electrification surge:German and Italian EV manufacturers scale technical textile procurement for lightweight interior components and battery compartment insulation.
- Wood-based cellulosic fiber platforms:Lenzing Group's Tencel and Refibra production anchors sustainable feedstock supply chains serving fashion and home textile end-uses.
Market Restraints
- Energy cost volatility:Natural gas price fluctuations in Germany and Italy compress margins for wet-processing mills dependent on thermal dyeing operations.
- Feedstock concentration risk:Polyester staple fiber supply concentrates among Asian petrochemical complexes, exposing European weavers to shipping cost and currency volatility.
- REACH SVHC disclosure friction:ECHA's evolving restricted substance list forces continuous reformulation of dye auxiliaries and finishing chemicals, extending R&D cycles.
Strategic Opportunities
- Medical textile expansion:Antimicrobial woven and non-woven fabrics for surgical gowns and wound care represent underpenetrated demand within EU healthcare procurement frameworks.
- CSRD reporting alignment:Corporate sustainability reporting mandates create first-mover advantage for mills with certified carbon accounting and supply chain traceability systems.
- Digital printing convergence with AI:Automated color matching and predictive maintenance integration compress make-ready times and reduce dye waste for short-run fashion orders.
Industry Challenges
- Skilled technician scarcity:Digital loom operation and color management expertise gaps constrain mill modernization timelines in Portugal and Romania.
- Legacy ERP integration complexity:Batch-size-one production workflows require reconfiguration of inventory and scheduling systems rooted in mass-production logic.
- Multi-certification timeline compression:Simultaneous OEKO-TEX, GOTS, and EU Ecolabel audits strain quality assurance bandwidth for mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Fabrics Market |
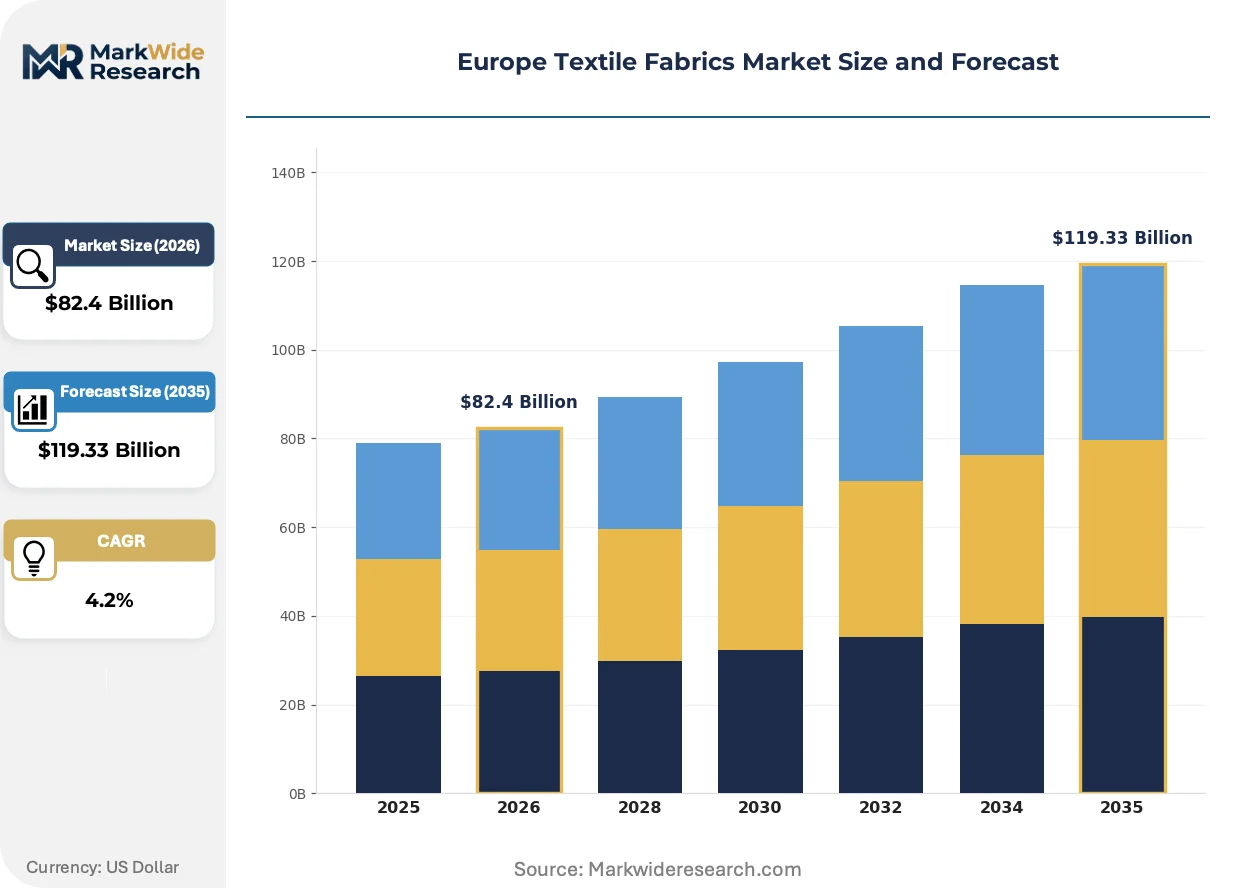
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $119.33 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Silk, Wool End User: Fashion Industry, Interior Design, Automotive, Healthcare Application: Apparel, Upholstery, Industrial, Home Textiles Grade: Standard, Premium, Eco-Friendly, Luxury |
| Companies Covered | AMANN Group, Reju, Lenzing Group, Toray Industries, BASF, Beaulieu International Group, Getzner Textil, Milliken & Company, European Spinning Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Fabrics Market Trends and Innovations
Three intersecting forces reshape European textile production: digital workflow compression, regulatory chemistry constraints, and procurement model fragmentation toward micro-batch responsiveness.
Single-pass digital textile printing is collapsing rotary screen and flatbed analog workflows across Portuguese and Italian mills. Fast-fashion brands and sportswear labels adopt inkjet systems for runs below five hundred meters. The technology compresses lead times from weeks to days and eliminates screen engraving costs for seasonal collections.
REACH authorization requirements for chromium-based dye mordants and certain azo compounds force reformulation of coloration chemistry across finishing houses. ECHA's SVHC candidate list expansion triggers substitution investments in bio-based thickeners and low-impact reactive dyes. Italian luxury supply chains absorb compliance premiums most readily, while commodity apparel converters face margin compression.
Micro-batch procurement models displace traditional minimum-order-quantity contracts between brands and mills. Direct-to-consumer labels in France and the Netherlands source fabric quantities below historical economic thresholds, enabled by digital printing and on-demand cutting integration. This fragmentation concentrates volume volatility risk with converters while transferring inventory carrying costs downstream to brands.
Europe Textile Fabrics Market Segmentation
Segmentation reveals how procurement priorities diverge across European textile converters. Fiber chemistry, end-use specifications, and sustainability certifications reshape margin structures and supplier selection criteria.
Product Type:
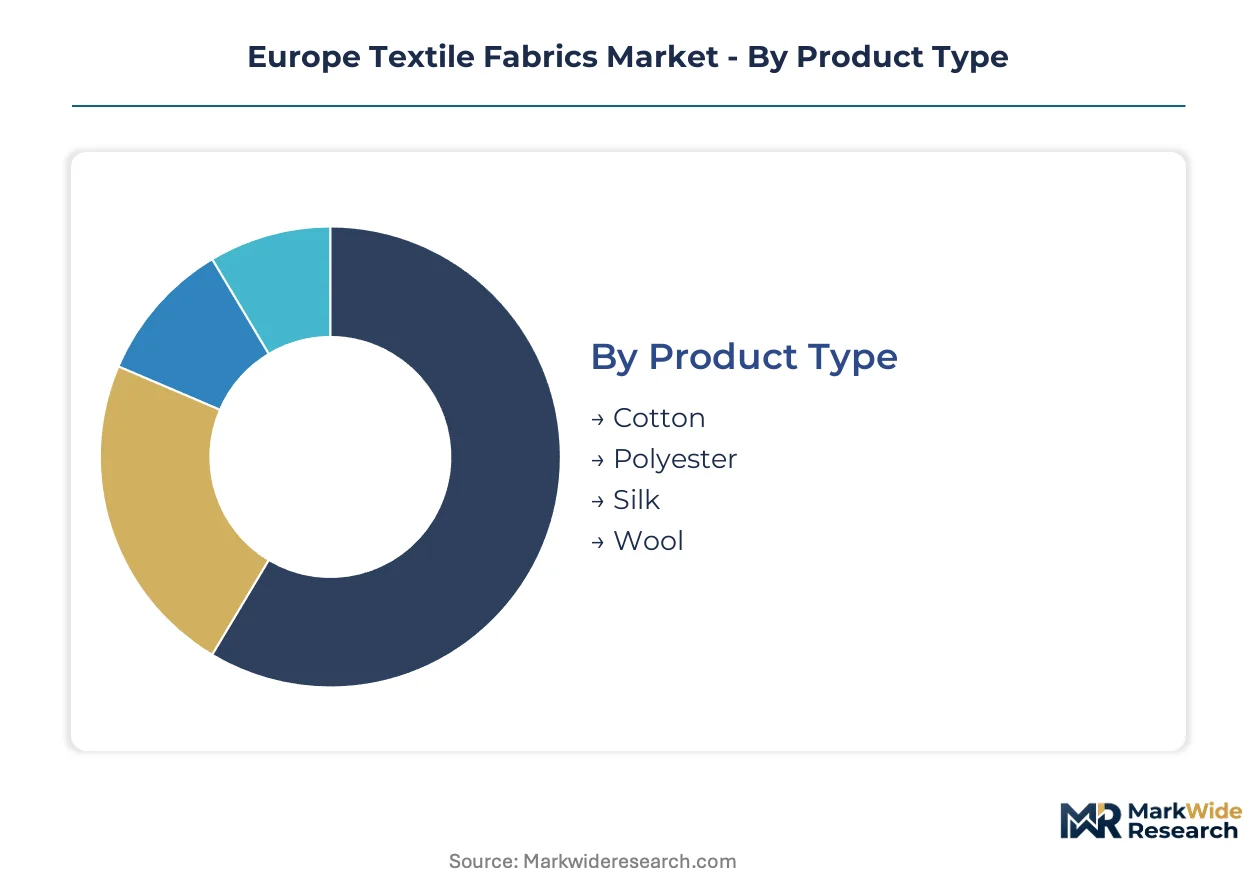
Polyester and cotton anchor volume procurement across apparel and technical applications, while silk and wool serve narrower premium niches with distinct supply chain requirements.
- Polyester:Petroleum-derived synthetic fiber dominating volume throughput across Portuguese and Turkish weaving mills serving fast-fashion supply chains. German automotive converters source high-tenacity industrial grades for seatbelt webbing and airbag substrates under REACH-compliant finishing protocols.
- Cotton:Cellulosic staple fiber prized for breathability in Mediterranean summer apparel collections. Italian spinning mills in Biella and Prato concentrate premium long-staple procurement, while mass-market converters face margin pressure from volatile lint prices and water-intensive processing costs.
- Silk:Protein fiber from Bombyx mori cocoons sustaining artisanal weaving traditions in Como and Lyon.
- Wool:Keratin-based animal fiber from Merino and Shetland breeds anchoring Scottish and Irish tweed production.
The dominant share belongs to polyester, while eco-friendly alternatives are closing the gap fastest.
End User:
Cost tier stratification separates commodity converters from certified suppliers serving regulated industries.
- Fashion Industry:Apparel brands and contract manufacturers sourcing seasonal collections across woven shirting, denim, and outerwear substrates. Paris and Milan design houses drive micro-batch digital printing adoption for runway-to-retail acceleration.
- Automotive:Tier-1 seating and interior trim suppliers in Stuttgart and Turin procuring technical textiles for flame-retardant headliners and battery compartment insulation. EU vehicle safety directives mandate specific abrasion and fogging performance thresholds.
- Interior Design:Hospitality and residential furnishing specifiers selecting upholstery fabrics for contract durability ratings.
- Healthcare:Hospital procurement frameworks and medical device manufacturers sourcing antimicrobial non-wovens for surgical drapes and wound contact layers.
Fashion industry procurement commands the largest order book, though automotive technical specifications yield the highest per-meter margins.
Application:
Volume concentration in apparel contrasts with specialized performance requirements for industrial composites.
- Apparel:Woven and knitted constructions for shirts, trousers, dresses, and outerwear serving mass-market and premium fashion labels. Portuguese mills specialize in quick-turnaround jersey knits for Spanish and French retailers.
- Industrial:High-performance fabrics for filtration, geotextiles, and composite reinforcement. German technical weavers in Baden-Württemberg supply carbon fiber preforms and aramid ballistic panels for aerospace and defense contractors.
- Home Textiles:Bed linens, tablecloths, and decorative fabrics for hospitality and residential channels.
- Upholstery:Heavy-duty woven and tufted constructions for furniture and automotive seating applications.
Apparel absorbs the greatest fiber volume, yet industrial applications sustain the steepest expansion trajectory as electrification and lightweighting priorities accelerate.
Grade:
Certification tier determines market access and pricing power across EU procurement frameworks.
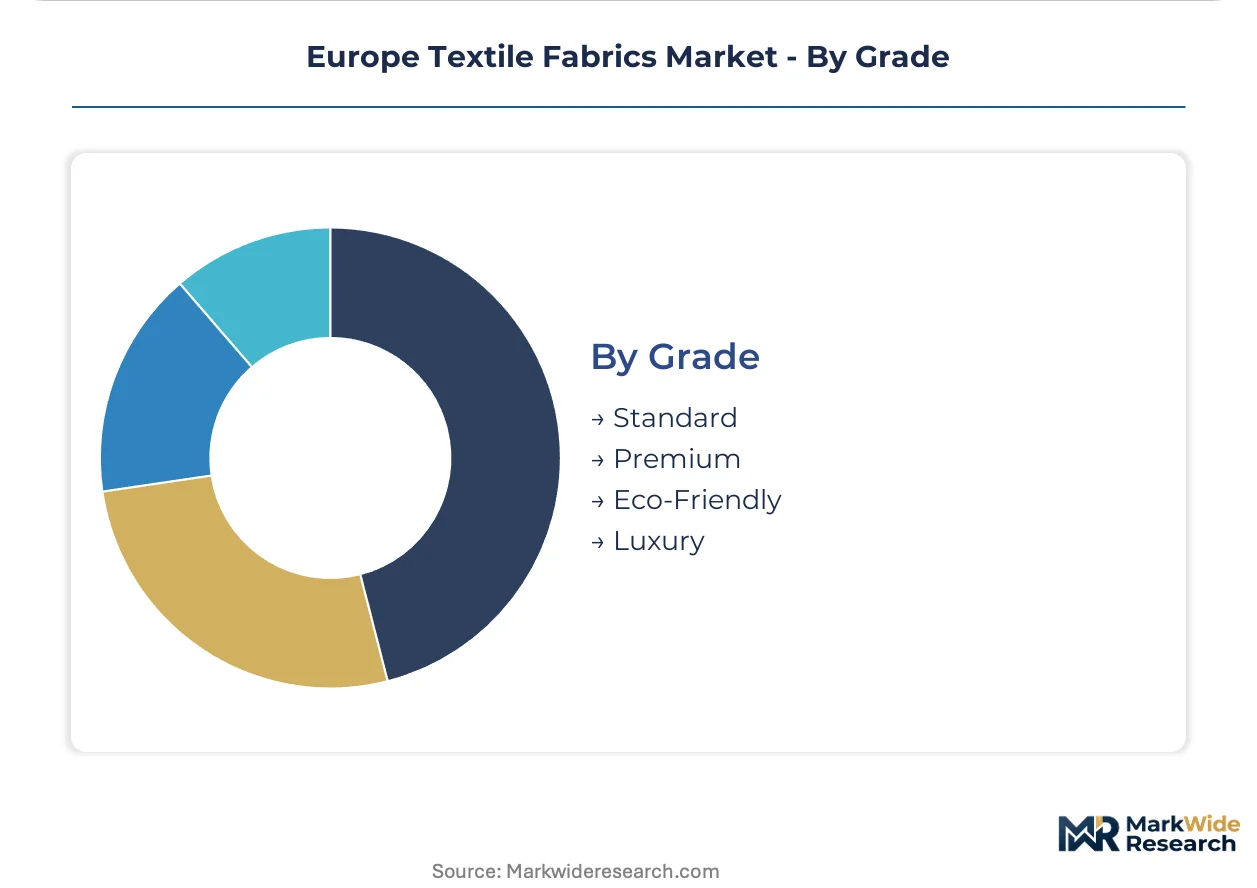
- Eco-Friendly:Recycled polyester from post-consumer PET, organic cotton under GOTS certification, and Lenzing Group cellulosics meeting EU Ecolabel criteria. Brands facing CSRD disclosure mandates prioritize these grades for scope 3 emissions reduction.
- Standard:Conventional fiber grades without third-party sustainability certification serving price-sensitive volume channels.
- Premium:Finer yarn counts, specialized finishing, and design house exclusivity commanding 40-60% markups over standard grades.
- Luxury:Artisanal production from heritage mills with geographic indication protection, limited batch sizes, and bespoke color matching for haute couture ateliers.
Standard grade still moves the most meters, though eco-friendly certification is gaining share fastest as extended producer responsibility schemes take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and luxury fashion houses concentrate procurement across Germany, Italy, and France, while technical textile demand from EV battery insulation and circular economy mandates reshapes converter investment priorities.
Germany
Stuttgart and Munich OEMs scale technical textile procurement for electric vehicle battery compartment insulation and lightweight seat structures. REACH SVHC disclosure obligations from ECHA force continuous reformulation of flame-retardant finishing chemistry. The Baden-Württemberg technical textiles corridor anchors carbon fiber preform and aramid weaving capacity for aerospace and defense contractors.
Italy
Milan and Turin design houses drive micro-batch digital printing adoption for runway-to-retail acceleration. EU Green Deal circular textile mandates redirect Como silk and Prato wool converters toward GOTS-certified organic fiber streams. The Biella spinning district concentrates premium long-staple cotton procurement for luxury shirting and suiting applications.
France
Parisian haute couture ateliers and Lyon-based furnishing specifiers sustain demand for heritage weaving and bespoke color matching. CSRD reporting requirements create first-mover advantage for mills with certified carbon accounting systems. The Alsace technical textiles cluster supplies antimicrobial non-wovens for hospital procurement frameworks.
United Kingdom
Scottish and Irish tweed producers anchor keratin-based wool weaving for heritage outerwear brands. The country's national chemical regulator enforces REACH-aligned restrictions on azo dyes and chromium mordants. Yorkshire worsted mills specialize in fine-gauge suiting fabrics for London-based tailoring houses.
Spain
Barcelona and Madrid fast-fashion retailers source quick-turnaround jersey knits from Portuguese partner mills. Extended producer responsibility schemes under EU circular textile strategy alter cost structures for domestic converters. The Valencia region concentrates upholstery fabric weaving for hospitality and residential furnishing channels.
Europe Textile Fabrics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification and end-use segments. The vendor base organizes around three archetypes: integrated fiber-to-fabric converters, specialty chemical suppliers, and engineered thread specialists. Consolidation pressure concentrates among mid-cap mills lacking CSRD-compliant traceability systems. Dominant competitive moves include strategic partnerships for recycled feedstock security and capacity expansion in wood-based cellulosic platforms.
Within the fiber-platform archetype, Lenzing Group anchors sustainable cellulosic supply chains serving fashion and home textile end-uses. Among diversified chemical suppliers, BASF occupies a position representing polymer chemistry leadership in high-performance industrial yarns. At the engineered-thread specialization tier, AMANN Group exemplifies technical sewing thread production for automotive and medical applications.
| Leading Market Players |
|---|
| AMANN Group |
| Reju |
| Lenzing Group |
| Toray Industries |
| BASF |
| Beaulieu International Group |
| Getzner Textil |
| Milliken & Company |
| European Spinning Group |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's technical textiles corridor anchors carbon fiber and aramid weaving capacity that commands premium pricing power over commodity converters in Portugal and Turkey. REACH-compliant finishing protocols and EU Green Deal circular mandates reshape cost structures across certification tiers, concentrating margin advantage with mills possessing verified traceability systems.
Pricing Analysis
Polyester staple contracts index to petrochemical feedstock benchmarks with quarterly adjustment clauses that transfer crude volatility risk to European weavers. Three-tier pricing structure across eco-friendly, standard, and premium certification levels separates GOTS-certified organic cotton from conventional grades by 25-40% at wholesale. Pricing pressure stems from energy cost volatility in German wet-processing mills, with fast-fashion buyers in Spain exhibiting highest price sensitivity while Italian luxury houses absorb compliance premiums with minimal volume elasticity.
Supply Chain Analysis
Dual-use export controls on carbon fiber precursor technology constrain supply flows from US and Japanese chemical producers to European aerospace weavers. Raw material dependencies center on PTA and MEG for polyester polymerization, wood pulp for Lenzing Group cellulosics, and long-staple cotton from Egyptian and US delta growers. Single-source vulnerability concentrates in Asian petrochemical complexes supplying polyester chip, while distribution runs through Rotterdam and Hamburg port hubs for containerized fiber delivery to Portuguese and Italian mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Textile Fabrics Market rewards mills possessing CSRD-compliant carbon accounting and digital workflow integration capabilities that mid-cap competitors struggle to replicate. Scarcity of color management technicians and REACH formulation chemists concentrates competitive advantage with established technical textiles corridors.
For Market Incumbents: Harden supply chain resilience through backward integration into recycled PET flake processing and certified organic cotton ginning partnerships in Mediterranean sourcing zones. Anchor position in Baden-Württemberg and Biella production clusters against emerging technical textile competitors from Central European accession states by accelerating OEKO-TEX and GOTS multi-certification coverage ahead of extended producer responsibility enforcement. For New Entrants and Emerging Players: Build out micro-batch digital printing capacity serving direct-to-consumer labels in France and the Netherlands with sub-five-hundred-meter minimum order quantities. Medical textile applications for antimicrobial non-wovens represent the most penetrable white-space segment within EU healthcare procurement frameworks, with Alsace and Yorkshire clusters offering contract manufacturing partnership entry points. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mills with installed digital printing infrastructure and established REACH compliance protocols over greenfield analog capacity. Long-term viability across the analysis window hinges on CSRD disclosure readiness and scope 3 emissions traceability systems. Acquisition targets should demonstrate certified carbon accounting and wood-based cellulosic fiber platform partnerships. The signal to watch is acceleration of EU Green Deal circular textile mandate enforcement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captures margin from post-consumer PET collection and flake processing ahead of EPR schemes. |
| Digital Printing Platform Expansion | Compresses lead times for micro-batch orders from Paris and Milan design houses. |
| Multi-Certification Acceleration | Secures market access under simultaneous OEKO-TEX, GOTS, and EU Ecolabel audit requirements. |
| Medical Textile Capacity Buildout | Targets antimicrobial non-woven demand from hospital procurement frameworks in France and Germany. |
| CSRD-Compliant Traceability Investment | Enables scope 3 emissions reporting for fashion brands facing mandatory disclosure obligations. |
Research Methodology
Cross-validation between mill operator interviews and customs trade data anchors the qualitative findings on feedstock sourcing patterns across the analysis window. Primary fieldwork encompassed technical textiles procurement managers at Stuttgart and Turin automotive OEMs, dye house formulators navigating ECHA SVHC restrictions, and sustainability officers at Lenzing Group and BASF. Secondary validation drew from EUROSTAT textile production statistics, ECHA restricted substance registry updates, and CSRD implementation guidance documents. Bottom-up capacity assessments and top-down end-use demand triangulation produced convergent volume estimates.
Calibration against historical polyester staple price series and wood pulp cost indices refined the projection framework across fiber type, end-use industry, and certification grade segmentation. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive electrification content forecasts and circular textile mandate compliance timelines. Industry-specific inputs included EV battery compartment insulation technical specifications and digital printing adoption rates from Portuguese and Italian mill surveys.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish petrochemical-integrated weavers or accelerated EU AI Act enforcement on automated quality control would shift outcomes. Material shifts in REACH authorization timelines for chromium-based mordants or natural gas price trajectories in Germany would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Denim Fabric Market