
 Global Textile Yarn Market | 2026-2036
Global Textile Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Yarn Market Outlook
Subscription-based fiber traceability services is recalibrating how textile yarn value gets captured and sold. Parkdale Mills leverages its vertical integration across US cotton gins to sustain premium positioning in ring-spun segments. Toray Industries anchors its competitive stance through advanced polymer R&D in Japan, while Lenzing Group differentiates via proprietary lyocell manufacturing scale in Austria and Asia.
Textile yarn comprises continuous strands of interlocked fibers, measured in denier or tex, engineered through ring spinning, open-end spinning, or air-jet methods for tensile strength and uniformity. Cotton yarn maintains mature volume leadership across apparel applications, while technical textiles represent the fastest-expanding margin pool driven by industrial filtration and medical-grade specifications. Polyester yarn dominates home furnishing channels through cost-engineered bulk supply, with nylon retaining specialized positions in high-performance industrial belting.
The EU Green Deal and REACH compliance frameworks in Europe, alongside EPA industrial emissions standards in the United States and China's dual carbon goals administered by MEE, are tightening fiber provenance and chemical disclosure requirements. India's BIS certification mandates and PLI scheme incentives are redirecting domestic capacity toward value-added synthetic outputs. Stakeholders must monitor evolving extended producer responsibility rules and carbon border adjustment mechanisms to align sourcing strategies with compliance-bound buyer procurement criteria.
Market Dynamics
The EU Green Deal's due diligence rules are restructuring fiber sourcing obligations across apparel supply chains, forcing yarn producers to reconfigure procurement networks and traceability systems to retain market access.
Growth Catalysts
- EU Green Deal compliance mandates:Apparel brands must verify fiber provenance, creating pull for certified recycled polyester and lyocell alternatives across European retail channels.
- Technical textile specifications:Industrial filtration and medical-grade applications require engineered yarns with precise denier control, opening premium margin pools outside commodity apparel.
- Vietnam and Bangladesh demand concentration:Southeast Asian garment exporters are scaling sustainable fiber procurement to meet EU buyer requirements, accelerating regional yarn consumption.
Market Restraints
- Petrochemical feedstock volatility:Polyester and nylon production remains exposed to crude oil price swings, compressing margins for synthetic yarn producers during energy market turbulence.
- Chinese capacity dominance:Concentrated polyester spinning in Zhejiang and Jiangsu provinces creates supply-side vulnerability for buyers seeking geographic diversification.
- Natural fiber substitution ceiling:Cotton yarn faces yield constraints from water scarcity in Punjab and Texas, limiting expansion against synthetic alternatives.
Strategic Opportunities
- India PLI scheme incentives:Domestic manufacturers can capture value-added synthetic output subsidies by redirecting capacity from commodity spinning to technical textile grades.
- Blockchain-enabled fiber traceability:Subscription-based verification services allow yarn producers to capture recurring revenue from compliance-bound European apparel brands.
- Carbon border adjustment mechanism preparation:Early adopters of lifecycle carbon accounting can secure preferred supplier status before full EU CBAM enforcement on textile imports.
Industry Challenges
- Polymer science talent scarcity:Advanced lyocell and bio-based fiber R&D requires specialized chemical engineering expertise concentrated in Austria and Japan.
- Ring-to-rotor spinning conversion capex:Legacy equipment replacement for open-end and air-jet methods demands capital deployment that smaller mills struggle to finance.
- Multi-jurisdiction certification synchronization:Simultaneous compliance with REACH, BIS, and EPA disclosure rules creates documentation overhead for exporters serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Yarn Market |
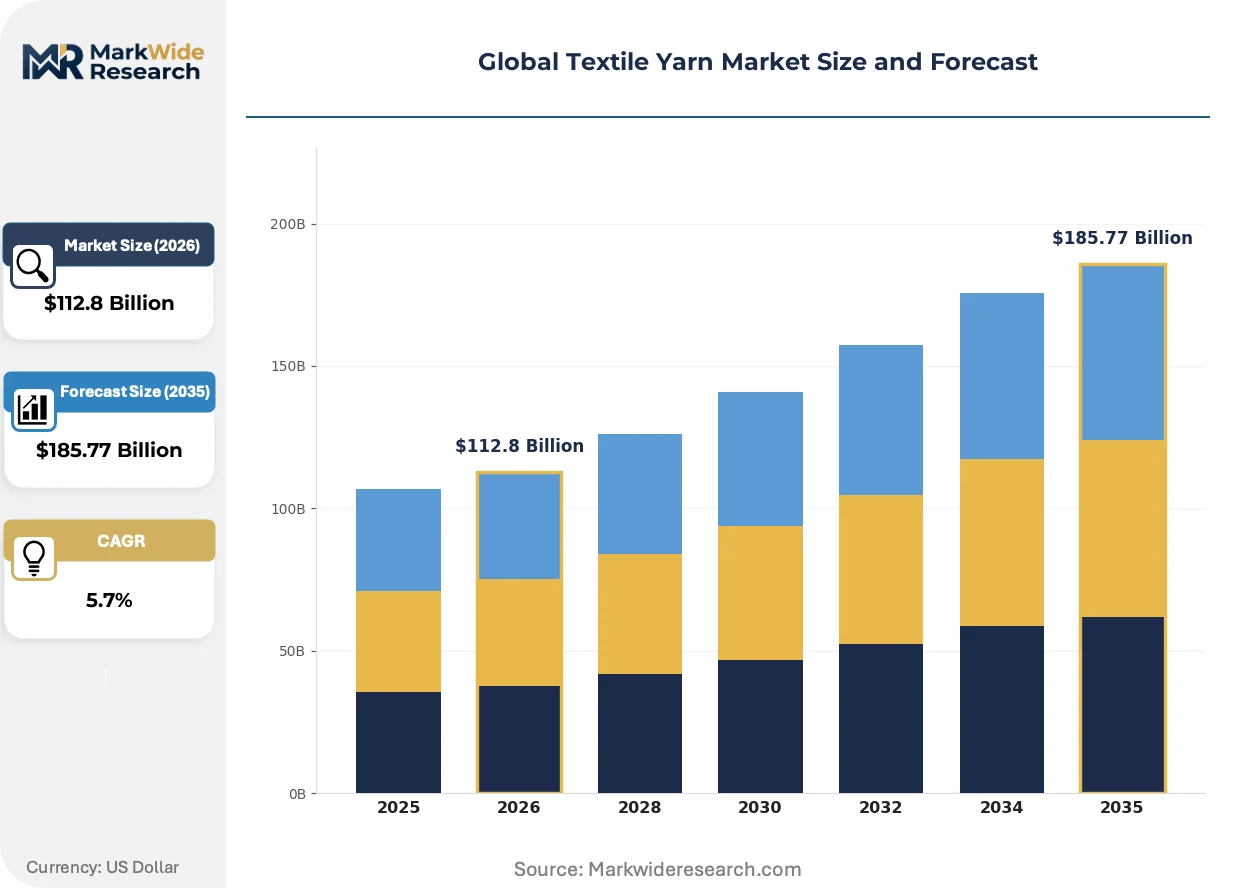
| Market Size in 2026 | $112.8 Billion |
| Market Size in 2035 | $185.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Wool, Nylon Application: Apparel, Home Textiles, Industrial Textiles, Technical Textiles End User: Fashion Brands, Manufacturers, Retailers, Home Furnishing Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Parkdale Mills, Unifi, Toray Industries, Lenzing Group, Arvind Limited, Weiqiao Textile, Milliken & Company, Buhler Quality Yarns, Vardhman Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Yarn Market Strategic Shifts
Digital traceability infrastructure and advanced polymer chemistry are converging to redefine how yarn value gets captured, with compliance technology becoming as critical as tensile performance in supplier selection.
Closed-loop chemical recycling for polyester is rewriting the cost structure of certified recycled fiber production. Industrial filtration and automotive interior suppliers are adopting these inputs at scale. The technology is compressing the premium gap between virgin and recycled polyester, forcing conventional mechanical recyclers to defend margin positions through speed-to-certification.
REACH chemical disclosure expansion is tightening fiber provenance requirements across European textile imports. The regulation now mandates substance-level transparency from polymer pellet to finished yarn. Medical-grade and children's apparel segments are responding fastest, with buyers consolidating supplier bases to reduce audit complexity.
Subscription-based fiber verification is displacing traditional spot-certification models among mid-tier apparel brands. European and North American buyers are unbundling traceability from physical supply, purchasing software-layer compliance as a separate service. This pattern is most visible in denim and activewear verticals where consumer-facing sustainability claims carry pricing power.
Global Textile Yarn Market Segmentation
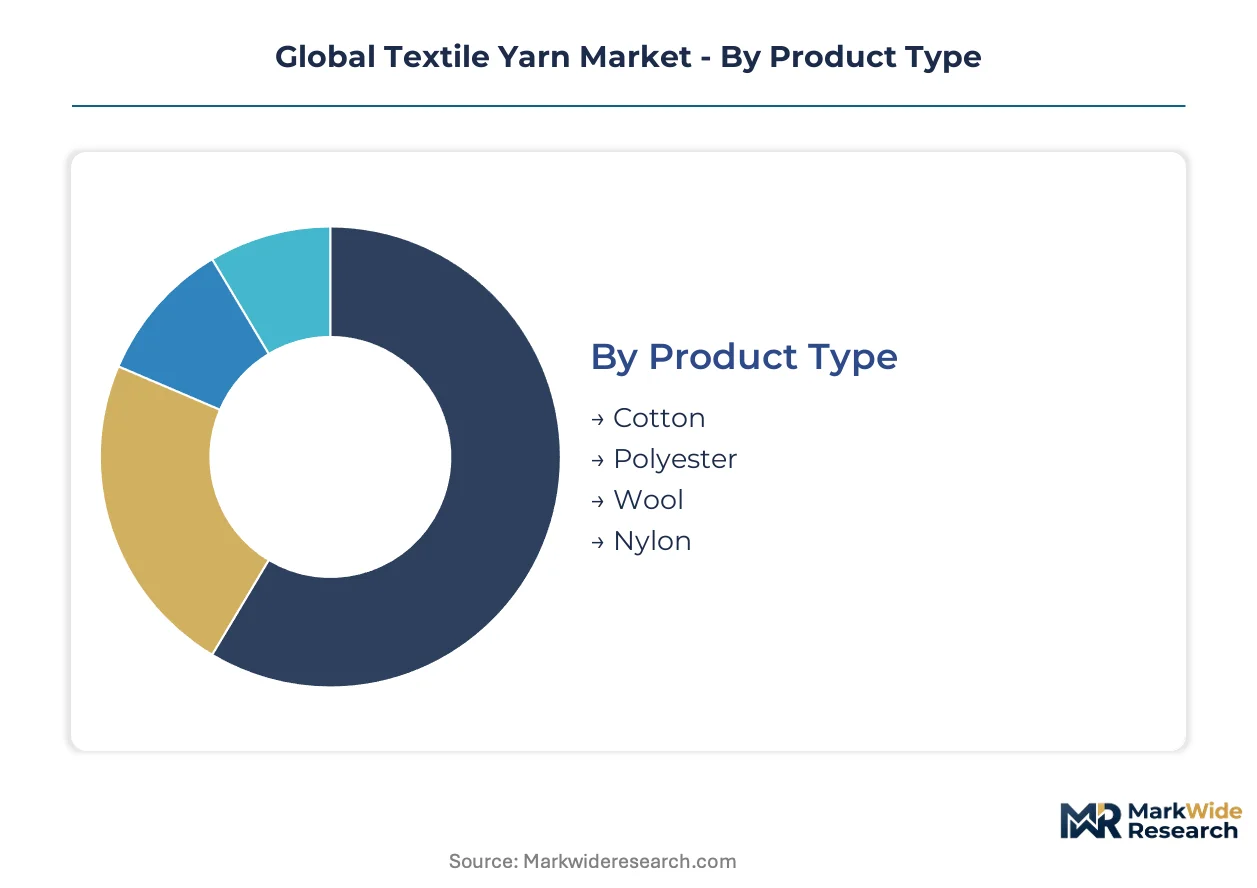
Segmentation in textile yarn markets reveals how fiber chemistry, end-use specifications, and channel economics create distinct margin profiles. Buyers prioritize different performance attributes across apparel versus industrial applications, fragmenting procurement strategies and pricing power.
Product Type:
Supply concentration for natural fibers in specific growing regions contrasts with petrochemical-based synthetics clustered near polymer production hubs.
- Cotton:Staple fiber spun from Gossypium plant bolls, measured in micronaire and staple length for yarn fineness. Apparel demand in Vietnam and Bangladesh drives certified organic procurement, though water stress in Punjab and Texas constrains yield expansion against synthetic alternatives.
- Polyester:Thermoplastic polymer yarn extruded from purified terephthalic acid and ethylene glycol, dominating cost-engineered bulk supply. Zhejiang and Jiangsu provinces concentrate global spinning capacity, creating geographic vulnerability for buyers seeking diversification.
- Wool:Animal fiber from Merino and crossbred sheep, valued for moisture-wicking and thermal regulation in premium outerwear. Australian and New Zealand auctions set global price benchmarks.
- Nylon:Polyamide engineering with high tenacity and abrasion resistance, retaining specialized positions in industrial belting and performance activewear. PA6 and PA6,6 polymer grades differentiate end-use suitability.
Today's leader: Polyester. Tomorrow's challenger: Cotton under regenerative agriculture certification.
Application:
Cost tier separation between commodity apparel and specification-driven technical grades determines supplier qualification requirements and contract structures.
- Apparel:Woven and knitted garments requiring hand-feel, drape, and dye affinity specifications. Fast-fashion brands in Bangladesh concentrate volume demand, while EU Green Deal compliance mandates reshape fiber provenance requirements for European retail access.
- Home Textiles:Bedding, upholstery, and curtain applications prioritizing durability and flame-retardant properties. Polyester bulk supply dominates through cost-engineered positioning in mass-market distribution.
- Industrial Textiles:Conveyor belts, ropes, and geotextiles requiring tensile strength and UV degradation resistance. Nylon and high-tenacity polyester grades capture this specification-driven demand.
- Technical Textiles:Engineered yarns for medical filtration, automotive interiors, and aerospace composites with precise denier control and biocompatibility certification. Industrial filtration and medical-grade specifications open premium margin pools outside commodity apparel.
Apparel commands volume dominance. Technical textiles are climbing the fastest as industrial buyers substitute performance for cost.
End User:
Customer type fragmentation separates compliance-heavy European brands from price-sensitive Asian garment exporters, altering traceability service economics.
- Fashion Brands:Design houses and labels specifying fiber content, finish, and sustainability certification for consumer-facing claims. Subscription-based traceability services capture recurring revenue from compliance-bound European buyers.
- Manufacturers:Cut-make-trim contractors converting yarn into finished garments under brand specifications. Vietnam and Bangladesh facilities scale sustainable fiber procurement to retain EU market access.
- Retailers:Multi-brand department stores and fast-fashion chains sourcing private-label textile products. Consolidated supplier bases reduce audit complexity under REACH chemical disclosure expansion.
- Home Furnishing:Upholstery, mattress, and curtain producers prioritizing bulk supply contracts and flame-retardant compliance. Polyester cost-engineered positioning aligns with mass-market pricing requirements.
Manufacturers absorb the most volume. Fashion brands are gaining share fastest through direct fiber contracting.
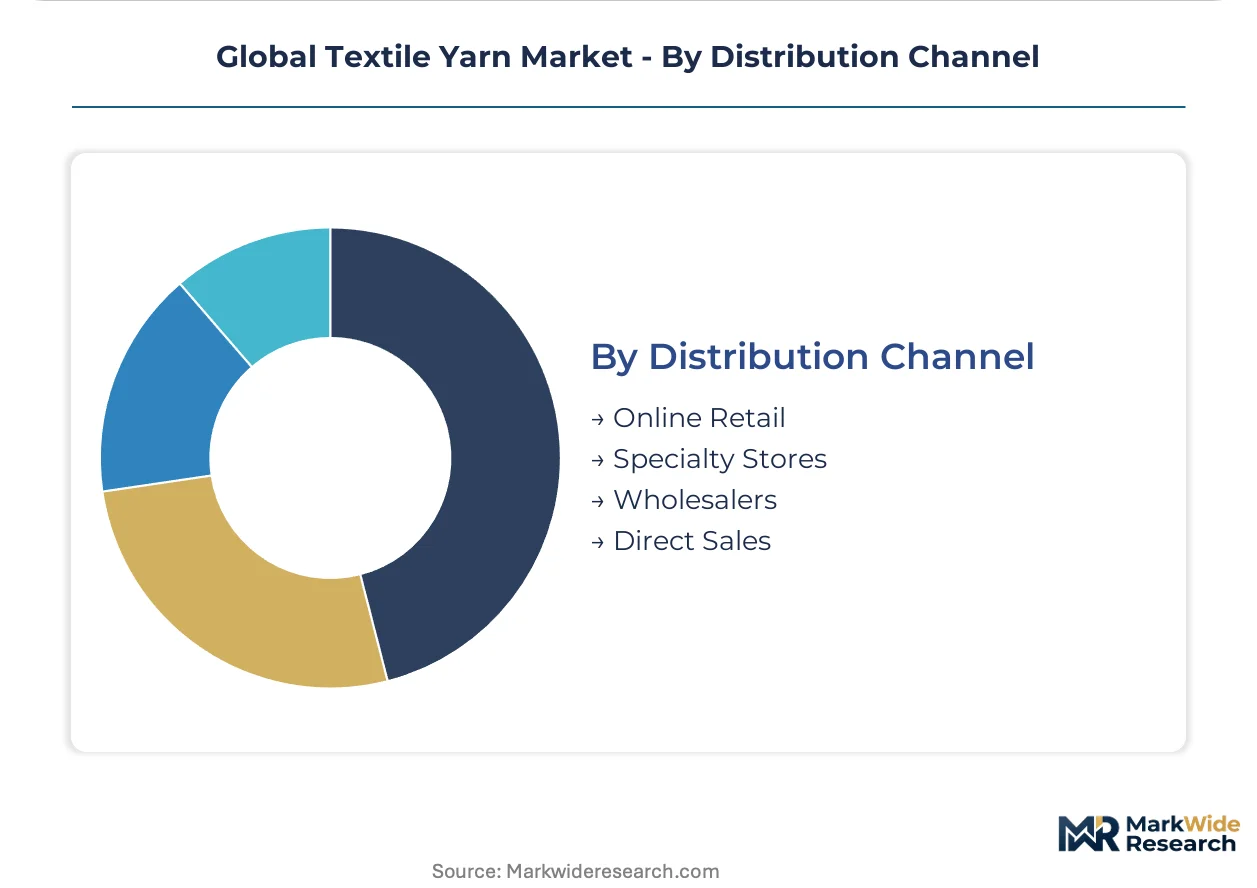
Distribution Channel:
Channel margin structure reflects inventory risk allocation and technical service intensity, with direct sales capturing specification-heavy technical yarn demand.
- Online Retail:Digital platforms for specialty and small-lot yarn sales, serving craft, hobby, and niche industrial buyers. Limited penetration in bulk industrial procurement.
- Specialty Stores:Physical outlets for premium natural fibers and certified sustainable yarns, targeting home sewers and small-batch designers. Regional concentration in European and North American urban centers.
- Wholesalers:Volume aggregators managing inventory for commodity cotton and polyester grades across fragmented downstream spinners and weavers. Credit terms and logistics coordination define competitive positioning.
- Direct Sales:Mill-direct relationships for technical textile specifications requiring custom denier, twist, and finish engineering. Medical-grade and automotive interior suppliers adopt these inputs at scale.
Wholesalers maintain volume leadership. Direct sales show steepest expansion trajectory as technical specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing textile yarn production maps as EU Green Deal compliance costs push capacity toward jurisdictions with lighter disclosure burdens. Manufacturers are relocating spinning assets to capture margin relief while maintaining European market access through certified supply chains.
China
Zhejiang and Jiangsu provinces host the world's densest polyester spinning clusters, supplying cost-engineered bulk yarn to global garment exporters. MEE dual carbon goals are tightening emissions disclosure for chemical fiber producers. The Yangtze River Delta spinning corridor is absorbing compliance technology investments to preserve European buyer relationships.
Vietnam
Garment export growth is accelerating certified recycled polyester consumption as EU-bound manufacturers reconfigure fiber procurement. The country's national standards body is aligning traceability protocols with REACH chemical disclosure requirements. Ho Chi Minh City and surrounding industrial zones concentrate spinning capacity serving compliance-bound European retail channels.
India
Domestic technical textile demand is expanding under PLI scheme incentives redirecting capacity from commodity spinning to engineered grades. BIS certification mandates are tightening quality disclosure for synthetic yarn exports. Tamil Nadu and Gujarat spinning belts are capturing value-added output subsidies while scaling recycled fiber production.
United States
EPA industrial emissions standards are elevating compliance costs for petrochemical-based fiber production. Parkdale Mills leverages backward integration across cotton gins to sustain premium positioning in ring-spun segments. The Southeast cotton belt maintains organic and regenerative certification programs serving sustainability-focused apparel brands.
Germany
REACH chemical disclosure expansion is mandating substance-level transparency from polymer pellet to finished yarn across European textile imports. The country's engineering textile sector demands precise denier control for automotive interior and industrial filtration applications. Baden-Württemberg technical textile clusters are consolidating supplier bases to reduce audit complexity under tightening provenance rules.
Global Textile Yarn Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium fiber innovators capturing margin from compliance-bound European buyers while volume spinners compete on cost-engineered bulk supply. The vendor base concentrates around three strategic archetypes: vertically integrated cotton processors, advanced polymer chemistry specialists, and regional scale spinners serving garment export hubs. Competitive moves center on fiber traceability technology licensing and strategic partnerships with certified recycling technology providers.
Within the vertically integrated tier, Parkdale Mills exemplifies backward integration strategies anchoring premium cotton yarn positioning. Among Asian chemical fiber specialists, Toray Industries and Lenzing Group occupy positions representing advanced polymer R&D and proprietary lyocell manufacturing scale respectively. These three companies illustrate how geographic specialization—US cotton belt, Japan polymer science, Austria-Asia lyocell networks—shapes competitive differentiation in a market where compliance technology now rivals tensile performance in supplier selection.
| Leading Market Players |
|---|
| Parkdale Mills |
| Unifi |
| Toray Industries |
| Lenzing Group |
| Arvind Limited |
| Weiqiao Textile |
| Milliken & Company |
| Buhler Quality Yarns |
| Vardhman Textiles |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal due diligence mandates are forcing yarn producers to absorb traceability certification costs, compressing margins in commodity polyester grades while enabling premium capture in verified recycled and lyocell segments.
Pricing Analysis
Distributor margins in wholesale channels for commodity cotton and polyester grades range from 8-15%, while direct-to-OEM technical yarn contracts command 20-35% premiums through custom denier engineering and biocompatibility certification. Three-tier pricing structure across premium certified recycled, standard virgin synthetic, and economy bulk grades reflects fiber provenance transparency levels. Cost compression in standard polyester runs through petrochemical feedstock volatility and Chinese oversupply. Price-sensitive fast-fashion manufacturers in Bangladesh concentrate volume procurement in economy tiers, while EU-bound brands show low sensitivity to certified fiber premiums.
Supply Chain Analysis
Direct-to-garment-exporter channels handle compliance-bound European demand, with Ho Chi Minh City and Dhaka industrial zones absorbing certified recycled polyester at scale. Raw material sourcing draws from PTA/MEG petrochemical complexes in Zhejiang, cotton gins across Texas and Punjab, and wood pulp refineries in Austria and Indonesia. Single-source vulnerability concentrates in Chinese polyester spinning clusters, where Zhejiang and Jiangsu provinces supply over half of global cost-engineered bulk yarn. Distribution runs through regional wholesalers managing credit terms for fragmented South Asian weavers, supplemented by mill-direct technical specifications for automotive and medical-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical textile specifications are displacing commodity apparel as the primary margin pool, rewarding producers with advanced polymer R&D capabilities and certified recycling infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into cotton ginning or polymer pellet production, locking in feedstock cost control against petrochemical volatility. Prioritize lyocell and closed-loop chemical recycling capacity additions in Austria or Southeast Asia to capture EU Green Deal compliance premiums. Consolidate supplier audit burdens for European buyers through integrated traceability platforms, reducing their REACH documentation overhead. For New Entrants and Emerging Players: The mid-tier price gap between premium certified recycled and economy virgin polyester offers white-space entry through mechanical recycling speed-to-certification. Target Vietnam's garment export corridor with subscription-based fiber verification services, unbundling compliance software from physical supply. Penetrate through partnerships with Ho Chi Minh City spinning mills seeking EU market access without legacy certification infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with regional scale spinners serving compliance-bound garment export hubs, where traceability technology licensing can revalue commodity assets. Five-to-ten year viability favors producers with captive recycled fiber supply and established European brand relationships. Watch for EU CBAM enforcement timeline acceleration as the inflection signal for carbon-accounting-ready suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemical Recycling Scale-Up | Compresses virgin-recycled polyester premium gap for EU Green Deal compliance. |
| Blockchain-Enabled Fiber Traceability Licensing | Captures recurring SaaS revenue from REACH-bound European apparel brands. |
| Lyocell Capacity Expansion in Southeast Asia | Positions near Vietnam-Bangladesh garment export demand for EU retail access. |
| Backward Integration into Cotton Ginning | Secures organic and regenerative certification control for ring-spun premium positioning. |
| Technical Textile Grade Certification Investment | Opens medical filtration and automotive interior margin pools outside commodity apparel. |
Study Parameters
Multiple input streams — primary interviews with spinning mill executives, garment exporter procurement leads, and polymer R&D directors; secondary validation through customs trade data, BIS certification registries, and EU ECHA disclosure filings — were reconciled through bottom-up capacity modeling and top-down demand triangulation across the analysis window.
Historical shipment patterns from Zhejiang and Jiangsu polyester clusters were cross-referenced against panel input from Vietnam and Bangladesh garment exporters to derive volume trajectories over the projection horizon. Segmentation dimensions modeled include fiber chemistry, end-use application tier, certification grade, and regional production hub. CAGRs were computed from reconciled base-year sizing and elasticity-adjusted demand drivers including EU CBAM preparation timelines and PLI scheme incentive windows.
Caveats apply where MEE dual carbon enforcement intensity, REACH chemical disclosure expansion scope, or Punjab cotton yield stress from water scarcity could materially shift the outlook. Forecasts reflect documented assumptions about compliance technology adoption curves and recycled fiber cost convergence. Periodic stress-testing of base assumptions against regulatory announcement timelines and polymer feedstock price bands is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market