
 School Uniform Market | 2026-2036
School Uniform Market Size, Share, and Industry Trends Forecast 2026-2036
School Uniform Market Analysis
The school uniform supply chain is rebalancing between premium bespoke tailoring and commodity bulk manufacturing. Dennis Uniform leverages its vertical integration to control quality across private school contracts. LT Apparel Group sustains manufacturing scale that anchors its position in high-volume public school tenders. Trutex Limited differentiates through specialized performance fabric development for activewear-oriented uniform programs.
School uniforms are standardized garments—typically comprising cotton, polyester, or blended woven textiles with specified GSM weights, colorfastness ratings, and reinforced seam constructions—designed to equalize student appearance and reduce socioeconomic visibility within educational environments. Polo shirts and blazers concentrate margin pools where technical specifications around wrinkle resistance and extended wear cycles command premium positioning. The online retail channel leads structural expansion as direct-to-school procurement platforms displace traditional wholesale intermediaries, while performance fabrics represent the fastest-growing fabric type segment driven by moisture-wicking and antimicrobial properties.
REACH and OEKO-TEX standards in Europe constrain chemical inputs in dyeing and finishing processes, compelling suppliers to reformulate textile treatments or forfeit market access. The US Consumer Product Safety Commission governs flammability and small-part standards for younger student segments, shaping product design minimums. Stakeholders must monitor how evolving sustainability disclosure requirements across multiple jurisdictions will redefine supplier qualification criteria and contract renewal terms.
Market Dynamics
REACH compliance in Europe is forcing textile suppliers to reformulate dyeing processes and abandon conventional chemical treatments, compressing margins for non-compliant manufacturers while creating qualification barriers for new entrants.
Growth Catalysts
- REACH chemical standards:European ECHA mandates on restricted substances are accelerating certified organic cotton adoption among suppliers seeking market access.
- India government enrollment:Bulk procurement tenders from state education departments are concentrating volume demand in standardized garment categories.
- Recycled polyester blends:Mechanical recycling technologies are enabling closed-loop fiber production that satisfies sustainability disclosure requirements.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations from Indian and Chinese agricultural regions destabilize input cost forecasting.
- Supplier concentration in South Asia:Bangladesh and Vietnam garment manufacturing clusters create geopolitical and logistics risk exposure.
- Fast fashion substitution:Low-cost casual wear retailers capture price-sensitive family budgets in markets without strict uniform mandates.
Strategic Opportunities
- Rural India penetration:Government school expansion into tier-3 and tier-4 cities offers volume growth in previously underserved districts.
- Direct-to-school platforms:Digital procurement portals are displacing traditional wholesale intermediaries and capturing margin compression benefits.
- EU Green Deal alignment:Carbon border adjustment mechanisms reward early adopters of renewable energy in textile finishing operations.
Industry Challenges
- Colorfastness certification delays:Extended testing timelines for OEKO-TEX Standard 100 compliance slow product launch cycles.
- Legacy ERP integration:School district procurement systems require custom API development for platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Uniform Market |
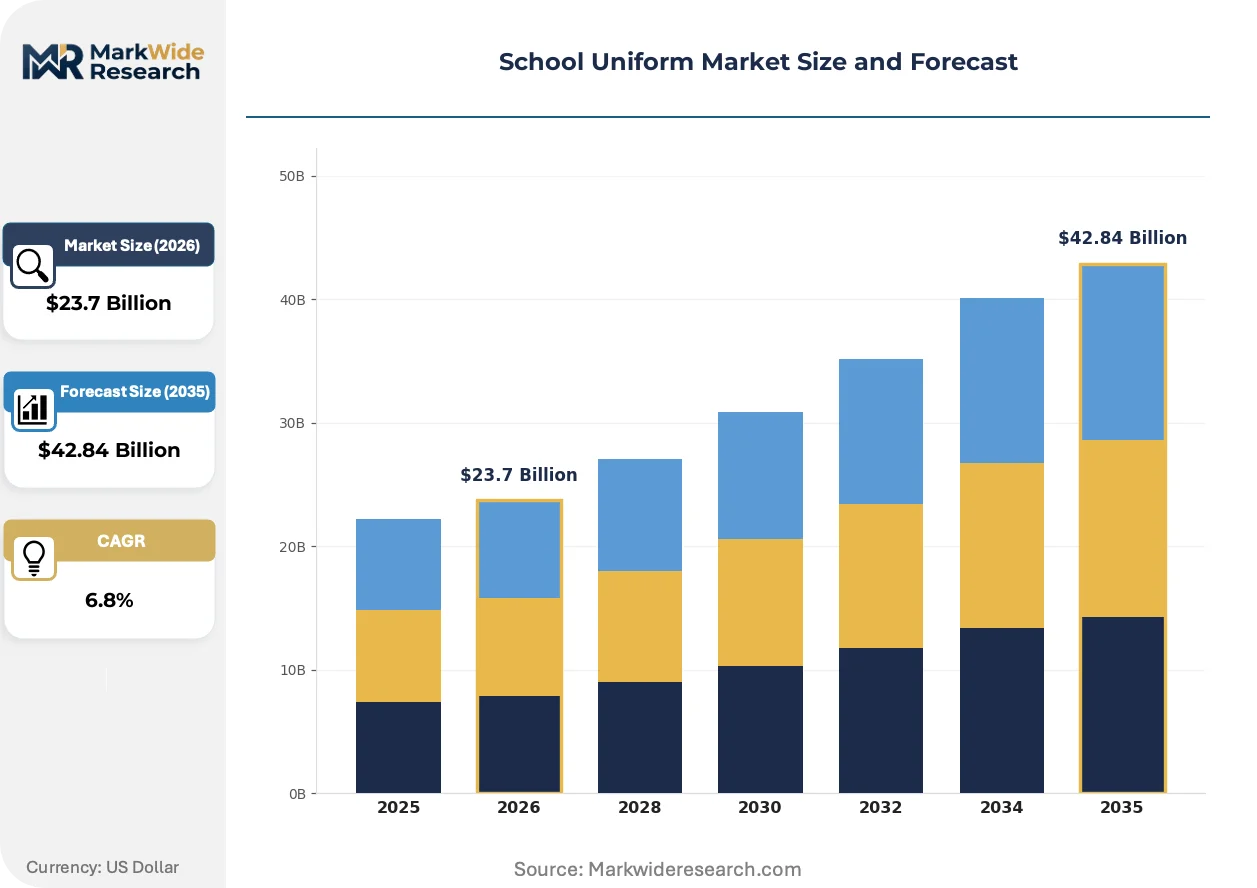
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polo Shirts, Pants, Skirts, Blazers Distribution Channel: Online Retail, Specialty Stores, School Outlets, Wholesale End User: Primary Schools, Secondary Schools, Private Institutions, Public Schools Fabric Type: Cotton, Polyester, Blends, Performance Fabrics |
| Companies Covered | Dennis Uniform, LT Apparel Group, Alinta Apparel Pty Ltd, GS International, Trutex Limited, Beleza Pty Ltd, Donya Uniforms Private Limited, Zeco Ltd, FlynnO'Hara Uniforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Uniform Market Emerging Trajectories
Digital manufacturing and regulatory chemistry constraints are converging to reshape how uniforms are specified, produced, and delivered to educational institutions across multiple geographies.
Automated cutting and sewing systems are automating pattern nesting and fabric utilization in high-volume polo shirt production. Private school contractors in the United Kingdom are adopting these systems to reduce labor dependency and improve size-grade consistency. The technology is automating quality control checkpoints that previously required manual inspection, compressing defect rates and return processing costs.
EU REACH Annex XVII restrictions on azo dyes and flame retardants are eliminating conventional textile treatments from European supply chains. Manufacturers serving German and French school markets must now source compliant chemical formulations or forfeit contract eligibility. Performance fabric segments requiring moisture-wicking properties are most affected, driving reformulation partnerships between finishers and specialty chemical suppliers.
Parental purchasing through centralized school portals is consolidating individual transactions into institutional procurement workflows. United States private academies are migrating from retail partnerships to captive e-commerce platforms that capture student measurement data and automate reorder cycles. California and Texas districts demonstrate the fastest platform adoption, where large enrollment bases justify dedicated technology investment.
School Uniform Market Segmentation
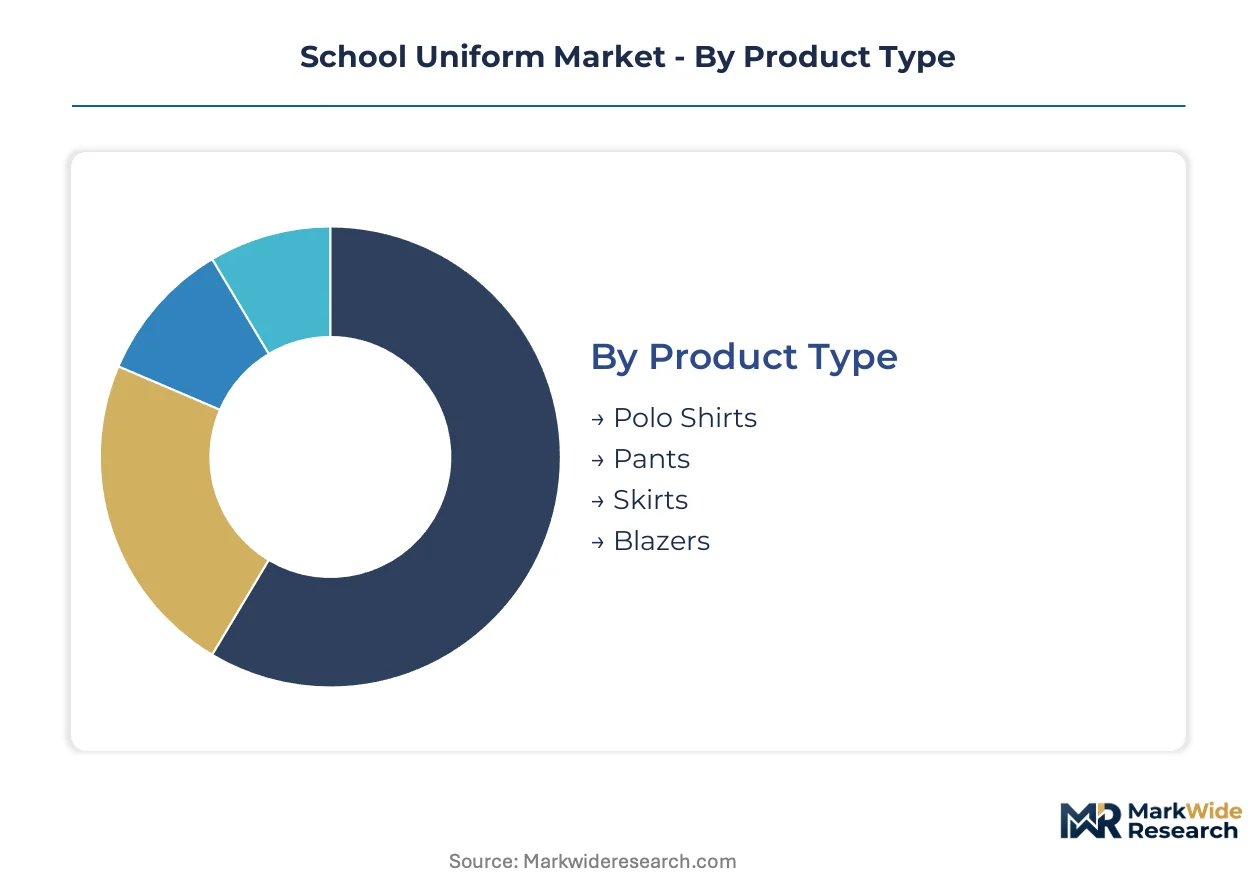
School uniform procurement varies sharply across institutional budgets, regulatory environments, and climate requirements. Segment-level analysis reveals where premium specifications command price premiums versus where commodity volumes dominate contract economics.
Product Type:
Institutional buyers prioritize durability-to-cost ratios and replacement frequency when selecting garment categories for bulk tender awards.
- Polo Shirts:Knit cotton-polyester constructions with pique weaves and reinforced collar bands withstand industrial laundering cycles. Indian government school tenders concentrate volume demand here, where standardized sizing and colorfastness certification drive supplier qualification.
- Blazers:Structured wool-polyester blends with fused interlinings and reinforced stress points carry the highest per-unit margins. Private institutions in the United Kingdom specify these for branding differentiation, with crest embroidery and custom button requirements extending procurement lead times.
- Pants:Twill weave cotton or poly-cotton blends with soil-release finishes serve high-wear daily use.
- Skirts:Pleated polyester or blended constructions with permanent press treatments dominate formal uniform programs.
Polo shirts lead on scale; blazers lead on momentum.
Distribution Channel:
Channel selection reflects institutional procurement maturity and parent payment structures rather than pure retail convenience.
- Online Retail:Direct-to-school portals with student measurement databases and automated reorder triggers. California private academies and Texas districts demonstrate fastest platform adoption where enrollment scale justifies dedicated technology investment.
- Specialty Stores:Fitted services with in-house alteration capabilities and seasonal collection launches. These outlets capture premium positioning in markets with established uniform mandates.
- School Outlets:Captive campus stores with immediate fulfillment and logo verification protocols serve parent convenience.
- Wholesale:Volume contracts with extended payment terms and bulk shipment logistics anchor public sector procurement.
Wholesale channels lead on scale; online retail leads on momentum.
End User:
Buyer sophistication and specification stringency diverge between government-mandated programs and independently governed institutions.
- Public Schools:State-funded procurement with standardized specifications and lowest-bidder contract awards. Indian state education departments drive the steepest expansion trajectory through rural enrollment expansion into tier-3 and tier-4 cities.
- Private Institutions:Customized programs with branded elements, performance fabric requirements, and multi-year supplier relationships. These contracts emphasize color consistency across production batches and dedicated account management.
- Primary Schools:Smaller sizing ranges with flammability and small-part safety requirements governing design minimums.
- Secondary Schools:Expanded size grading and formal dress code components with gender-specific tailoring requirements.
Public schools lead on scale; private institutions lead on momentum.
Fabric Type:
Material selection balances regulatory compliance, climate adaptation, and sustainability disclosure requirements across procurement jurisdictions.
- Performance Fabrics:Engineered textiles with moisture-wicking filament yarns and antimicrobial silver-ion treatments. ECHA REACH restrictions on conventional chemical finishes are accelerating reformulation partnerships between European finishers and specialty chemical suppliers.
- Blends:Cotton-polyester combinations optimizing breathability against wrinkle resistance and shrinkage control. These constructions dominate mid-tier pricing segments where institutional buyers seek durability without premium positioning.
- Cotton:Natural fiber with certified organic variants required for EU Green Deal alignment and carbon border adjustment mechanism compliance.
- Polyester:Virgin and mechanically recycled filament options with closed-loop production claims satisfying sustainability procurement criteria.
Blends lead on scale; performance fabrics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled garment workers in Bangladesh, Vietnam, and southern India anchor the production base for school uniform manufacturing. These labor pools support both high-volume commodity production and precision tailoring for premium institutional contracts.
United States
Private academy expansion in California and Texas drives demand for customized uniform programs with performance fabric specifications. The US Consumer Product Safety Commission governs flammability standards for primary school garments. Dallas-Fort Worth hosts several institutional procurement platforms that automate student measurement databases and reorder cycles.
United Kingdom
Independent school branding requirements sustain demand for crested blazers and bespoke tailoring services. REACH Annex XVII restrictions on azo dyes and flame retardants eliminate conventional textile treatments from supply chains. Leicester's garment manufacturing cluster specializes in automated cutting systems for private school contractors seeking labor cost reduction.
India
Government school enrollment expansion into tier-3 and tier-4 cities concentrates bulk procurement volume in standardized polo shirts and trousers. State education departments issue lowest-bidder tenders with standardized sizing and colorfastness certification requirements. Tiruppur's knitwear cluster dominates cotton-polyester pique production for national school tenders.
Germany
ECHA chemical mandates accelerate certified organic cotton adoption among suppliers seeking EU market access. The EU Green Deal's carbon border adjustment mechanisms reward renewable energy adoption in textile finishing operations. North Rhine-Westphalia's industrial textile belt hosts reformulation partnerships between finishers and specialty chemical suppliers.
Vietnam
Mechanical recycling technologies enable closed-loop polyester fiber production for sustainability-conscious export markets. Geopolitical logistics risks from supplier concentration create pressure for diversification into alternative manufacturing bases. Ho Chi Minh City's garment districts scale production of recycled polyester blends for European and North American institutional buyers.
School Uniform Market Vendor Landscape
Top-tier vendors anchor multi-year private school contracts with customized branding elements, while mid-tier manufacturers compete on scale for government tender awards. The market structure separates premium bespoke positioning from commodity bulk production. Three archetypes dominate: vertically integrated specialists controlling quality across private contracts, high-volume producers anchoring public sector tenders, and performance fabric developers serving activewear-oriented programs. Competitive moves concentrate on backward integration into textile finishing and digital procurement platform development.
Within the premium-tier vector, Dennis Uniform and Trutex Limited exemplify specialized positioning archetypes, while LT Apparel Group occupies the scale-driven manufacturing segment. Dennis Uniform's vertical structure supports quality control across private school relationships. Trutex Limited represents performance fabric development specialization. LT Apparel Group anchors high-volume production capacity for institutional tender participation.
| Leading Market Players |
|---|
| Dennis Uniform |
| LT Apparel Group |
| Alinta Apparel Pty Ltd |
| GS International |
| Trutex Limited |
| Beleza Pty Ltd |
| Donya Uniforms Private Limited |
| Zeco Ltd |
| FlynnO'Hara Uniforms |
| Others |
Supply Flow & Price Mechanics
Mechanical recycling technologies for polyester fiber production are compressing raw material costs while concentrating supplier leverage among Vietnamese and Ho Chi Minh City-based finishers with closed-loop capabilities. This production-method transition simultaneously reshapes cost economics for sustainable fabric tiers and reinforces supply concentration in mechanical recycling hubs.
Pricing Analysis
Bundled portal services with measurement databases and automated reorder cycles command premium positioning against unbundled wholesale transactions with extended payment terms. Three-tier pricing structure across premium bespoke, standard blended, and economy bulk levels separates private academy contracts from government tender awards. Cost compression in economy tiers is intensifying because Indian state education departments consolidate lowest-bidder awards. Government procurement managers exhibit highest price sensitivity; private institution facilities directors prioritize color consistency and crest embroidery quality over unit cost.
Supply Chain Analysis
Freight cost volatility from Bangladesh and Vietnam garment clusters is forcing European and North American buyers to diversify sourcing into Tiruppur and southern India knitwear hubs. Raw material flows draw from Indian cotton agricultural regions, Chinese polyester filament production, and German specialty chemical formulations for moisture-wicking finishes. Single-source vulnerability concentrates in azo dye and flame retardant chemical suppliers facing ECHA REACH Annex XVII restrictions. Distribution runs through direct-to-school digital portals displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The school uniform market functions as a stable compounder anchored by government enrollment mandates and institutional procurement cycles that resist discretionary spending volatility.
For Market Incumbents: Lock in multi-year private academy contracts with dedicated account management and color-matching guarantees before REACH compliance costs escalate. Backward integration into certified organic cotton sourcing and automated cutting systems in Leicester or Tiruppur protects margin pools from fast fashion substitution threats.
For New Entrants and Emerging Players: Capture rural India government tender participation through tier-3 and tier-4 city distribution partnerships with state education departments. Direct-to-school platform development with student measurement databases offers the most penetrable entry vector against legacy wholesale relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers with scale capacity but lacking digital procurement infrastructure. Long-term viability over a multi-year horizon rests on EU Green Deal alignment and carbon border adjustment mechanism readiness. Watch ECHA chemical restriction expansion timelines as the primary inflection signal for supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-School Platform Development | Captures margin compression benefits from wholesale intermediary displacement in California and Texas districts. |
| REACH-Compliant Chemical Reformulation | Secures contract eligibility in German and French markets facing ECHA Annex XVII dye restrictions. |
| Mechanical Recycling Capacity Expansion | Enables closed-loop polyester claims for EU Green Deal procurement criteria satisfaction. |
| Automated Cutting System Deployment | Reduces labor dependency for UK private school contractors in Leicester manufacturing clusters. |
| Rural India Distribution Partnership | Positions for state education department bulk tenders in tier-3 and tier-4 city expansions. |
Methodological Framework
Multiple input streams — procurement director interviews, textile mill operational data, and regulatory filing analysis — were reconciled to construct demand estimates. Primary discussions with school district purchasing officers, private academy facilities directors, garment manufacturing plant managers, and specialty chemical supplier R&D leads were cross-checked against customs trade records, ECHA substance restriction databases, state education department tender documents, and SEC apparel company filings. Bottom-up volume modeling and top-down market sizing were triangulated for consistency.
Historical shipment patterns from Tiruppur and Bangladesh clusters were cross-referenced against panel input from procurement platform operators and uniform program administrators. Segmentation dimensions modeled include product type, fabric technology tier, distribution channel structure, and institutional buyer category across the analysis window. CAGRs were derived from enrollment trend projections, uniform mandate expansion patterns, and replacement cycle assumptions. Cotton price volatility indices and REACH compliance cost curves informed scenario boundaries.
Weather-driven agricultural disruption, sudden ECHA chemical restriction amendments, and geopolitical logistics interruptions are the dominant revision risks to procurement volume assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Down Jacket Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Denim Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Blank Apparel Market