
 Knitwear Market | 2026-2036
Knitwear Market Size, Share, and Industry Trends Forecast 2026-2036
Knitwear Market Intelligence
The proliferation of on-demand digital knitting platforms is fragmenting the traditional seasonal collection model. This shift allows agile brands like Adidas AG to leverage rapid prototyping for performance athletic wear. In contrast, Brunello Cucinelli sustains its market position through mastery of artisanal cashmere and alpaca production. Gildan Activewear competes on the basis of scaled manufacturing for high-volume cotton and acrylic basics.
Knitwear comprises apparel constructed by interlocking loops of yarn, a process distinct from weaving. This structure imparts inherent elasticity and drape to garments, with gauge (stitches per inch) determining fabric density. While wool and cashmere command premium pricing, the market's volume is anchored in cotton and acrylic materials. The women's end-user segment remains the largest, but the men's category shows significant expansion in premium pullovers and cardigans.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates supply chain transparency for larger apparel companies. Material composition and labeling are governed by frameworks like the US Federal Trade Commission (FTC) textile acts and Europe's REACH regulation on chemical use. Navigating the patchwork of sustainability certifications and material traceability requirements is becoming a central strategic decision for all brands.
Market Dynamics
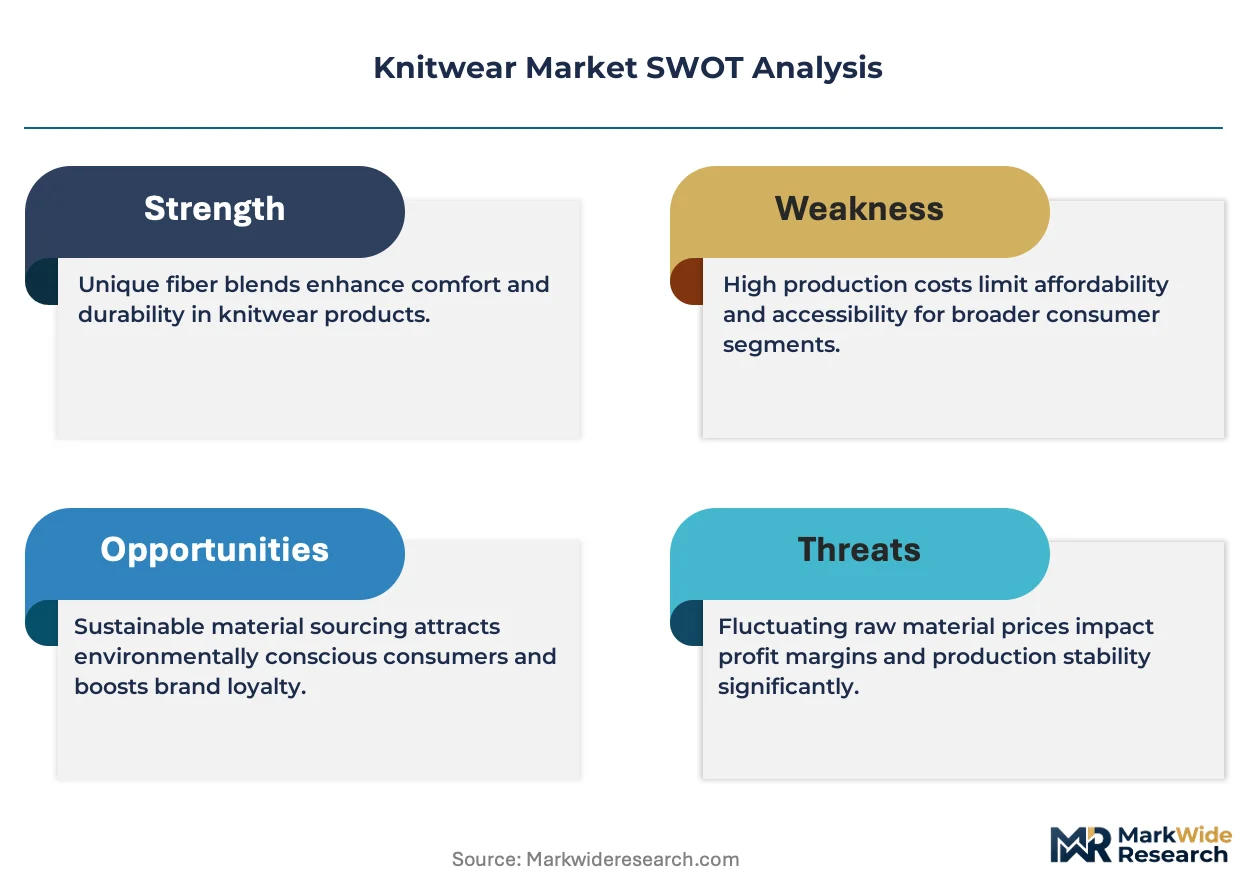
The central tension in the knitwear market is the collision between scaled, low-cost manufacturing concentrated in hubs like China and the rising regulatory and consumer pressure for transparent, sustainable, and traceable supply chains. This dynamic forces a strategic choice between volume-based efficiency and value-based differentiation through material provenance and ethical production claims.
Growth Catalysts
- 3D Knitting Technology:The adoption of seamless 3D knitting reduces material waste by up to 30% and allows for on-demand production, appealing to sustainability-focused consumers.
- Children's Wear Segment:Demand from the children's wear category for soft, flexible, and non-restrictive clothing provides a consistent volume driver for cotton and cotton-blend knits.
- Traceability Mandates:Regulations like the EU's CSRD create demand for certified fibers such as organic cotton and recycled wool, benefiting suppliers with robust traceability systems.
Market Restraints
- Material Price Volatility:The price of premium natural fibers like cashmere and merino wool is subject to significant fluctuation due to climate conditions and agricultural yields.
- Geopolitical Risk:Heavy concentration of manufacturing capacity in China exposes the global supply chain to trade policy shifts, tariffs, and logistical disruptions.
- Fabric Substitution:Advances in performance woven textiles, which can be engineered with stretch and moisture-wicking properties, present a substitution threat in the activewear segment.
Strategic Opportunities
- Technical Textiles:Adapting knitting technologies to produce shaped components for non-apparel applications, such as medical compression garments or lightweight automotive upholstery, opens new industrial markets.
- Smart Garments:Integrating conductive yarns and micro-sensors directly into knitted fabrics enables the creation of garments for health monitoring and biometric data tracking.
- On-Demand Services:Launching digital platforms that offer customized knitwear based on body scans or specific design inputs allows for a high-margin, direct-to-consumer business model.
Industry Challenges
- Advanced Skill Gaps:A persistent shortage of technicians proficient in programming, operating, and maintaining sophisticated digital and 3D knitting machinery constrains production scaling.
- Regulatory Fragmentation:Navigating disparate chemical safety rules like Europe's REACH and textile labeling laws from the US FTC increases compliance costs and complexity for global brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knitwear Market |
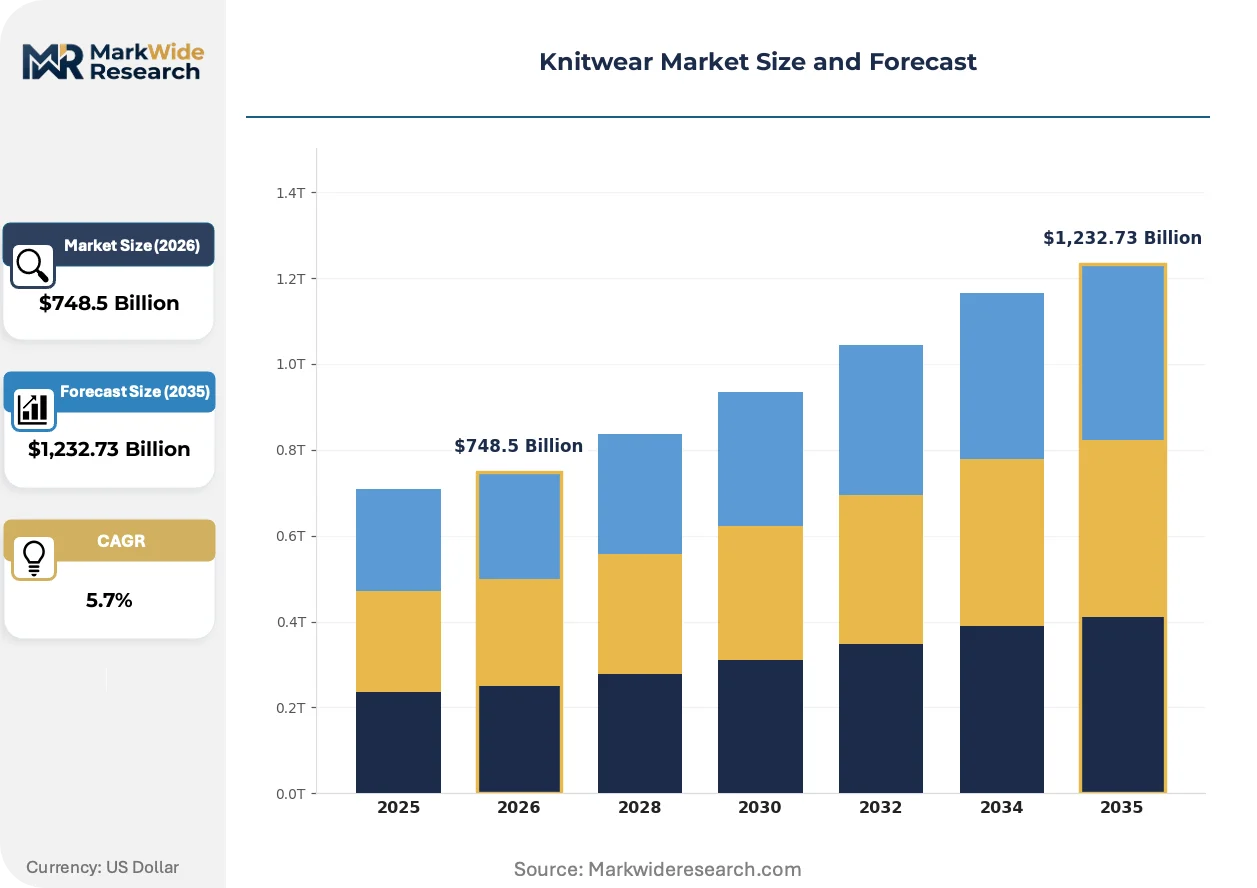
| Market Size in 2026 | $748.5 Billion |
| Market Size in 2035 | $1,232.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweaters, Cardigans, Pullovers, Vests, Ponchos Material: Wool, Cotton, Acrylic, Cashmere, Mohair, Alpaca End User: Women, Men, Children, Infants Distribution Channel: Online Stores, Specialty Boutiques, Department Stores, Direct-to-Consumer, Franchise Outlets |
| Companies Covered | Loro Piana S.p.A., Ralph Lauren, Adidas AG, Puma SE, Nike, Inc., Brunello Cucinelli, Johnstons of Elgin, Marks and Spencer Group plc, Gildan Activewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knitwear Market Strategic Shifts & Innovations
Digitalization and sustainability are converging to fundamentally alter knitwear production models. This shift moves the industry from a reliance on seasonal forecasts toward more agile, data-driven, and responsive systems of creation and distribution.
Complete garments are now produced directly from digital files using 3D knitting machines, eliminating most cutting and sewing. Performance athletic and agile fashion brands are the primary adopters for rapid prototyping. This technology is virtualizing the sample development cycle, reducing lead times and material waste significantly.
The EU's Corporate Sustainability Reporting Directive (CSRD) imposes stringent transparency requirements on apparel companies. This regulation mandates audited disclosure of environmental and social impacts throughout the supply chain, from fiber source to finished product. The premium wool and cashmere segments are most affected, needing to invest heavily in traceability systems to validate material origin and production claims.
Consumer purchasing is moving from large seasonal buys to a pattern of continuous, smaller-scale acquisitions. This behavior disrupts the traditional wholesale model built on large pre-season orders, favoring direct-to-consumer and on-demand platforms. The shift is most pronounced in the North American and European markets for women's casualwear, driven by social media and e-commerce.
Knitwear Market Segmentation
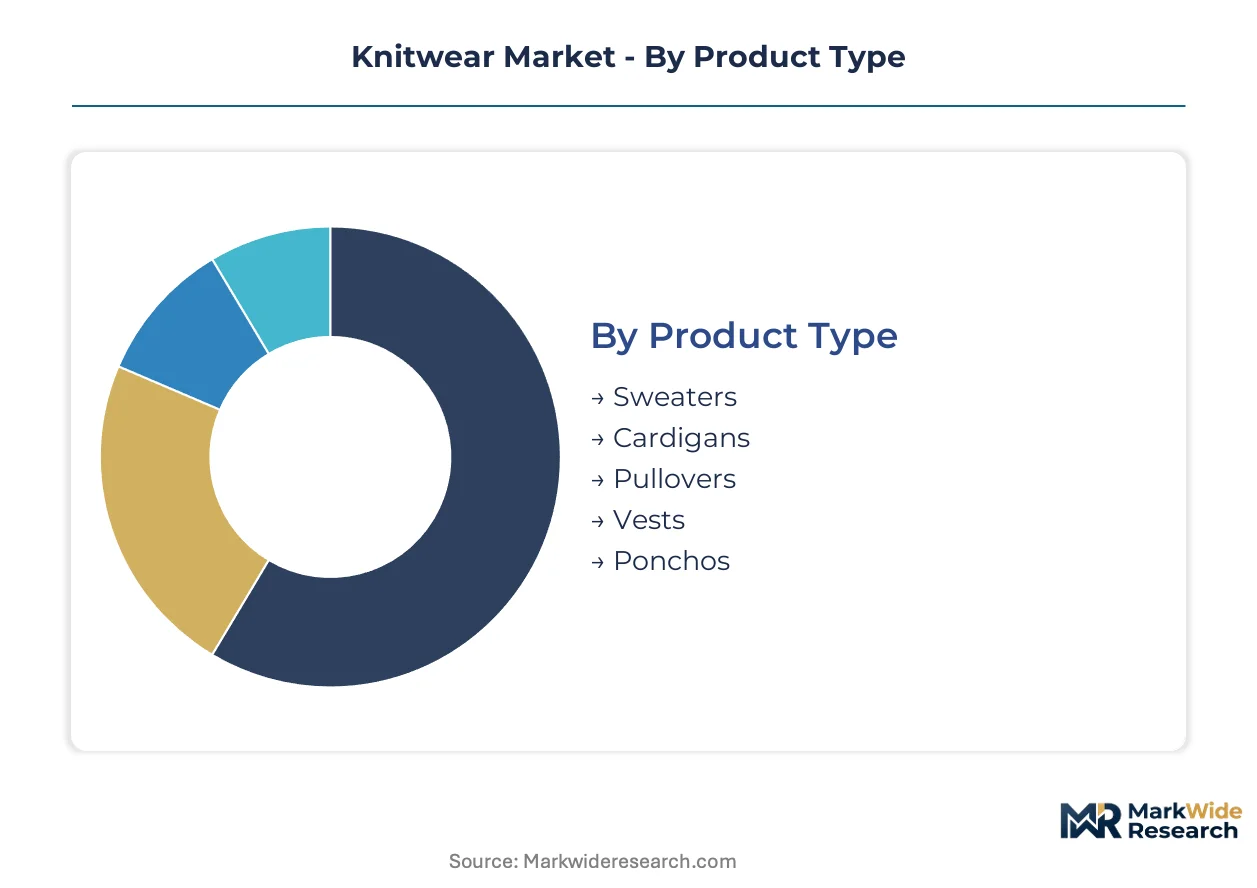
The knitwear market's segmentation provides a granular view of demand drivers and competitive dynamics. Understanding these distinct categories helps brands tailor product development, supply chain strategies, and market entry approaches. This analysis reveals where value is created and how different segments respond to technological shifts and consumer preferences.
Product Type:
The product type segment spans mature staples and emerging fashion items, reflecting diverse consumer needs and production complexities.
- Sweaters:These garments, typically worn on the upper body, are constructed from various yarns to provide warmth and comfort. Demand concentrates in colder climates across North America and Northern Europe, driven by seasonal utility and evolving fashion trends.
- Cardigans:Open-front knitted garments often featuring buttons or zippers, cardigans offer versatile layering options. The women's wear segment in the United States and Germany drives consistent demand for cardigans, valuing their adaptability for various occasions.
- Pullovers:Pullovers are seamless, closed-front garments designed to be "pulled over" the head, offering a sleek profile.
- Vests:Sleeveless knitted garments provide an additional layer of warmth without restricting arm movement.
- Ponchos:Large, often rectangular pieces of fabric with a central opening for the head, ponchos offer a relaxed, flowing silhouette.
Sweaters handle the majority of throughput; Pullovers are the fastest mover on share.
Material:
Supply concentration heavily influences material availability and pricing across the knitwear market.
- Cotton:A natural cellulosic fiber, cotton offers breathability, softness, and absorbency, making it a staple for everyday knitwear. Demand remains high in China and India for volume production, benefiting from scaled agricultural output.
- Cashmere:This luxurious natural fiber, sourced from cashmere goats, is prized for its exceptional softness, lightness, and warmth. Its premium pricing and limited supply concentrate demand among high-end consumers in Western Europe and Japan, who value exclusivity and quality.
- Wool:Derived from sheep, wool is a durable and warm natural fiber with inherent elasticity and moisture-wicking properties.
- Acrylic:A synthetic fiber known for its soft, wool-like feel, acrylic is often used as a cost-effective alternative to natural fibers.
- Mohair:Obtained from Angora goats, mohair is a silky, lustrous fiber known for its warmth and durability.
- Alpaca:Sourced from alpacas, this natural fiber is soft, lightweight, and hypoallergenic, often considered a premium alternative to wool.
Cotton dominates the material volume, while recycled wool shows the steepest expansion trajectory due to sustainability mandates.
End User:
Customer type defines distinct product requirements and purchasing behaviors within the knitwear sector.
- Women:This segment includes a broad range of knitwear from fashion-forward pieces to comfort-oriented basics. Demand for women's knitwear is consistently robust across all major markets, driven by diverse styling preferences and seasonal fashion cycles.
- Men:The men's segment encompasses classic pullovers, cardigans, and performance-oriented activewear. Expansion in this category is significant in the United States and Germany, with consumers seeking premium materials and versatile designs.
- Children:Knitwear for children emphasizes softness, durability, and ease of care, often incorporating playful designs.
- Infants:This category focuses on extremely soft, non-irritating, and easy-to-wash knit garments for newborns and toddlers.
The women's segment maintains the largest market presence, and the men's category is gaining share through increased product diversification.
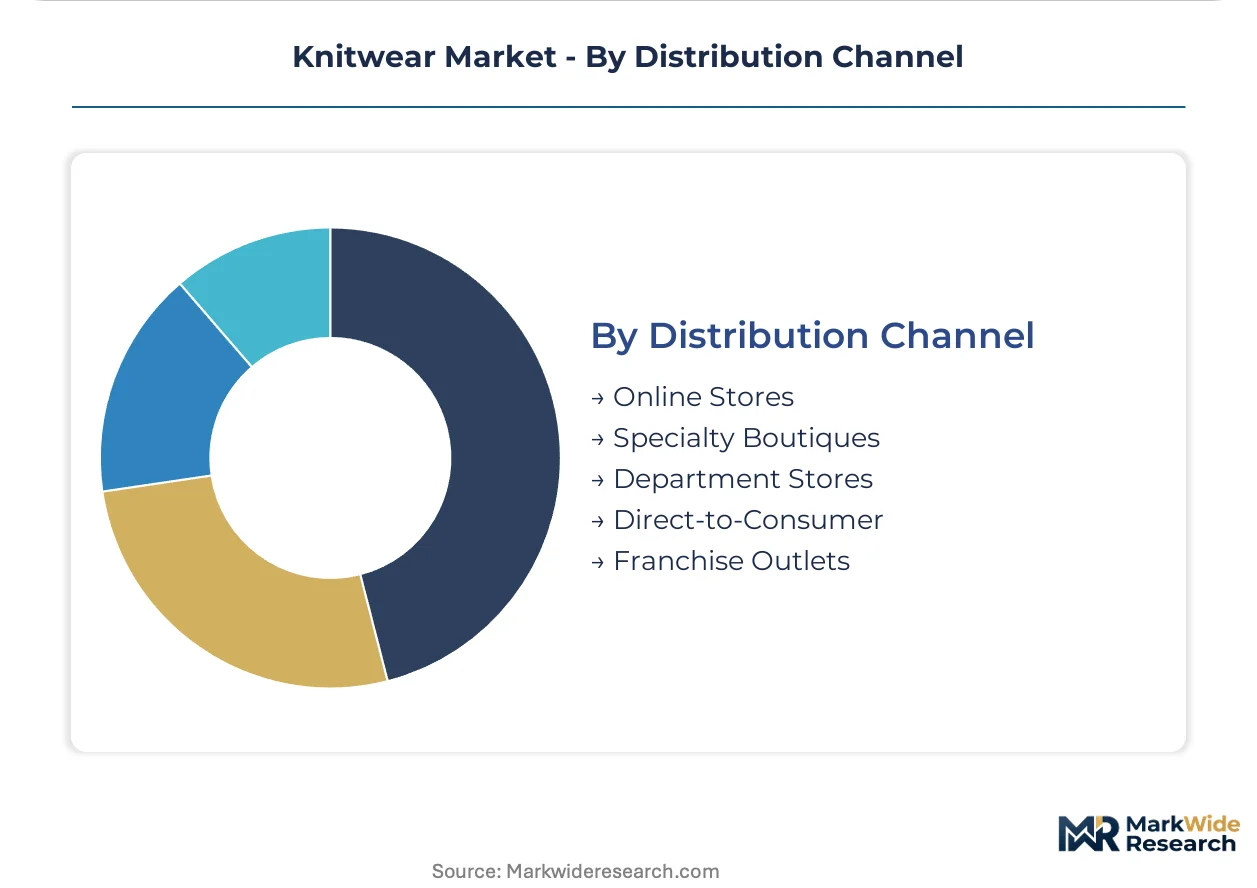
Distribution Channel:
Margin structures vary significantly across the different distribution channels in the knitwear industry.
- Online Stores:E-commerce platforms offer broad product selections and convenience, enabling direct consumer access. The digital shift is pronounced in North America and Europe, where consumers increasingly prefer online purchasing for apparel.
- Specialty Boutiques:These smaller, curated retail spaces often focus on niche brands, unique designs, or premium materials.
- Department Stores:Large retail establishments offer a wide array of brands and product categories under one roof.
- Direct-to-Consumer:Brands selling directly to consumers bypass intermediaries, allowing for greater control over branding and pricing. This model is expanding rapidly in the United States, driven by customization and personalized experiences.
- Franchise Outlets:Retail stores operating under a licensing agreement with a larger brand, offering a consistent product line.
Online Stores capture substantial sales volume, and Direct-to-Consumer models are experiencing accelerated growth in market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrations of specific buyer archetypes significantly influence regional knitwear demand patterns. The market's diverse end-user segments, from high-volume children's wear to premium adult garments, create distinct geographic consumption profiles. Manufacturing hubs also dictate supply chain dynamics and material flow across different regions.
China
Volume production of cotton knitwear for local and export markets drives demand in China. The country's dual carbon goals and GB standards encourage sustainable manufacturing practices. Textile clusters in the Yangtze River Delta focus on scaled production and digital knitting technology adoption.
United States
The women's segment and expanding men's category consistently generate knitwear demand in the United States. The Federal Trade Commission (FTC) textile acts govern labeling and material composition for all apparel. Los Angeles serves as a design hub, leveraging rapid prototyping for fashion-forward knitwear.
Germany
Consistent demand for cardigans and premium men's knitwear anchors the German market. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates supply chain transparency for larger apparel companies. Bavaria hosts manufacturers specializing in high-quality wool and cashmere knitwear production.
Japan
High-end consumers in Japan seek luxurious cashmere and alpaca knitwear, valuing craftsmanship and material quality. The Ministry of Economy, Trade and Industry (METI) supports textile industry innovation and material research. Osaka remains a center for advanced textile development, including technical knitwear applications.
India
India's large domestic market drives substantial volume demand for cotton and cotton-blend knitwear. The Bureau of Indian Standards (BIS) sets quality benchmarks for textile products, including knit fabrics. Tiruppur functions as a major knitwear manufacturing and export hub, specializing in mass-produced garments.
Knitwear Market Key Industry Players
Channel-controlling players compete with product-specialist players across the knitwear market, creating a tiered competitive structure. The industry exhibits fragmentation at the manufacturing base, while brand differentiation occurs through material provenance or performance attributes. Dominant competitive moves include strategic partnerships for technological integration and portfolio diversification into new end-user segments.
At the scale-driven end, Gildan Activewear exemplifies efficiency in high-volume cotton and acrylic basics production. Performance athletic wear brands like Adidas AG leverage rapid prototyping and 3D knitting technology for agile product development. Meanwhile, Brunello Cucinelli S.p.A. represents the premium-tier vector, anchoring its market position through mastery of artisanal cashmere and alpaca production for discerning consumers.
| Leading Market Players |
|---|
| Loro Piana S.p.A. |
| Ralph Lauren |
| Adidas AG |
| Puma SE |
| Nike, Inc. |
| Brunello Cucinelli |
| Johnstons of Elgin |
| Marks and Spencer Group plc |
| Gildan Activewear |
| Others |
Cost & Logistics Intelligence
Tiruppur's scaled knitwear manufacturing capacity directly influences global pricing dynamics for cotton basics. Its volume efficiency creates a baseline for market entry and competitive offers.
Pricing Analysis
Cost-plus contract patterns, often indexed to cotton and acrylic fiber prices, dominate the high-volume knitwear segment. Price differentiation occurs through material provenance, such as certified organic cotton, and customization levels for specific brand requirements. Pricing softness reflects intense competition from Asian manufacturers. The children's wear segment exhibits the highest price sensitivity, while premium cashmere buyers are least sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices supporting large-scale knitwear production. Geographic supply concentrates in China, India, and Vietnam, relying heavily on raw material inputs like cotton from India and acrylic from China. Geopolitical risk, particularly trade policy shifts impacting China, represents a significant structural vulnerability. Distribution runs through online stores for direct-to-consumer models and department stores for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The knitwear market presents an early-cycle expansion story, driven by the increasing adoption of 3D knitting technology. This innovation enables rapid prototyping and sustainable production, attracting new consumer segments.
For Market Incumbents: Build a proprietary digital platform moat to counter agile fashion brands and mitigate supply chain fragmentation. Consolidate manufacturing capacity in strategic regions like the Yangtze River Delta to leverage scale, ensuring compliance with EU CSRD mandates. Invest in advanced materials R&D to differentiate against performance woven textiles.
For New Entrants and Emerging Players: On-demand, customized knitwear services for North American and European direct-to-consumer markets represent the most penetrable entry point. Niche product lines focusing on smart garments with integrated sensors offer significant differentiation. A direct-to-consumer e-commerce model, leveraging social media for targeted outreach, provides a viable go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists in sustainable materials and 3D knitting. Long-term viability hinges on companies mastering both artisanal craft and digital production capabilities over the next decade. Acquisition targets include firms with proprietary 3D knitting software or certified traceable fiber supply chains. Watch for increasing patent filings in technical textiles as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand 3D Knitting Capacity | Reduces material waste by up to 30% and shortens lead times for agile brands. |
| Invest in Traceability Systems | Ensures compliance with EU CSRD and validates material origin for premium wool segments. |
| Develop Smart Garment Applications | Integrates conductive yarns for health monitoring, opening new industrial markets. |
| Launch Direct-to-Consumer Platforms | Captures high-margin sales by offering customized knitwear based on consumer inputs. |
| Diversify Raw Material Sourcing | Mitigates price volatility of premium natural fibers like cashmere and merino wool. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Interviews included textile manufacturers, brand managers, supply chain logistics heads, and sustainability officers. Secondary validation drew from EU CSRD reports, US FTC textile acts, China GB standards, and METI publications. Bottom-up market sizing was triangulated against top-down industry revenue figures.
Forecast inputs considered historical market performance, technological adoption rates, and regulatory impacts across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, end-user, and distribution channel, alongside the impact of 3D knitting technology. Compound annual growth rates were derived from a multi-variant regression model. Consumer purchasing behavior shifts towards continuous, smaller-scale acquisitions served as a key input.
Macroeconomic conditions sit as an overlay; deviation in global consumer spending or raw material prices would shift the trajectory. Forecasts reflect assumptions documented regarding technological advancements and regulatory enforcement. Geopolitical risks affecting manufacturing hubs could also revise the forecast. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Global Socks Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Functional Apparel Market