
 Canvas Roll Market | 2026-2036
Canvas Roll Market Size, Share, and Industry Trends Forecast 2026-2036
Canvas Roll Market Outlook
India's textile belt expansion is reshaping regional supply dynamics for woven substrates. Fredrix Artist Canvas leverages its domestic mill network to sustain cost-competitive cotton canvas output. Blick Art Materials anchors North American distribution through direct-to-studio channel control. Winsor & Newton differentiates via archival-grade coating chemistry that commands premium placement in professional art supply retail.
Canvas roll denotes a continuous woven textile substrate, typically manufactured from cotton, linen, or synthetic fibers in weights ranging from 5 oz to 15 oz per square yard, engineered for stretching, priming, and direct pigment application. The material serves as the foundational support structure for fine art painting, commercial digital printing, and protective cover applications across industrial and consumer markets. Cotton canvas dominates volume flows within the product type dimension due to established artist preference and breathability, while polyester canvas captures share in commercial printing for its dimensional stability under humidity variation. The coating type dimension concentrates margin pools in acrylic-coated and fire-retardant categories, where technical certification requirements create supplier stickiness and pricing power.
REACH in Europe and the EPA's TSCA framework in the United States govern chemical emissions from coating processes and substrate treatments, pushing manufacturers toward water-based acrylic systems and lower-VOC primers. India's BIS certification for textile durability and flammancy standards shapes import competitiveness for foreign suppliers. Fire-safety regulations across commercial venue applications are elevating specification complexity for fire-retardant coated grades. Stakeholders must monitor evolving certification reciprocity between regional frameworks and assess captive coating capacity as a strategic hedge against formulation compliance costs.
Market Dynamics
Commercial large-format printing is compressing traditional artist-canvas supply chains as digital printshops demand polyester substrates with tighter dimensional tolerances than cotton equivalents.
Growth Catalysts
- REACH compliance in Europe:Chemical safety mandates are pushing coating houses toward water-based acrylic primers that reduce VOC emissions, creating specification pull for certified suppliers.
- Fire-retardant grade demand from commercial venues:Event halls and hospitality spaces require B1-rated substrates, elevating technical barriers and locking in premium pricing for certified mills.
- India's textile belt expansion:Domestic weaving and finishing clusters in Tamil Nadu and Gujarat are reducing import dependency for raw cotton canvas.
Market Restraints
- Cotton price volatility:Raw fiber costs swing with monsoon patterns and global commodity markets, squeezing margin predictability for natural substrate producers.
- Supply concentration in Asian coating capacity:A narrow base of specialized finishers controls fire-retardant and archival-grade treatment output.
- Polyester substitution in commercial printing:Synthetic alternatives capture share in humidity-sensitive applications where dimensional stability outweighs artist preference.
Strategic Opportunities
- Underpenetrated fine art reproduction in Southeast Asia:Gallery and museum-quality printing infrastructure remains sparse in Indonesia and Vietnam.
- EU Green Deal procurement mandates:Public sector art commissions increasingly specify recycled-content or bio-based substrate alternatives.
- Direct-to-studio e-commerce channels:Online platforms bypass traditional distributor markups, capturing margin and customer data simultaneously.
Industry Challenges
- Certification timeline compression:Fire-safety and archival testing protocols require 6-12 month validation cycles that lag product development schedules.
- Coating chemistry talent scarcity:Formulation expertise for archival-grade primers concentrates among retiring specialists with limited knowledge transfer pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canvas Roll Market |
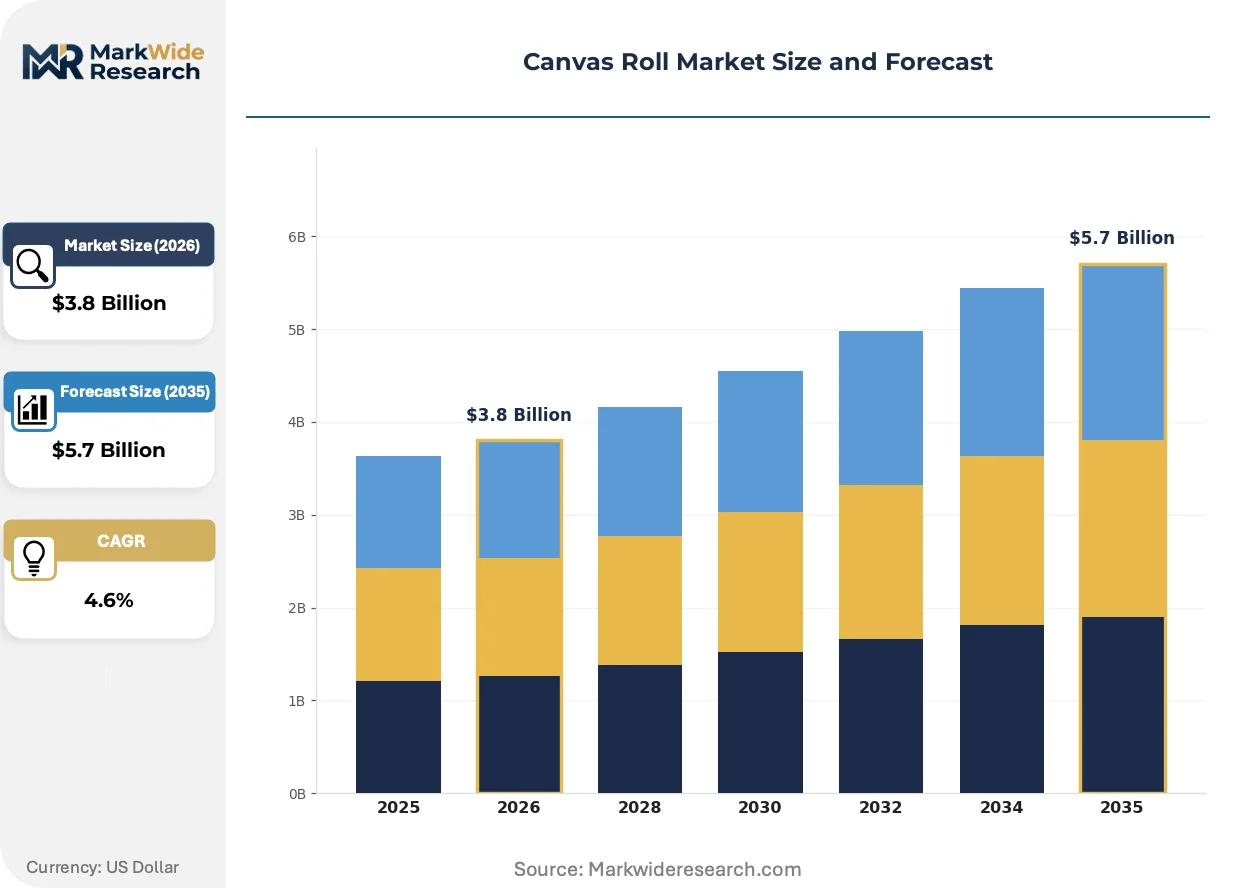
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof Canvas, Cotton Canvas, Polyester Canvas, Blended Canvas End Use: Commercial Printing, Art Supplies, Outdoor Equipment, Upholstery Thickness: Heavyweight, Mediumweight, Lightweight, Extra Lightweight Coating Type: Uncoated, Acrylic Coated, PVC Coated, Fire Retardant |
| Companies Covered | Jack Richeson & Co., Inc., Blick Art Materials, Fredrix Artist Canvas, US Art Supply, Art Alternatives, Arteza, Masterpiece Artist Canvas, Jerry’s Artarama, Winsor & Newton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canvas Roll Market Strategic Shifts
Digital printing workflows are rewiring substrate specifications as printheads achieve finer droplet control, demanding surface engineering that bridges artistic tradition with industrial throughput.
Water-based UV-curable primers are collapsing the performance gap between solvent and aqueous coating systems. Commercial printshops in Germany and the Netherlands are adopting these formulations at accelerating rates. The technology is collapsing capital barriers for mid-scale coating operations seeking archival-grade output without emission control infrastructure.
REACH SVHC candidate list expansions are forcing reformulation of legacy flame-retardant chemistries. Coating houses face 18-month transition windows to substitute halogenated compounds. Professional art supply retail in France and Italy is most affected, with buyers now demanding full material disclosure documentation.
Studio procurement patterns are fragmenting as individual artists bypass regional distributors for direct mill relationships. Online marketplaces and manufacturer-direct portals are displacing brick-and-mortar art supply stores for bulk canvas purchases. This channel shift concentrates in North America and Australia where studio density supports container-direct minimums.
Canvas Roll Market Segmentation
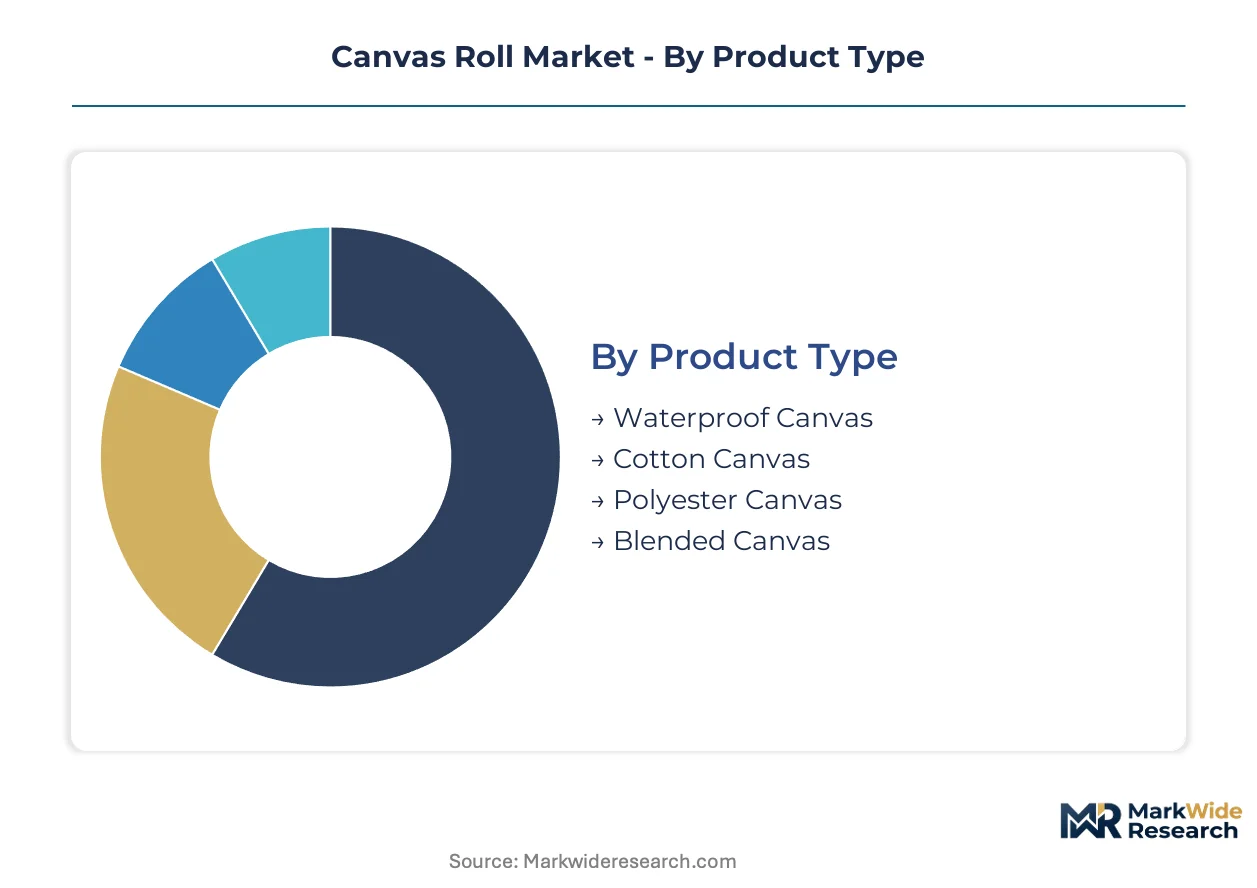
Canvas roll segmentation separates artistic heritage from industrial utility. Material composition, coating chemistry, and end-use durability requirements create distinct procurement channels with minimal overlap between fine art studios and commercial print operations.
Product Type:
Artists demand breathability and tooth; commercial operators prioritize dimensional stability under humidity stress.
- Cotton Canvas:Woven from natural cellulose fibers in weights spanning 5 oz to 15 oz per square yard, prized for moisture absorption that prevents paint film cracking. Demand concentrates in professional art supply retail across Germany and France, where REACH-compliant water-based primers now dominate coating specifications.
- Polyester Canvas:Synthetic polyethylene terephthalate weave delivering sub-0.5% moisture expansion, essential for large-format digital printing in event graphics and retail display. Commercial printshops in the Netherlands and California are standardizing on this substrate for humidity-sensitive outdoor installations.
- Waterproof Canvas:Tight-weave cotton or synthetic base with wax or polymer barrier treatment for marine and tenting applications.
- Blended Canvas:Cotton-polyester hybrid yarns balancing artistic hand with mechanical stability for educational and hobbyist markets.
The dominant share belongs to Cotton Canvas, while Polyester Canvas is closing the gap fastest.
End Use:
Volume flows split between pigment-bearing substrates and protective covering applications with opposing performance requirements.
- Commercial Printing:Wide-format inkjet and UV-cured output for retail graphics, museum reproductions, and architectural rendering. Tamil Nadu's textile finishing clusters are scaling coating capacity to serve Southeast Asian printshop demand.
- Art Supplies:Stretched and primed supports for oil, acrylic, and mixed-media painting. Winsor & Newton's archival-grade coating chemistry commands premium placement in UK and Italian professional retail.
- Outdoor Equipment:Tentage, pack fabric, and protective covers requiring tear strength and UV degradation resistance.
- Upholstery:Decorative and contract furniture applications where abrasion resistance and flame certification intersect.
Commercial Printing commands the largest volume, though Art Supplies retains the highest margin per linear meter.
Thickness:
Weight classification signals structural load-bearing capacity and stretching behavior under tension.
- Mediumweight:8 oz to 10 oz per square yard, the workhorse specification balancing portability and structural integrity for studio painting and moderate-scale printing. Fredrix Artist Canvas mills in Georgia optimize output at this weight tier for North American distributor supply.
- Heavyweight:12 oz and above, selected for large unstretched works and aggressive paint application where sag resistance is paramount. Museum conservation departments in New York and London specify this grade for oversized contemporary pieces.
- Lightweight:6 oz to 7 oz, favored for travel easels and plein air setups where kit weight constrains selection.
- Extra Lightweight:Below 6 oz, restricted to sketching surfaces and temporary display applications with minimal durability requirements.
Mediumweight absorbs the greatest production volume, with Heavyweight expanding most quickly in institutional procurement.
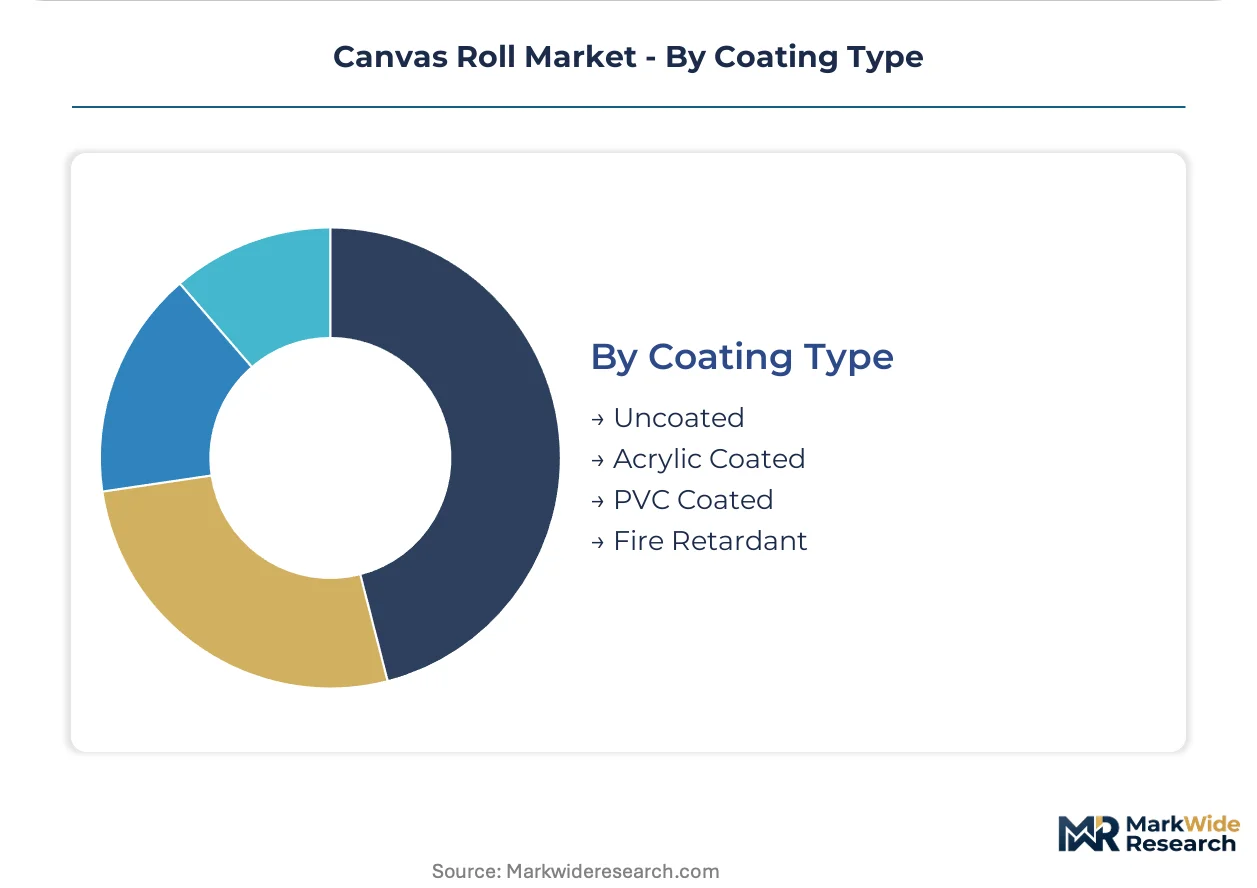
Coating Type:
Surface chemistry determines archival longevity, ignition behavior, and ink adhesion across divergent end-use environments.
- Acrylic Coated:Water-based primer systems delivering pH-neutral, flexible ground layers compatible with oil and acrylic media. German coating houses are converting solvent lines to meet EU Green Deal procurement mandates for public art commissions.
- Fire Retardant:Halogen-free or phosphorus-based treatments achieving B1 classification for event venues and hospitality interiors. Certification testing protocols require 6-12 month validation cycles that lag product development schedules.
- Uncoated:Raw woven substrate for custom priming by conservators and specialized studio practitioners.
- PVC Coated:Vinyl barrier treatments for industrial tarpaulin and truck cover applications outside fine art supply chains.
Acrylic Coated holds the established position, though Fire Retardant is climbing the fastest as commercial venue regulations tighten across France, Italy, and Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance requirements across the European Union are reshaping coating chemistry specifications, while India's BIS certification framework and the United States' EPA TSCA oversight create divergent regulatory entry barriers for substrate suppliers.
United States
Commercial printshops in California and New York Metro drive polyester canvas consumption for large-format retail graphics and museum reproductions. EPA TSCA framework governs chemical emissions from coating processes, pushing manufacturers toward water-based acrylic primer systems. Georgia-based weaving operations supply mediumweight cotton grades to North American distributor networks.
Germany
Professional art supply retail in Berlin and Munich commands archival-grade acrylic-coated canvas with full material disclosure documentation. EU Green Deal procurement mandates for public art commissions accelerate conversion from solvent-based to aqueous coating lines. Coating houses in the Ruhr region face 18-month transition windows to substitute halogenated flame-retardant compounds under REACH SVHC expansions.
India
Tamil Nadu and Gujarat textile clusters scale domestic weaving and finishing capacity to reduce import dependency for raw cotton canvas. BIS certification for textile durability and flammancy standards shapes import competitiveness for foreign suppliers. Mumbai and Delhi-NCR studio density supports direct-to-mill procurement patterns bypassing traditional distributor channels.
France
Event venue and hospitality interior specifications in Paris and Lyon elevate demand for B1-rated fire-retardant substrates. REACH compliance timelines compress product development cycles as coating houses validate reformulated chemistries. Conservation departments in Marseille specify heavyweight grades for oversized contemporary pieces requiring sag resistance.
Netherlands
Commercial printshops in Amsterdam and Rotterdam standardize on polyester canvas for humidity-sensitive outdoor installations requiring sub-0.5% moisture expansion. Water-based UV-curable primer adoption accelerates among mid-scale coating operations seeking archival-grade output without emission control infrastructure. Eindhoven-region technical textile research clusters advance surface engineering for digital printhead compatibility.
Canvas Roll Market Competitive Environment
Heritage art supply houses and digital-native direct-to-consumer platforms split the market into divergent channel architectures. The vendor base concentrates among three strategic archetypes: vertically integrated domestic mill networks, distributor-anchored multi-brand retailers, and formulation-specialist coating houses. Capacity expansion in South Asian weaving clusters and strategic partnerships between coating houses and commercial printshop networks represent the dominant competitive moves reshaping supply relationships.
Within the heritage mill archetype, Fredrix Artist Canvas and Masterpiece Artist Canvas exemplify vertically integrated production models. Blick Art Materials and Jerry's Artarama occupy positions across the distributor-retailer spectrum. Winsor & Newton represents the formulation-specialist tier with coating chemistry capabilities. These named entities anchor industry-level commentary on channel control, certification compliance, and procurement pattern fragmentation without implying specific strategic actions or financial positions beyond their visible market presence.
| Leading Market Players |
|---|
| Jack Richeson & Co., Inc. |
| Blick Art Materials |
| Fredrix Artist Canvas |
| US Art Supply |
| Art Alternatives |
| Arteza |
| Masterpiece Artist Canvas |
| Jerry's Artarama |
| Winsor & Newton |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit cotton fiber cost volatility directly into European coating house margins, while Asian textile clusters exploit logistics savings to widen price spreads between premium archival grades and commodity uncoated rolls.
Pricing Analysis
Price spreads between German professional retail and Indian direct-mill procurement exceed threefold for equivalent mediumweight cotton grades. Three-tier pricing structure across premium archival, certified commercial, and economy hobbyist levels dominates the market, with REACH-compliant water-based primers and B1 fire-retardant certification commanding substantial premiums. Pricing pressure stems from polyester substitution in commercial printing, where synthetic substrates undercut natural fiber equivalents on dimensional stability metrics. Commercial printshops exhibit highest price sensitivity, while museum conservation departments absorb premium archival coatings without volume negotiation.
Supply Chain Analysis
Raw cotton fiber draws from Mississippi Delta gins, Gujarat spinning mills, and Egyptian long-staple cooperatives as primary upstream inputs. Coating chemistry concentrates in German Ruhr-region specialists, Tamil Nadu textile finishing clusters, and Georgia-based mill networks. Supply chain risk centers on single-source dependency for halogen-free flame-retardant formulations facing REACH SVHC transition deadlines. Distribution runs through direct-to-studio e-commerce portals, North American distributor-anchored retailers, and Southeast Asian printshop network partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canvas roll demand sits in early-cycle expansion as commercial large-format printing infrastructure penetrates Southeast Asian markets previously served by import-dependent gallery networks.
For Market Incumbents: Insulate coating chemistry margins by securing captive supply of water-based UV-curable primer formulations before REACH SVHC transition windows close. Deepen backward integration into Tamil Nadu weaving clusters to offset cotton price volatility exposure. Fredrix Artist Canvas and Winsor & Newton demonstrate how archival-grade certification investment creates distributor lock-in against polyester substitution threats. For New Entrants and Emerging Players: Establish a beachhead in Indonesia and Vietnam fine art reproduction infrastructure, where gallery-quality printing capacity remains sparse relative to regional demand growth. Target fire-retardant coated grades for Paris and Lyon event venue procurement, where B1 certification requirements create technical barriers protecting early movers. Deploy direct-to-studio e-commerce platforms with container-direct minimums to bypass entrenched distributor markups in North America and Australia. For Investors and Strategic Acquirers: REACH SVHC candidate list expansion reshapes the acquisition landscape toward coating houses with validated halogen-free formulation pipelines. Long-term viability favors specialists combining archival-grade chemistry expertise with captive South Asian weaving capacity. Watch for reciprocity agreements between India's BIS certification and European REACH frameworks as the inflection signal for cross-regional supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Ginning | Georgia and Gujarat mill networks secure fiber cost predictability against monsoon volatility. |
| Water-Based UV-Curable Primer Conversion | German coating houses meet EU Green Deal mandates without emission control capital expenditure. |
| Fire-Retardant Certification Investment | B1-rated substrate suppliers capture premium pricing from Paris and Lyon hospitality interiors. |
| Direct-to-Studio E-Commerce Launch | Online portals displace Blick Art Materials and Jerry's Artarama distributor markups in North America. |
| Southeast Asian Printshop Partnership | Tamil Nadu finishing clusters serve Jakarta and Ho Chi Minh City museum reproduction demand. |
Study Parameters
A standing panel of coating house technical directors, commercial printshop procurement managers, fine art supply retail buyers, and textile mill operations heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade databases, BIS certification registries, and ECHA REACH submission filings. Bottom-up volume triangulation from mill output records and top-down demand estimation from printshop capacity expansion announcements converged on segment-level projections.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include material composition, coating chemistry tier, end-use durability requirements, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating cotton fiber price indices and digital printing equipment deployment rates. Industry-specific inputs encompassed REACH SVHC transition timelines and BIS flammancy standard reciprocity negotiations.
Sensitivities concentrate around cotton commodity price spikes, coating chemistry reformulation delays, and fire-safety certification timeline compression. Forecasts reflect documented assumptions regarding polyester substitution rates and e-commerce channel penetration. Cross-checking against ECHA registration statistics and Indian textile export customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market