
 Global Cashmere Yarn Market | 2026-2036
Global Cashmere Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cashmere Yarn Market Analysis
Direct sourcing agreements between Mongolian herding cooperatives and European spinners is reconfiguring traditional wholesale brokerage channels. King Deer leverages in-house scouring and dyeing capacity to control quality consistency from raw fiber to finished cone. Consinee Group anchors its position through vertical integration across Inner Mongolia's Hohhot industrial zone. Erdos Group differentiates via brand equity that extends from pastoral sourcing narratives to retail shelf presence.
Cashmere yarn consists of fine animal fibers harvested from Capra hircus goats, typically measuring under 19 microns in diameter and processed through dehairing, carding, and ring-spinning sequences to produce luxury textiles with exceptional warmth-to-weight ratios. Knitted yarn commands the largest volume share as sweater and accessory manufacturers specify its loft and elasticity characteristics. Woven yarn occupies premium margin pools in suiting and coat applications where tensile strength and drape precision justify higher per-kilogram pricing. Blended yarn, combining cashmere with silk or merino, represents the fastest-expanding category as mills seek to moderate raw material cost exposure while preserving tactile luxury cues.
REACH registration requirements in Europe mandate chemical disclosure throughout dyeing and finishing stages, while China's GB standards govern fiber content labeling and dehairing effluent discharge limits. The International Wool Textile Organization's Cashmere Guidelines provide voluntary grading protocols that major spinners adopt to assure downstream buyers. Stakeholders must monitor how climate stress on Mongolian pasturelands affects fiber diameter consistency and herder contract stability.
Market Dynamics
Direct sourcing agreements between Mongolian herding cooperatives and European spinners are collapsing traditional wholesale brokerage tiers, compressing margin extraction at intermediary levels while elevating traceability premiums for origin-verified fiber.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA registration requirements for dyeing auxiliaries and finishing agents are accelerating investment in closed-loop effluent systems at Italian and French finishing houses.
- Inner Mongolia fiber clustering:Raw cashmere collection and early-stage scouring concentrate in China's autonomous region, creating scale economies that lower unit processing costs for downstream spinners.
- Fine-count yarn specification:Luxury knitwear manufacturers in Milan and Paris are expanding technical requirements for sub-16 micron counts, pulling premium fiber volumes away from commodity grades.
Market Restraints
- Pastureland degradation:Climate stress on Mongolian grasslands is narrowing the geographic window for fiber collection and increasing diameter variability in harvested lots.
- GB labeling enforcement:China's SAMR fiber content verification rules are extending compliance timelines for export-bound yarn lots, creating inventory friction at port.
- Silk-merino substitution:Blended luxury yarns combining alternative protein fibers are capturing price-sensitive positioning in accessory manufacturing.
Strategic Opportunities
- Blockchain traceability protocols:The International Wool Textile Organization's voluntary grading standards are creating infrastructure for tokenized provenance claims that command retail shelf premiums.
- South Korean duty-free retail:Incheon and Seoul airport luxury corridors remain underpenetrated by origin-branded cashmere knitwear, offering direct-to-consumer bypass of traditional wholesale.
- Dual carbon alignment:China's MEE discharge limits and EU Green Deal border adjustments are converging to reward early adopters of renewable thermal energy in scouring operations.
Industry Challenges
- Dehairing technician scarcity:Mechanical fiber separation requires specialized operators trained on specific equipment configurations, with training pipelines concentrated in Hohhot industrial zone.
- Multi-standard certification overlap:Simultaneous compliance with IWTO Cashmere Guidelines, OEKO-TEX, and brand-specific restricted substance lists extends batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cashmere Yarn Market |
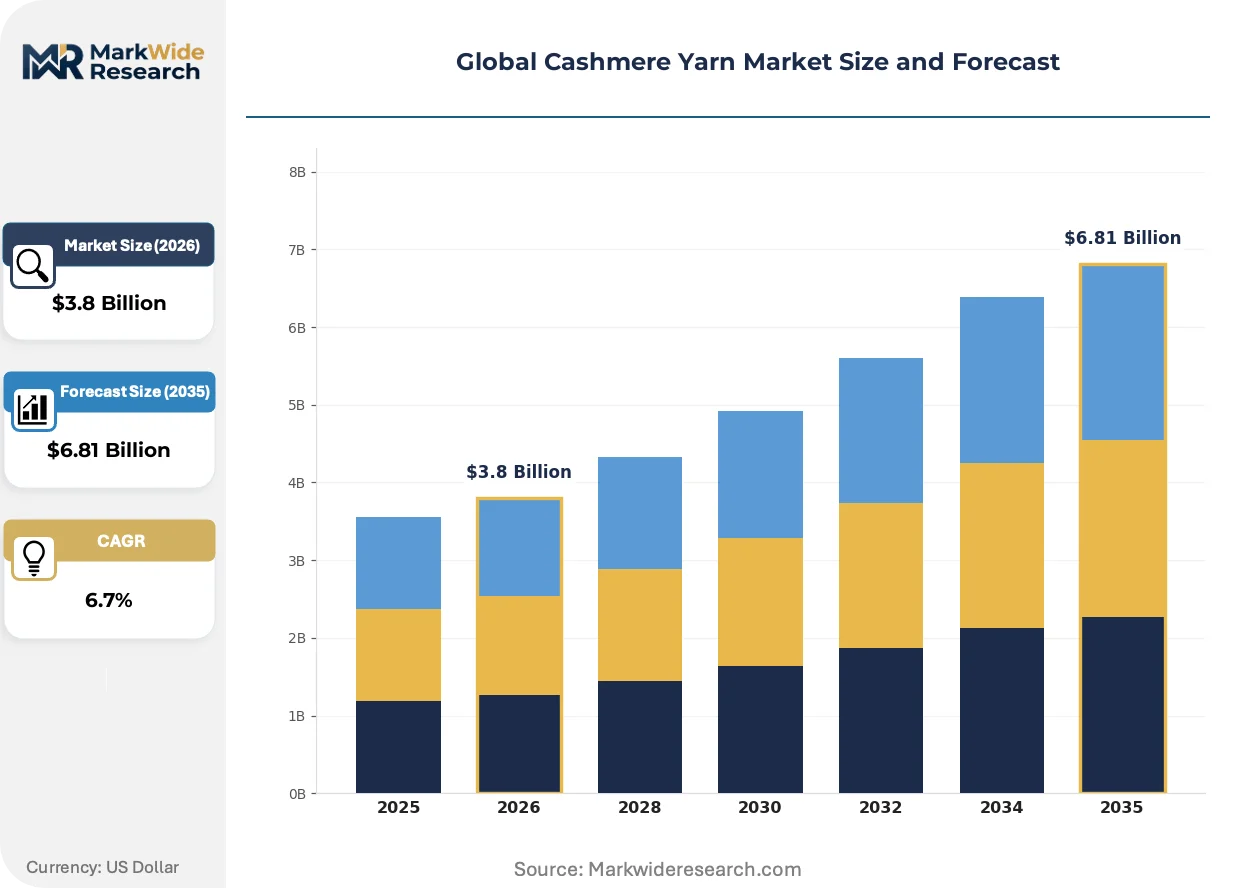
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knitted Yarn, Woven Yarn, Blended Yarn, Specialty Yarn End User: Fashion Apparel, Home Textiles, Accessories, High-Performance Clothing Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale Distributors, Direct Sales Quality Grade: Premium Grade, Standard Grade, Economy Grade, Organic Grade |
| Companies Covered | King Deer, Hongye Cashmere, Consinee Group, Rongchang Cashmere, Jiayuan Cashmere, Zhejiang Xinao Textiles, Dongbao Cashmere Product, Shengxuehai Cashmere Group, Erdos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cashmere Yarn Market Emerging Trajectories
Near-infrared spectroscopy deployed at fiber collection points is digitizing quality assessment, compressing the information asymmetry between pastoral suppliers and industrial buyers that historically defined trading relationships.
NIR-based micron testing equipment installed at Mongolian cooperative collection stations is digitizing real-time diameter mapping before bales reach scouring facilities. Italian spinners are integrating these data streams into raw material procurement algorithms, bypassing traditional broker grading. This compression of quality verification cycles is digitizing price discovery and reducing arbitration disputes over lot consistency.
ECHA's expanded REACH authorization requirements for chromium-based dye mordants are forcing substitution toward bio-based metal complexes across European finishing operations. The industrial consequence is elevated R&D spend at dyestuff houses and extended color-matching timelines for heritage shade libraries. Italian luxury knitwear brands with established palette commitments face the steepest reformulation costs and are responding by consolidating supplier bases to capture technical service support.
Brand-led direct contracting with herding cooperatives is displacing spot-market fiber acquisition as the dominant upstream sourcing modality. European spinners and Japanese trading houses are establishing multi-year offtake agreements with guaranteed floor prices, replacing auction-based volume allocation. This behavioral shift is most visible in China's Inner Mongolia autonomous region, where cooperative managers now maintain dedicated liaison staff for foreign buyer relationship management.
Global Cashmere Yarn Market Segmentation
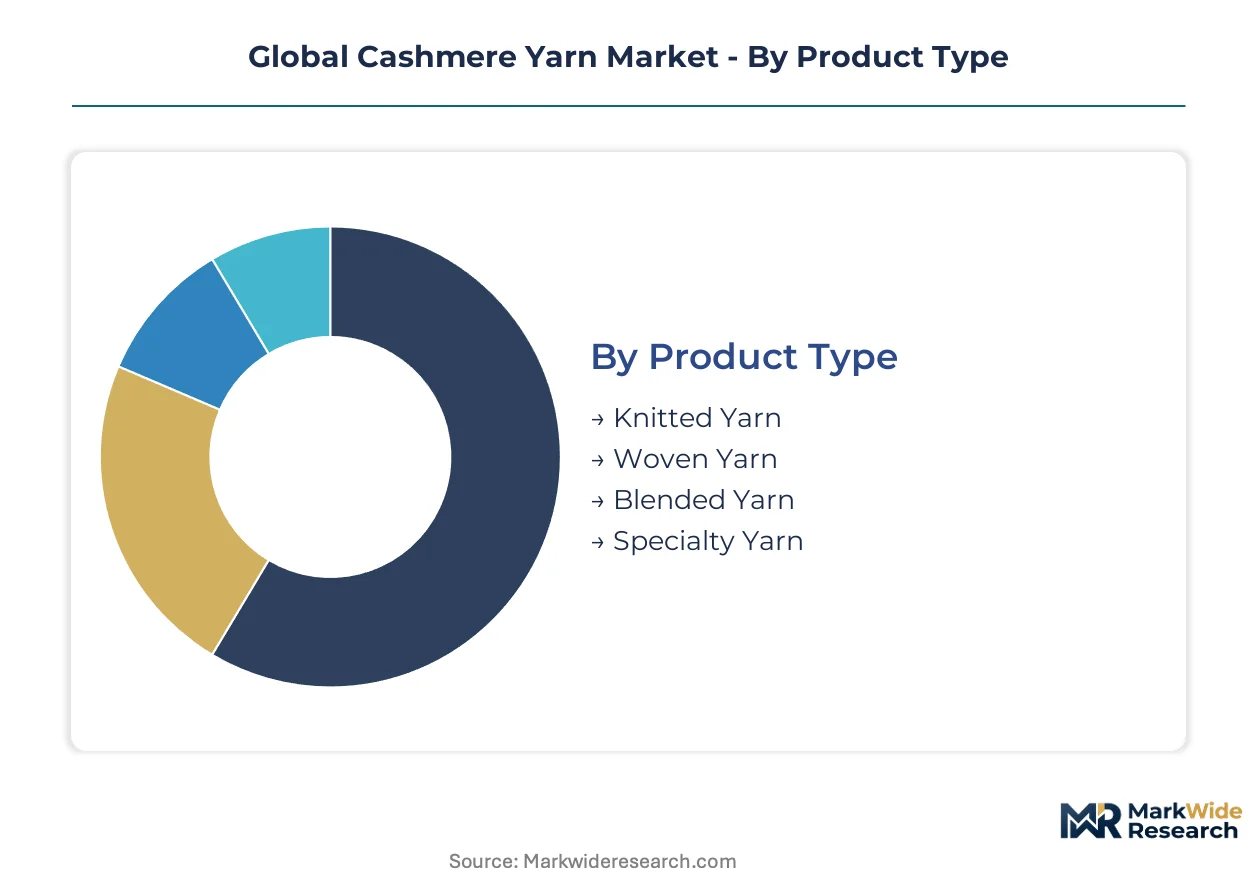
Cashmere yarn segmentation reveals divergent inventory velocities across product categories. Cycle times compress sharply for fashion-facing grades while technical specifications extend procurement lead times for premium woven applications.
Product Type:
Knitted yarn turns inventory fastest through seasonal replenishment cycles, while specialty yarn sits longest awaiting custom dye matches and small-batch finishing slots.
- Knitted Yarn:Fine-count ring-spun construction optimized for loft and elasticity in sweater manufacturing. Italian luxury knitwear houses in Milan drive specification intensity for sub-16 micron counts, compressing supplier response windows to six-week seasonal cycles.
- Woven Yarn:Higher-twist ply structures engineered for tensile strength in suiting and coat applications. Parisian tailoring ateliers specify this grade for drape precision, though extended color-matching timelines under ECHA REACH dye substitution mandates slow batch release.
- Blended Yarn:Cashmere-silk and cashmere-merino combinations moderating raw material cost exposure.
- Specialty Yarn:Technical constructions including core-spun and air-jet textured variants for performance applications.
Knitted yarn anchors the volume base while blended yarn gains share at the steepest rate.
End User:
Margin concentration varies sharply across end-use applications, with fashion apparel capturing volume scale and high-performance clothing extracting premium per-kilogram realizations.
- Fashion Apparel:Sweater and outerwear manufacturing dominates fiber offtake, with European luxury houses and Japanese trading houses anchoring multi-year contracting.
- Accessories:Scarves, gloves, and small leather-goods-adjacent knit items turning fastest through duty-free retail channels at Incheon and Seoul airports.
- Home Textiles:Throws and bedding applications requiring heavier gauge counts and extended staple preparation.
- High-Performance Clothing:Technical base layers and alpine sport applications demanding micron consistency and moisture-wicking finishes.
Fashion apparel commands the revenue base while accessories expand most quickly through underpenetrated airport retail corridors.
Distribution Channel:
Channel selection directly determines working capital intensity, with wholesale distributors demanding longest payment terms and direct sales compressing margin leakage.
- Wholesale Distributors:Traditional brokerage tiers aggregating Mongolian and Inner Mongolian fiber lots for European spinners. These intermediaries face margin compression as direct cooperative contracting accelerates.
- Direct Sales:Brand-led contracting with herding cooperatives and scouring facilities, eliminating arbitrage layers. King Deer and Consinee Group leverage this channel for quality consistency control.
- Online Retail:E-commerce platforms for finished yarn cones and small-batch sampling.
- Brick-and-Mortar Stores:Physical presence concentrated in Hohhot industrial zone for domestic Chinese procurement.
Wholesale distributors still handle the volume base while direct sales climbs fastest as traceability premiums reshape upstream sourcing.
Quality Grade:
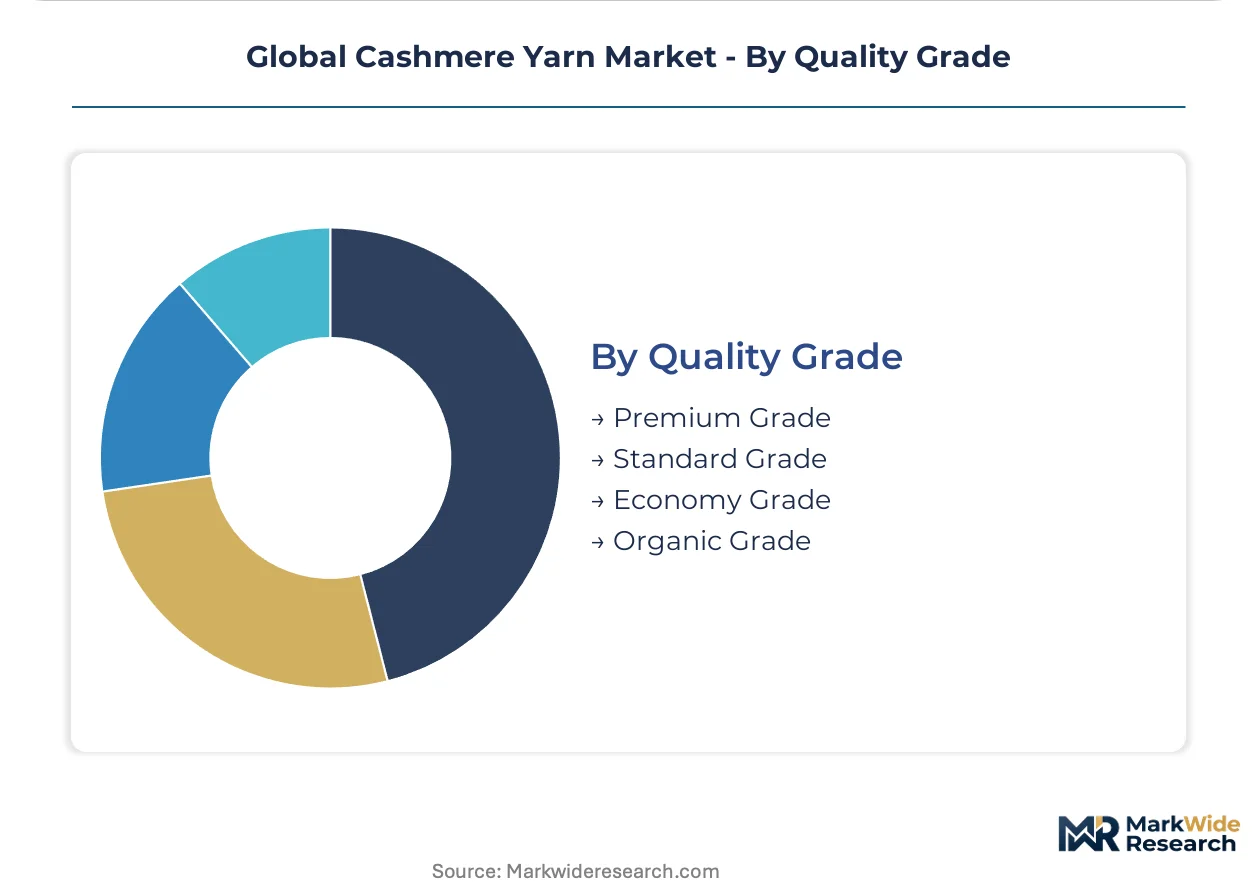
Certification tiering creates price stratification that separates origin-verified fiber from commodity grades, with organic commanding the steepest testing and documentation burden.
- Premium Grade:Sub-16 micron fiber with full provenance documentation and IWTO Cashmere Guidelines certification. Italian spinners pay traceability premiums for blockchain-verified Mongolian origin.
- Organic Grade:Pasture-certified fiber meeting dual carbon alignment standards under China's MEE discharge limits and EU Green Deal border adjustments.
- Standard Grade:Mid-micron counts serving commercial knitwear manufacturers with moderate certification requirements.
- Economy Grade:Broader diameter tolerance for price-accessory manufacturing facing silk-merino substitution pressure.
Premium grade holds the margin base while organic grade expands most steeply as dual carbon convergence rewards early renewable thermal adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH chemical disclosure mandates and China's dual carbon alignment under MEE discharge limits are reshaping procurement geography. Italian and French spinners now prioritize origin-verified Mongolian fiber with full provenance documentation.
China
Inner Mongolia's Hohhot industrial zone anchors upstream processing capacity for scouring and dehairing operations. SAMR's GB fiber content labeling standards extend compliance timelines for export-bound yarn lots. The autonomous region's cooperative managers now maintain dedicated liaison staff for European and Japanese buyer relationship management.
Italy
Milan-based luxury knitwear houses drive specification intensity for sub-16 micron counts through six-week seasonal replenishment cycles. ECHA's expanded REACH authorization requirements for chromium-based dye mordants force substitution toward bio-based metal complexes. Piedmont and Lombardy finishing houses consolidate supplier bases to capture technical service support for heritage shade reformulation.
France
Parisian tailoring ateliers specify high-twist woven yarn grades for drape precision in suiting applications. EU Green Deal border adjustments converge with China's MEE standards to reward renewable thermal energy adoption in scouring operations. The Île-de-France region hosts brand headquarters directing multi-year offtake agreements with Mongolian herding cooperatives.
Mongolia
Pastoral fiber collection faces narrowing geographic windows from climate stress on grassland ecosystems. The country's herding cooperatives negotiate direct sourcing agreements with European spinners and Japanese trading houses, displacing traditional auction-based volume allocation. Ulaanbaatar-based cooperative managers deploy near-infrared spectroscopy at collection points for real-time diameter mapping.
South Korea
Incheon and Seoul airport luxury corridors remain underpenetrated by origin-branded cashmere knitwear accessories. Duty-free retail channels offer direct-to-consumer bypass of traditional wholesale brokerage tiers. Seoul-based trading houses intermediate between Inner Mongolian processors and domestic fashion distributors seeking traceability-verified fiber.
Global Cashmere Yarn Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated processors with captive scouring capacity and direct cooperative contracting relationships. Three archetypes dominate: Inner Mongolian industrial-zone operators controlling upstream dehairing infrastructure, European brand-anchored spinners prioritizing micron consistency and provenance documentation, and trading houses facilitating multi-year offtake agreements with floor-price guarantees. Competitive moves concentrate on backward integration into pastoral sourcing and strategic partnerships for blockchain traceability infrastructure.
Among Inner Mongolian operators, King Deer exemplifies the integrated-processor archetype through in-house scouring and dyeing capacity, while Consinee Group anchors the Hohhot industrial zone's cluster density. Erdos Group occupies a distinct position extending from pastoral sourcing narratives to retail shelf presence, representing the brand-equity vector that commands traceability premiums in European procurement algorithms.
| Leading Market Players |
|---|
| King Deer |
| Hongye Cashmere |
| Consinee Group |
| Rongchang Cashmere |
| Jiayuan Cashmere |
| Zhejiang Xinao Textiles |
| Dongbao Cashmere Product |
| Shengxuehai Cashmere Group |
| Erdos Group |
| Others |
Supply Flow & Price Mechanics
Climate stress on Mongolian pasturelands determines both the widening spread between premium and economy yarn tiers and the geographic consolidation of upstream procurement. Herding cooperatives now demand floor-price guarantees in multi-year contracts, compressing spot-market liquidity while elevating traceability premiums for origin-verified fiber.
Pricing Analysis
Certification level under IWTO Cashmere Guidelines creates the primary spread between transaction tiers, with blockchain-verified Mongolian origin commanding substantial premiums from Italian spinners. Three-tier pricing structure across premium, standard, and economy levels reflects micron count precision and provenance documentation depth. Cost compression in economy grades intensifies because silk-merino blends capture price-sensitive accessory manufacturing. Brand-led direct contracting shows least price sensitivity, while wholesale distributors face margin erosion from disintermediation.
Supply Chain Analysis
Extended payment terms from European luxury houses now stretch to 120 days, forcing Inner Mongolian processors to rely on supply-chain finance facilities for working capital. Raw material sourcing concentrates in Mongolia, China, and Afghanistan, with dehairing capacity clustering in Hohhot industrial zone. Mechanical fiber separation draws from specialized technician pipelines concentrated in specific equipment configurations. Single-source vulnerability runs through Mongolian pastoral collection windows narrowed by grassland degradation. Distribution runs through direct cooperative contracting displacing traditional wholesale brokerage tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
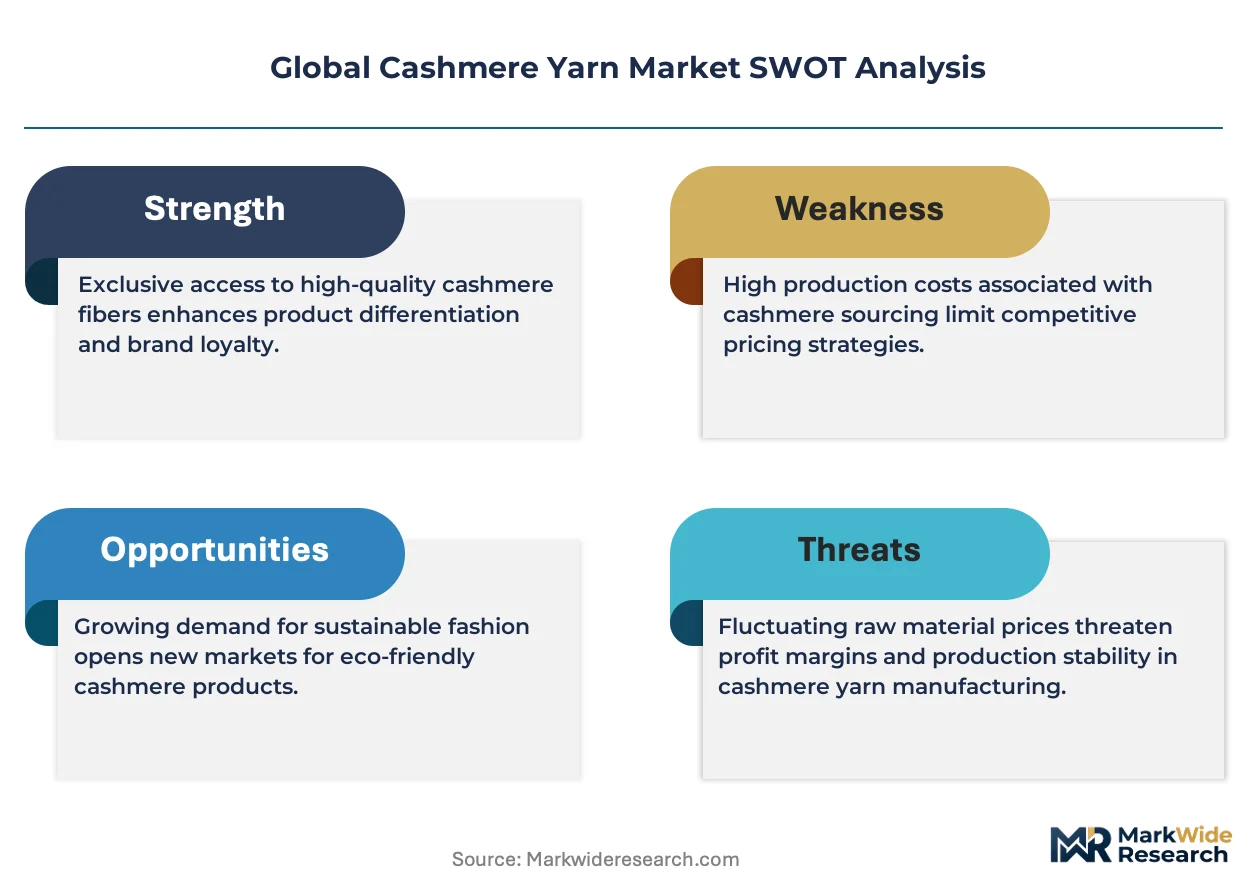
Traceability infrastructure adoption represents an early-cycle expansion story as European REACH mandates and Chinese dual carbon alignment converge to reward provenance-verified supply chains. The window favors operators with captive upstream relationships and certification-ready processing assets.
For Market Incumbents: Pre-empt silk-merino substitution in economy tiers by accelerating R&D into bio-based fiber blends that preserve tactile luxury cues. Secure multi-year offtake agreements with Mongolian cooperatives before Japanese trading houses consolidate remaining pastoral supply. Vertical integration into renewable thermal energy for scouring operations captures dual carbon alignment rewards.
For New Entrants and Emerging Players: South Korean duty-free retail corridors at Incheon and Seoul airports represent the most penetrable entry point for origin-branded cashmere accessories, with traditional wholesale channels already saturated. Blockchain-enabled provenance marketing offers direct-to-consumer bypass of established brokerage tiers. Target technical base layer applications in high-performance clothing where micron consistency commands premium realizations absent entrenched supplier relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with captive scouring capacity and direct cooperative contracting infrastructure. Long-term viability hinges on climate adaptation capabilities across Mongolian sourcing regions. Watch NIR spectroscopy deployment rates at pastoral collection points as the signal for digitization maturity and price discovery compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pastoral Sourcing | Eliminates broker margins and secures floor-price guaranteed fiber streams from Mongolian cooperatives. |
| Blockchain Traceability Deployment | IWTO guideline-aligned tokenized provenance commands retail shelf premiums from European luxury houses. |
| Renewable Thermal Energy Conversion | China MEE discharge limits and EU Green Deal border adjustments reward early scouring facility adopters. |
| Near-Infrared Spectroscopy Installation | Real-time micron mapping at collection points compresses quality verification cycles and reduces arbitration disputes. |
| Multi-Year Offtake Agreement Structuring | Guaranteed volume commitments with herding cooperatives displace auction-based allocation and stabilize input costs. |
Methodological Framework
Desk research of customs trade databases, IWTO technical guidelines, and ECHA REACH authorization filings preceded structured interviews with cashmere mill procurement directors, herding cooperative managers, Italian luxury knitwear technical specification leads, and dyehouse R&D heads. Primary fieldwork across Inner Mongolia's Hohhot industrial zone and Mongolian pastoral collection regions validated secondary trade flow estimates. Bottom-up fiber volume modeling triangulated against top-down apparel consumption projections.
Assumptions held fixed include ECHA's expanded chemical disclosure mandates and China's GB fiber content labeling enforcement trajectory, while pastureland degradation severity and renewable energy adoption pace were varied across scenarios. Segmentation dimensions encompassed product type, quality grade, end-use application, and distribution channel structure. CAGRs derived from normalized historical trade volumes and projected luxury apparel consumption elasticity. Forecast inputs included climate stress indices for Mongolian grasslands and NIR spectroscopy deployment rates at cooperative collection stations.
Practitioners should monitor REACH authorization list expansions and MEE discharge limit revisions for early signals of regulatory cost pass-through requirements. Forecasts reflect documented assumptions about dual carbon alignment convergence and traceability premium sustainability. Macroeconomic volatility in luxury consumption, regulatory acceleration beyond modeled trajectories, or technological disruption in synthetic protein fibers would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market