
 Polypropylene Yarn Market | 2026-2036
Polypropylene Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Yarn Market Outlook
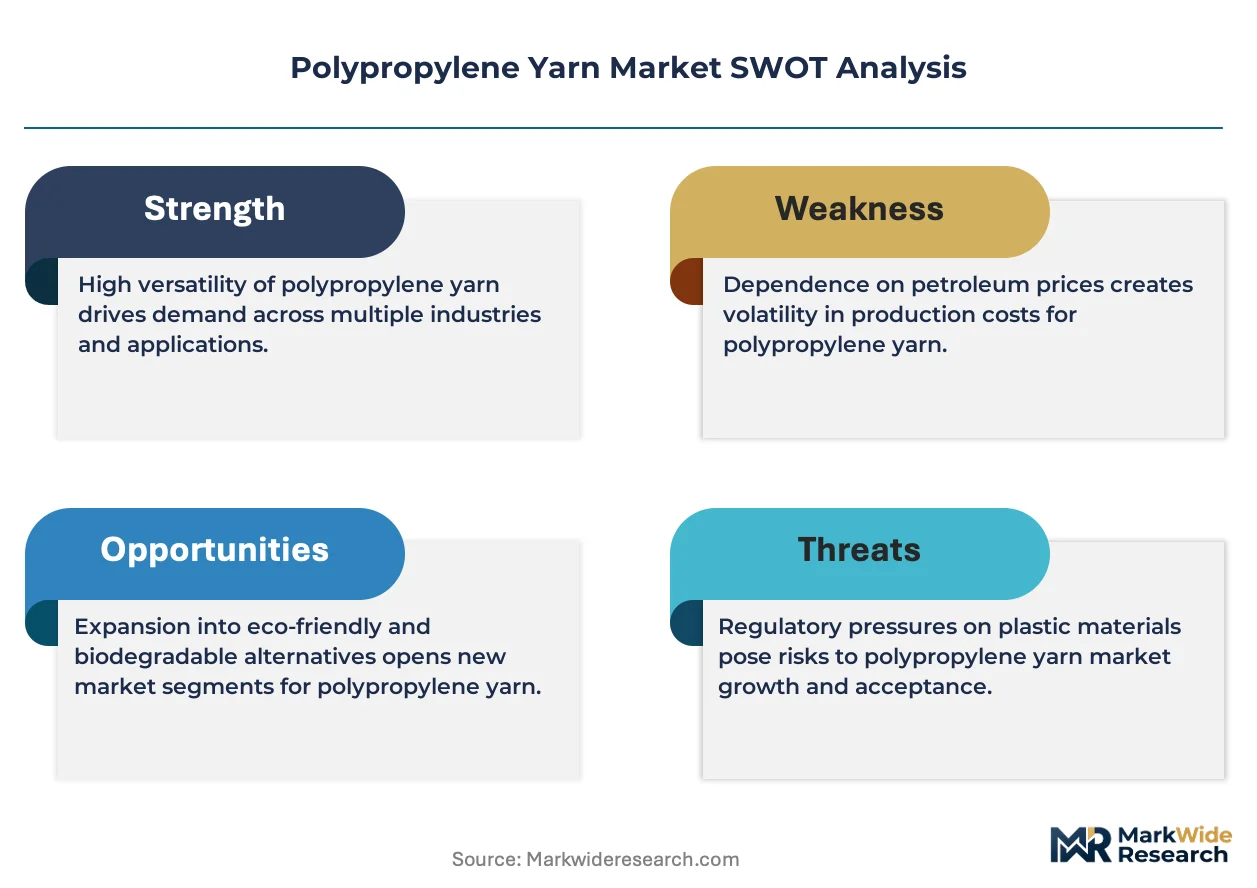
REACH compliance is rebalancing the cost-of-entry calculus for European polypropylene yarn suppliers. Indorama Ventures leverages its integrated petrochemical footprint to manage feedstock volatility. LyondellBasell Industries anchors its position through proprietary catalyst technology that reduces energy intensity in filament production. BASF differentiates via specialty additives that enhance UV resistance for outdoor applications.
Polypropylene yarn comprises extruded thermoplastic polymer filaments with a density of 0.90-0.91 g/cm³, manufactured through melt spinning of isotactic polypropylene resin for applications requiring chemical resistance and low moisture absorption. Staple fiber dominates volume consumption in nonwoven hygiene products, while BCF yarn captures premium margin pools in residential and commercial carpeting. Melt blowing technology is expanding fastest, driven by filtration media demand, though spun bonding retains scale leadership in geotextile and agricultural fabric production.
EPA regulations on industrial emissions constrain US-based melt spinning operations, while ECHA's microplastic restrictions under REACH reshape product formulation requirements across European supply chains. India's BIS certification mandates for textile-grade polypropylene are tightening import quality thresholds. Stakeholders must monitor how evolving extended producer responsibility frameworks in the EU and India alter recycling infrastructure investments and virgin resin substitution economics.
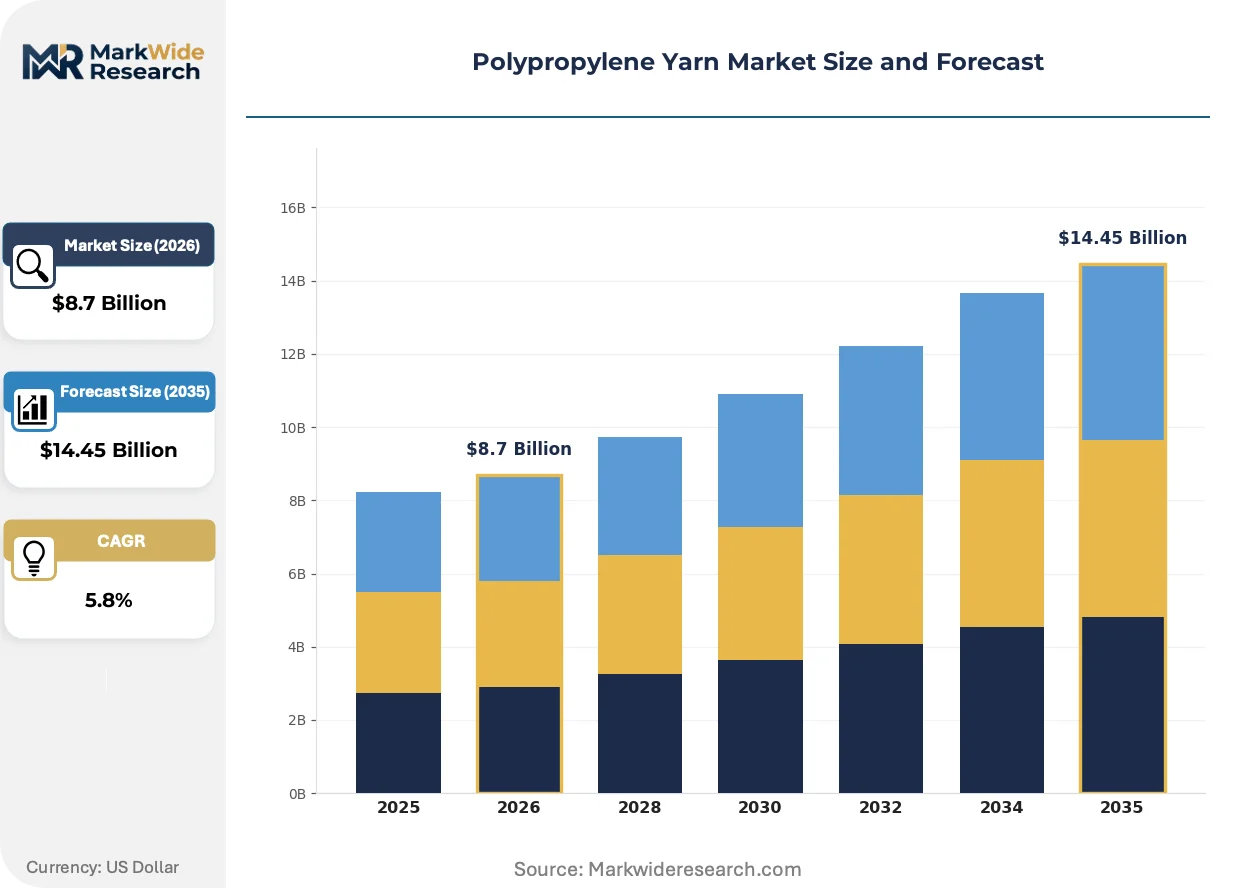
Market Dynamics
Geotextile infrastructure deployment is concentrating polypropylene yarn demand into high-volume, specification-grade contracts that favor producers with backward integration into resin supply and melt-spinning scale. This demand compression is restructuring competitive positioning around filament consistency, certification breadth, and logistics proximity to megaproject corridors.
Growth Catalysts
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks are accelerating mechanical recycling infrastructure investments, creating certified recycled-content yarn premiums for construction and automotive applications.
- India PLI scheme for technical textiles:Domestic manufacturing incentives are scaling BCF and staple fiber capacity to serve export-oriented carpet and nonwoven hygiene markets.
- Melt blowing process refinement:Filtration media specifications for industrial and healthcare applications are expanding fine-denier capacity utilization rates at integrated spunbond-meltblown-spunbond lines.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and PDH unit economics transmit directly to filament cost structures, compressing margin predictability for non-integrated spinners.
- Middle East supply concentration:Saudi Aramco and SABIC resin dominance creates single-source exposure for European and Asian yarn producers without captive polymerization.
- REACH microplastic restrictions:ECHA's synthetic polymer fiber shedding limits are constraining staple fiber formulation flexibility for apparel and home textile applications.
Strategic Opportunities
- Vietnam technical textile manufacturing:Underpenetrated geotextile and industrial fabric capacity offers first-mover positioning for producers establishing regional melt-spinning and texturing operations.
- Dual carbon goals in China:MIIT energy-intensity benchmarks are incentivizing recycled polypropylene filament adoption in construction reinforcement and agricultural mesh.
- Digital textile printing compatibility:BCF yarn surface modification for ink adhesion is opening specification wins in custom carpet and soft signage segments.
Industry Challenges
- Polymer rheology expertise scarcity:Melt index control and spinneret design optimization for high-speed spinning lines require specialized process engineering talent concentrated at legacy European and Japanese producers.
- Multi-certification timeline compression:Simultaneous BIS, REACH, and OEKO-TEX compliance for Indian export shipments extends qualification cycles and ties up technical documentation resources.
- Recycled-content feedstock traceability:Mass balance accounting and blockchain verification for post-consumer resin streams complicates supply chain audit readiness for brand sustainability commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Yarn Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Staple Fiber, Filament Yarn, BCF Yarn, Mono Filament End User: Textiles, Automotive, Packaging, Carpeting Application: Upholstery, Ropes, Geotextiles, Carpet Tiles Technology: Spun Bonding, Melt Blowing, Weaving, Knitting |
| Companies Covered | Reliance Industries, Indorama Ventures, LyondellBasell Industries, BASF, Lankhorst Yarns, Chemosvit Fibrochem, Filatex India Limited, Toray Industries, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Yarn Market Strategic Shifts
Filament production technology is bifurcating between commodity scale and specialty precision, with regulatory pressure on carbon intensity and microplastic shedding forcing simultaneous investment in process efficiency and material innovation. This dual-track evolution is reshaping capital allocation and partnership strategies across the value chain.
Multicomponent bicomponent spinning technology is converging with sheath-core configurations that embed recycled content or functional additives within virgin polymer matrices. Construction geotextile contractors and automotive tier-1 suppliers are specifying these hybrid filaments for load-bearing applications requiring controlled degradation or antimicrobial surface properties. The structural consequence is converging with circular economy certification requirements, compressing the timeline for mechanical recycling integration into mainstream filament supply.
ECHA's REACH microplastic restriction dossier is mandating synthetic fiber shedding testing protocols that reshape staple fiber finishing chemistry. Industrial laundries and home textile brands are reformulating procurement specifications around biodegradable spin finishes and reduced-fleece construction. Filtration and hygiene nonwoven segments are responding with denser web bonding and surface encapsulation investments to maintain regulatory access.
Specification-grade procurement is consolidating around certified sustainability credentials that displace transactional spot purchasing. European carpet manufacturers and North American geotechnical engineering firms are embedding OEKO-TEX and Global Recycled Standard requirements into multi-year supply agreements. India and Vietnam represent the geographies where this contract structure is penetrating fastest, as export-oriented producers seek qualification locks against Chinese resin cost volatility.
Polypropylene Yarn Market Segmentation
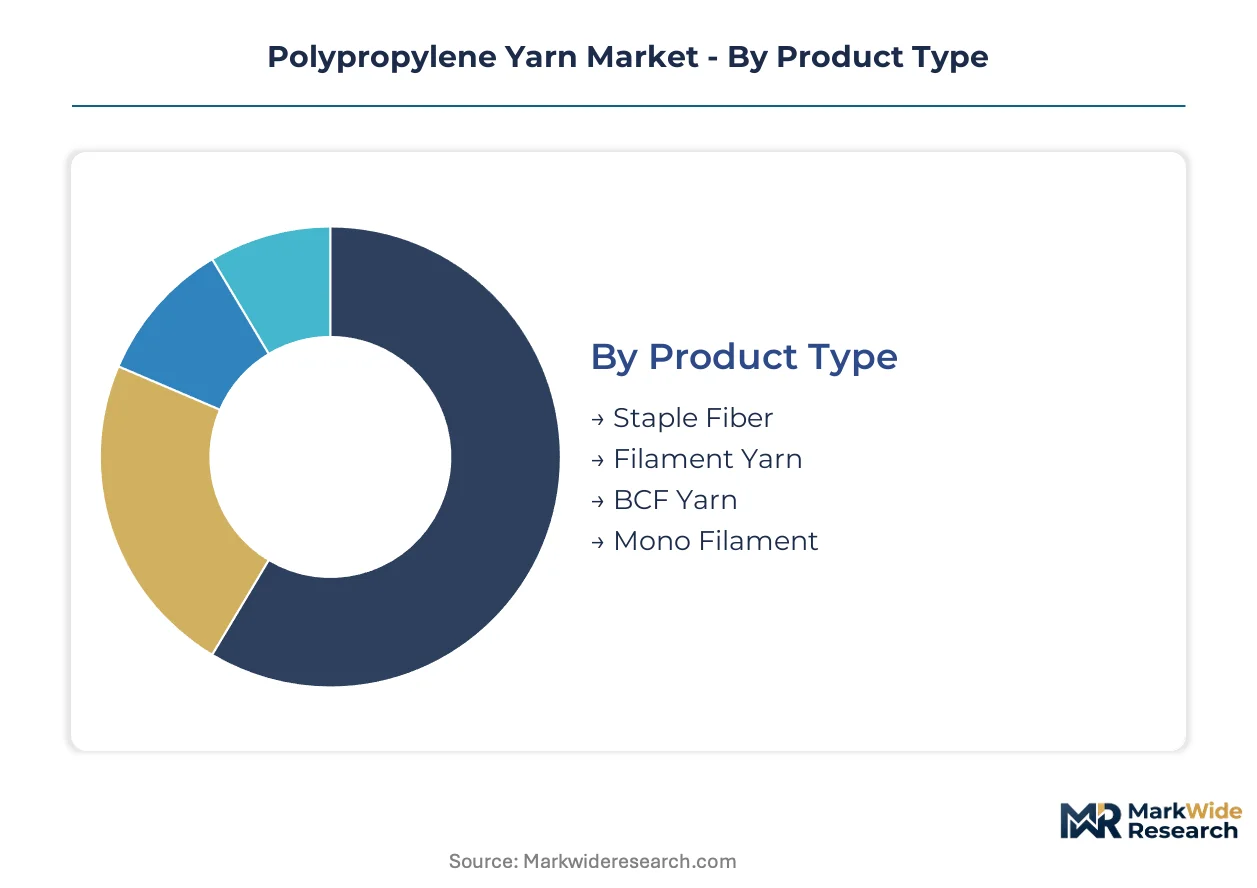
Polypropylene yarn segmentation reflects divergent technical requirements across construction reinforcement, filtration media, and soft surface applications. Specification-grade buyers prioritize filament consistency and certification breadth over unit cost, fragmenting procurement patterns across product categories.
Product Type:
Application performance demands dictate material form selection, with load-bearing specifications favoring continuous filament structures while disposability requirements drive staple fiber adoption.
- Staple Fiber:Short-cut filaments (38-102mm) processed through carding and needle-punching for nonwoven hygiene and geotextile applications. Demand concentrates in India's export-oriented diaper and sanitary product manufacturing, constrained by ECHA microplastic shedding limits under REACH that are reformulating spin finish chemistry.
- Filament Yarn:Continuous extruded strands with controlled denier for woven industrial fabrics and flexible intermediate bulk containers. European carpet weavers and Vietnamese technical textile producers are specifying high-tenacity grades for automated tufting lines, with OEKO-TEX certification becoming a non-negotiable entry requirement.
- BCF Yarn:Bulked continuous filament with three-dimensional crimp for cut-pile and loop-pile carpeting.
- Mono Filament:Single-strand extrusions for filtration mesh, agricultural shade nets, and synthetic grass backing.
Volume sits with Staple Fiber; growth tilts toward BCF Yarn.
End User:
Customer procurement scale and specification complexity create distinct service requirements across value chain tiers.
- Textiles:Woven and knitted apparel fabrics, home furnishings, and industrial narrow fabrics requiring dyeable and UV-stabilized grades. India's PLI scheme for technical textiles is scaling domestic melt-spinning capacity to serve export markets, with BIS certification tightening import quality thresholds for foreign suppliers.
- Automotive:Interior trim, seat fabrics, and underbody splash shields demanding low-VOC emissions and flame-retardant properties. Tier-1 suppliers in Germany and the US are specifying recycled-content filaments to meet OEM sustainability scorecards, with mass balance accounting complicating feedstock verification.
- Packaging:Flexible intermediate bulk containers, woven sacks, and strapping tapes.
- Carpeting:Residential, commercial, and automotive floor coverings.
Procurement scale clusters with Carpeting; specification complexity peaks in Automotive.
Application:
Functional performance requirements and regulatory exposure determine formulation and finishing investments.
- Geotextiles:Soil stabilization, drainage, and erosion control fabrics for infrastructure megaprojects. Demand is compressing into high-volume contracts favoring producers with backward integration into resin supply, particularly across India's Delhi-Mumbai Industrial Corridor and Vietnam's North-South Expressway segments.
- Carpet Tiles:Modular floor coverings for commercial office and hospitality installations. Digital textile printing compatibility is driving surface modification R&D for ink adhesion, with European and North American specification-grade procurement consolidating around multi-year supply agreements.
- Upholstery:Furniture and vehicle seating fabrics.
- Ropes:Marine, industrial, and agricultural cordage.
Contract value concentrates in Geotextiles; margin expansion favors Carpetet Tiles.
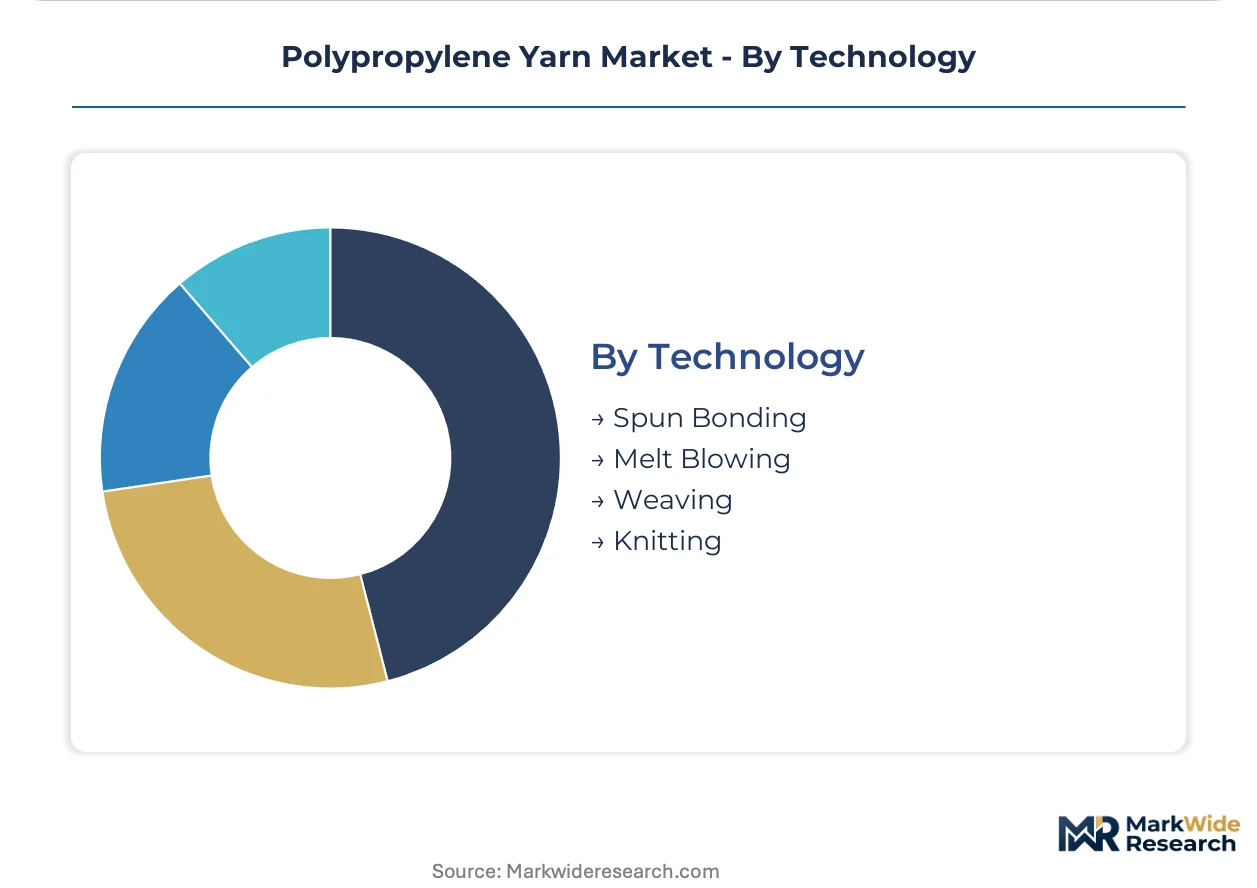
Technology:
Process selection governs capital intensity, output specifications, and regulatory compliance pathways.
- Spun Bonding:Continuous filament extrusion and web bonding for geotextile and agricultural fabric production. Scale leadership persists in this segment, though EPA emissions constraints on US-based operations and EU Green Deal carbon intensity benchmarks are forcing efficiency investments at legacy European lines.
- Melt Blowing:Fine-denier microfiber production for filtration media and absorbent hygiene products. Healthcare and industrial filtration specifications are expanding capacity utilization at integrated SMS (spunbond-meltblown-spunbond) lines, with process refinement enabling sub-micron fiber diameters for HVAC and liquid filtration markets.
- Weaving:Interlacing warp and weft yarns for industrial and decorative fabrics.
- Knitting:Loop formation for stretchable technical textiles and apparel.
Installed capacity favors Spun Bonding; capacity expansion tilts toward Melt Blowing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates polypropylene yarn demand through its scaling technical textile manufacturing base, while regulatory divergence across major economies fragments supply chain strategies. Geotextile infrastructure deployment and circular economy mandates are redrawing competitive maps by region.
India
Domestic textile manufacturing expansion under the PLI scheme is absorbing record volumes of BCF and staple fiber for export-oriented carpet and hygiene nonwoven production. BIS certification mandates are tightening import quality thresholds, favoring local melt-spinning investments. The Delhi-Mumbai Industrial Corridor anchors geotextile specification-grade contracting for soil stabilization and drainage applications.
China
Construction reinforcement and agricultural mesh applications are pivoting toward recycled polypropylene filament adoption under MIIT energy-intensity benchmarks. Dual carbon goals are compressing virgin resin economics for non-integrated spinners. The Yangtze River Delta retains scale leadership in spunbond-meltblown-spunbond integrated lines serving filtration media export markets.
Germany
Automotive tier-1 suppliers are specifying recycled-content filaments to meet OEM sustainability scorecards, with mass balance accounting complicating feedstock verification. ECHA's REACH microplastic restrictions are reshaping staple fiber formulation chemistry for home textile applications. The North Rhine-Westphalia cluster concentrates carpet weaving and technical textile R&D investment.
United States
EPA emissions constraints on melt spinning operations are forcing efficiency investments at legacy production lines serving geotextile and industrial fabric markets. Flexible intermediate bulk container and woven sack demand from agricultural and chemical sectors sustains volume consumption. The Southeast manufacturing corridor is attracting texturing and finishing capacity to serve Latin American export markets.
Vietnam
Underpenetrated geotextile and industrial fabric capacity is drawing first-mover melt-spinning and texturing investments for regional supply chain positioning. North-South Expressway segments are concentrating specification-grade procurement into high-volume contracts. Export-oriented producers are seeking OEKO-TEX qualification locks against Chinese resin cost volatility.
Polypropylene Yarn Market Competitive Environment
Asian producers anchor the scale-driven tier; European specialists hold certification-intensive segments. The vendor base splits between integrated petrochemical conglomerates with captive resin supply and independent spinners competing on filament consistency and logistics proximity. Three archetypes dominate: backward-integrated resin-to-yield operators, specialty additive formulators, and regional contract manufacturers serving megaproject corridors. Capacity expansion and mechanical recycling infrastructure partnerships constitute the primary competitive moves.
Within the integrated petrochemical tier, Reliance Industries and Indorama Ventures exemplify resin-to-filament control strategies that buffer feedstock volatility. LyondellBasell Industries occupies a position in specialty catalyst and polymer technology licensing. BASF represents the functional additives vector, while SABIC anchors Middle East resin supply concentration. Lankhorst Yarns and Chemosvit Fibrochem sit within the European specialist tier focused on specification-grade industrial applications. Toray Industries exemplifies Japanese precision filament engineering for high-tenacity industrial fabrics. Filatex India Limited represents domestic Indian capacity scaling under PLI incentives.
| Leading Market Players |
|---|
| Reliance Industries |
| Indorama Ventures |
| LyondellBasell Industries |
| BASF |
| Lankhorst Yarns |
| Chemosvit Fibrochem |
| Filatex India Limited |
| Toray Industries |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Melt blowing process refinement for sub-micron filtration media is compressing cost economics at integrated spunbond-meltblown-spunbond lines while concentrating supply leverage among producers with captive resin polymerization. This dual compression is reshaping procurement negotiations as specification-grade buyers trade unit price for filament consistency and certification breadth.
Pricing Analysis
Volume concentrates in staple fiber for hygiene nonwovens; margin pools sit with BCF yarn for specification-grade carpeting. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified grades from commodity spot transactions. Cost compression in standard grades is intensifying because Middle East resin supply concentration transmits propylene volatility directly to non-integrated spinners. Hygiene product manufacturers exhibit highest price sensitivity; automotive tier-1 suppliers show least sensitivity due to sustainability scorecard requirements.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Aramco and SABIC resin dominance for European and Asian yarn producers lacking captive polymerization. Manufacturing concentrates in China, India, and Germany for filament extrusion; Vietnam is emerging as a regional texturing hub. Feedstock draws from naphtha-cracking margins and PDH unit economics across the Middle East and Asia-Pacific. Tariff exposure on resin imports complicates margin predictability for independent spinners. Distribution runs through direct mill relationships for geotextile megaprojects and distributor networks for industrial fabric spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH microplastic restrictions and BIS certification mandates raise capital barriers that force sub-scale spinners toward exit or acquisition.
For Market Incumbents: Cement filament consistency advantages through backward integration into resin supply and melt-spinning scale. Lock in multi-year specification-grade contracts with geotextile contractors across India's Delhi-Mumbai Industrial Corridor. Invest in mechanical recycling infrastructure partnerships to capture certified recycled-content premiums before ECHA circular economy mandates tighten further. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated geotextile and industrial fabric capacity for first-mover regional positioning. Target North-South Expressway segments with OEKO-TEX qualified production to secure qualification locks against Chinese resin cost volatility. Pursue digital textile printing compatibility as a go-to-market angle for custom carpet and soft signage segments. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty additive formulators and regional contract manufacturers serving megaproject corridors. Long-term viability favors integrated resin-to-filament operators with certification breadth across REACH, BIS, and OEKO-TEX tiers. Watch for inflection signals in India's PLI scheme disbursement rates and mechanical recycling infrastructure buildout timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive resin supply buffers Indorama Ventures and Reliance Industries against propylene feedstock volatility from Middle East sources. |
| Mechanical Recycling Infrastructure | Certified recycled-content yarn premiums align with EU Green Deal circular economy mandates for construction and automotive applications. |
| Regional Melt-Spinning Scale-Up | Vietnam's North-South Expressway concentrates specification-grade procurement into high-volume contracts favoring local production. |
| Certification Investment | Simultaneous BIS, REACH, and OEKO-TEX compliance extends qualification cycles and ties up technical documentation resources for Indian exports. |
| Surface Modification R&D | BCF yarn ink adhesion properties open specification wins in European carpet tile and soft signage segments requiring digital printing compatibility. |
Study Parameters
Multi-period observation of melt spinning capacity utilization, resin import volumes, and certification compliance timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at automotive tier-1 suppliers, technical R&D directors at specialty additive formulators, and distribution channel partners serving geotextile contractors. Secondary validation drew from customs and trade data, chemical industry association reports, SEC 10-K filings from listed petrochemical conglomerates, and regulatory dossiers from ECHA and BIS. Bottom-up filament production estimates triangulated against top-down resin consumption forecasts.
Segment-weighting across product type, end user, application, and technology dimensions shaped the analytical framework across the projection horizon. Staple fiber, filament yarn, BCF yarn, and mono filament categories were modeled with distinct growth trajectories reflecting ECHA microplastic restrictions and India PLI scheme incentives. CAGRs were derived from regression analysis against resin cost volatility indices and infrastructure investment pipelines. Feedstock price elasticity and spinneret technology diffusion curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; spun bonding and melt blowing carry tighter precision than weaving and knitting due to consolidated production reporting. Forecasts reflect assumptions around regulatory implementation timelines and circular economy infrastructure deployment rates. Specific risk factors include propylene feedstock volatility from PDH unit economics, REACH microplastic restriction enforcement intensity, and BIS certification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market