
 Nonwoven Fabric Production Line Market | 2026-2036
Nonwoven Fabric Production Line Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Fabric Production Line Market Insights
Software-defined process control is recalibrating how nonwoven fabric production lines are sold and monetized. Freudenberg Group leverages embedded sensor networks to offer predictive maintenance contracts that extend machine uptime guarantees. Toray Industries anchors its Asian installed base through remote diagnostics subscriptions tied to spunbond throughput optimization. Berry Global Inc. competes on modular line configurations that let hygiene product manufacturers scale meltblown capacity without full rebuilds.
A nonwoven fabric production line is an integrated manufacturing system that transforms synthetic or natural staple fibers into bonded sheet structures through thermal, mechanical, or chemical processes without weaving or knitting; typical specifications include web widths of 2.4 to 6.0 meters and throughput rates from 500 to 5,000 kilograms per hour depending on bonding technology. Spunbond lines dominate installed capacity worldwide due to their efficiency in producing continuous filament webs for hygiene and agricultural applications. Meltblown lines command premium pricing because of their specialized role in filtration media and medical barrier fabrics where fiber diameters below 3 microns are required. Hydroentanglement lines are gaining share in personal care and wipes as brands eliminate chemical binders to meet clean-label sourcing standards.
REACH chemical restrictions and the EU Green Deal carbon border adjustments are forcing European line operators to eliminate solvent-based bonding chemistry and document energy intensity per square meter of output. The FDA regulates medical-grade nonwoven barriers through 21 CFR biocompatibility testing, while China's GB standards mandate filtration efficiency reporting for respirator media produced on domestic meltblown equipment. Stakeholders must weigh capital allocation between retrofitting existing thermal bonding lines for lower emissions and commissioning greenfield hydroentanglement capacity for premium personal care contracts.
Market Dynamics
Water-based hydroentanglement bonding is electrifying capital allocation across European nonwoven production, as REACH solvent restrictions and EU Green Deal carbon border adjustments force line operators to abandon thermal and chemical bonding architectures. This technology pivot reconfigures supplier relationships, energy contracts, and facility footprints simultaneously.
Growth Catalysts
- EU Green Deal carbon border mechanisms:German and Italian hygiene manufacturers accelerate meltblown capacity additions to preempt 2026-2030 carbon tariffs on imported barrier fabrics.
- Spunbond efficiency gains:Continuous filament web production achieves 40% lower energy intensity than staple fiber alternatives, pulling investment toward agricultural and geotextile applications.
- Medical barrier demand:FDA 21 CFR biocompatibility requirements for surgical drapes and gowns sustain premium pricing for validated meltblown lines in North American hospital supply chains.
Market Restraints
- Polypropylene price volatility:Spunbond and meltblown lines remain captive to propylene feedstock swings, compressing margin visibility for 18-24 month equipment procurement cycles.
- German engineering concentration:Stuttgart and Düsseldorf equipment clusters create single-source dependency for precision meltblown die heads and air knife systems.
- Hydroentanglement water intensity:High-pressure needle bonding consumes 15-20 cubic meters of water per ton of output, restricting deployment in drought-prone manufacturing zones.
Strategic Opportunities
- India PLI scheme for technical textiles:Domestic nonwoven investment incentives target filtration and hygiene applications, opening greenfield opportunities for European line exporters.
- Bio-based fiber integration:PLA and lyocell staple compatibility with existing hydroentanglement infrastructure enables clean-label personal care contracts without full line replacement.
- Remote diagnostics convergence:Embedded sensor networks and cloud-based throughput optimization create recurring revenue streams independent of hardware sales cycles.
Industry Challenges
- Multi-physics simulation expertise:Meltblown die design requires computational fluid dynamics and polymer rheology skills scarce in traditional textile engineering labor pools.
- Legacy thermal bonding retrofit complexity:Converting solvent-based lines to water-based hydroentanglement demands simultaneous HVAC, wastewater, and electrical infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Fabric Production Line Market |
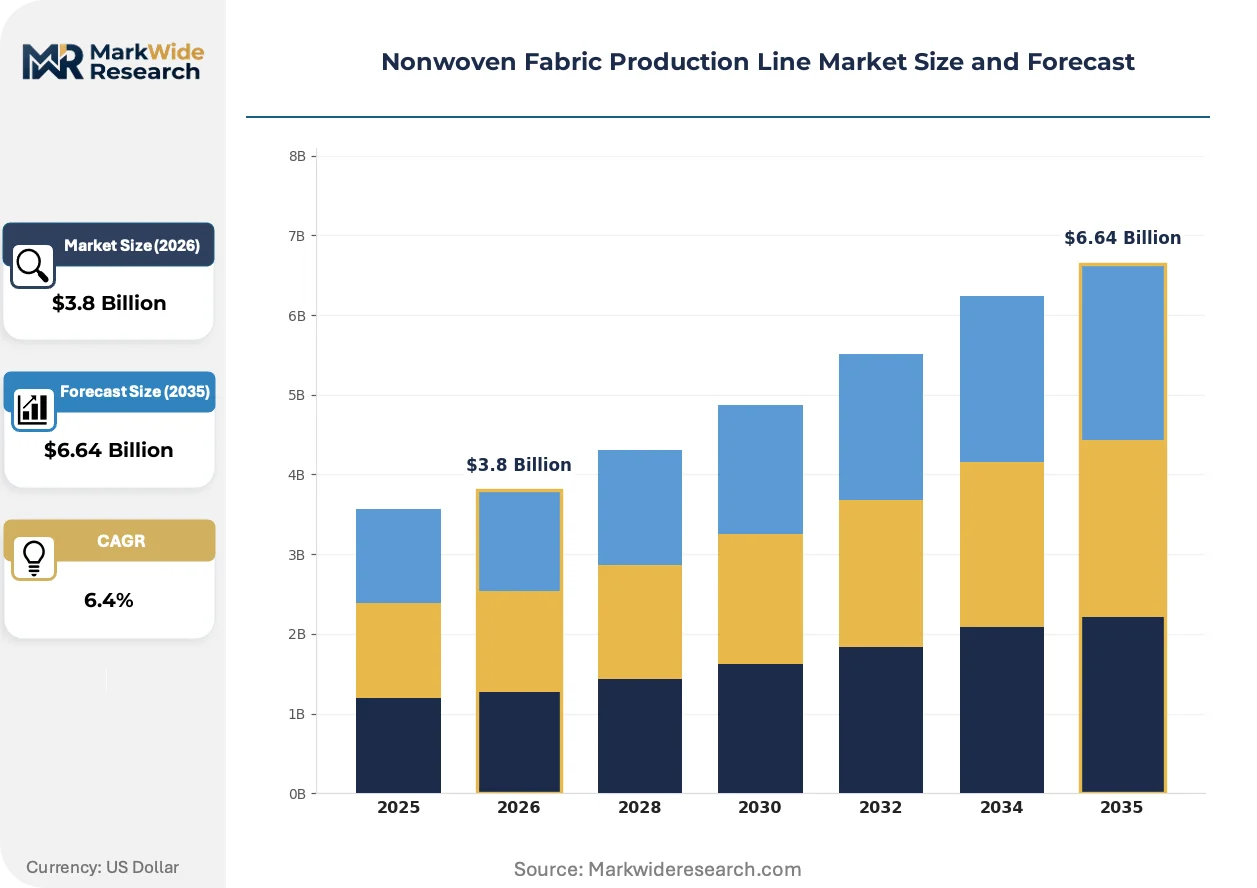
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond Lines, Meltblown Lines, Needle Punch Lines, Hydroentanglement Lines, Thermal Bonding Lines Technology: Airlaid Technology, Wet Laid Technology, Spunlace Technology, Chemical Bonding Technology, Dry Laid Technology Application: Personal Care, Filtration, Automotive Interiors, Agriculture Covers, Protective Apparel End User Industry: Hygiene Product Manufacturers, Filtration Equipment Makers, Automotive Component Suppliers, Textile Producers, Medical Supplies Companies |
| Companies Covered | Berry Global Inc., Freudenberg Group, DuPont, Kimberly-Clark Corporation, Fitesa, Ahlstrom, Johns Manville, Toray Industries, Magnera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Fabric Production Line Market Trends and Innovations
Software-defined process control and predictive maintenance architectures are restructuring how production line value is captured and monetized. Equipment suppliers now compete on uptime guarantees and throughput optimization rather than capital equipment specifications alone.
Electrified needle bonding is electrifying water-based hydroentanglement adoption across European personal care manufacturing. This high-pressure mechanical bonding eliminates chemical binders from wet wipe and cosmetic pad production. Unilever and Procter & Gamble contract manufacturers in the Netherlands and Belgium specify electrified needle lines for 2025-2027 capacity additions. The technology is electrifying regional equipment demand while compressing thermal bonding line residual values in secondary markets.
REACH Annex XVII solvent restrictions are eliminating toluene and xylene-based thermal bonding chemistry from EU nonwoven production. ECHA enforcement timelines require full phase-out by 2030 for hygiene applications. German and French line operators face 18-24 month certification windows for alternative bonding validation, accelerating depreciation of legacy thermal assets and redirecting capex toward hydroentanglement greenfields.
Outcome-based service contracting is displacing traditional equipment sales in Asian spunbond markets. Toray Industries and regional competitors now bundle remote diagnostics, spare parts logistics, and throughput guarantees into multi-year subscriptions. Hygiene manufacturers in Indonesia and Vietnam prefer operating expense treatment over capital intensity, particularly for 2.4-3.2 meter web width lines serving regional diaper and feminine care demand. This procurement shift concentrates vendor relationships and extends equipment lifecycle management responsibilities upstream to line builders.
Nonwoven Fabric Production Line Market Segmentation
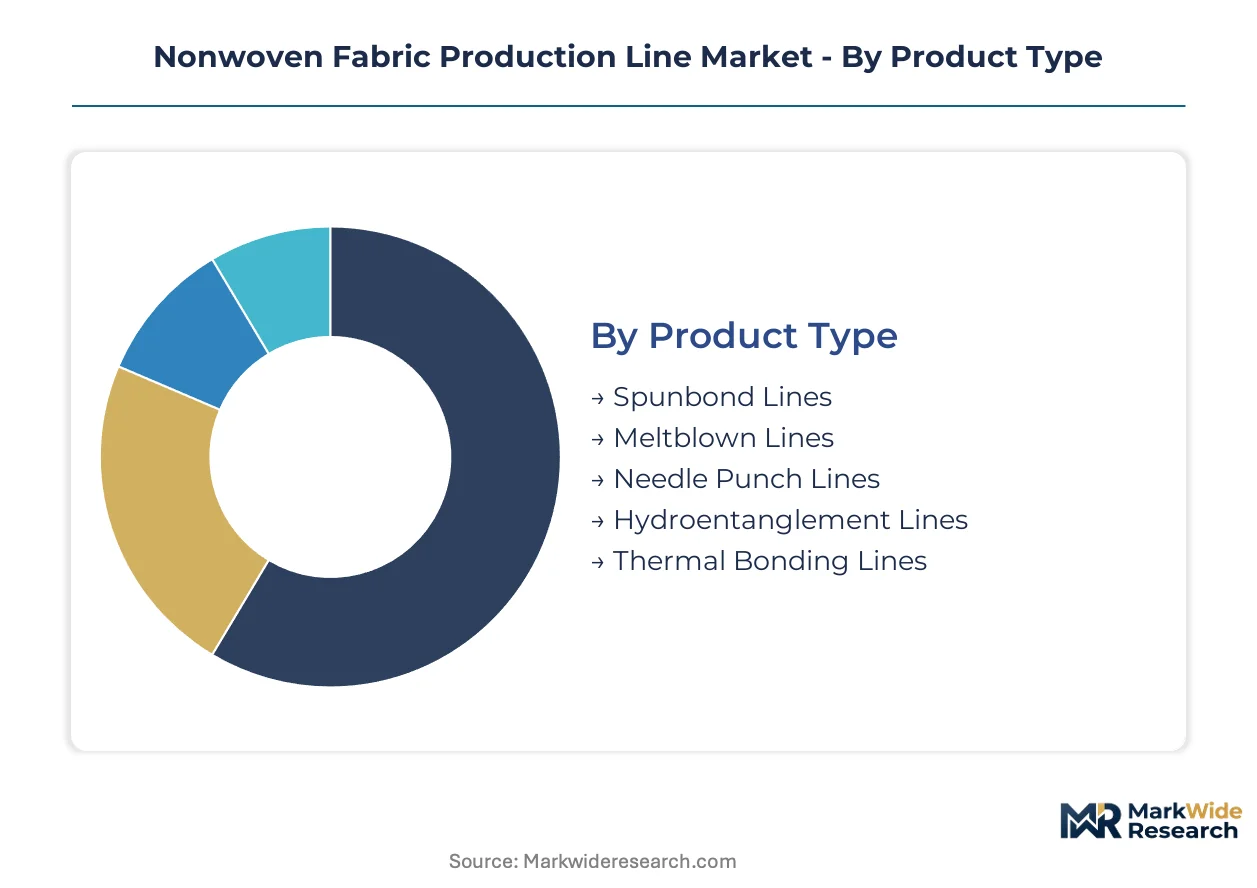
Nonwoven fabric production lines fragment across bonding physics, fiber preparation methods, and end-use certification requirements. Each segmentation axis carries distinct capital intensity, regulatory exposure, and aftermarket service attach rates that reshape vendor-customer contracting terms.
Product Type:
Buyers in this category separate by filtration precision requirements and energy cost tolerance rather than web width alone.
- Spunbond Lines:Continuous filament extrusion systems bond polypropylene webs through calendar thermal compression. Hygiene product manufacturers in Germany and Italy favor these configurations for diaper topsheet production where throughput economics dominate specification sheets.
- Meltblown Lines:Microfiber die systems extrude filaments below 3 microns for medical barrier and respirator media. FDA 21 CFR biocompatibility validation requirements sustain premium pricing for lines serving North American hospital supply chains.
- Needle Punch Lines:Mechanical felting equipment interlocks staple fibers for geotextile and automotive carpet applications.
- Hydroentanglement Lines:High-pressure water jet bonding eliminates chemical binders for wet wipe and cosmetic pad manufacturing.
- Thermal Bonding Lines:Hot air or calendar systems fuse thermoplastic webs for agricultural cover and furniture backing.
Volume sits with Spunbond Lines; growth tilts toward Hydroentanglement Lines.
Technology:
Technology selection tracks raw material flexibility and wastewater treatment infrastructure availability.
- Spunlace Technology:Water jet entanglement produces soft, drapable fabrics for personal care applications. Dutch and Belgian contract manufacturers specify these systems for Unilever and Procter & Gamble supply contracts eliminating chemical binders.
- Dry Laid Technology:Carded staple fiber webs form through mechanical layering without water or solvent bonding. Agricultural cover producers in drought-prone zones favor this approach for its minimal utility demands.
- Airlaid Technology:Fluff pulp and superabsorbent polymer distribution creates absorbent cores for hygiene products.
- Wet Laid Technology:Suspended fiber slurry deposition mimics papermaking for filtration media and wipes.
- Chemical Bonding Technology:Latex or solvent binders cure through thermal ovens for stiffened industrial fabrics.
Spunlace Technology captures the steepest expansion trajectory as REACH Annex XVII solvent restrictions accelerate phase-out of chemical alternatives.
Application:
Application segmentation reflects divergent certification burdens and replacement cycle frequencies.
- Personal Care:Wet wipes, cosmetic pads, and diaper components demand soft hand-feel and clean-label sourcing. ECHA enforcement timelines for solvent elimination redirect European capacity toward hydroentanglement-compatible lines.
- Filtration:HVAC, automotive, and respirator media require precise fiber diameter control and electrostatic charging compatibility. China's GB standards mandate efficiency reporting for domestic meltblown equipment.
- Automotive Interiors:Headliner, trunk liner, and insulation applications prioritize moldability and acoustic dampening.
- Agriculture Covers:Crop protection and greenhouse films balance UV stability with biodegradability for seasonal use.
- Protective Apparel:Surgical gowns and industrial coveralls integrate meltblown barriers with spunbond structural layers.
Filtration commands the highest line pricing; Personal Care drives replacement demand fastest.
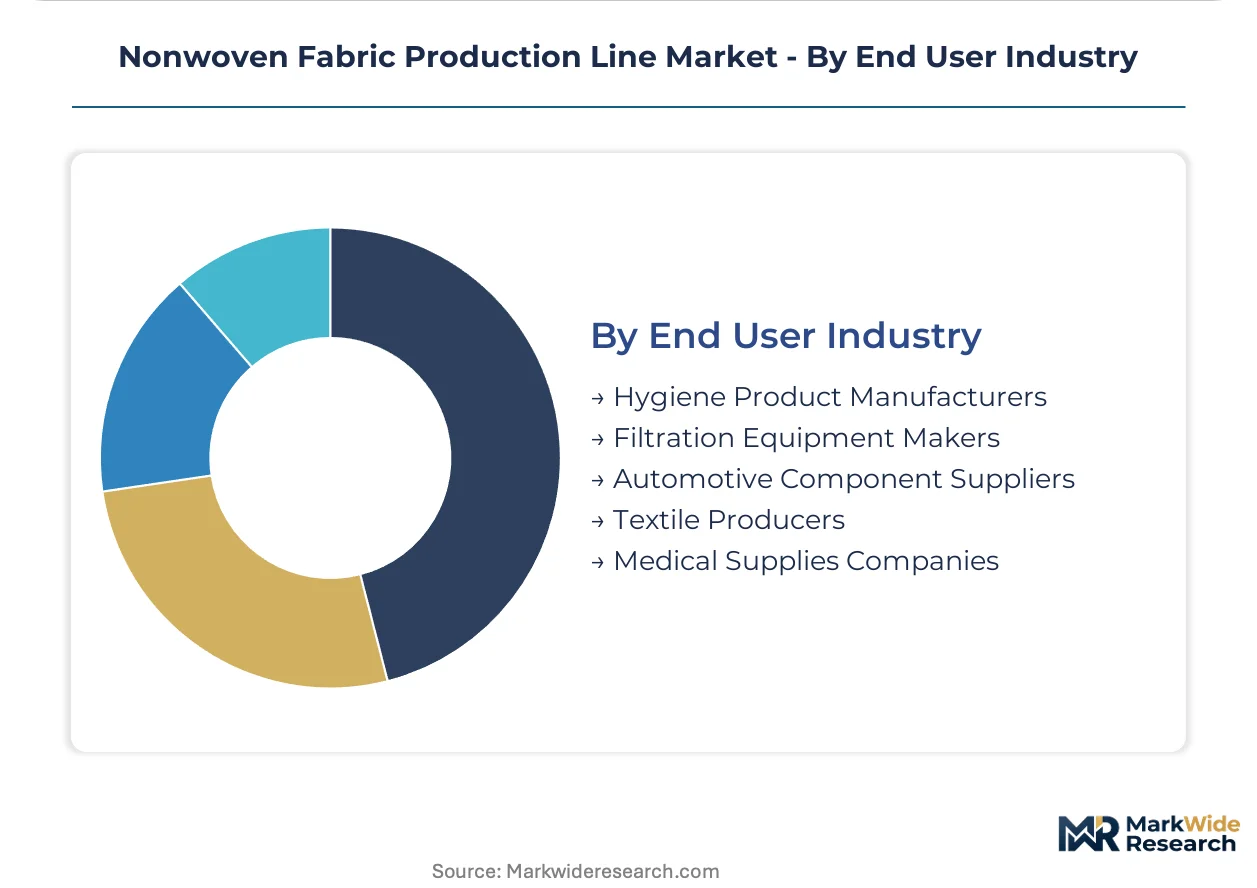
End User Industry:
End user categories separate by in-house technical expertise and preferred procurement mechanics.
- Hygiene Product Manufacturers:Diaper and feminine care producers favor outcome-based service contracts over capital purchases. Indonesian and Vietnamese operators subscribe to remote diagnostics bundles from Toray Industries for 2.4-3.2 meter web width lines.
- Medical Supplies Companies:Surgical drape and gown suppliers require FDA-validated meltblown capacity with documented biocompatibility testing.
- Filtration Equipment Makers:HVAC and industrial filter assemblers specify fiber diameter distributions and electrostatic retention properties.
- Automotive Component Suppliers:Tier-1 interior trim manufacturers prioritize just-in-time web delivery and color matching consistency.
- Textile Producers:Traditional woven converters enter nonwoven through hybrid lines serving industrial wiping and interlining markets.
Hygiene Product Manufacturers dominate installed base; Medical Supplies Companies generate the highest service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in Germany and China while consumption spreads across hygiene manufacturing hubs in Southeast Asia and North America. This geographic split creates trade flows in precision components and finished lines. Regional regulatory divergence on chemical bonding and carbon intensity is accelerating localized capacity buildouts.
United States
FDA 21 CFR biocompatibility requirements sustain premium meltblown line demand for surgical drape and gown production. Hospital supply chain reshoring incentives under the Defense Production Act accelerate domestic barrier fabric capacity additions. North Carolina and South Carolina host expanding nonwoven manufacturing corridors serving medical device clusters.
Germany
EU Green Deal carbon border adjustments and REACH Annex XVII solvent restrictions force wholesale bonding technology transitions. Engineering firms cluster around Stuttgart and Düsseldorf to supply precision meltblown die heads and hydroentanglement systems. German line builders dominate European medical-grade equipment procurement through validated quality protocols.
China
GB standards mandate filtration efficiency reporting for respirator media produced on domestic meltblown equipment. Yangtze River Delta and Pearl River Delta manufacturing zones integrate spunbond capacity for diaper and feminine care export production. Local equipment makers compete on cost while importing precision air knife systems from European specialists.
India
PLI scheme incentives for technical textiles target filtration and hygiene applications with 15-20% capex subsidies. Gujarat and Maharashtra states attract greenfield nonwoven investments from hygiene contract manufacturers serving Middle East and African markets. Domestic line procurement favors 2.4-3.6 meter web width configurations for regional scale economics.
Indonesia
Toray Industries anchors Southeast Asian spunbond demand through outcome-based service contracts with diaper manufacturers. Jababeka and MM2100 industrial zones outside Jakarta concentrate wet wipe and personal care production requiring hydroentanglement-compatible lines. Indonesian operators prefer operating expense treatment over capital intensity for capacity expansion.
Nonwoven Fabric Production Line Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology licensing and equipment fabrication models. The vendor base separates into three strategic archetypes: integrated polymer-to-line conglomerates, precision component specialists, and regional system integrators. Consolidation pressures concentrate in German engineering clusters where multi-physics simulation expertise commands scarcity premiums. Dominant competitive moves include technology licensing partnerships for emerging market penetration and backward integration into polymer compounding to secure feedstock margins.
Within the integrated conglomerate tier, Berry Global Inc. and Toray Industries occupy positions spanning polymer supply through finished equipment validation. Freudenberg Group exemplifies the precision component archetype with sensor-embedded line architectures. These three anchors demonstrate how vendor strategies diverge between hardware sales cycles and recurring service revenue models across hygiene and medical barrier end markets.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Freudenberg Group |
| DuPont |
| Kimberly-Clark Corporation |
| Fitesa |
| Ahlstrom |
| Johns Manville |
| Toray Industries |
| Magnera |
| Others |
Pricing and Supply Chain Analysis
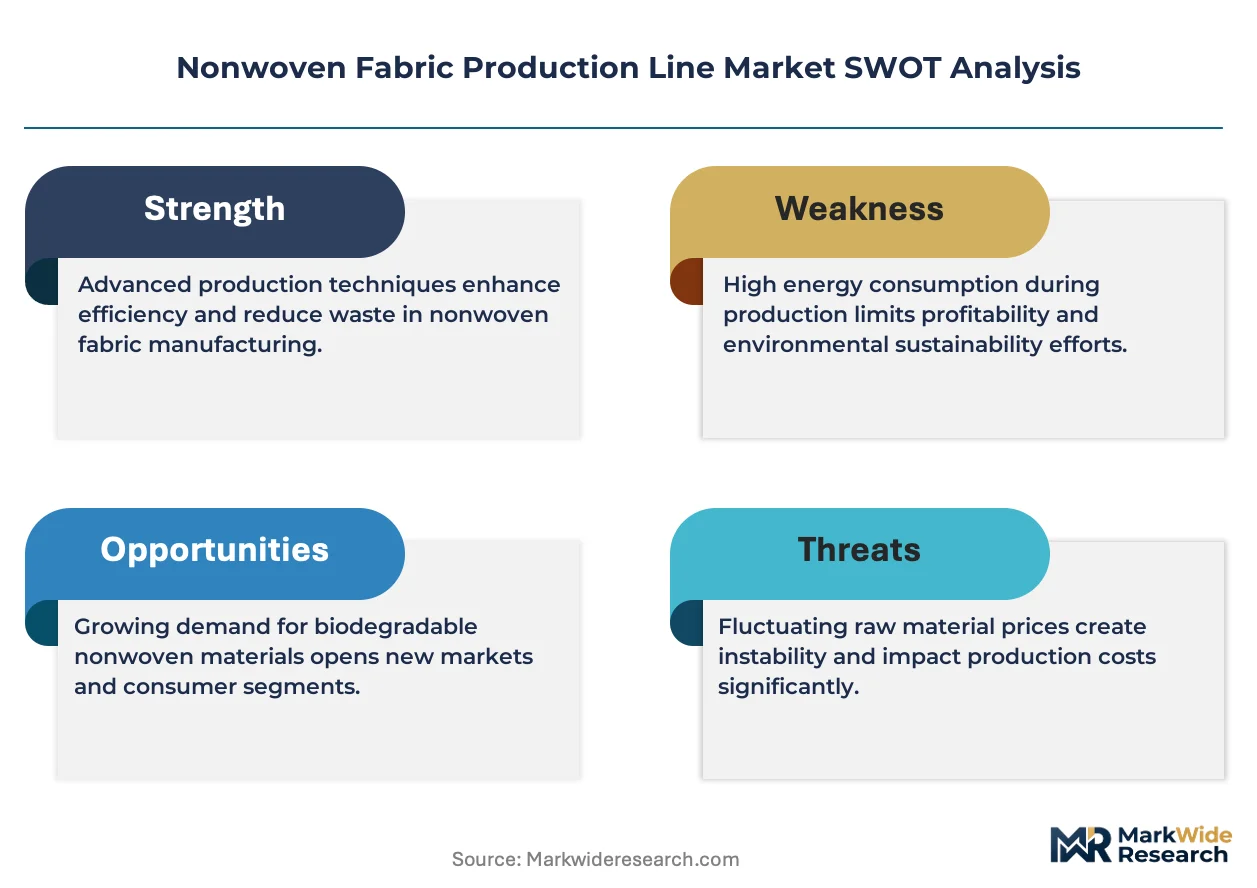
Water-based hydroentanglement bonding is simultaneously elevating capital costs and concentrating supply relationships among German engineering clusters. This technology pivot forces hygiene manufacturers to absorb premium line pricing while accepting longer procurement cycles from Stuttgart and Düsseldorf precision die specialists.
Pricing Analysis
Margin tightening in medical-grade meltblown lines reflects FDA 21 CFR biocompatibility validation requirements that sustain three-tier pricing stratification across validated, certified, and standard equipment tiers. Price differentiation hinges on certification grade and after-sales service bundling, with hygiene product manufacturers exhibiting highest price sensitivity compared to hospital supply chains. Cost-down pressure on standard thermal bonding lines accelerates because REACH Annex XVII solvent restrictions are compressing residual values in secondary markets.
Supply Chain Analysis
FDA and REACH certification gating concentrates precision component supply in Germany, China, and Japan for meltblown die heads, air knife systems, and sensor-embedded control architectures. Raw material dependencies draw from polypropylene resin, high-pressure pump assemblies, and precision needle boards. Single-source vulnerability around German engineering clusters for multi-physics simulation expertise creates structural exposure. Distribution runs through direct OEM relationships for large-format lines and regional system integrators for modular configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of computational fluid dynamics and polymer rheology expertise props pricing for validated meltblown capacity, creating supply-constrained conditions favoring incumbents with captive engineering talent.
For Market Incumbents: To counter emerging Asian equipment makers competing on cost, deepen backward integration into polymer compounding to secure feedstock margins and accelerate certification investment for dual REACH-FDA compliance to maintain premium positioning in medical barrier supply chains.
For New Entrants and Emerging Players: Remote diagnostics platforms offer the most penetrable entry vector, targeting Indonesian and Vietnamese hygiene manufacturers seeking operating-expense treatment over capital intensity for 2.4-3.2 meter web width spunbond capacity expansions.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision component specialists with embedded sensor networks and predictive maintenance attach rates, with long-term viability hinging on software-defined service revenue transition; watch for inflection when European carbon border adjustments trigger accelerated thermal bonding line replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive polypropylene supply secures margin visibility against propylene feedstock volatility for German line builders. |
| REACH-FDA Dual Certification Investment | Simultaneous ECHA and FDA validation opens premium medical barrier contracts with North American hospital supply chains. |
| Remote Diagnostics Platform Launch | Cloud-based throughput optimization creates recurring revenue independent of hardware sales cycles for Asian hygiene markets. |
| Hydroentanglement Greenfield Capacity | Water-based bonding lines capture Unilever and Procter & Gamble contract manufacturing demand in Netherlands and Belgium. |
| Multi-Physics Simulation Talent Acquisition | Computational fluid dynamics expertise scarcity commands premium pricing for meltblown die design validation services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with line engineering directors, hygiene product procurement leads, and aftermarket service heads at German equipment clusters combined with ECHA enforcement timelines, FDA 510(k) databases, and spunbond capacity utilization reports. Bottom-up equipment shipment tallies and top-down end-use demand estimates underwent triangulation validation.
Segment-level modeling applied bonding technology, web width configuration, and end-use certification tier as primary dimensions across the projection horizon. CAGRs derived from equipment order backlogs, retrofit cycle frequencies, and greenfield investment announcements tracked through national technical textile incentive disclosures. Energy intensity benchmarks and wastewater treatment capacity constraints informed regional adoption curve assumptions.
The model holds under sustained REACH enforcement timelines and carbon border adjustment implementation; deviation in polypropylene price volatility or drought-driven hydroentanglement deployment restrictions would shift capacity addition trajectories. A model refresh is warranted upon material change in EU Green Deal carbon tariff schedules or FDA biocompatibility testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Airlaid Textile Market