
 Europe Cotton Market | 2026-2036
Europe Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cotton Market Foresight
Precision agriculture and blockchain traceability is tilting procurement toward digitally verified supply chains. ECOM Agroindustrial Corp Ltd. leverages its integrated farm-to-gin networks across Mediterranean growing zones. Louis Dreyfus Company anchors European merchandising through port terminals in Greece and Italy. Bayer AG differentiates via biological seed treatments that reduce synthetic pesticide dependence in contracted acreage.
Europe cotton comprises Gossypium hirsutum and Gossypium barbadense cultivars with staple lengths ranging from 25mm to 35mm, ginned and baled for spinning into yarn or direct use in nonwoven medical applications. Organic cotton commands premium positioning as EU textile brands face mandatory due diligence under the Corporate Sustainability Due Diligence Directive. Specialty grade cotton occupies narrow but high-margin niches in luxury apparel, while conventional cotton sustains volume throughput for mass-market home furnishing supply chains.
REACH governs chemical inputs in fiber processing, while the EU Green Deal's Farm to Fork Strategy restricts pesticide residues on imported lint. ECHA maintains the restricted substances database that determines market access for treated cotton goods. Stakeholders must weigh certification costs against the narrowing window for conventional product lines as Ecodesign rules harden.
Market Dynamics
EU Green Deal traceability mandates are compressing conventional cotton margins while redirecting procurement toward digitally verified supply chains. The Ecodesign for Sustainable Products Regulation tightens documentation requirements across every tier of textile manufacturing.
Growth Catalysts
- Corporate Sustainability Due Diligence Directive:Mandatory due diligence obligations push EU textile brands toward certified organic fiber, expanding premium-grade acreage under contract.
- Precision agriculture adoption:Sensor-based irrigation and variable-rate fertilization boost lint yield consistency across Mediterranean growing zones, reducing quality variance for ginners.
- Barcelona and Valencia clusters:Spain's concentrated textile manufacturing base generates localized demand pull for regional cotton sourcing, shortening logistics loops.
Market Restraints
- REACH chemical restrictions:ECHA's restricted substances database blocks market access for conventionally processed lint, raising compliance costs for non-certified suppliers.
- Input cost volatility:Synthetic fertilizer and energy price swings squeeze margins on conventional cultivation, particularly for smallholder contract farmers.
- Substitution threat from recycled synthetics:rPET fiber advances in home furnishing applications displace volume demand for standard-grade cotton in non-apparel segments.
Strategic Opportunities
- Portugal's underpenetrated organic market:Limited certified acreage in Portuguese Alentejo creates first-mover positioning for integrated farm-to-gin operators establishing traceable supply.
- Blockchain-IoT convergence:Distributed ledger systems paired with field sensors enable real-time provenance verification, unlocking premium positioning for specialty grades.
- EU Farm to Fork Strategy residue limits:Tightening pesticide thresholds on imported lint advantage EU-origin cotton in regional procurement decisions.
Industry Challenges
- Certification timeline compression:Organic transition periods and Ecodesign documentation requirements outpace existing auditor capacity, creating backlog risks for new entrants.
- Legacy gin equipment integration:Retrofitting Mediterranean ginneries for traceability data capture requires capital outlay that fragments processing capacity between compliant and conventional lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cotton Market |
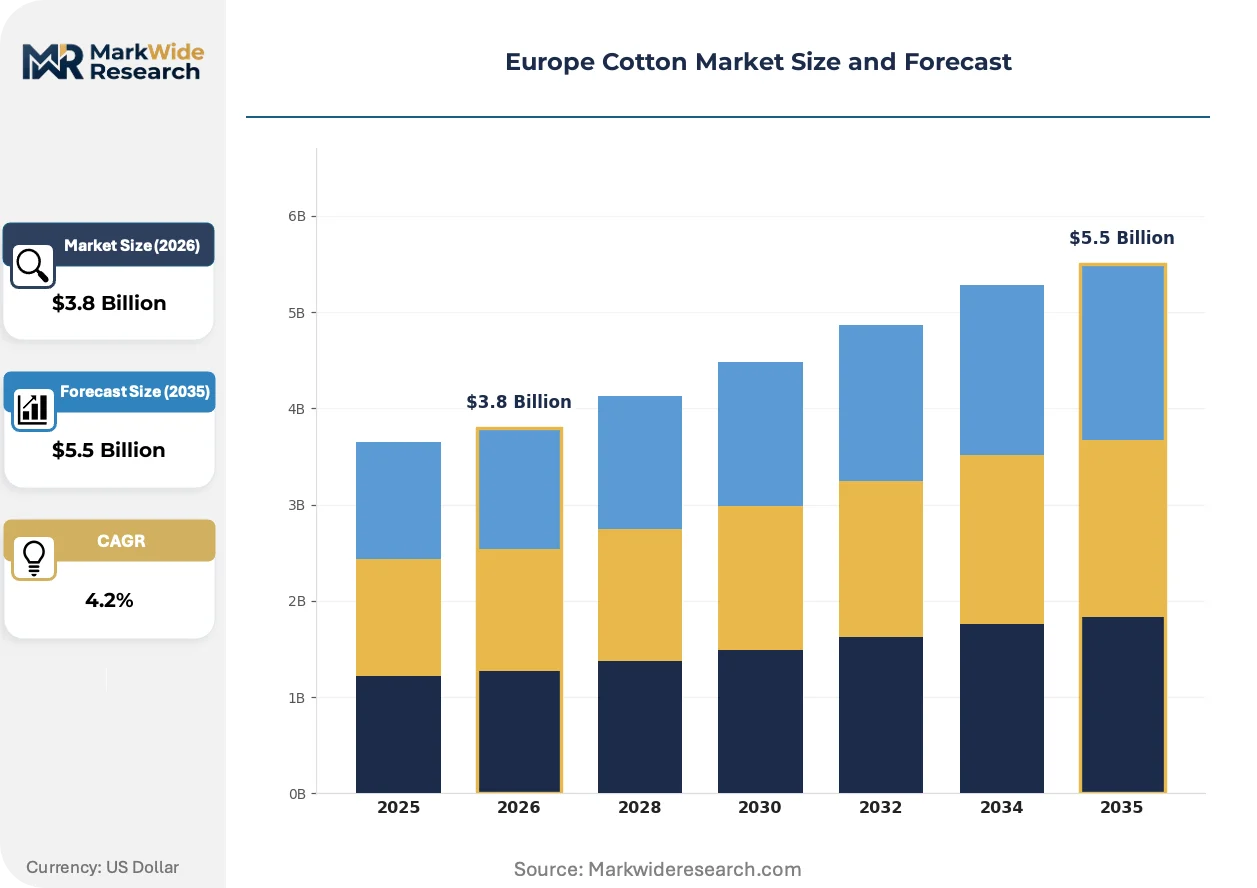
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Conventional Cotton, Cotton Wool, Cotton Yarn End User: Textile Industry, Apparel Manufacturers, Home Furnishing, Medical Sector Quality Grade: Premium Grade, Standard Grade, Low Grade, Specialty Grade Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | ECOM Agroindustrial Corp Ltd., COFCO International, Louis Dreyfus Company, C.A.R.E Srl, Plexus Cotton Ltd., Olam International, Deltex GmbH, Bayer AG, Cargill, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cotton Market Shifts & Advancements
Digital verification infrastructure is displacing paper-based chain-of-custody systems across European cotton procurement. Three convergent developments are compressing the window for conventional supply models.
Blockchain-based provenance tracking is virtualizing the documentation layer between field and spinner. Premium apparel brands in Northern Italy now require cryptographic lot verification as a procurement gate. This compression of trust infrastructure eliminates multi-party audit redundancy, reducing certification overhead for compliant suppliers while excluding non-digitized origin cotton from qualified supplier lists.
REACH enforcement through ECHA's SCIP database is hardening chemical disclosure requirements for processed fiber. Industrial laundries and finishers face mandatory substance registration that propagates upstream to ginners. Specialty medical nonwoven producers respond by segregating processing lines to isolate compliant from conventional lint streams, raising fixed cost thresholds for multi-grade operators.
Spinner procurement committees now weight traceability scores above price in annual contract negotiations. Mass-market home furnishing buyers in Turkey's European-facing export sector consolidate supplier panels to reduce audit burden. This concentration is most visible in Greek port-terminal merchandising, where integrated traders with captive farm networks capture expanding share of qualified volume.
Europe Cotton Market Segmentation
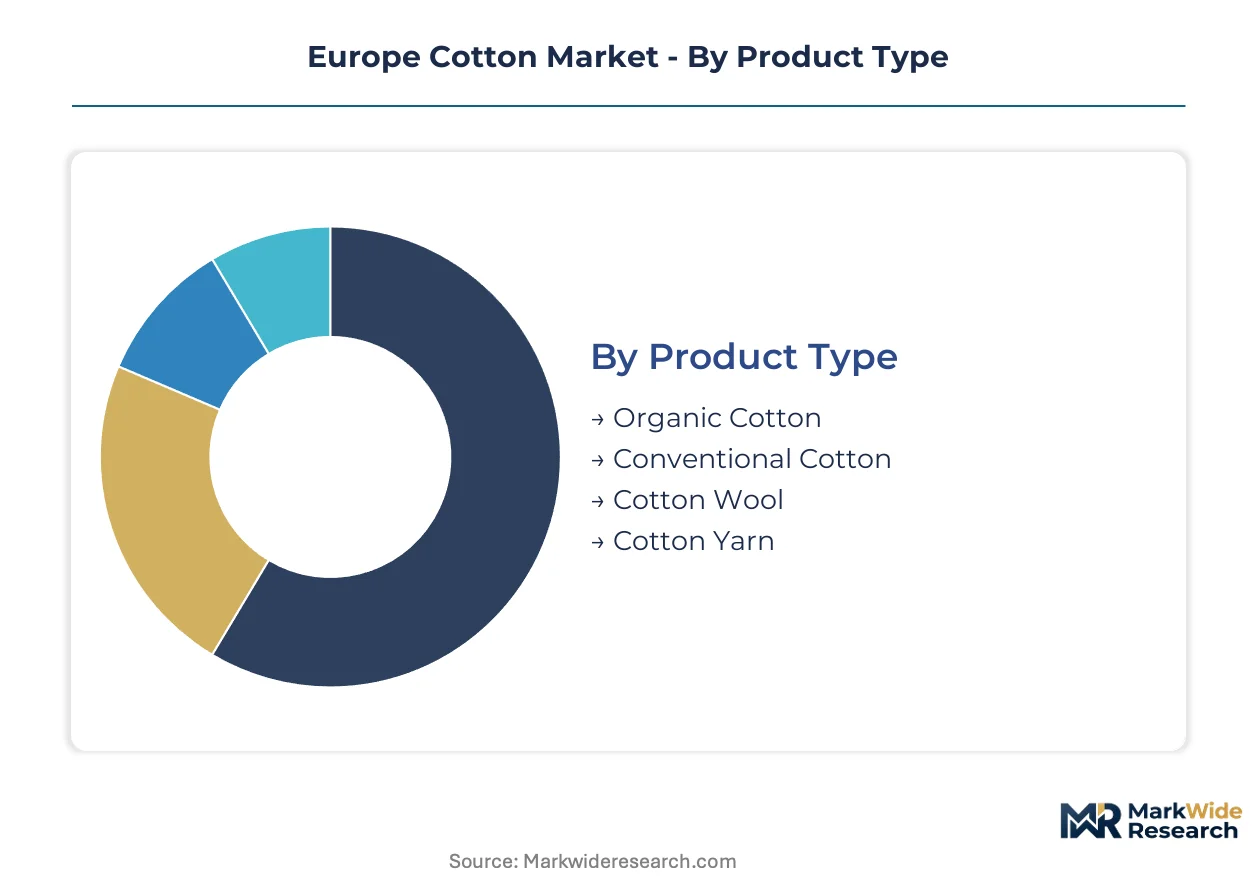
Europe cotton procurement committees now segment supplier panels by certification tier and traceability infrastructure. Segmentation discipline determines qualified supplier status under Ecodesign documentation mandates.
Product Type:
After-sales service intensity varies sharply across product types, with organic cotton requiring ongoing certification audits and chain-of-custody maintenance that conventional grades avoid.
- Organic Cotton:Certified fiber grown without synthetic pesticides or fertilizers, meeting EU Green Deal traceability thresholds. Demand concentrates in Northern Italy's premium apparel sector where Ecodesign compliance is non-negotiable for qualified supplier lists.
- Conventional Cotton:Standard cultivation using synthetic inputs, still dominating volume throughput for mass-market applications. Spain's Barcelona and Valencia textile clusters sustain localized demand despite narrowing margin windows under REACH chemical restrictions.
- Cotton Wool:Raw unprocessed fiber for medical and cosmetic applications, requiring sterility-grade handling protocols.
- Cotton Yarn:Spun intermediate product for downstream textile manufacturing, with traceability data embedded at ginning stage.
Conventional cotton holds the largest share; momentum sits with organic certification tiers.
End User:
Cost tier segmentation separates premium-positioned medical and apparel buyers from price-sensitive home furnishing procurement.
- Textile Industry:Integrated spinning and weaving operations consuming bulk lint volumes. Greek and Italian port terminals anchor merchandising to these buyers, with ECOM Agroindustrial Corp and Louis Dreyfus Company capturing qualified volume through captive farm networks.
- Apparel Manufacturers:Brand-led procurement committees weighting traceability scores above price in annual contract negotiations. Northern Italy's luxury segment demands blockchain-verified provenance as a procurement gate.
- Home Furnishing:Mass-market bedding and upholstery facing substitution pressure from rPET recycled synthetics in non-apparel segments.
- Medical Sector:Nonwoven applications requiring REACH-compliant processing lines segregated from conventional lint streams.
Textile industry holds the largest share; momentum sits with apparel manufacturers.
Quality Grade:
Margin structure stratifies sharply across quality tiers, with specialty grades capturing narrow but defensible premium positioning.
- Premium Grade:Long-staple Gossypium barbadense cultivars with staple lengths exceeding 33mm for luxury yarn spinning. Demand concentrates in Barcelona's high-end textile cluster where Ecodesign compliance is mandatory.
- Standard Grade:Mid-length Gossypium hirsutum fiber serving volume markets. Portugal's Alentejo region presents first-mover positioning for integrated operators establishing traceable supply.
- Low Grade:Short-staple fiber for industrial nonwoven and filling applications with minimal processing value-add.
- Specialty Grade:Niche cultivars with unique color or fiber properties commanding artisanal textile premiums.
Standard grade holds the largest share; momentum sits with premium certification tiers.
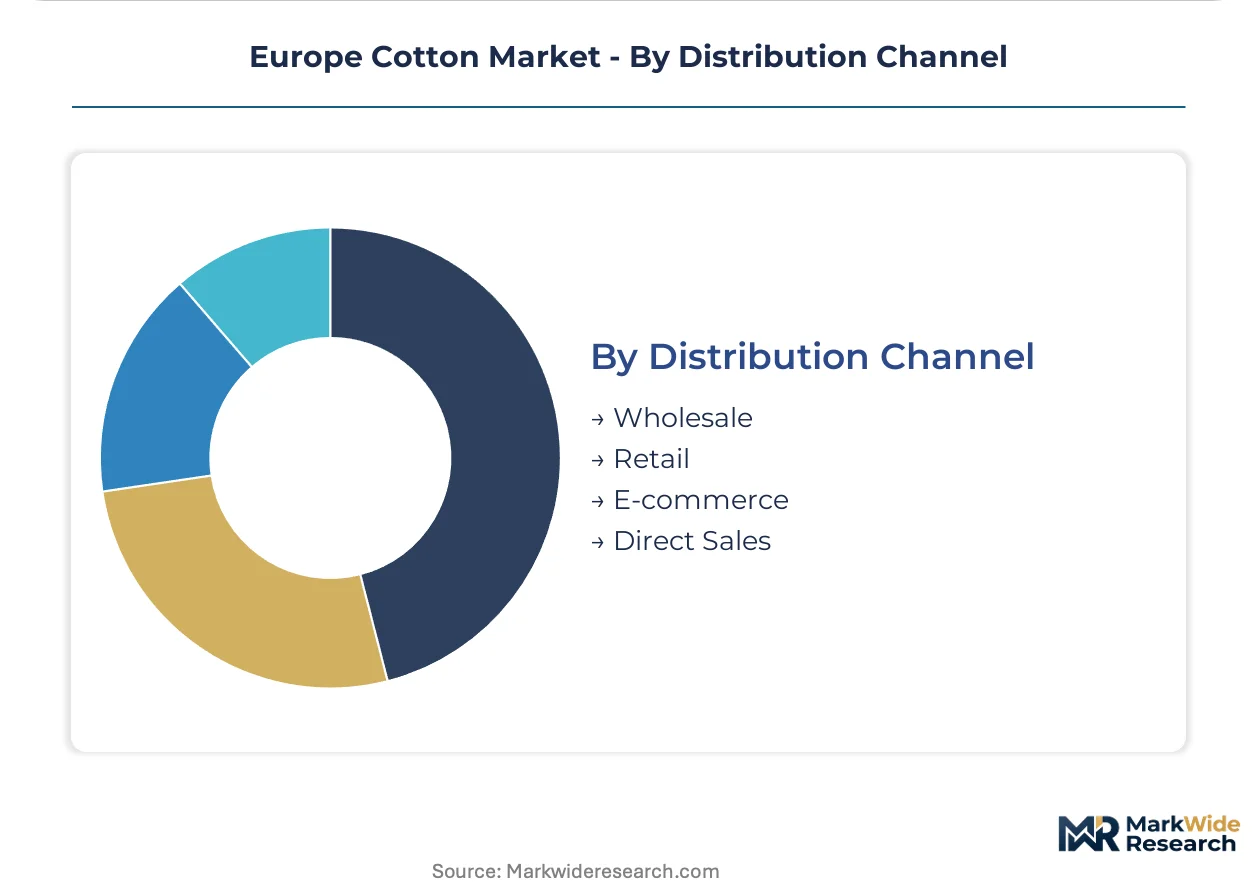
Distribution Channel:
Supply concentration favors integrated traders with port-terminal infrastructure over fragmented wholesale networks.
- Wholesale:Bulk lint merchandising through established gin-to-spinner relationships. Mediterranean growing zones feed Greek and Italian port terminals where Louis Dreyfus Company anchors European distribution.
- Retail:Direct consumer-facing sales of finished cotton goods, less relevant for raw fiber procurement.
- E-commerce:Digital platforms for specialty and organic certified lots with embedded traceability documentation.
- Direct Sales:Contract farming arrangements linking integrated operators like ECOM Agroindustrial Corp directly to spinner procurement committees.
Wholesale holds the largest share; momentum sits with direct sales channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greek port terminals in Piraeus and Thessaloniki channel Mediterranean-grown lint toward Italian spinners in Lombardy and Veneto. This trade corridor concentrates qualified volume under EU Green Deal traceability mandates.
Spain
Barcelona and Valencia textile clusters generate localized demand pull for regional cotton sourcing. The EU Green Deal's Farm to Fork Strategy tightens pesticide residue thresholds on imported lint. Almería's precision agriculture pilots deploy sensor-based irrigation across contracted acreage, improving yield consistency for ginners serving Catalan mills.
Italy
Northern Italy's premium apparel sector demands blockchain-verified provenance as a procurement gate. REACH enforcement through ECHA's SCIP database hardens chemical disclosure requirements for processed fiber. Prato's historic textile district retrofits ginneries for traceability data capture, segregating compliant from conventional lint streams.
Greece
Port terminals in Piraeus and Thessaloniki anchor European merchandising for integrated traders with captive farm networks. The Corporate Sustainability Due Diligence Directive pushes procurement committees toward certified organic fiber. Thessaly's growing zones supply regional spinners under contract farming arrangements that embed traceability documentation at ginning stage.
Portugal
Limited certified acreage in Alentejo creates first-mover positioning for integrated farm-to-gin operators. EU Ecodesign for Sustainable Products Regulation documentation requirements outpace existing auditor capacity, creating backlog risks. The country's underpenetrated organic market attracts operators establishing traceable supply chains for Spanish and French buyers.
Germany
Industrial laundries and finishers face mandatory substance registration under REACH that propagates upstream to ginners. Bayer AG's biological seed treatments reduce synthetic pesticide dependence in contracted acreage across Mediterranean sourcing regions. Hamburg's port infrastructure handles transit volumes for Central European textile manufacturers consolidating supplier panels.
Europe Cotton Market Competitive Landscape
On the supply side, the industry is consolidating around integrated traders with port-terminal infrastructure and captive farm networks. Merchant houses with gin-to-spinner relationships capture qualified volume under tightening documentation mandates. Two strategic archetypes dominate: integrated farm-to-gin operators controlling provenance data, and port-based merchandisers anchoring regional distribution. Competitive moves center on backward integration into growing zones and blockchain-IoT partnerships for real-time verification.
Within the integrated trader tier, ECOM Agroindustrial Corp Ltd. and Louis Dreyfus Company occupy positions as archetypal port-terminal anchors. Among Germany-based input suppliers, Bayer AG exemplifies the biological-treatment differentiation vector. These three names represent the span from upstream cultivation inputs through midstream merchandising to downstream qualified-supplier positioning.
| Leading Market Players |
|---|
| ECOM Agroindustrial Corp Ltd. |
| COFCO International |
| Louis Dreyfus Company |
| C.A.R.E Srl |
| Plexus Cotton Ltd. |
| Olam International |
| Deltex GmbH |
| Bayer AG |
| Cargill |
| Others |
Supply & Pricing Matrix
REACH chemical chokepoints determine both certification-grade price spreads and Mediterranean supply chain configuration. ECHA's restricted substances database blocks conventional lint from qualified supplier lists, compressing margins on non-certified tiers while widening premiums for organic-verified fiber.
Pricing Analysis
Certification-generation pricing gaps separate blockchain-verified organic from conventional and transitional grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by traceability infrastructure maturity. Price differentiation centers on Ecodesign documentation completeness and EU Green Deal compliance tier. Pricing pressure stems from rPET substitution in home furnishing segments, squeezing standard-grade margins. Mass-market Turkish exporters exhibit highest price sensitivity; Northern Italian luxury spinners weight provenance scores above cost.
Supply Chain Analysis
Greek and Italian port-terminal operators anchor European merchandising capacity for Mediterranean-grown lint. Spain, Greece, and Turkey concentrate ginnery infrastructure serving regional textile clusters. Raw material flows draw from Alentejo growing zones, Thessaly contract farms, and Almería precision agriculture pilots. Single-source vulnerability sits with auditor capacity bottlenecks for organic transition certification. Distribution runs through captive farm-to-gin networks and integrated trader port terminals rather than fragmented wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified acreage under management emerges as the binding constraint, with auditor backlog risks and Ecodesign documentation complexity outpacing available farm-to-gin integration expertise.
For Market Incumbents: Entrench qualified supplier positioning by retrofitting Mediterranean ginneries for blockchain-IoT traceability data capture. Deepen upstream control over Alentejo and Thessaly growing zones through exclusive contract farming arrangements that embed documentation at ginning stage. Defend against rPET substitution threat by segregating compliant processing lines for medical nonwoven premiums. For New Entrants and Emerging Players: Portugal's underpenetrated organic market offers first-mover positioning before auditor capacity constraints harden entry barriers. Target Spanish and French buyers seeking shortened logistics loops from Alentejo-sourced supply. Penetrate via integrated farm-to-gin partnerships that bypass fragmented wholesale channels and capture Ecodesign-compliant volume directly. For Investors and Strategic Acquirers: Mid-scale gin operators with traceability-ready infrastructure represent priority acquisition archetypes as certification timeline compression accelerates consolidation. Long-term viability hinges on captive farm network scale and Ecodesign documentation systems. Monitor ECHA SCIP database enforcement intensity and organic auditor queue lengths as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-IoT Traceability Deployment | Cryptographic lot verification unlocks qualified supplier status under Ecodesign mandates for Northern Italian spinners. |
| Backward Integration into Growing Zones | Captive farm networks in Alentejo and Thessaly secure provenance data for premium-grade contract positioning. |
| Ginnery Retrofit for Compliance Segregation | Isolated processing lines isolate REACH-compliant lint streams for medical nonwoven applications. |
| Long-term Supply Agreement with Apparel Brands | Annual contracts with Barcelona and Valencia clusters reduce audit burden through consolidated supplier panels. |
| Organic Certification Pipeline Investment | Transition period management builds certified acreage ahead of Corporate Sustainability Due Diligence Directive enforcement. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with gin operators, spinner procurement committees, and Ecodesign compliance officers; and secondary validation through EU customs trade databases, ECHA restricted substances filings, and organic certification body registries. Bottom-up acreage estimates triangulated against top-down textile consumption figures across Mediterranean sourcing regions.
Forecast inputs span certification tier adoption curves, precision agriculture penetration rates, and Ecodesign documentation compliance timelines. Segmentation dimensions modeled include product type, end-use industry, quality grade, and distribution channel. CAGRs derive from regression analysis of historical price spreads between conventional and organic grades, adjusted for regulatory enforcement intensity projections.
Practitioners should monitor REACH substance list updates, organic auditor capacity expansion, and rPET fiber cost parity for early signals of forecast revision. Quarterly review of ECHA SCIP database enforcement actions and Spanish textile cluster sourcing shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market