
 Canvas and Muslin Bags Market | 2026-2036
Canvas and Muslin Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Canvas and Muslin Bags Market Outlook
Subscription-based replenishment programs for branded reusable bags is expanding how suppliers monetize repeat engagement. Chapman Bags leverages direct-to-consumer channels to sustain premium positioning in European markets. Green Packaging Industries Private Limited anchors large-volume contracts with Indian retail conglomerates through localized manufacturing scale.
Canvas and muslin bags are woven textile containers fabricated from cotton or cotton-blend fibers, typically ranging from 4 oz to 12 oz fabric weight, with muslin distinguished by its finer plain-weave construction and lower thread count. These bags serve primary commercial purposes in retail merchandise transport, agricultural produce storage, and promotional brand distribution. Tote bags occupy the dominant volume position within product type segmentation due to their structural versatility for grocery and fashion applications. Drawstring bags represent the fastest-expanding category among end users, particularly event organizers seeking lightweight branded collateral. Online retail channels now capture disproportionate margin pools compared to wholesalers, driven by customization tooling and reduced intermediary costs.
The EU Single-Use Plastics Directive and California's SB 270 plastic bag ban shape product standards by mandating minimum durability thresholds and recycled content disclosures for reusable alternatives. BIS certification requirements in India and FDA food-contact material guidelines in the United States further constrain material sourcing and finishing chemistries. Stakeholders must monitor evolving state-level procurement mandates and substrate traceability requirements to anticipate compliance-driven sourcing decisions.
Market Dynamics
Single-use plastic bans across Germany, the United Kingdom, and the northeastern United States are forcing retail procurement departments to rewrite supplier qualification criteria around durability thresholds and recycled content verification.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-out of lightweight plastic carrier bags creates immediate replacement demand for cotton-based alternatives in grocery and fashion retail.
- Subscription replenishment models:Direct-to-consumer channels enable bag suppliers to capture recurring revenue streams through branded membership programs rather than one-time wholesale transactions.
- California SB 270:State-level durability standards for reusable bags elevate technical specifications, filtering out low-quality imports and rewarding certified domestic manufacturers.
Market Restraints
- Cotton price volatility:Input cost swings tied to commodity cotton futures compress margin predictability for converters operating on fixed-price annual contracts.
- Indian supply concentration:Disproportionate weaving and finishing capacity clustered in Gujarat and Tamil Nadu creates geographic vulnerability to monsoon disruptions and power rationing.
- Polypropylene non-woven substitution:Lower-cost synthetic reusables from Southeast Asian producers undercut cotton positioning in price-sensitive promotional bag segments.
Strategic Opportunities
- Indian organized retail expansion:Reliance Retail and DMart procurement windows favor localized BIS-certified suppliers capable of meeting 10,000-unit minimum order quantities with 14-day turnaround.
- Digital printing convergence:Integration of direct-to-garment systems with web-to-print configurators collapses customization lead times from weeks to 48 hours for event marketing buyers.
- Corporate ESG procurement mandates:CSRD-aligned sustainability reporting requirements in the European Union are elevating traceability-certified bags to preferred vendor status in enterprise promotional spending.
Industry Challenges
- GOTS certification timelines:Organic textile standard audits require 90-120 day validation cycles that misalign with seasonal retail buying calendars.
- ERP integration friction:Legacy wholesale distributors struggle to connect inventory systems with Shopify and WooCommerce storefronts demanded by emerging direct-to-consumer brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canvas and Muslin Bags Market |
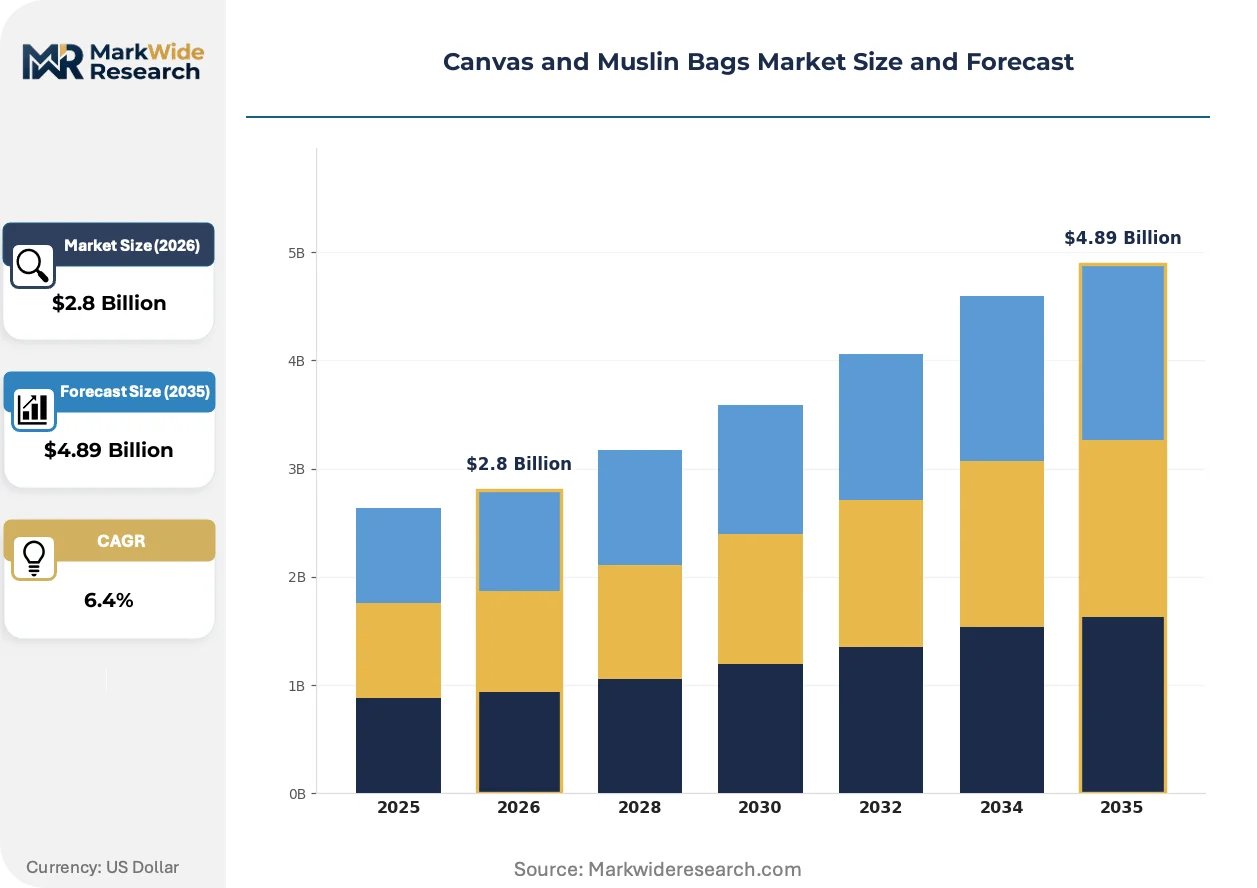
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Eco-Friendly Bags, Drawstring Bags, Tote Bags End User: Retail Stores, Grocery Chains, Fashion Brands, Event Organizers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores Application: Daily Use, Promotional Use, Packaging, Gift Bags |
| Companies Covered | StateLine Bag Company, Inc., Chapman Bags, The Clever Baggers Ltd, Celestial Gifts LLC, Sofar International Industry, Green Packaging Industries Private Limited, Bags Direct International Ltd., Lanxi Chik Lee Fabrics Co., Ltd., Shenzhen Jiaxinda Packing Products Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canvas and Muslin Bags Market Strategic Shifts
Digital production workflows and substrate traceability systems are compressing the traditional separation between commodity bag manufacturing and premium customization services.
Water-based pigment inkjet systems are modularizing the economics of short-run decorated bags. Event marketing agencies now order 500-unit customized drops rather than committing to 5,000-unit screen-print minimums. This technology is modularizing supplier capabilities, allowing regional converters to compete with offshore scale players on speed rather than unit cost.
REACH SVHC disclosure requirements are tightening chemical transparency obligations across European supply chains. Dye houses and finishing facilities must now document substance volumes above 0.1% w/w thresholds in articles placed on the EU market. German retail consortiums are responding by consolidating procurement around vertically integrated mills with certified chemical management systems.
Corporate buyers are unbundling bag procurement from broader promotional merchandise contracts. Marketing departments now issue standalone RFPs for reusable carriers with specified carbon footprint data, displacing the traditional bundled approach through general merchandise distributors. This pattern is most pronounced in United Kingdom financial services and professional services verticals where ESG disclosure requirements shape vendor selection.
Canvas and Muslin Bags Market Segmentation
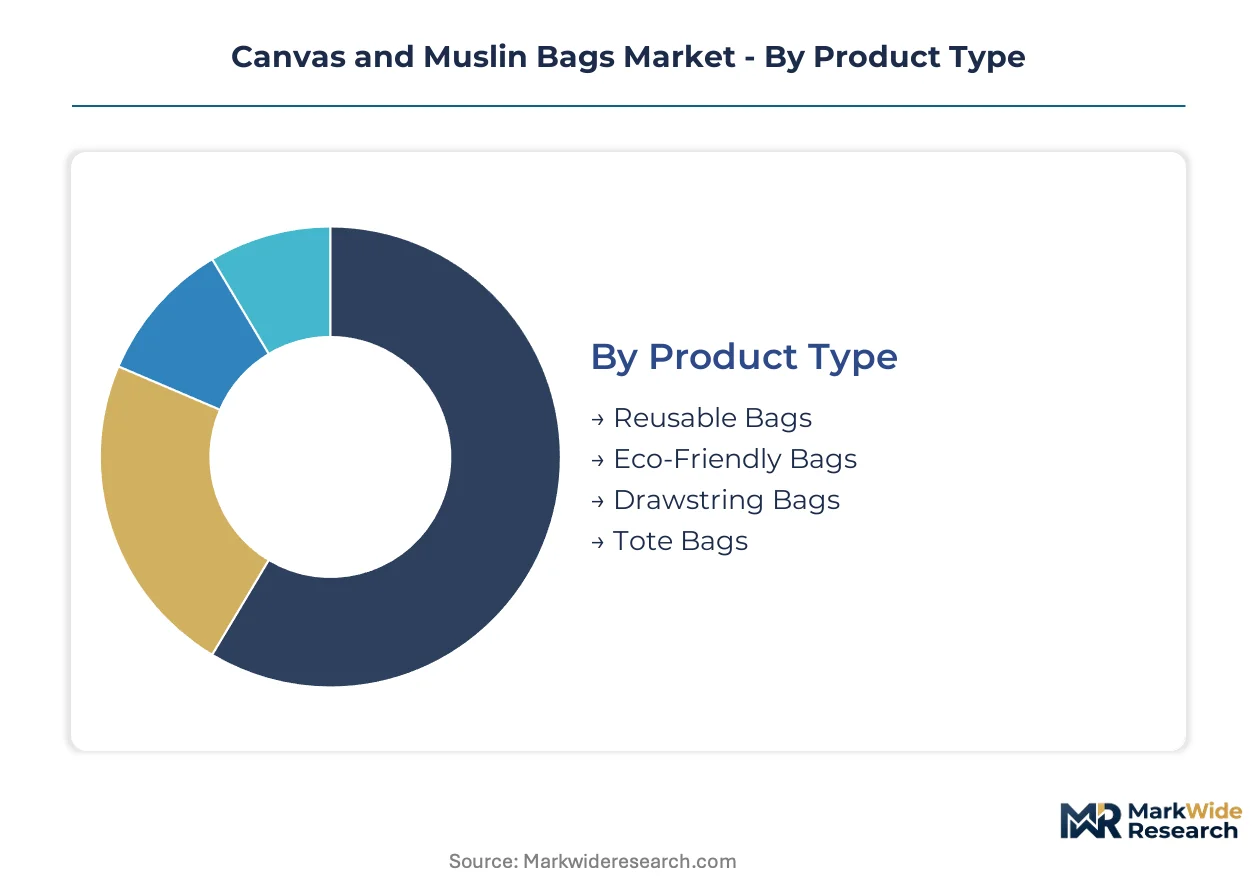
Segmentation in the canvas and muslin bags market reveals distinct procurement behaviors across product formats and buyer categories. Replacement cycles vary dramatically between grocery-driven reusable totes and event-focused drawstring formats.
Product Type:
Upgrade cycles differ sharply across bag formats, with grocery retailers replacing inventory on 18-24 month schedules while promotional buyers rotate designs seasonally.
- Tote Bags:Open-top rectangular carriers with reinforced handles dominate grocery and fashion retail procurement. German supermarket chains specify 10-ounce cotton duck construction with bar-tacked stress points for 100-load durability cycles.
- Drawstring Bags:Lightweight cinch-closure containers with simple channel stitching represent the fastest-expanding format. Event marketing agencies in the United Kingdom favor these for conference swag programs requiring sub-50 gram unit weights.
- Reusable Bags:General-purpose carriers spanning multiple closure styles serve municipal bag-ban compliance markets. California retailers prioritize these for SB 270 qualification.
- Eco-Friendly Bags:Certified organic or recycled-content variants command premium positioning in corporate ESG procurement. REACH-compliant dye processes are mandatory for EU placement.
Tote bags sit at the top of the volume ranking, with drawstring bags climbing the fastest.
End User:
Cost tiers separate end-user categories, with fashion brands absorbing 3-4x unit costs versus grocery chains through customization and certification premiums.
- Retail Stores:Department stores and boutique chains source branded carriers as margin-building accessories. United States Northeast corridor buyers emphasize FDA food-contact compliance for in-store café bundling.
- Grocery Chains:High-volume procurement departments negotiate 50,000-unit annual contracts with durability verification. EU Single-Use Plastics Directive compliance drives specification rigor.
- Fashion Brands:Label-conscious buyers specify GOTS-certified organic cotton with custom woven labels. These accounts tolerate 8-12 week lead times for certified supply chains.
- Event Organizers:Trade show and conference planners prioritize 48-hour customization turnaround over unit cost. Digital printing compatibility is a primary selection filter.
Grocery chains anchor the volume base, though fashion brands generate the steepest margin expansion.
Distribution Channel:
Channel selection tracks customer scale and technical requirements, with large accounts bypassing intermediaries while smaller buyers rely on configurators.
- Online Retail:Web-to-print platforms capture customization-heavy orders below 1,000 units. Shopify-integrated suppliers win emerging direct-to-consumer bag brands.
- Direct Sales:Manufacturer field teams handle enterprise accounts requiring specification negotiation. These relationships lock in 3-year supply agreements with price collars.
- Wholesalers:Traditional distributors serve price-sensitive promotional markets with undecorated stock bags. Inventory depth determines competitive position.
- Specialty Stores:Eco-focused retailers curate certified organic assortments for conscious consumers. BIS certification opens access to Indian urban premium channels.
Direct sales channels dominate value capture, while online retail is gaining share fastest among sub-5,000 unit orders.
Application:
Application segmentation maps to durability requirements and decoration complexity, with daily-use bags facing mechanical stress versus promotional items optimized for visual impact.
- Daily Use:Grocery and shopping applications demand abrasion-resistant 8-12 ounce canvas with reinforced seams. Washing cycle tolerance is a critical specification.
- Promotional Use:Brand distribution at events and trade shows prioritizes surface area for logo reproduction. Water-based ink compatibility drives substrate selection.
- Packaging:Product containment applications in cosmetics and gourmet foods require food-grade finishing. FDA compliance documentation is mandatory for United States placement.
- Gift Bags:Premium presentation formats use finer muslin weaves with ribbon or button closures. Seasonal demand peaks concentrate in fourth-quarter procurement calendars.
Daily use applications command the highest unit volumes, with promotional use expanding most quickly as event marketing budgets recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in regulatory-driven bag procurement velocity, while India scales manufacturing capacity faster than any Southeast Asian competitor. National policy frameworks and retail consolidation patterns create divergent growth trajectories across key production and consumption markets.
United States
California and New York state mandates are forcing nationwide retailer compliance recalibration. The FDA maintains strict food-contact material guidelines for in-store café bundling applications. Dallas-Fort Worth logistics clusters now host regional distribution hubs serving grocery chains across the Southwest and Midwest corridors.
Germany
Supermarket chains specify 10-ounce cotton duck construction with bar-tacked stress points for durability verification. The EU Single-Use Plastics Directive mandates phase-out timelines that accelerate replacement procurement cycles. The Ruhr industrial region concentrates weaving and finishing capacity for Western European retail supply.
United Kingdom
Financial services and professional services verticals issue standalone RFPs for reusable carriers with carbon footprint specifications. REACH SVHC disclosure requirements tighten chemical transparency obligations across dye houses and finishing facilities. Manchester-based converters are integrating digital printing workflows for event marketing agencies.
India
Reliance Retail and DMart procurement windows favor localized BIS-certified suppliers with 10,000-unit minimum order capabilities. The Bureau of Indian Standards certification requirements constrain material sourcing and finishing chemistries for organized retail channels. Gujarat and Tamil Nadu weaving clusters face geographic vulnerability to monsoon disruptions and power rationing.
China
Export-oriented manufacturers serve European and North American private-label demand through direct sales relationships. GB standards and SAMR oversight shape domestic product specifications for food-contact applications. The Pearl River Delta maintains concentrated capacity for short-run customization with 48-hour turnaround capabilities.
Canvas and Muslin Bags Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among European heritage names and volume production anchored in South Asian scale players. The vendor base organizes into three functional tiers: vertically integrated mills controlling dye-to-distribution workflows, regional converters competing on speed-to-market, and trading houses arbitraging offshore capacity. Two dominant competitive moves are reshaping positioning: European retail consortiums consolidating procurement around certified chemical management systems, and Indian suppliers deepening backward integration into cotton ginning to secure BIS-compliant input streams.
Among UK-based heritage specialists, Chapman Bags occupies a position exemplifying direct-to-consumer premium positioning, while The Clever Baggers Ltd represents the contract manufacturing archetype serving private-label retail programs. Green Packaging Industries Private Limited anchors the Indian scale tier, demonstrating how localized BIS-certified production captures organized retail procurement windows. These three entities illustrate the geographic and functional stratification defining competitive dynamics.
| Leading Market Players |
|---|
| StateLine Bag Company, Inc. |
| Chapman Bags |
| The Clever Baggers Ltd |
| Celestial Gifts LLC |
| Sofar International Industry |
| Green Packaging Industries Private Limited |
| Bags Direct International Ltd. |
| Lanxi Chik Lee Fabrics Co., Ltd. |
| Shenzhen Jiaxinda Packing Products Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Digital printing convergence is compressing minimum order quantities from thousands to hundreds of units, simultaneously eroding scale-based pricing premiums and dispersing production capacity across regional converters in Germany, the United Kingdom, and the United States.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade canvas totes, forcing European heritage suppliers toward certified organic tiers where GOTS validation sustains 40-60% premiums over commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels separates fashion brand procurement from grocery chain volume contracts. Cost compression in the promotional segment stems from polypropylene non-woven substitution out of Southeast Asia. Event organizers exhibit the highest price sensitivity, while fashion brands absorb certification premiums with minimal negotiation.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Rotterdam, and Singapore anchor hub-and-spoke fulfillment for grocery and retail procurement. Raw cotton supply draws from India, the United States, and Brazil, with weaving and finishing capacity concentrating in Gujarat, Tamil Nadu, and the Pearl River Delta. Single-source vulnerability persists in certified organic cotton gins, where GOTS-compliant supply chains tether to fewer than twelve validated facilities globally. Distribution runs through direct manufacturer relationships for enterprise accounts and web-to-print platforms for sub-1,000 unit orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement departments unbundling bag contracts from general merchandise to specify carbon footprint and chemical transparency thresholds.
For Market Incumbents: Anticipate margin compression in undifferentiated promotional tiers as digital printing democratizes customization capabilities. Prioritize backward integration into certified organic cotton ginning to secure GOTS-compliant input streams against supply scarcity. Lock three-year enterprise contracts with price collars before Indian scale players achieve REACH-equivalent chemical management certifications. For New Entrants and Emerging Players: Launch via Shopify-integrated web-to-print platforms targeting event marketing agencies with 48-hour turnaround guarantees. White-space concentrates in BIS-certified supply for Indian organized retail, where Reliance Retail and DMart procurement windows favor localized 10,000-unit minimum order capabilities. Penetrate through sustainability-native direct-to-consumer brands seeking domestic manufacturing transparency. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with digital printing infrastructure but lacking certification depth. Long-term viability favors vertically integrated mills controlling dye-to-distribution workflows with validated chemical management systems. Watch CSRD-aligned sustainability reporting requirements as the inflection signal elevating traceability-certified bags to preferred vendor status.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Investment | Organic textile validation unlocks fashion brand procurement with 8-12 week lead time tolerance. |
| Digital Printing Infrastructure | Direct-to-garment systems collapse customization lead times from weeks to 48 hours for event buyers. |
| Backward Cotton Integration | In-house ginning secures BIS-compliant input streams for Indian organized retail contracts. |
| Web-to-Print Platform Launch | Shopify integration captures emerging direct-to-consumer bag brands below 1,000-unit thresholds. |
| REACH-Compliant Dye House Consolidation | Certified chemical management systems satisfy German retail consortium procurement mandates. |
Study Parameters
Direct dialogue with procurement directors at grocery chains, sustainability officers at fashion brands, dye house technical managers, and event marketing agency buyers grounded the qualitative foundation. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, BIS certification registries, FDA food-contact material guidelines, and REACH SVHC disclosure databases. Bottom-up and top-down triangulation reconciled unit volume estimates with value projections.
Bottom-up modeling tracked tote, drawstring, and reusable bag formats across retail, grocery, fashion, and event end-use categories. Top-down demand estimation calibrated against cotton fiber consumption data and weaving capacity utilization in Gujarat, Tamil Nadu, and the Pearl River Delta. CAGRs derived from regression analysis of historical replacement cycle data and regulatory mandate implementation timelines. Segment-level forecasts incorporated durability specification thresholds, certification penetration rates, and digital printing adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cotton price volatility and monsoon disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Cotton Bags Market