
 Asia Pacific Cotton Market | 2026-2036
Asia Pacific Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cotton Market Outlook
The EU Green Deal's due diligence requirements for deforestation-free supply chains is hardening compliance burdens on Asian cotton exporters. Cargill, Incorporated leverages its origination networks across Australia and India to secure traceable lint for European buyers. Vardhman Textiles Limited anchors its competitive position through backward integration into yarn and fabric production. ECOM Agroindustrial Corporation Ltd. specializes in sustainable certification programs that differentiate its offering in premium apparel supply chains.
Asia Pacific cotton comprises the seed-hair fibers of Gossypium species, typically measuring 25 to 40 millimeters in staple length and 12 to 22 microns in fiber fineness, spun into yarn for woven and knitted textiles. Raw cotton commands the largest value share among product types due to its role as the foundational input for regional spinning industries. Yarn and fabric segments attract growing investment as Bangladeshi and Vietnamese mills expand capacity to serve apparel brand sourcing shifts away from China. Cottonseed processing yields edible oil and animal feed, creating secondary revenue pools that offset ginning costs for integrated processors.
India's Textile Ministry enforces BIS fiber quality standards that govern domestic trading and export eligibility, while China's GB standards and MEE environmental audits constrain water-intensive ginning operations in Xinjiang and the Yellow River basin. The EU AI Act's supply chain transparency mandates will soon require automated traceability documentation for cotton entering European apparel channels. Stakeholders must monitor how India's PLI scheme disbursement timelines and China's dual carbon enforcement reshape regional cost structures and sourcing geography.
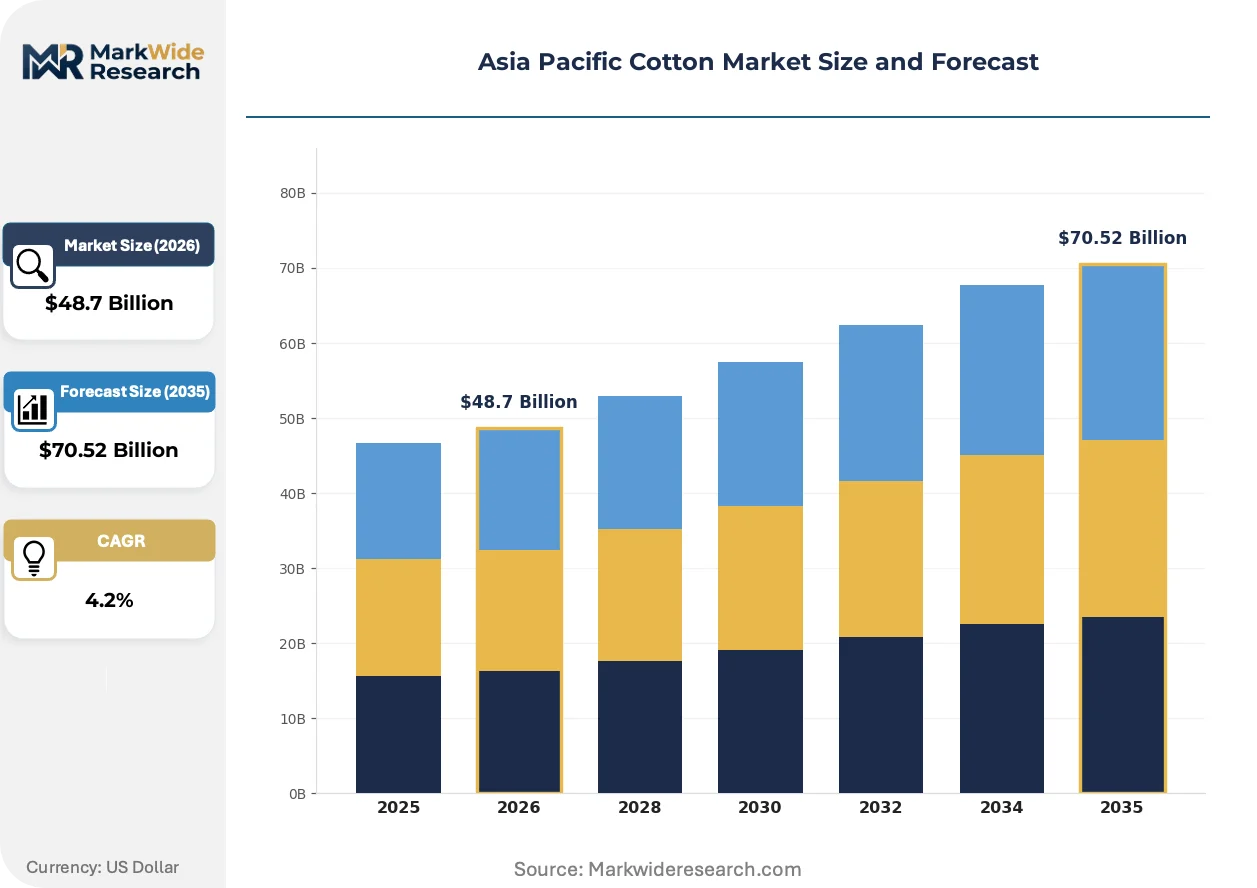
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are compressing sourcing options for Asia Pacific cotton exporters, forcing mills to rebuild traceability infrastructure or lose European apparel brand contracts.
Growth Catalysts
- India's PLI scheme for textiles:The production-linked incentive program is accelerating domestic cotton processing capacity expansion in Gujarat and Maharashtra, reducing raw lint export dependency.
- Apparel brand sourcing pivots:Bangladeshi and Vietnamese textile manufacturers are absorbing cotton orders previously routed through Chinese mills, lifting regional fiber throughput.
- Digital traceability platforms:Blockchain-enabled lint tracking systems are satisfying EU due diligence requirements and unlocking premium contract access for compliant processors.
Market Restraints
- Input cost volatility:Fertilizer and irrigation energy costs in India's cotton belt swing with global ammonia and diesel markets, compressing ginning margins unpredictably.
- Supply concentration risk:Xinjiang's dominance in Chinese cotton output exposes European-facing supply chains to forced labor documentation requirements and border detention risks.
- Water-intensive processing:China's MEE environmental audits are constraining ginning operations in the Yellow River basin, capping regional lint throughput regardless of fiber demand.
Strategic Opportunities
- Vietnam's underpenetrated spinning base:The country's apparel export growth has outpaced domestic cotton yarn capacity, creating import substitution potential for integrated Vietnamese mills.
- Sustainable certification premiums:BCI and organic cotton programs are commanding price premiums in European and North American apparel channels, rewarding early compliance investments.
- Cottonseed value capture:Integrated processors in India are expanding edible oil and animal feed output from ginning byproducts, offsetting lint price cyclicality through downstream revenue.
Industry Challenges
- Traceability system integration:Legacy inventory management platforms at Indian and Bangladeshi mills require costly retrofitting to meet EU AI Act automated documentation mandates.
- Skilled ginning technician shortages:Modern roller gin and contamination control operations in Vietnam lack trained operators, capping quality consistency for export-grade lint.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cotton Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cotton, Yarn, Fabric, Cottonseed End User: Textile Manufacturers, Apparel Brands, Home Furnishing, Industrial Users Application: Clothing, Home Textiles, Medical Textiles, Agricultural Uses Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Cargill, Incorporated, Lu Thai Textile Co., Ltd., Weiqiao Textile, Nishat Mills Limited, Shandong Jining Ruyi Woolen Textile Co., Ltd., Olam International Limited, Vardhman Textiles Limited, ECOM Agroindustrial Corporation Ltd., Louis Dreyfus Company B.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cotton Market Strategic Shifts
Automation and regulatory compliance technologies are restructuring how Asia Pacific cotton moves from field to spinner, with digital traceability and water-efficient processing emerging as decisive competitive differentiators.
Sensor-based precision agriculture is electrifying yield optimization across India's Deccan Plateau cotton farms. Andhra Pradesh and Telangana growers are deploying soil moisture monitors and drone-based pest detection to reduce input waste and fiber contamination. These systems are compressing the yield gap between smallholder plots and commercial estates while generating the farm-level data records required for EU supply chain audits.
China's dual carbon enforcement through MEE audits is mandating closed-loop water recycling at Xinjiang and Yellow River basin ginning facilities. The policy is shuttering non-compliant small processors and consolidating throughput among capital-rich operators capable of membrane filtration and solar thermal drying installations. Indian spinners sourcing from these zones now face truncated supplier lists and extended lead times for traceable lint.
European apparel brands are unbundling their cotton procurement from traditional trading house intermediaries, establishing direct mill relationships in Bangladesh and Vietnam with embedded sustainability auditors. This channel compression is disintermediating legacy lint traders who lack certification capabilities while rewarding vertically integrated spinners with captive compliance teams. The shift is most visible in Dhaka's export processing zones, where brand technical teams now co-locate with yarn producers.
Asia Pacific Cotton Market Segmentation
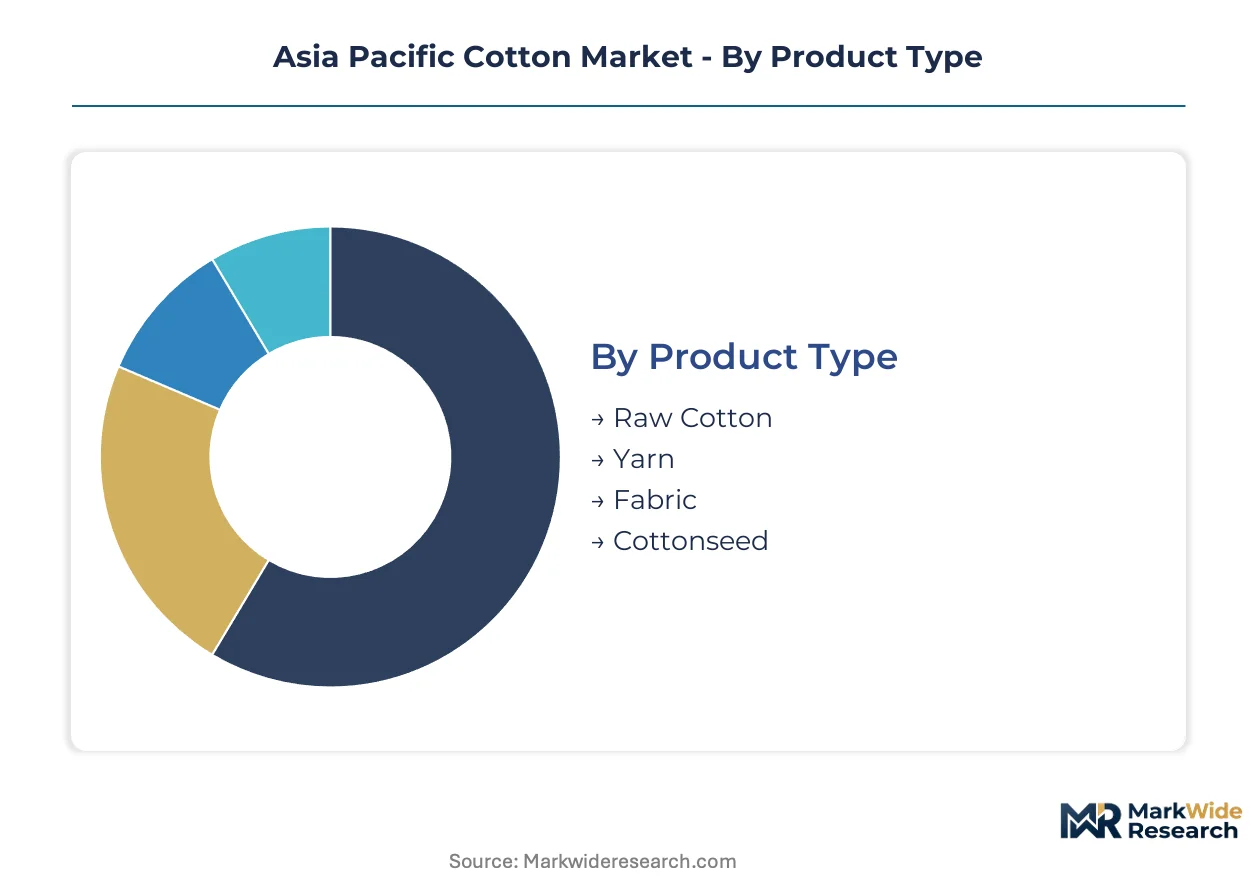
Segmentation reveals how certification burdens and processing depth reshape margin capture across the Asia Pacific cotton value chain. Regulatory divergence between EU, Indian, and Chinese compliance frameworks fragments procurement strategies by product form and end-use sophistication.
Product Type:
EU Green Deal deforestation-free mandates and India's BIS fiber quality standards impose divergent documentation requirements across processed versus unprocessed forms.
- Raw Cotton:Unprocessed seed-hair fibers of Gossypium species measuring 25-40mm staple length serve as the foundational input for regional spinning industries. Demand concentrates in India's Gujarat-Maharashtra belt and China's Xinjiang zone, where ginners face escalating EU due diligence audits for traceability documentation.
- Yarn:Spun fibers ready for weaving and knitting operations attract capacity expansion in Bangladesh and Vietnam as apparel brands pivot sourcing away from Chinese mills. Bangladeshi spinners absorb cotton orders previously routed through integrated Chinese processors, lifting regional fiber throughput.
- Fabric:Woven and knitted textiles represent downstream processing stages where PLI scheme incentives in India accelerate domestic value addition.
- Cottonseed:Ginning byproducts yield edible oil and animal feed, creating secondary revenue pools that offset lint price cyclicality for integrated processors in India.
Raw Cotton sits at the top of the volume ranking, with Yarn climbing the fastest.
End User:
Cost tier stratification separates commodity bulk buyers from premium channel partners bearing sustainability audit costs.
- Textile Manufacturers:Spinners and weavers in Bangladesh, Vietnam, and India's Tamil Nadu-Punjab corridors consume the majority of regional lint output. These mills face retrofitting costs for legacy inventory platforms to meet EU AI Act automated traceability mandates.
- Apparel Brands:European and North American clothing labels are unbundling procurement from trading intermediaries, establishing direct mill relationships with embedded sustainability auditors in Dhaka's export processing zones.
- Home Furnishing:Upholstery and bedding producers source longer-staple varieties for durability requirements in premium residential and hospitality segments.
- Industrial Users:Technical textile applications including automotive and filtration absorb specialty grades with contamination-controlled specifications.
Textile Manufacturers command the dominant volume position, while Apparel Brands are expanding most quickly through direct mill partnerships.
Application:
Margin structure varies sharply between standardized clothing volumes and specialized medical grades requiring contamination protocols.
- Clothing:Apparel production absorbs the majority of Asia Pacific cotton fiber, with Bangladesh and Vietnam expanding garment export capacity to capture orders shifting from China.
- Home Textiles:Bedding, towels, and curtains utilize medium-staple grades where price sensitivity limits premium certification penetration.
- Medical Textiles:Surgical gauze and hygiene products demand high-purity lint with strict bioburden controls, creating niche premiums for certified Indian and Australian origins.
- Agricultural Uses:Seed distribution and planting stock circulate through distinct channels separate from textile value chains.
Clothing maintains volume leadership, with Medical Textiles gaining share fastest on pandemic-era hygiene investment.
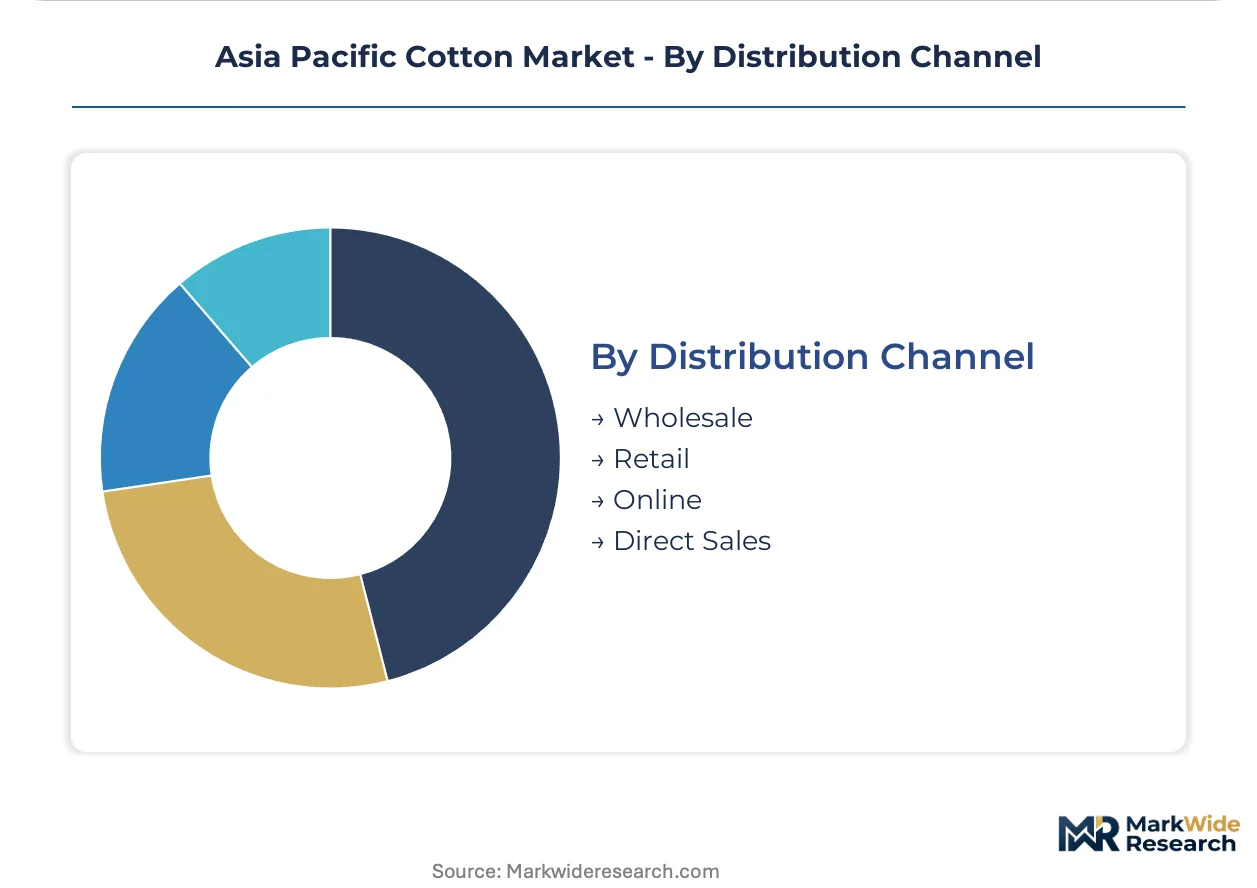
Distribution Channel:
Supply concentration in origination zones dictates channel efficiency for traceable versus commodity grades.
- Wholesale:Traditional trading houses in Mumbai, Karachi, and Shanghai handle bulk lint movements between ginners and spinners, though disintermediation pressures mount from brand direct sourcing.
- Retail:Finished yarn and fabric sales to small-scale weavers and regional garment units operate through localized trading networks.
- Online:Digital platforms for cotton procurement remain underdeveloped relative to other commodities, constrained by quality verification requirements.
- Direct Sales:Vertically integrated spinners with captive ginning operations in India's Vardhman cluster and China's Xinjiang zone bypass intermediaries for major brand accounts.
Wholesale retains volume dominance, while Direct Sales shows the steepest expansion trajectory as brands consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton cultivation and processing scaled across Asia Pacific through British colonial plantation systems in India and mechanized ginning adoption in China during the early twentieth century. Today the region concentrates ginning capacity, yarn spinning, and fabric weaving across distinct national production zones shaped by divergent regulatory frameworks.
India
Gujarat and Maharashtra cotton belts drive lint output through smallholder cultivation networks feeding domestic spinning mills. The Textile Ministry's PLI scheme accelerates processing capacity expansion while BIS fiber quality standards govern export eligibility. Tamil Nadu spinners in Coimbatore and Tiruppur absorb expanding yarn orders from Bangladeshi garment exporters.
China
Xinjiang autonomous zone dominates domestic fiber production through state-coordinated agricultural enterprises controlling ginning throughput. MEE environmental audits enforce water recycling mandates at Yellow River basin processing facilities while GB standards constrain contamination thresholds. Zhengzhou commodity exchanges anchor price discovery for regional lint trading.
Bangladesh
Garment export growth from Dhaka's export processing zones outpaces domestic yarn spinning capacity, creating import dependency for lint and intermediate goods. The country's national textile regulator enforces compliance protocols for European brand sourcing audits. Chittagong port logistics handle bulk cotton arrivals from Indian and Central Asian origins.
Vietnam
Apparel manufacturing expansion in Ho Chi Minh City and Hanoi corridors absorbs cotton orders previously routed through Chinese mills. Domestic ginning infrastructure remains underdeveloped relative to garment output, forcing reliance on imported yarn. The government's industrial zone incentives attract spinning investment from regional textile conglomerates.
Australia
New South Wales and Queensland irrigation districts supply contamination-controlled lint to premium medical and hygiene textile channels. Farm-level traceability systems satisfy EU deforestation-free supply chain mandates. Brisbane and Sydney trading houses coordinate export shipments to Asian spinning mills seeking certified origins.
Asia Pacific Cotton Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification capability and traceability infrastructure. The vendor base stratifies between integrated agricultural-trading conglomerates with origination networks and specialized textile manufacturers with captive spinning capacity. Three archetypes dominate: global commodity traders with sustainability certification programs, vertically integrated spinners with backward ginning control, and regional trading specialists with mill-direct relationships. Competitive moves concentrate on M&A for traceability technology and capacity expansion in Vietnam and Bangladesh.
Among integrated agricultural processors, Cargill, Incorporated and Louis Dreyfus Company B.V. represent the global trading archetype with multi-origination sourcing networks. Vardhman Textiles Limited anchors the spinner-integrated tier through captive yarn and fabric production. These three exemplify how compliance investment separates premium-contract access from commodity lint trading.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Lu Thai Textile Co., Ltd. |
| Weiqiao Textile |
| Nishat Mills Limited |
| Shandong Jining Ruyi Woolen Textile Co., Ltd. |
| Olam International Limited |
| Vardhman Textiles Limited |
| ECOM Agroindustrial Corporation Ltd. |
| Louis Dreyfus Company B.V. |
| Others |
Value Chain & Pricing Dynamics
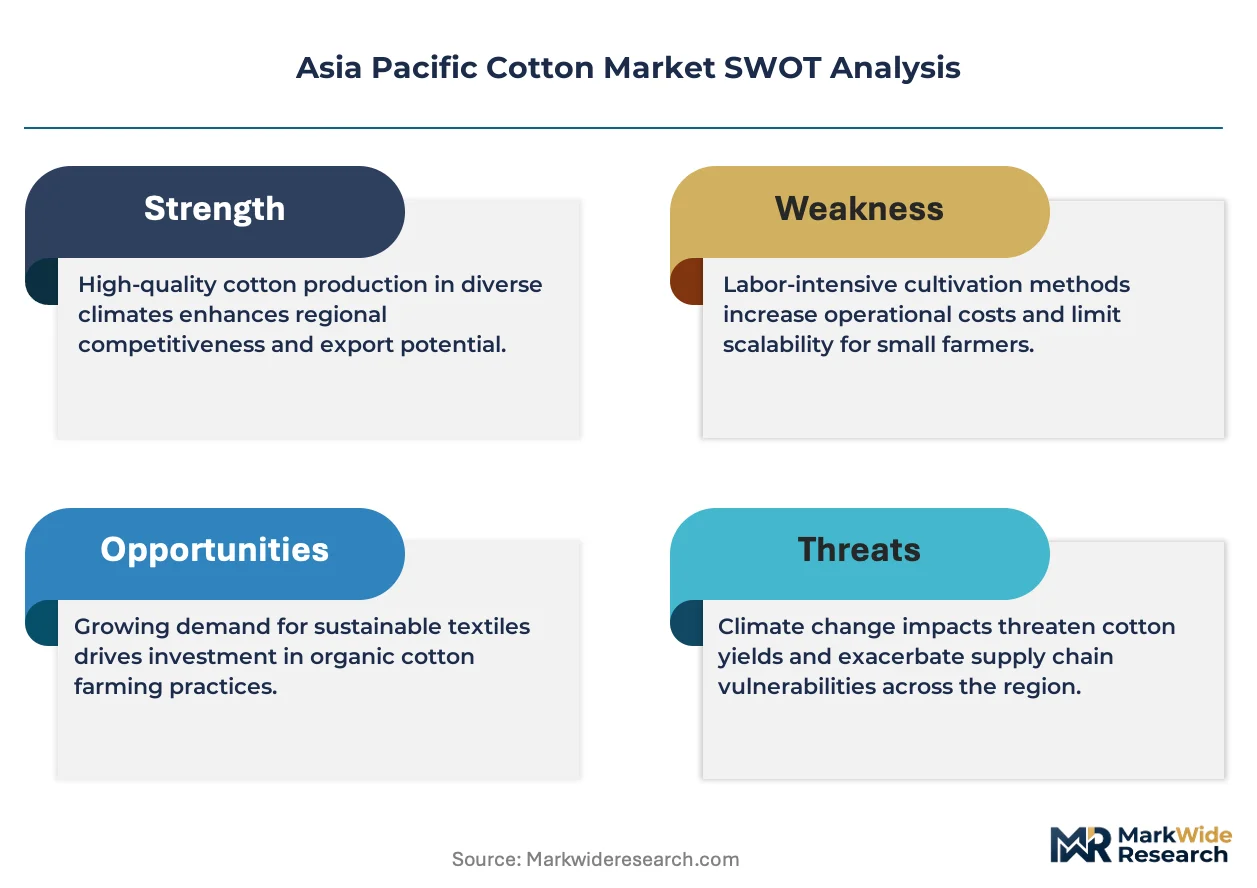
Certification-grade bifurcation between BCI-organic premium lint and commodity-grade standard cotton manifests in divergent pricing power and supply chain configurations across the Asia Pacific cotton market. EU Green Deal deforestation-free mandates compress sourcing options for uncertified lint while rewarding compliant processors with premium contract access and direct mill relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs lint transactions across Asia Pacific origination zones. Price differentiation separates BCI-certified and organic grades from conventional lint, with certification premiums widening as European apparel brands harden sustainability audit requirements. Cost compression in standard-grade segments intensifies because Indian and Bangladeshi mills absorb rising fertilizer and irrigation energy expenses without full pass-through to buyers. Textile manufacturers in Vietnam exhibit highest price sensitivity due to import-dependent spinning capacity, while European apparel brands demonstrate lowest sensitivity when securing traceable supply for premium channels.
Supply Chain Analysis
Seed cotton supply rests on smallholder cultivation networks across India's Gujarat-Maharashtra belt, state-coordinated enterprises in China's Xinjiang zone, and irrigation-dependent estates in Australia's New South Wales-Queensland districts. Raw material inputs draw from ammonia fertilizer producers, diesel-powered ginning operations, and water-intensive processing facilities. Single-source vulnerability concentrates in Xinjiang's dominance of Chinese lint output, exposing European-facing supply chains to forced labor documentation requirements and border detention risks. Distribution runs through Mumbai, Karachi, and Shanghai trading houses for bulk movements, though brand-direct mill relationships in Dhaka's export processing zones are compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific cotton market functions as a regulatory compounder where EU AI Act supply chain transparency mandates and Green Deal due diligence requirements are restructuring procurement economics and competitive positioning.
For Market Incumbents: Lock in traceability infrastructure investments before EU AI Act automated documentation mandates take full effect, retrofitting legacy inventory platforms at Indian and Bangladeshi mill networks. Deepen backward integration into ginning operations across Gujarat and Maharashtra to capture PLI scheme incentives and reduce raw lint export dependency. Threats from digital-native trading platforms with embedded blockchain verification capabilities are displacing traditional intermediary margins. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated spinning base where apparel export growth has outpaced domestic yarn capacity, creating import substitution potential for integrated mills. Target sustainable certification programs as the most penetrable wedge, commanding price premiums in European and North American apparel channels. A go-to-market angle anchored in farm-level sensor deployments and drone-based pest detection generates the data records required for EU supply chain audits. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated spinners with captive ginning control and certification capabilities across India's Vardhman cluster and comparable operations. Long-term viability favors processors capable of offsetting lint price cyclicality through cottonseed value capture in edible oil and animal feed production. The signal to watch is disbursement timelines under India's PLI scheme and enforcement intensity of China's MEE environmental audits reshaping regional cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ginning | Captures PLI scheme incentives in Gujarat-Maharashtra while securing traceable lint supply for European buyers. |
| Blockchain Traceability Deployment | Satisfies EU AI Act automated documentation mandates and unlocks premium contract access for compliant processors. |
| Cottonseed Value Expansion | Offsets lint price cyclicality through edible oil and animal feed output from ginning byproducts in India. |
| Vietnam Spinning Capacity Buildout | Addresses import substitution potential as garment export growth outpaces domestic yarn production. |
| Sustainable Certification Investment | Commands price premiums in European apparel channels through BCI and organic cotton program compliance. |
Study Parameters
Multiple input streams — ginning operation assessments, textile mill procurement data, and apparel brand sourcing disclosures — were reconciled across primary interviews with ginning facility managers, spinning mill procurement leads, textile ministry officials, and sustainability auditors at European apparel brands. Secondary validation drew from BIS fiber quality standards documentation, EU Green Deal regulatory texts, MEE environmental audit protocols, and customs trade records. Bottom-up lint production estimates and top-down apparel demand projections were triangulated to anchor volume and value assessments.
Historical shipment patterns were cross-referenced against expert panel inputs from regional trading houses and textile conglomerates. Segmentation dimensions modeled span product type, end-user category, application, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation adjusted for policy intervention effects. Forecast inputs incorporated PLI scheme disbursement schedules, MEE audit enforcement trajectories, and apparel brand sourcing pivot velocities away from Chinese mills.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts, climate-induced yield volatility in Deccan Plateau cultivation zones, and geopolitical disruptions to Xinjiang lint export pathways. Forecasts reflect assumptions around regulatory implementation timelines and certification program adoption rates. A small set of named triggers — EU AI Act enforcement commencement, India PLI scheme revision, and China dual carbon goal acceleration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market