
 Rayon Fibers Market | 2026-2036
Rayon Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Rayon Fibers Market Intelligence
Traceability and sustainability certification as a value-added service is consolidating the definition of premium rayon fibers. This shift benefits specialized producers like Lenzing AG, which differentiates through branded, eco-responsible fibers. In contrast, Aditya Birla Group leverages its vast production capacity to serve high-volume segments. Sateri competes on manufacturing scale, particularly within the viscose staple fiber category, supplying major textile hubs.
Rayon fibers are semi-synthetic textiles produced from regenerated cellulose, most commonly sourced from wood pulp through processes like the viscose method. These fibers are engineered to create fabrics with desirable properties like softness and absorbency for the textile industry. While viscose rayon constitutes the largest product segment by volume, lyocell rayon is expanding rapidly due to its sustainable, closed-loop manufacturing. The apparel application dominates consumption, utilizing rayon for everything from dresses to linings.
Regulatory frameworks increasingly influence material choice and production methods. The EU Green Deal and its Corporate Sustainability Reporting Directive (CSRD) mandate greater transparency in supply chains. China's dual carbon goals pressure manufacturers to adopt cleaner technologies, while ISO standards set global benchmarks. Producers must now navigate the strategic trade-off between the cost-effectiveness of traditional viscose and the premium value of certified, sustainably sourced fibers.
Market Dynamics
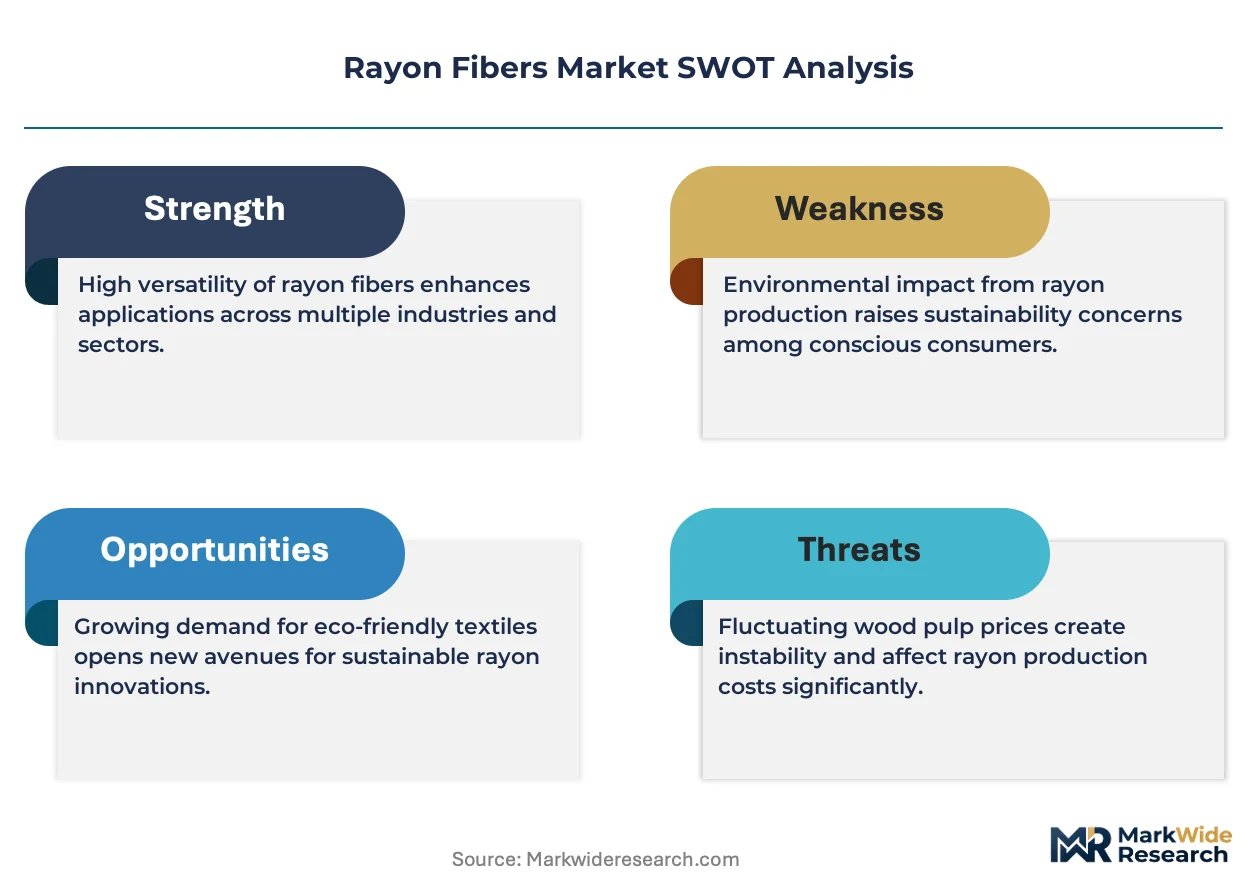
The central force shaping the rayon fibers market is the strategic tension between the scale economies of conventional viscose production and the premium value captured by certified, sustainable manufacturing processes. This dynamic is intensified by global regulatory pressures for supply chain transparency and circularity.
Growth Catalysts
- Apparel Sector Demand:The textile industry's continuous need for fabrics with softness, high absorbency, and a silk-like drape drives consumption in dresses, blouses, and activewear, sustaining baseline volume for rayon fibers.
- Circular Economy Policies:Regulatory frameworks like the EU Green Deal promote materials derived from renewable sources with end-of-life solutions, creating a favorable environment for cellulose-based fibers like rayon over petroleum-based synthetics.
- Lyocell Process Adoption:The expansion of lyocell production, a closed-loop process that recycles water and solvents, offers a sustainable alternative that commands a premium and meets growing consumer demand for eco-friendly textiles.
Market Restraints
- Input Cost Volatility:The market is sensitive to fluctuations in the price of wood pulp, its primary feedstock, which can compress producer margins and create price instability for textile manufacturers.
- Environmental Scrutiny:The traditional viscose process involves toxic chemicals like carbon disulfide, attracting stringent environmental regulations and negative perceptions that limit its application in eco-conscious segments.
- Threat from Alternative Fibers:Rayon faces persistent competition from natural fibers like cotton and linen, as well as from advanced synthetic fibers that offer comparable performance characteristics in specific technical applications.
Strategic Opportunities
- Non-Woven Applications:Expansion into the non-wovens sector presents a significant opportunity, particularly for use in disposable hygiene products like wipes, medical gowns, and filtration media, where absorbency is critical.
- Hybrid Fabric Development:Blending rayon with other fibers such as cotton, wool, or polyester creates hybrid textiles with enhanced durability, stretch, or texture, opening new niches in performance apparel and home furnishings.
- Geographic Market Penetration:There is untapped potential in emerging textile manufacturing hubs across Southeast Asia and Latin America, where local apparel industries are expanding and require a consistent supply of versatile fibers.
Industry Challenges
- Certification and Traceability Hurdles:Producers face the operational challenge of implementing and managing complex traceability systems to comply with multiple sustainability standards like FSC and PEFC for responsible sourcing.
- High Capital Expenditure:Transitioning from conventional viscose manufacturing to cleaner, closed-loop technologies like lyocell demands substantial capital investment in new equipment and plant retrofitting.
- Water Resource Management:The water-intensive nature of rayon production creates operational risks and regulatory compliance challenges for facilities located in regions facing water scarcity and stricter environmental controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rayon Fibers Market |
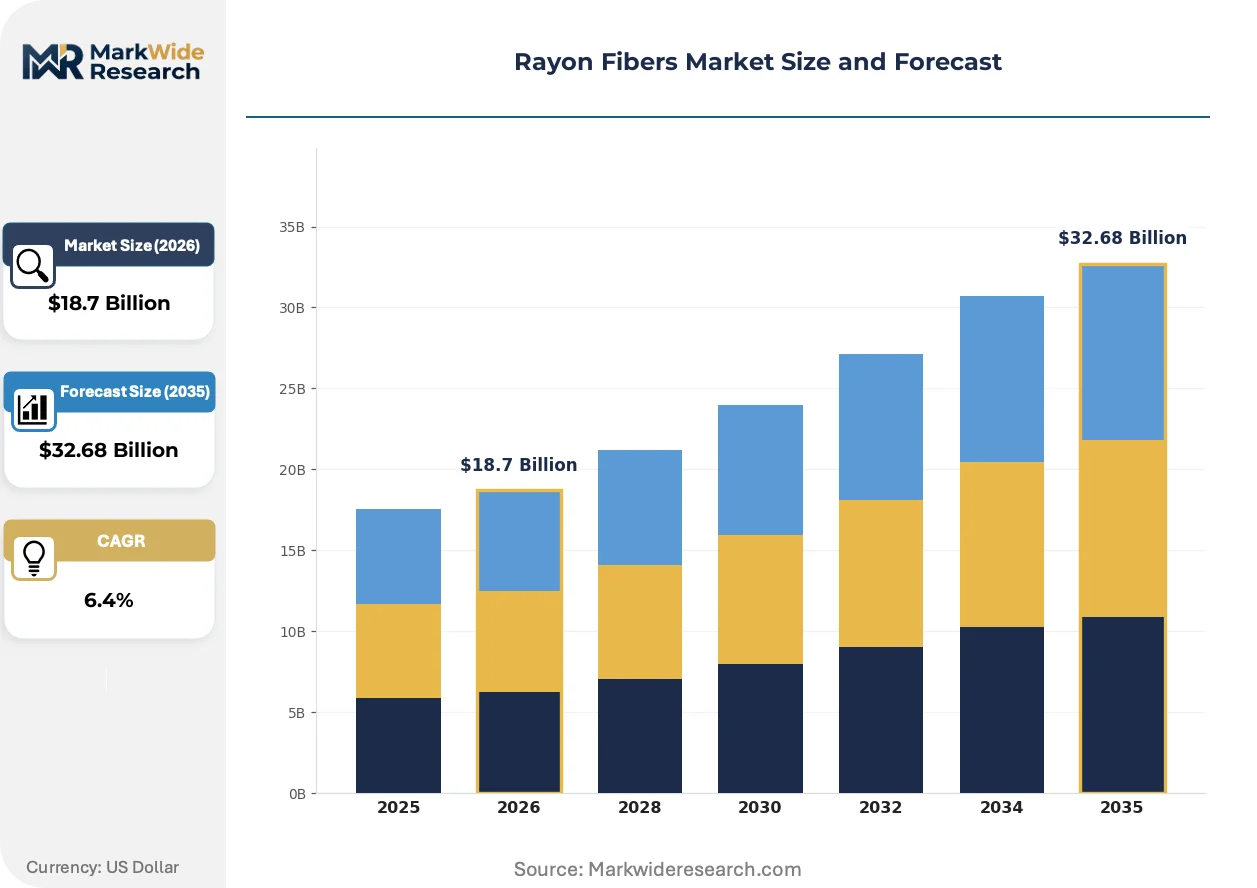
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscose Rayon, Modal Rayon, Lyocell Rayon, Cupro Rayon Application: Apparel, Home Textiles, Industrial Fabrics, Medical Textiles, Nonwovens End User Industry: Fashion Designers, Textile Manufacturers, Technical Textile Firms, Medical Suppliers Form: Staple Fiber, Filament Fiber, Tow, Yarn |
| Companies Covered | Sateri, Eastman Chemical Company, Lenzing AG, Zhejiang Fulida Holding Co., Ltd., Kelheim Fibres GmbH, Aditya Birla Group, Asia Pacific Rayon Limited, Toray Industries Inc., Grasim Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rayon Fibers Market Strategic Shifts & Innovations
Technological advancements in traceability are fundamentally altering supply chain accountability. The push for verifiable sustainability claims, driven by both regulatory mandates and consumer expectations, is compelling producers to adopt digital solutions that provide unprecedented transparency from forest to fabric.
Digital traceability platforms are being integrated into rayon supply chains to authenticate fiber origin and production methods. Apparel brands and environmentally conscious consumers are increasingly relying on these systems to validate the eco-credentials of finished garments. This technology is electrifying the value chain by forging a verifiable connection between raw material and retail product, which strengthens brand trust.
The European Union's Corporate Sustainability Reporting Directive (CSRD) imposes stringent disclosure requirements on supply chain impacts. This directive compels rayon manufacturers to establish comprehensive data-gathering processes covering their environmental and social footprint. Viscose staple fiber producers targeting the European market are most directly impacted, accelerating investments in cleaner production to ensure compliance.
A distinct behavioral shift is underway as textile buyers increasingly prioritize certified sustainable fibers over lower-cost, unverified alternatives. This trend disrupts traditional procurement models that were based purely on volume and price, creating a preference for suppliers holding credentials from bodies like the Forest Stewardship Council (FSC). This sourcing evolution is most visible within premium apparel and home textile segments in North America and Europe.
Rayon Fibers Market Segmentation
Understanding the rayon fibers market through segmentation reveals distinct value propositions and growth trajectories across various product forms and end-use sectors. Manufacturers tailor production processes and fiber characteristics to meet specific application requirements, influencing material selection in the global textile value chain. This granular view highlights areas of concentrated demand and emerging opportunities.
Product Type:
The market for rayon fibers demonstrates a clear differentiation between foundational material inputs and specialized performance enhancers.
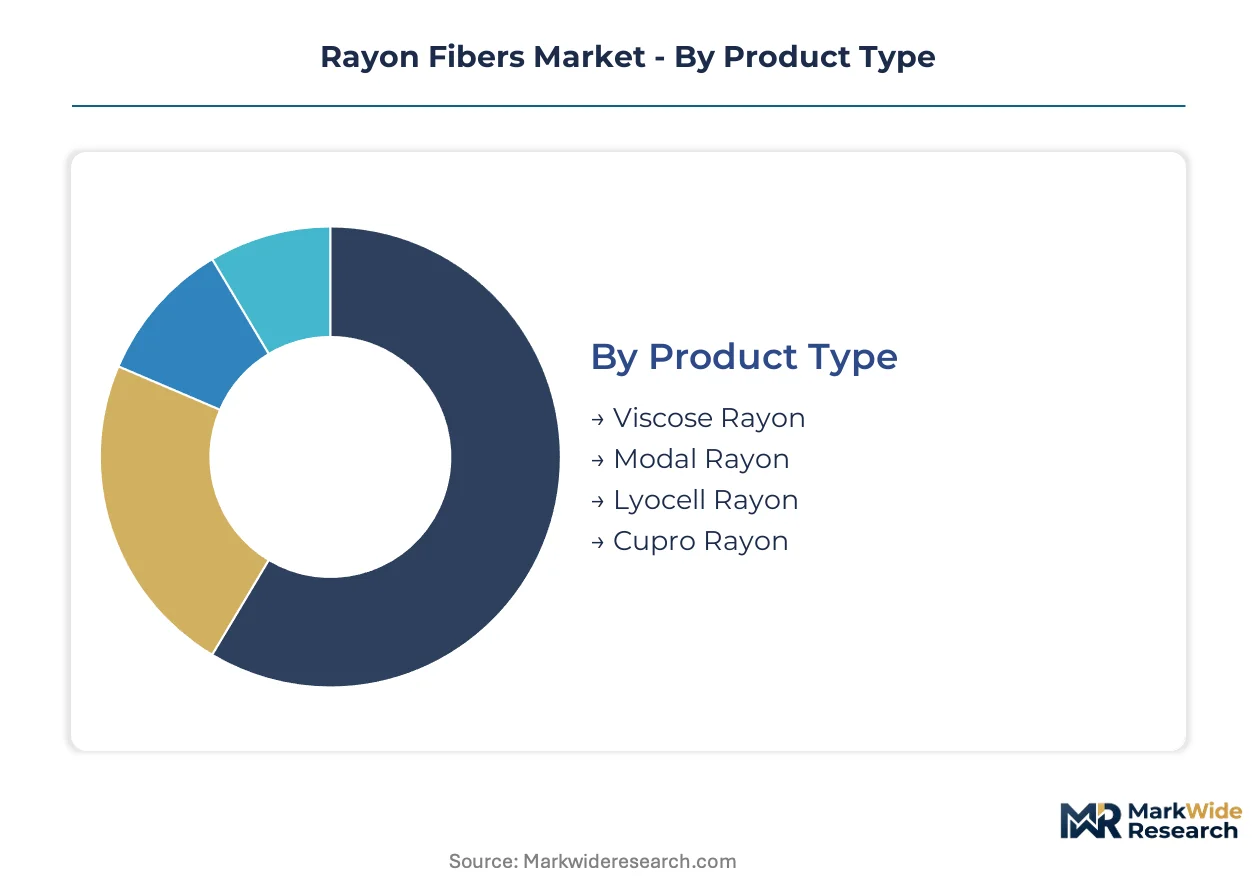
- Viscose Rayon:This regenerated cellulose fiber constitutes the largest product segment by volume, produced primarily through the traditional viscose method. Its widespread demand concentrates in the apparel sector due to its softness, absorbency, and silk-like drape, making it a staple for dresses and blouses.
- Lyocell Rayon:Engineered through a sustainable, closed-loop manufacturing process, lyocell offers high tenacity and excellent moisture management properties. Demand for this eco-friendly alternative is expanding rapidly in premium apparel and activewear segments, driven by consumer preference for sustainable textiles in North America and Europe.
- Modal Rayon:Known for its exceptional softness and resistance to shrinkage, modal rayon finds applications in intimate apparel and home textiles.
- Cupro Rayon:Produced from cotton linter, cupro rayon offers a luxurious feel and breathability, often used in linings and high-end fashion.
Volume placements concentrate in Viscose Rayon; the faster expansion belongs to Lyocell Rayon.
Application:
The consumption patterns within the rayon fibers market are dictated by the specific functional and aesthetic needs of various end-use industries, driving distinct volume and value contributions.
- Apparel:This segment dominates consumption, utilizing rayon for its desirable properties like softness, high absorbency, and elegant drape in clothing items. Demand is concentrated across Asia, particularly China, where large-scale textile manufacturing feeds global fashion markets.
- Nonwovens:Expansion into non-woven applications presents significant opportunities, particularly in disposable hygiene products, medical gowns, and wipes. The absorbency and biodegradability of rayon fibers make them suitable for these single-use items in healthcare and consumer goods.
- Home Textiles:Rayon fibers contribute to home furnishings such as bed linens, towels, and upholstery due to their comfort and aesthetic appeal.
- Industrial Fabrics:These applications include tire cords, conveyor belts, and filtration media, where rayon's strength and stability are utilized.
- Medical Textiles:Rayon is used in surgical dressings, bandages, and other medical disposables, valued for its absorbency and skin compatibility.
This segment's expansion depends on consumer preference for natural-feel fabrics; its constraint is competition from synthetic alternatives in performance applications.
End User Industry:
Different end-user industries exhibit distinct purchasing behaviors and material specifications, reflecting varying requirements for fiber properties and supply chain transparency.
- Textile Manufacturers:These firms represent the largest end-user group, processing rayon fibers into yarns and fabrics for diverse applications. Their procurement prioritizes consistent quality and scale economies, especially in major textile hubs like China and India.
- Fashion Designers:This segment increasingly demands certified, sustainably sourced rayon fibers for their collections, aligning with eco-conscious consumer trends. Their material choices influence premium brand positioning and consumer perception in North America and Europe.
- Technical Textile Firms:These users require specific performance characteristics from rayon, such as strength or absorbency, for specialized industrial and medical products.
- Medical Suppliers:Companies providing healthcare products utilize rayon for its hygiene, absorbency, and comfort in items like bandages and surgical drapes.
Profitability varies significantly, with Fashion Designers commanding higher margins due to demand for premium, certified fibers, while Textile Manufacturers compete primarily on scale.
Form:
The market for rayon fibers is structured by the physical form in which the fiber is supplied, impacting its processing and final application characteristics.
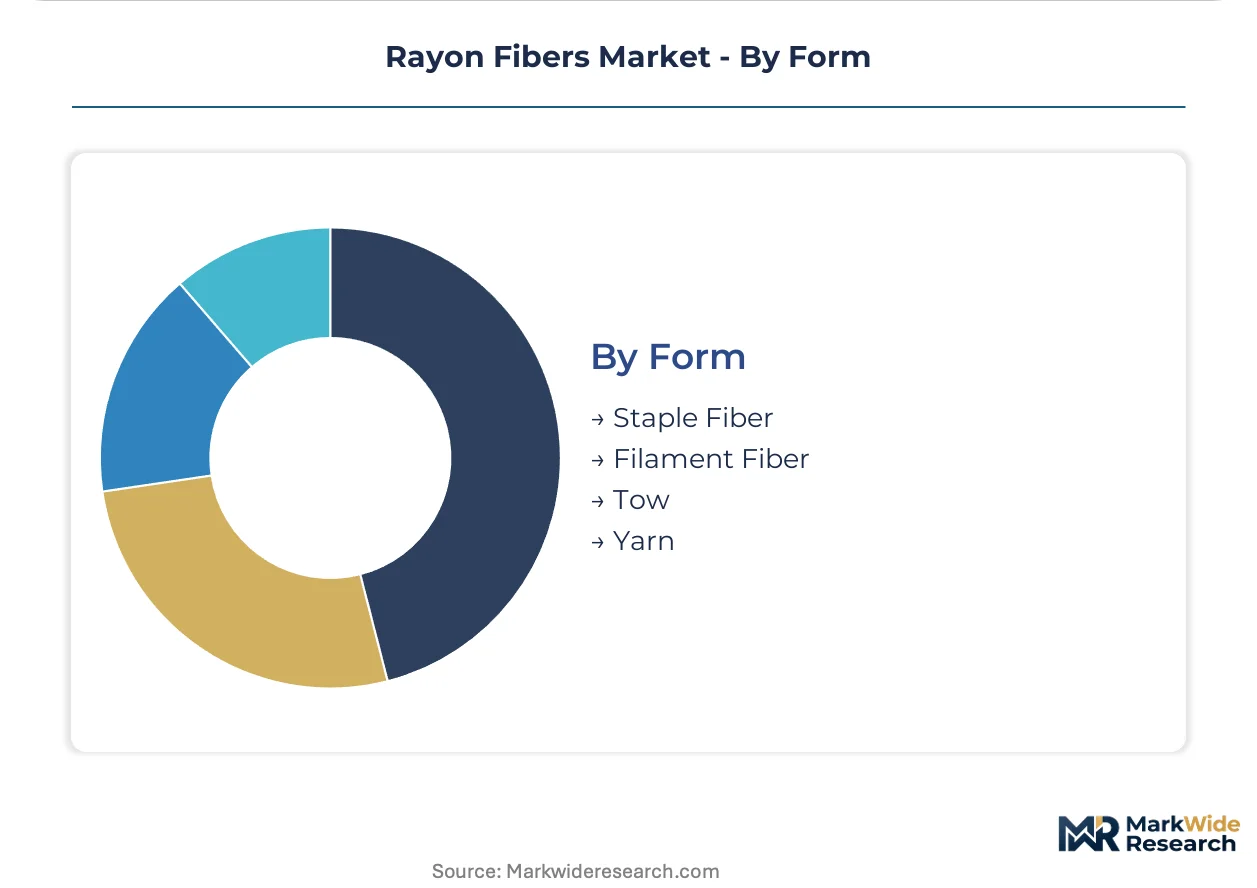
- Staple Fiber:This form consists of short, cut fibers, which are spun into yarns or used directly in non-woven applications. Viscose staple fiber constitutes a large volume segment, supplying textile manufacturers for apparel and home textiles globally.
- Filament Fiber:Comprising continuous, long strands, filament rayon offers a smooth, lustrous finish, often used for silk-like fabrics and linings. Its application is prominent in high-end apparel due to its drape and aesthetic qualities.
- Tow:This is a continuous bundle of parallel filaments, typically processed further into staple fibers or used in specific industrial applications.
- Yarn:Rayon yarns are ready-to-use threads, directly woven or knitted into fabrics, offering convenience to smaller textile producers.
The competitive landscape in this segment is shaped by processing technology; market leadership requires robust supply chain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global rayon fibers market exhibits a distinct divide between production centers and consumption hubs. Production often concentrates in regions with abundant wood pulp resources, while demand is heavily influenced by large-scale textile manufacturing industries. Regulatory landscapes significantly shape material sourcing and market penetration strategies across these diverse geographies.
China
China's vast textile manufacturing industry drives substantial demand for rayon fibers, particularly viscose rayon for apparel production. The government's dual carbon goals pressure manufacturers to adopt cleaner production technologies, influencing fiber sourcing decisions. Industrial clusters in provinces like Guangdong and Zhejiang represent major consumption points for both domestic and imported rayon fibers.
India
India's burgeoning textile sector, a significant global apparel producer, fuels consistent demand for rayon fibers due to their versatility and cost-effectiveness. The Production Linked Incentive (PLI) scheme for textiles encourages domestic manufacturing and value addition, impacting fiber procurement. Textile centers in Gujarat and Maharashtra are key areas for rayon fiber processing and consumption.
United States
Consumer preference for sustainable textiles and premium apparel drives demand for eco-friendly rayon variants, especially lyocell, in the United States. Regulatory trends emphasize supply chain transparency and product sustainability, influencing brand material choices. Fashion and textile innovation hubs in New York and Los Angeles increasingly seek certified and traceable rayon fibers.
Germany
Germany, a key European market, demonstrates strong demand for sustainable and certified rayon fibers, aligning with the EU Green Deal's objectives. The Corporate Sustainability Reporting Directive (CSRD) mandates greater transparency, pushing manufacturers towards cleaner production processes. Technical textile and apparel manufacturers in regions like Bavaria and North Rhine-Westphalia prioritize sustainably sourced materials.
Vietnam
Vietnam's growing role as a textile and apparel export hub generates increasing demand for versatile fibers like rayon. Its participation in various free trade agreements necessitates compliance with international environmental and social standards. Major textile and garment manufacturing zones around Ho Chi Minh City and Hanoi require a reliable supply of quality rayon fibers.
Rayon Fibers Market Key Industry Players
Top-tier vendors anchor the premium, certified segment, while scale-focused producers compete on volume and cost-efficiency. The market exhibits a tiered structure, with specialized players differentiating through sustainable processes and integrated fiber production. Strategic archetypes include large-scale commodity suppliers and niche innovators. Capacity expansion and strategic partnerships are dominant competitive moves.
On the premium-tier vector, Lenzing AG exemplifies the eco-responsible fiber segment, leveraging branded, sustainable offerings like TENCEL. Aditya Birla Group, a diversified conglomerate, represents the large-scale production archetype, serving high-volume textile segments globally. Sateri, a major viscose staple fiber producer, occupies a position focused on manufacturing scale, particularly for textile hubs. These firms navigate the market by balancing sustainable innovation with cost-effective volume supply.
| Leading Market Players |
|---|
| Sateri |
| Eastman Chemical Company |
| Lenzing AG |
| Zhejiang Fulida Holding Co., Ltd. |
| Kelheim Fibres GmbH |
| Aditya Birla Group |
| Asia Pacific Rayon Limited |
| Toray Industries Inc. |
| Grasim Industries Limited |
| Others |
Cost & Logistics Intelligence
Wood pulp commodity prices directly influence the cost structure of rayon fibers, cascading through the supply chain to establish distinct pricing tiers for viscose and lyocell products. This foundational input dictates margins for producers and affects final textile manufacturer procurement.
Pricing Analysis
Margin tightening in traditional viscose production reflects volatile wood pulp costs and intense competition from synthetic alternatives. Per-unit transactional pricing dominates the high-volume viscose segment, driven by scale economies. Price differentiation hinges on certification level, with FSC or PEFC-certified fibers commanding a premium. Textile manufacturers represent the most price-sensitive buyers for conventional rayon, while fashion designers prioritize certified, value-based offerings.
Supply Chain Analysis
Workforce availability in major textile manufacturing geographies like China and India underpins the rayon fiber supply chain. The supply chain concentrates heavily in Asia, particularly China, India, and Vietnam, drawing primarily from global wood pulp resources. Single-source vulnerability for specialized chemicals used in traditional viscose presents a structural risk. Distribution runs through established textile hubs, where large-scale manufacturers convert fibers into fabrics for global markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rayon fibers market increasingly operates as a cost-of-compliance story, where stringent environmental regulations like the EU Green Deal create a significant barrier-to-entry moat for non-compliant producers. This dynamic favors manufacturers investing in cleaner, closed-loop technologies.
For Market Incumbents:To counter environmental scrutiny and negative perceptions of traditional viscose, market incumbents must accelerate investment in sustainable production technologies. Capacity additions in lyocell manufacturing, particularly in Europe and North America, will capture premium demand. Robust traceability and sustainability certifications, like FSC, enhance brand value and secure market access. Strategic partnerships with apparel brands can lock in demand for certified fibers.
For New Entrants and Emerging Players:A price-point gap between premium lyocell and economy viscose offers an entry opportunity for new players with innovative, mid-tier sustainable offerings. Target the non-wovens sector, specifically disposable hygiene products, where absorbency and biodegradability are critical. A go-to-market angle focusing on verifiable eco-credentials and competitive pricing can attract value-driven buyers. Southeast Asia's expanding textile hubs represent a penetrable geographic segment.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized lyocell producers in Europe, particularly those with advanced closed-loop systems, offering long-term value in a sustainability-driven market. Long-term viability hinges on continuous innovation in eco-friendly processes and diversified feedstock. Acquisition targets include mid-sized firms with proprietary lyocell technology or strong regional supply chain integration. A signal to watch is enforcement of CSRD mandates across EU markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyocell Capacity Expansion | Increases supply of high-value, eco-friendly fibers for premium apparel markets. |
| Digital Traceability Platform Integration | Enhances supply chain transparency and compliance with regulations like CSRD. |
| Sustainable Wood Pulp Sourcing Partnerships | Secures feedstock from responsibly managed forests, supporting certification goals. |
| Non-Woven Product Development | Diversifies application portfolio into high-growth disposable hygiene and medical segments. |
| Hybrid Fabric R&D Collaboration | Creates new performance textiles by blending rayon with other advanced fibers. |
Research Approach
Multi-period observation of production volumes, pricing trends, and regulatory changes anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with textile manufacturing executives, sustainability directors, and material procurement managers. Secondary validation drew from corporate financial filings, customs trade data, and reports from textile industry associations. This approach combined bottom-up and top-down triangulation for comprehensive data integrity.
Segment-weighting across product types, applications, and end-user industries informed the quantitative forecast framework. The analysis modeled demand for viscose, lyocell, and modal rayon, projecting their adoption in apparel and non-woven applications. Compound Annual Growth Rates were derived from historical data and projected market dynamics over the analysis window. Key inputs included wood pulp supply forecasts and textile manufacturing capacity expansions.
Inputs from major rayon producers and textile industry bodies were available through the study window; gaps in emerging market consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and raw material supply. Geopolitical shifts or unforeseen technological breakthroughs represent material deviation triggers, warranting pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
High End Synthetic Suede Market