
 Textile Fabrics Market | 2026-2036
Textile Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Fabrics Market Outlook
Automotive interior buyers is collapsing as the dominant procurement archetype while medical and aerospace textile purchasers gain share. Toray Industries leverages its carbon fiber composite expertise to dominate technical fabric supply chains for mobility applications. DuPont sustains competitive positioning through aramid fiber specialization in protective textiles. BASF competes via polymer science leadership that anchors its position in high-performance synthetic substrates.
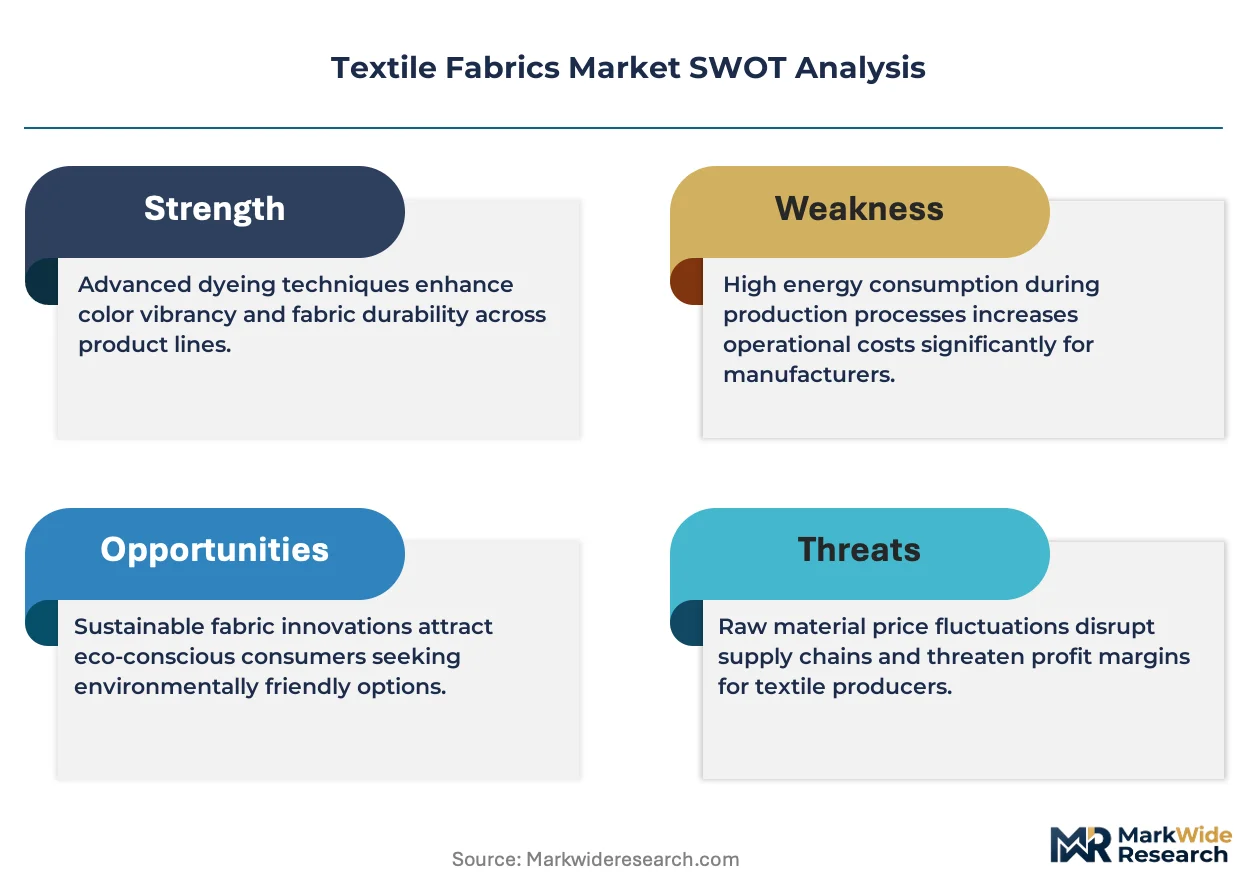
Textile fabrics are engineered sheet structures composed of interlaced, looped, or bonded fibers with specified tensile strength, elongation, and air permeability parameters, manufactured through weaving, knitting, or non-woven entanglement processes to deliver barrier, filtration, or structural functions across industrial and consumer applications. Polyester leads volume production due to cost scalability and chemical resistance, while non-woven forms capture the fastest expansion in disposable medical and filtration end-uses where meltblown microfiber architectures command premium margin pools. Cotton retains maturity in apparel applications but faces displacement in technical segments where woven glass and aramid composites deliver superior strength-to-weight ratios.
REACH in Europe restricts azo dyes and perfluorinated chemicals in textile finishing, forcing reformulation of water-repellent coatings and dyehouse chemistry across export-oriented supply chains. The EU Green Deal's extended producer responsibility mandates for textile waste are accelerating demand for recycled PET and closed-loop viscose systems that Lenzing AG and Eastman Chemical Company navigate through certified circular feedstock programs. Stakeholders must monitor how the EU AI Act's forthcoming requirements for automated visual inspection in manufacturing will reshape quality control capital deployment across fabric production networks.
Market Dynamics
REACH azo dye restrictions and EU Green Deal extended producer responsibility mandates are forcing simultaneous reformulation of finishing chemistry and investment in closed-loop recycling infrastructure across export-oriented supply chains.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards push OEMs toward carbon fiber-reinforced technical textiles for interior panels and structural components, creating sustained pull from Tier 1 suppliers.
- EU Green Deal circularity requirements:Extended producer responsibility for textile waste accelerates certified recycled PET and viscose demand, rewarding producers with Lenzing AG-style circular feedstock certification.
- Technical textile manufacturing corridors:Production gravity concentrates in India's Surat and Coimbatore clusters, where integrated spinning-weaving-finishing capabilities reduce lead times for medical and filtration grades.
Market Restraints
- Petrochemical input volatility:PTA and MEG feedstock price swings compress margin pools for polyester producers lacking backward integration into paraxylene supply.
- Aramid fiber supply concentration:DuPont and Teijin control dominant positions in meta-aramid and para-aramid staple, creating single-source risk for protective textile manufacturers.
- Fluorinated chemistry substitution timeline:PFAS restrictions under REACH and emerging US state-level bans force premature obsolescence of durable water-repellent finishes before bio-based alternatives achieve performance parity.
Strategic Opportunities
- India technical textile penetration:PLI scheme incentives for man-made fiber and technical textile investments create first-mover advantages for producers establishing Surat-Coimbatore corridor presence ahead of 2026-27 capacity ramp.
- Aerospace interior textiles:FAR 25.853 fire-smoke-toxicity certification requirements for cabin materials create premium margin pools for woven glass and phenolic composite suppliers serving Boeing and Airbus tier networks.
- Digital textile printing convergence:Reactive inkjet systems combined with AI-driven color matching reduce dyehouse water consumption and enable lot-size-one production for fashion-adjacent technical applications.
Industry Challenges
- Certification timeline compression:OEKO-TEX and bluesign audit backlogs extend qualification periods for new finishing chemistry, delaying product launches in seasonal automotive and apparel cycles.
- Meltblown microfiber equipment scarcity:Specialized extrusion and attenuation systems for medical-grade non-wovens face 18-24 month delivery lead times, constraining filtration capacity expansion.
- Cross-functional talent gaps:Hybrid polymer science-textile engineering expertise required for technical textile R&D remains concentrated in legacy industrial regions, limiting innovation velocity in emerging manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Fabrics Market |
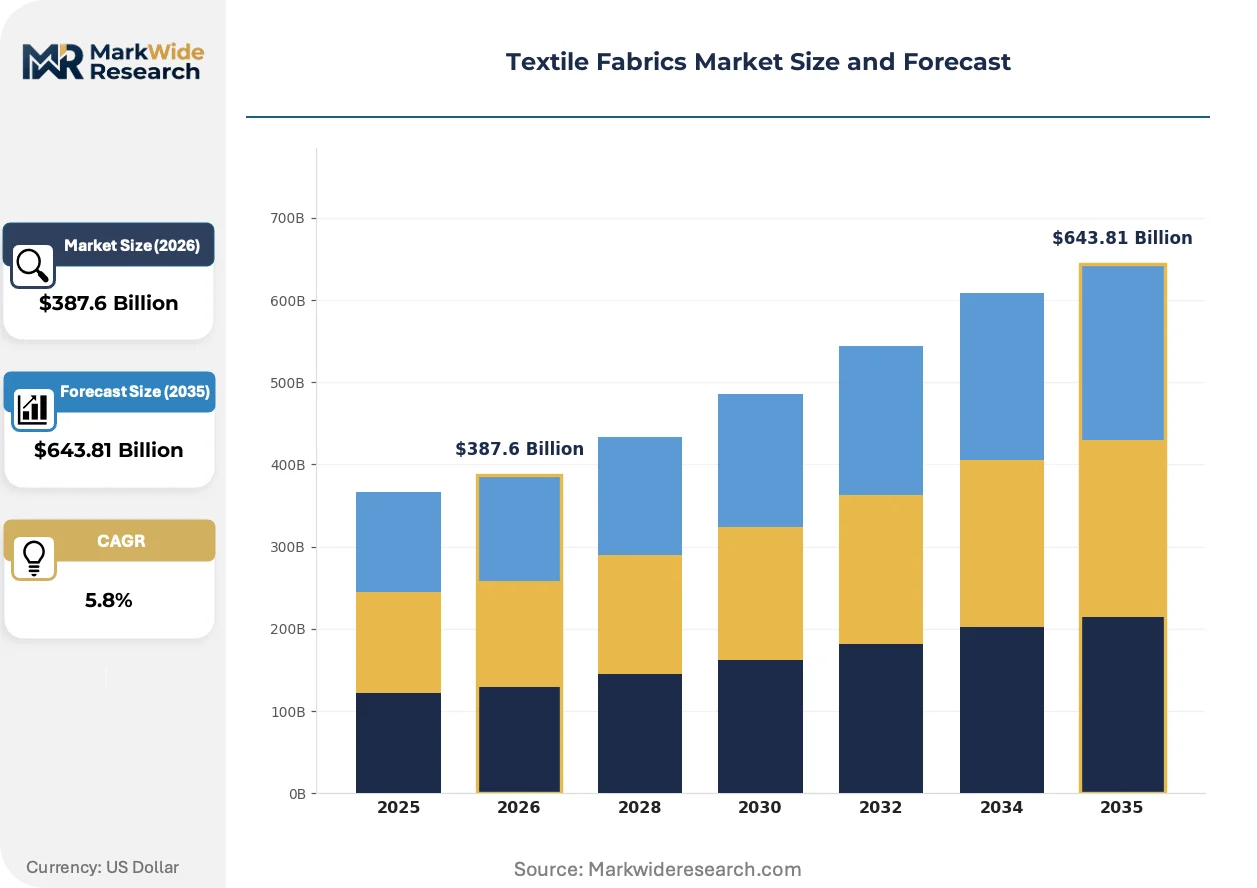
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Silk, Wool Application: Apparel, Upholstery, Industrial, Home Textiles Form: Woven, Knitted, Non-Woven, Composite End User: Fashion Designers, Manufacturers, Retailers, Consumers |
| Companies Covered | Toray Industries, DuPont, Berkshire Hathaway, BASF, Lenzing AG, Teijin Limited, Invista, Reliance Industries, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Fabrics Market Strategic Shifts
Bio-based polymer feedstocks, digital manufacturing integration, and regulatory-driven material substitution are compressing traditional competitive advantages while opening new value capture mechanisms across the value chain.
Polylactic acid fiber is supplanting conventional polyester in disposable medical non-wovens where compostability certifications command procurement preference. European hospital systems and Japanese healthcare distributors specify PLA-based surgical drapes and gowns to meet internal sustainability targets. This substitution is compressing virgin PET demand in single-use applications while requiring producers to rebuild melt-processing expertise around lower thermal stability biopolymers.
REACH perfluorinated chemical restrictions are eliminating C6 and C8 fluorocarbon water-repellent treatments from outdoor and protective textile specifications. Finish houses reformulate with silicone, paraffin, and dendrimer-based alternatives that sacrifice durability for regulatory compliance. German and Scandinavian workwear brands face the steepest reformulation curves as their domestic markets enforce the strictest PFAS enforcement timelines.
Automotive interior buyers now specify recycled content thresholds and carbon footprint documentation alongside traditional performance metrics. Tier 1 seating and trim suppliers source woven and knit fabrics through certified circular feedstock programs rather than spot commodity markets. This preference shift is most visible in German OEM supply chains, where BMW and Mercedes-Benz sustainability scorecards determine supplier qualification status independent of unit pricing.
Textile Fabrics Market Segmentation
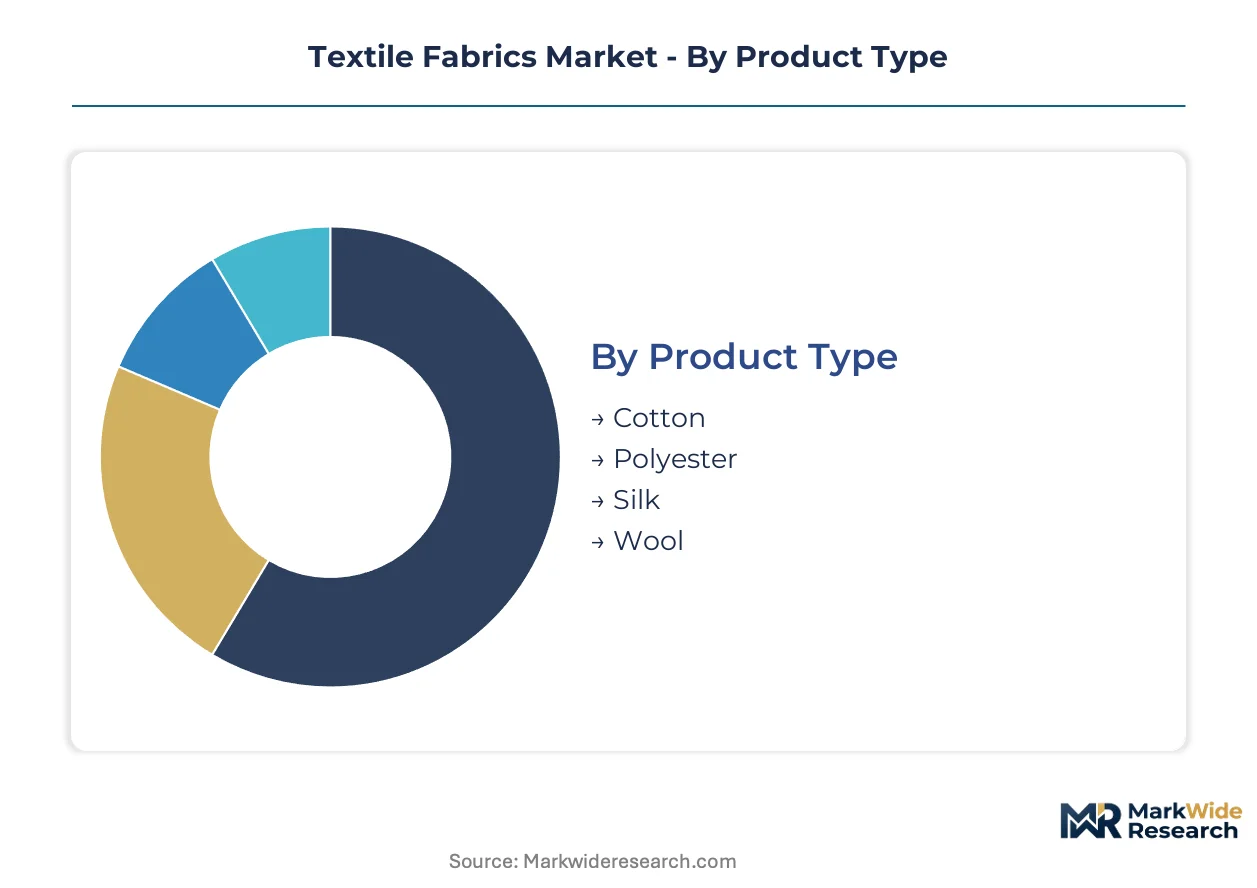
Segmentation in textile fabrics separates commodity-grade volume plays from specialized technical applications where certification and performance specifications command pricing power. Channel strategy diverges sharply across these boundaries, with spot-market distributors handling bulk polyester while direct mill relationships dominate aerospace and medical grades.
Product Type:
Polyester and cotton dominate spot-market procurement through commodity distributors, while silk and wool flow through specialty agents serving premium apparel houses.
- Polyester:Thermoplastic polymer fiber manufactured through melt-spinning of PTA and MEG precursors, delivering chemical resistance and dimensional stability. Demand concentrates in India's Surat corridor for automotive interior and filtration substrates, driven by cost scalability and backward integration into petrochemical feedstock. REACH azo dye restrictions are forcing reformulation of disperse dye chemistry across export-oriented supply chains.
- Cotton:Natural cellulose staple fiber with moisture absorption and breathability specifications. Demand centers on Bangladesh and Vietnam garment manufacturing for mass-market apparel, constrained by water-intensive cultivation and EU Green Deal due diligence requirements on agricultural sourcing.
- Silk:Protein fiber extruded by Bombyx mori larvae, characterized by triangular prism structure producing distinctive luster. Italian and Japanese weaving houses maintain captive supply relationships with sericulture cooperatives.
- Wool:Keratin-based animal fiber with natural crimp and flame resistance. Australian Merino grades supply European technical felting and luxury outerwear markets through auction-based procurement.
By volume, polyester leads. By growth pace, wool technical grades for filtration and acoustic insulation are climbing the fastest.
Application:
Cost tier stratification separates disposable medical non-wovens from capital-intensive aerospace composites, with upholstery and home textiles occupying mid-tier contract manufacturing channels.
- Apparel:Cut-and-sew garment construction spanning fast fashion through luxury ready-to-wear. Bangladesh and Vietnam cut-make-trim contractors source woven and knit substrates through volume tender processes, with sustainability scorecards displacing pure unit-cost procurement in German OEM supply chains.
- Upholstery:Heavy-duty woven and coated fabrics for residential, commercial, and transportation seating. North Carolina and Turkey mill networks supply North American furniture manufacturers through just-in-time programs.
- Industrial:Technical textiles for filtration, geotextiles, and protective applications. Meltblown microfiber architectures for medical filtration command premium margin pools.
- Home Textiles:Bedding, window treatments, and decorative woven goods. Portuguese and Pakistani towel manufacturers compete on terry-loop construction density and OEKO-TEX certification tiers.
By volume, apparel leads. By margin expansion, industrial technical grades are gaining share fastest.
Form:
Customer type determines form selection, with automotive Tier 1s specifying woven composites while hospital procurement favors non-woven disposables.
- Woven:Interlaced warp and weft yarn structures delivering dimensional stability and tensile strength. Germany's KBA-regulated automotive suppliers specify woven glass and aramid composites for interior panels.
- Knitted:Loop-structured fabrics with stretch recovery characteristics. Sri Lankan and Indonesian mills supply seamless garment producers through circular knitting technology.
- Non-Woven:Fiber-entangled sheet structures produced through mechanical, thermal, or chemical bonding. Medical-grade meltblown capacity expansion faces 18-24 month equipment lead times.
- Composite:Multi-layer engineered structures combining textile substrates with polymer matrices. Toray Industries dominates carbon fiber-reinforced technical fabric supply chains for mobility applications.
By volume, woven leads. By growth pace, composite structures for lightweighting applications show steepest expansion trajectory.
End User:
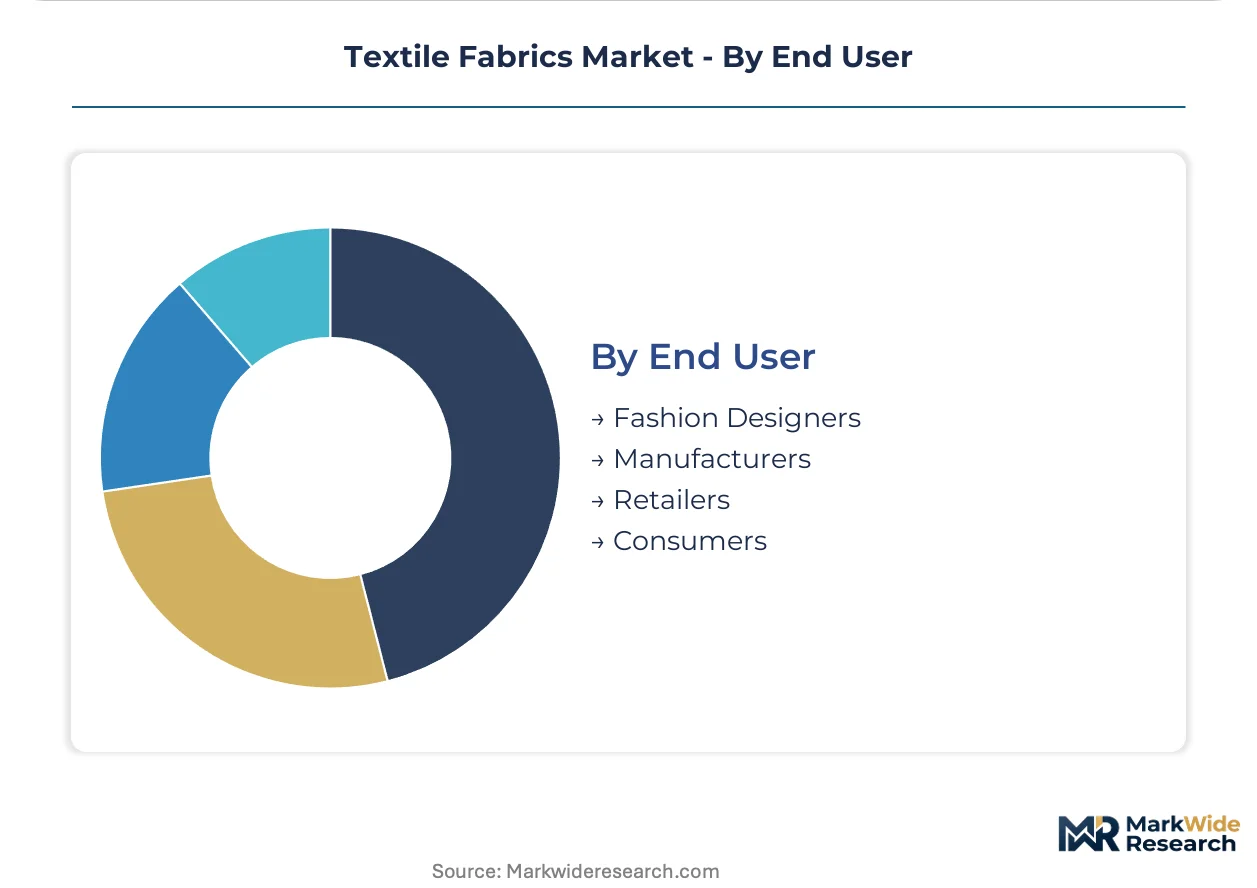
Supply concentration varies by buyer sophistication, with fashion designers accessing mill-direct programs while consumers purchase through retail intermediaries.
- Fashion Designers:Creative directors specifying custom-developed fabrics through mill-direct relationships. Milan and Paris houses maintain exclusive development partnerships with Italian and Japanese specialty weavers.
- Manufacturers:Cut-make-trim contractors and finished goods producers. Coimbatore's integrated spinning-weaving-finishing corridor reduces lead times for medical and filtration grade procurement.
- Retailers:Private label and branded apparel merchants. Inditex and H&M sustainability compliance requirements are reshaping supplier qualification standards.
- Consumers:Individual purchasers through e-commerce and brick-and-mortar channels. Direct-to-consumer technical textile penetration remains limited to outdoor and performance apparel niches.
By volume, manufacturers lead procurement. By influence over specification, fashion designers are expanding their sourcing leverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester capacity clusters in India, China, and Germany anchor the supply base for technical textile feedstocks. Regulatory divergence across REACH, India's PLI scheme, and China's dual carbon goals is fragmenting certification requirements. Automotive and medical procurement is pulling capacity toward Surat, Shanghai, and Stuttgart corridor networks.
India
Man-made fiber production is accelerating under PLI scheme incentives for technical textile investments. BIS certification mandates for protective textiles are tightening quality thresholds for export-bound supply chains. Surat and Coimbatore manufacturing corridors concentrate integrated spinning-weaving-finishing capabilities for medical and filtration grades.
China
Dual carbon goals are pressuring polyester producers to decarbonize PTA and MEG feedstock processing. MIIT standards for recycled fiber content in industrial textiles are accelerating closed-loop system adoption. Yangtze River Delta chemical fiber clusters are retrofitting melt-spinning lines for bio-based polymer compatibility.
Germany
KBA automotive safety regulations are mandating fire-smoke-toxicity certification for interior textile suppliers. REACH perfluorinated chemical bans are forcing water-repellent finish reformulation across technical fabric producers. Stuttgart and Munich industrial basins concentrate carbon fiber composite weaving for mobility applications.
United States
NHTSA fuel economy standards are driving carbon fiber-reinforced textile adoption for automotive lightweighting. EPA PFAS restrictions are overlapping with state-level bans to accelerate fluorinated chemistry substitution timelines. North Carolina upholstery mills are pivoting toward aerospace certification programs for cabin interior supply.
Japan
METI carbon neutrality roadmaps are targeting synthetic fiber production emissions for 2030 reduction commitments. JIS standards for high-performance industrial textiles are setting baseline specifications for export markets. Osaka and Nagoya technical textile R&D clusters are concentrating hybrid polymer-fiber engineering expertise.
Textile Fabrics Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized fiber producers that control proprietary polymer platforms. The vendor base splits between integrated petrochemical-textile hybrids and focused technical textile specialists. Three archetypes dominate: carbon fiber composite leaders, aramid fiber specialists, and circular feedstock certifiers. Competitive moves center on backward integration into paraxylene and bio-based feedstocks, plus strategic partnerships with automotive Tier 1 seating suppliers.
Within the diversified chemical conglomerate tier, Toray Industries, DuPont, and BASF exemplify distinct competitive positioning. Toray anchors the carbon fiber-reinforced technical fabric segment through composite expertise applied to mobility applications. DuPont occupies the protective textiles vector via aramid fiber specialization that commands premium positioning in safety-critical end-uses. BASF sits within the polymer science leadership archetype, leveraging high-performance synthetic substrate capabilities across industrial filtration and automotive interior supply chains.
| Leading Market Players |
|---|
| Toray Industries |
| DuPont |
| Berkshire Hathaway |
| BASF |
| Lenzing AG |
| Teijin Limited |
| Invista |
| Reliance Industries |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month equipment lead times for meltblown microfiber extrusion systems concentrate pricing power among incumbent non-woven producers with installed capacity, while polyester spot markets fragment bargaining leverage across India's Surat corridor buyers lacking backward integration into paraxylene supply.
Pricing Analysis
REACH azo dye and PFAS restrictions dictate the pricing tier structure across European export supply chains, separating OEKO-TEX certified premium grades from uncertified commodity lots. Three-tier pricing structure across premium certification, standard compliance, and economy spot tiers reflects audit backlog delays and reformulation cost pass-through. Cost compression in water-repellent finishing tiers is intensifying because silicone and paraffin alternatives trade durability for regulatory compliance. Hospital procurement committees exhibit lowest price sensitivity due to compostability certification requirements, while Bangladesh garment contractors face acute margin pressure from EU Green Deal due diligence mandates.
Supply Chain Analysis
Just-in-time programs dominate automotive Tier 1 upholstery procurement, while medical filtration buyers maintain strategic stockpiles against meltblown equipment scarcity. Supply concentrates in India, China, and Germany, with PTA and MEG petrochemical feedstocks anchoring polyester cost structures. Raw material flows draw from paraxylene crackers, bio-based PLA fermentation capacity, and aramid polymer synthesis. Single-source vulnerability sits with DuPont and Teijin para-aramid staple control. Distribution runs through certified circular feedstock programs for German OEM sustainability scorecards and spot commodity distributors for Bangladesh apparel contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical textile platforms are consolidating around circular feedstock certification interoperability, with Lenzing AG-style closed-loop viscose systems and recycled PET traceability becoming the dominant ecosystem architecture for supplier qualification.
For Market Incumbents: Secure backward integration into bio-based polymer feedstocks and captive paraxylene supply to defend margin pools against PTA price volatility. Reinforce certification investment in bluesign and OEKO-TEX tiers to maintain premium positioning as REACH restrictions eliminate fluorinated chemistry alternatives. Channel control through direct mill relationships with BMW and Mercedes-Benz Tier 1 networks protects against spot-market price erosion. For New Entrants and Emerging Players: Differentiate on PLA-based compostable medical non-wovens where European hospital sustainability targets create procurement preference. Target India's Surat-Coimbatore technical textile corridor ahead of PLI scheme capacity ramp, leveraging integrated spinning-weaving-finishing capabilities to compress lead times for filtration grades. Go-to-market through certified circular feedstock partnerships rather than commodity spot channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded carbon fiber composite assets lacking automotive lightweighting platform alignment. Five-to-ten year viability hinges on polymer science R&D pipelines and backward integration depth. Watch for BIS certification mandate tightening in India as inflection signal for quality-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures margin protection against petrochemical volatility and REACH compliance cost pass-through. |
| Certified Circular Feedstock Program Expansion | Unlocks BMW and Mercedes-Benz supplier qualification independent of unit pricing pressure. |
| Meltblown Microfiber Capacity Addition | Captures medical filtration premium pools constrained by 18-24 month equipment delivery timelines. |
| PLA Fiber Processing Expertise Buildout | Positions for European hospital compostability procurement preferences displacing virgin PET. |
| Joint Venture with Automotive Tier 1 Seating Suppliers | Locks in long-term offtake for carbon fiber-reinforced technical fabric lightweighting programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and BIS certification registries. Primary interviews engaged technical textile plant managers, automotive Tier 1 procurement leads, hospital purchasing committee directors, and distribution channel partners across India's Surat corridor and Germany's Stuttgart basin. Secondary validation drew from ECHA REACH substance restrictions, EU Green Deal extended producer responsibility documentation, and MIIT recycled fiber content standards. Bottom-up capacity modeling triangulated against top-down demand segmentation across automotive, medical, and filtration end-uses.
Segmentation dimensions modeled include fiber type, application grade, form structure, and end-user procurement sophistication across the projection horizon. CAGRs derived from volume-weighted growth assumptions anchored in NHTSA fuel economy standard compliance timelines and EU circularity mandate phase-ins. Industry-specific forecast inputs incorporated PLI scheme incentive disbursement schedules and meltblown equipment order backlogs.
Material uncertainties — PTA-MEG feedstock price swings, PFAS substitution timeline delays, and BIS audit backlog extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and polymer processing technology maturation. Revision becomes warranted when bio-based PLA thermal stability performance crosses parity thresholds with conventional polyester.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market