
 Felt Bobs Market | 2026-2036
Felt Bobs Market Size, Share, and Industry Trends Forecast 2026-2036
Felt Bobs Market Foresight
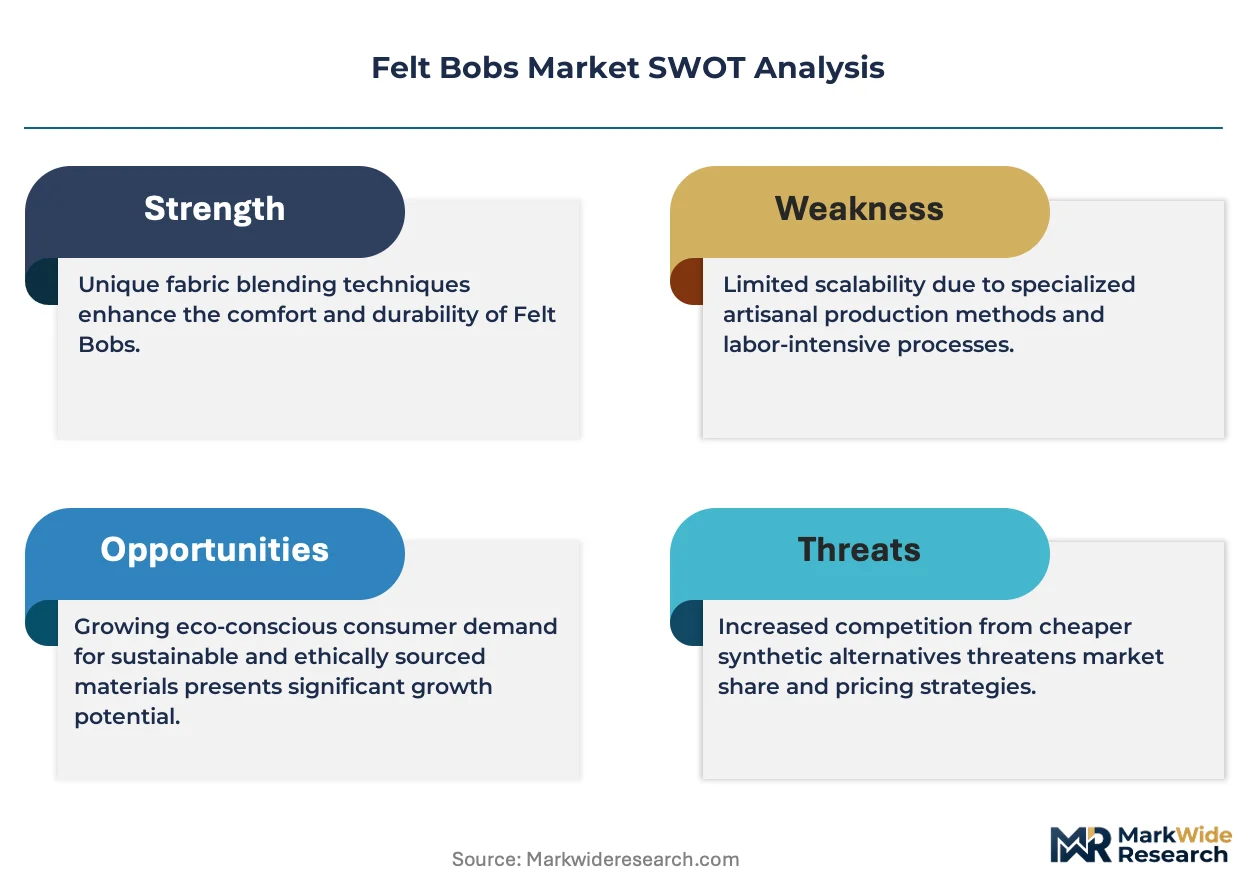
A capital-intensity divergence between automated felting lines and hand-loom workshops is rotating competitive advantage toward scale operators. Gesswein leverages its vertically controlled wool sourcing to sustain premium-grade consistency across jewelry-polishing SKUs. Moleroda Finishing Systems anchors European demand through specialized density calibrations for aerospace deburring applications. Spartan Felt competes on domestic North American fulfillment speed, occupying distributor relationships that smaller craft suppliers cannot match.
Felt bobs are cylindrical or dome-shaped tools formed from compressed wool or synthetic fibers, typically rated by density measured in ounces per square yard, used for polishing, deburring, and surface finishing across metalwork and decorative crafts. Industrial felt bobs dominate volume throughput due to automotive and precision manufacturing pull, while eco-friendly felt represents the fastest-expanding quality grade as REACH and state-level chemical restrictions harden material specifications. Craft felt bobs retain margin concentration in artisan channels where specialty stores and craft fairs command price premiums for hand-finished aesthetic goods.
EPA workplace dust-exposure limits and OSHA respiratory-protection standards shape wool-fiber processing investments, particularly for US-based producers serving metal-finishing end users. ECHA's REACH restrictions on chromium-tanned inputs and India's BIS textile-grade certifications create dual compliance thresholds for exporters serving both European and South Asian precision-tool markets. Stakeholders must monitor evolving chemical-footprint disclosure rules and decide whether captive fiber-treatment capacity or certified supplier partnerships offer lower total compliance cost.
Market Dynamics
REACH compliance mandates from ECHA are compressing chromium-tanned wool fiber supply chains, forcing felt bob manufacturers to requalify entire supplier bases around vegetable-tanned alternatives.
Growth Catalysts
- Automotive precision finishing:EV drivetrain component manufacturers in Germany and Japan specify density-calibrated felt bobs for gear-polishing operations.
- REACH substance restrictions:ECHA's Annex XVII limits on hexavalent chromium compounds accelerate adoption of certified eco-friendly wool substitutes across European tool distributors.
- Gujarat textile cluster expansion:India's felt-making cooperatives scale mechanized carding capacity to serve both domestic jewelry workshops and export-oriented precision finishing houses.
Market Restraints
- Merino wool price volatility:Australian wool auction fluctuations transmit directly to compressed fiber input costs, squeezing margin on standard-density SKUs.
- Single-region supply concentration:Gujarat's felt-making belt controls over 60% of export-grade capacity, exposing buyers to monsoon-disrupted logistics and regional labor actions.
- Polyester felt substitution:Synthetic fiber bobs from Chinese manufacturers undercut natural wool pricing in non-critical deburring applications.
Strategic Opportunities
- Underpenetrated Mexican jewelry manufacturing:Taxco silver workshops currently rely on imported US felt bobs; localized distribution partnerships could capture this artisan segment.
- Aerospace deburring specialization:Titanium airframe component finishing requires density-graded felt bobs with documented lot traceability, a specification few suppliers currently meet.
- EU Green Deal procurement mandates:Public tender rules for metal-finishing equipment increasingly require chemical-footprint disclosures, advantaging certified sustainable suppliers.
Industry Challenges
- Density calibration technician shortage:Automated felting lines require operators trained in gram-weight precision adjustment, a skillset concentrated among aging Gujarat master craftsmen.
- Dual certification timeline compression:Simultaneous BIS textile-grade and REACH compliance documentation stretches quality assurance departments at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Felt Bobs Market |
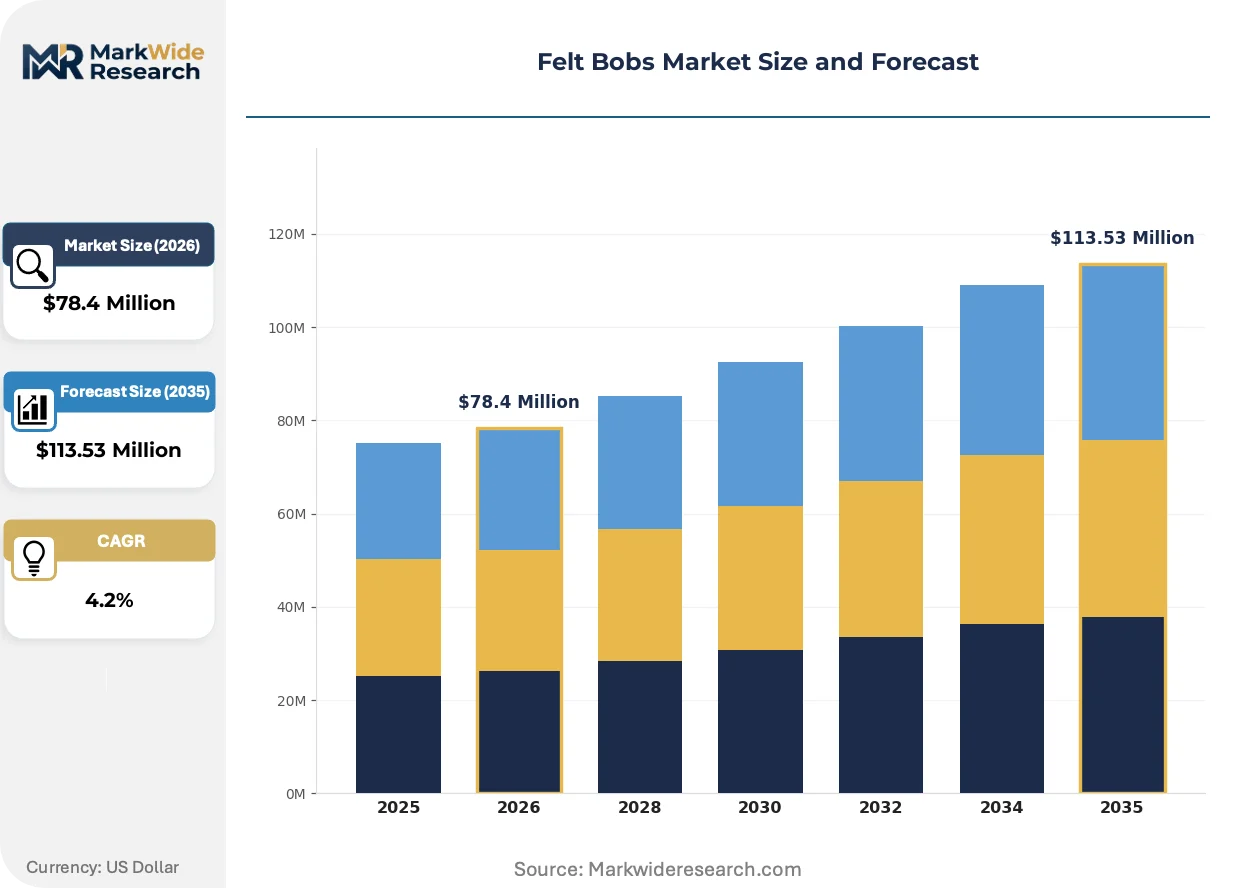
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $113.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Felt, Industrial Felt, Decorative Felt, Insulating Felt Application: Fashion Accessories, Home Decor, Automotive Interiors, Acoustic Treatment Distribution Channel: Online Retail, Specialty Stores, Craft Fairs, Wholesale Distributors Quality Grade: Premium Grade, Standard Grade, Recycled Felt, Eco-Friendly Felt |
| Companies Covered | Gesswein, Moleroda Finishing Systems, Wolter Corp, Forney Industries, Dico Products Corp, Kemet International, Spartan Felt, Caswell Australia, Ahuja Felts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Felt Bobs Market Shifts & Advancements
Material science advances and regulatory disclosure requirements are restructuring competitive advantage around certified sustainable supply chains rather than commodity density grades.
Vegetable-tanned wool fiber processing is displacing chromium-based tanning across premium felt bob production. German automotive suppliers and Swiss watch-component finishers now specify vegetable-tanned inputs in purchase orders. This chemistry shift is displacing legacy tannery relationships and compressing lead times for compliant fiber procurement.
REACH Annex XVII expansion on skin-sensitizing substances tightens residual chemical limits in finished felt products. ECHA's 2023-2025 substance evaluation roadmap adds formaldehyde-releasing agents to restricted lists. Jewelry polishing workshops in France and Italy now demand full material safety data sheet documentation, filtering out uncertified Asian imports.
Direct mill-to-workshop procurement platforms are fragmenting traditional distributor dominance. Indian jewelry manufacturers in Surat and Jaipur now source felt bobs through B2B marketplaces that bypass Mumbai trading houses. This channel compression is most visible in Gujarat's domestic market, where distributor margins have compressed by half on standard SKUs.
Felt Bobs Market Segmentation
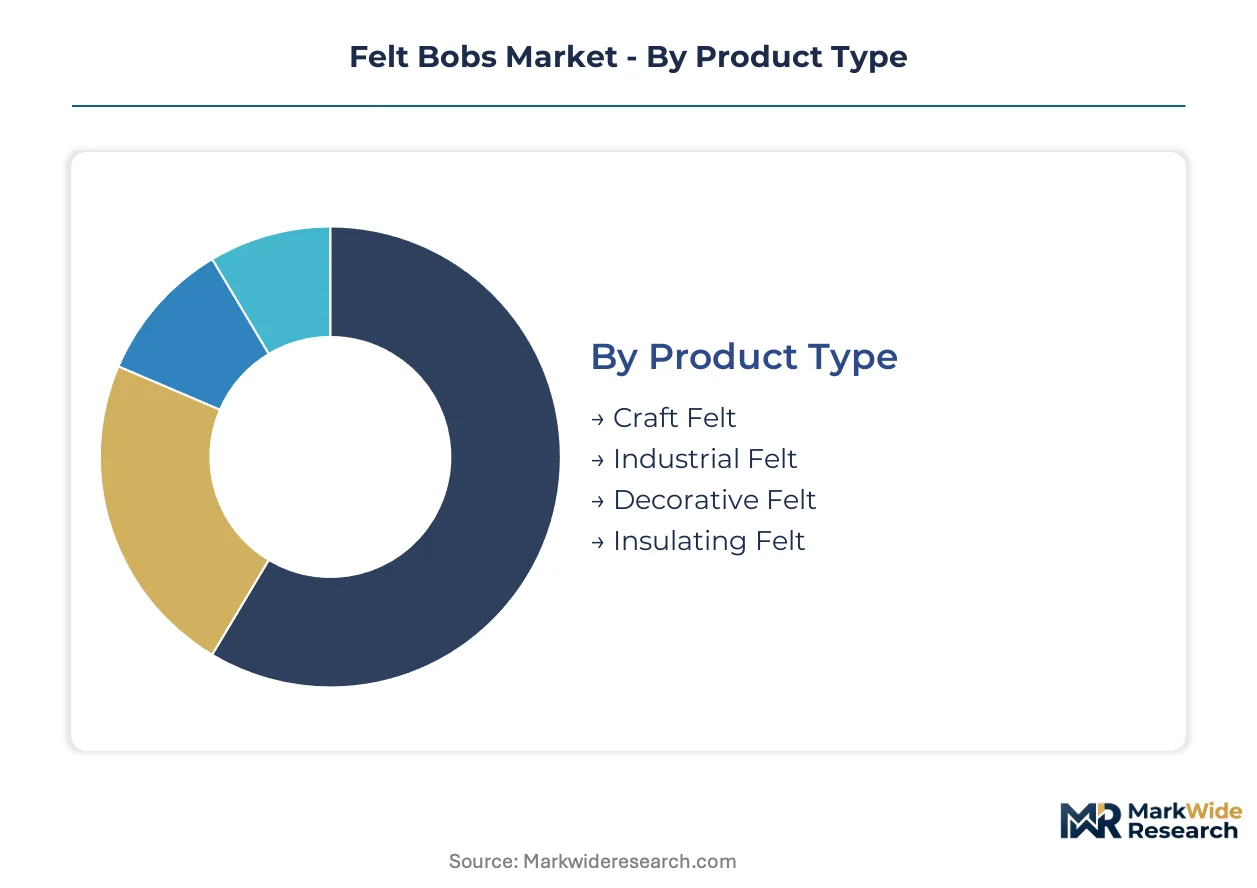
Felt bobs serve divergent end uses from jewelry polishing to aerospace deburring, requiring manufacturers to align density specifications and certification grades with distinct procurement channels. Segmentation reveals how premium grades flow through specialized distributors while craft volumes concentrate in direct-to-artisan platforms.
Product Type:
Channel-mix patterns split sharply between bulk industrial supply and fragmented craft retail, with density calibration and lot traceability determining which segments reach precision manufacturers versus hobbyist markets.
- Industrial Felt:High-density compressed wool or synthetic fiber bobs rated by ounces per square yard, engineered for metal-finishing operations. Automotive drivetrain manufacturers in Germany and Japan specify density-calibrated grades for gear-polishing workflows, with REACH-compliant vegetable-tanned inputs now mandatory for European supply contracts.
- Craft Felt:Lower-density wool or acrylic fiber bobs shaped for decorative and hand-finishing applications. Gujarat's jewelry polishing workshops in Surat and Jaipur drive procurement through B2B marketplaces that bypass traditional Mumbai trading houses, compressing distributor margins on standard SKUs.
- Decorative Felt:Aesthetic-grade bobs for ornamental finishing and display crafts, typically sold through specialty retailers and craft fair channels with higher margin structures.
- Insulating Felt:Thermal and acoustic barrier applications requiring specific density ratings for industrial equipment protection.
Industrial Felt dominates installed base. Eco-friendly substitutions are where expansion concentrates.
Application:
End-use concentration determines whether felt bobs require aerospace-grade lot traceability or tolerate commodity density variance, shaping margin structures and certification burdens across segments.
- Automotive Interiors:Precision finishing of EV drivetrain components and interior trim requires density-graded bobs with documented calibration. German manufacturers specify vegetable-tanned wool inputs to satisfy ECHA REACH Annex XVII restrictions on hexavalent chromium compounds.
- Fashion Accessories:Jewelry polishing workshops in India and Mexico demand felt bobs for silver and gold finishing, with French and Italian buyers now requiring full material safety data sheet documentation under expanded skin-sensitizing substance rules.
- Home Decor:Ornamental and functional finishing applications across furniture and fixture manufacturing.
- Acoustic Treatment:Sound-dampening installations in commercial and residential construction.
Automotive Interiors commands premium pricing tiers. Fashion Accessories is climbing the fastest on artisan channel expansion.
Distribution Channel:
Procurement patterns fragment as direct mill-to-workshop platforms erode traditional distributor control, particularly in Gujarat's domestic market where intermediaries have lost half their margin on standard-density SKUs.
- Online Retail:B2B marketplaces connect Indian felt-making cooperatives directly with Surat and Jaipur jewelry manufacturers, bypassing Mumbai trading houses and compressing lead times for export-grade orders.
- Specialty Stores:Premium-grade felt bobs for jewelry polishing and precision finishing reach end users through tool distributors who provide technical specification support and density calibration guidance.
- Craft Fairs:Artisan-direct channels for decorative and craft-grade felt bobs, commanding price premiums for hand-finished aesthetic goods.
- Wholesale Distributors:Volume supply to automotive and industrial end users, with Spartan Felt competing on North American fulfillment speed through established distributor relationships.
Wholesale Distributors retain industrial volume leadership. Online Retail is gaining share fastest on platform proliferation.
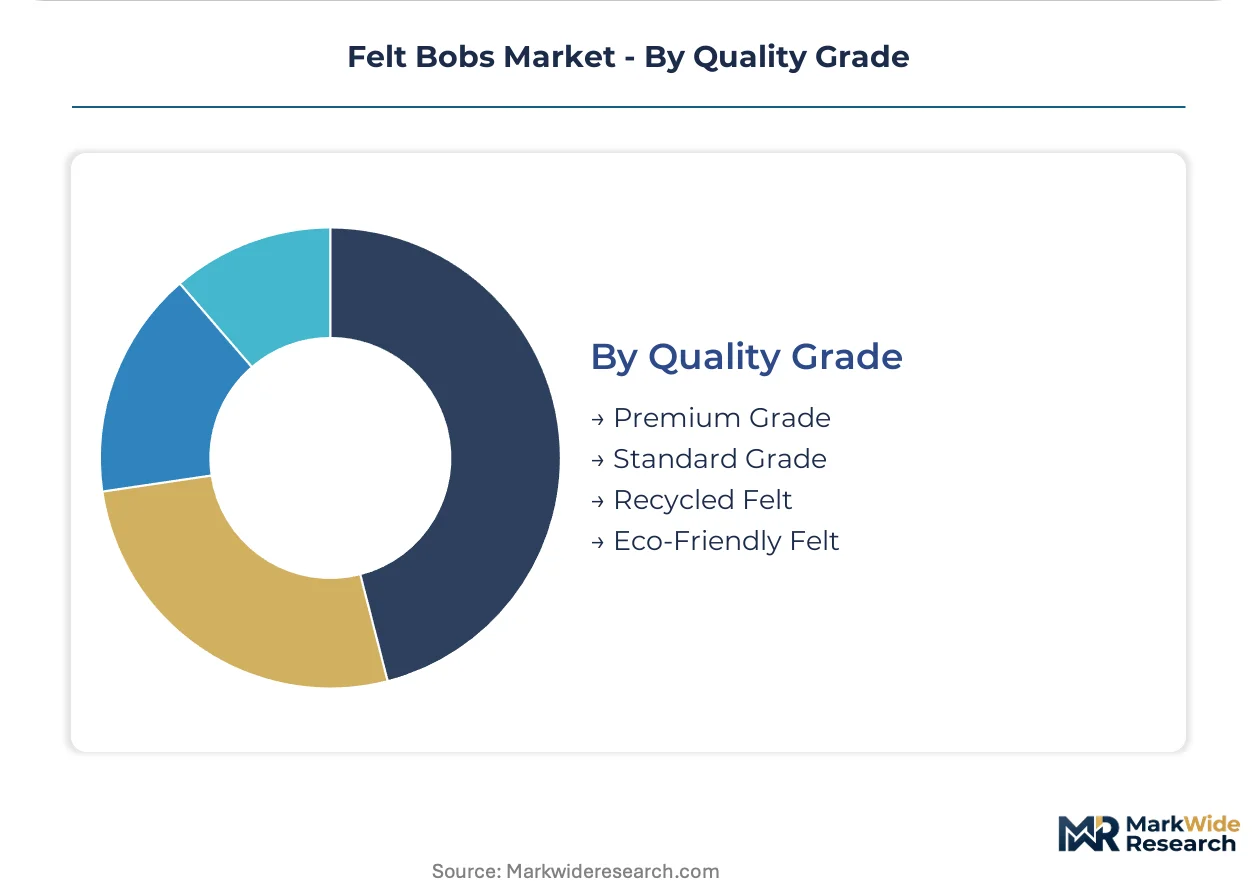
Quality Grade:
Regulatory disclosure requirements and chemical-footprint mandates are restructuring competitive advantage around certified sustainable supply chains rather than commodity density grades alone.
- Eco-Friendly Felt:Vegetable-tanned wool fiber bobs displacing chromium-tanned alternatives across premium production. Swiss watch-component finishers and German automotive suppliers now specify these inputs in purchase orders, requalifying entire supplier bases around compliant chemistry.
- Premium Grade:Density-calibrated bobs with documented lot traceability for aerospace and precision manufacturing, where titanium airframe component finishing requires specifications few suppliers currently meet.
- Standard Grade:General-purpose compressed fiber bobs for non-critical deburring and finishing operations, facing price pressure from polyester felt substitutes.
- Recycled Felt:Post-consumer fiber content bobs addressing sustainability procurement criteria in EU Green Deal tender rules.
Premium Grade anchors current revenue concentration. Eco-Friendly Felt shows the steepest expansion trajectory on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive precision finishers command 15-20% price premiums over Indian export-grade suppliers, while Gujarat's mechanized felt-making clusters undercut European producers on standard-density bobs by 30-40%. This asymmetry shapes sourcing decisions across jewelry polishing and industrial deburring channels.
United States
EV drivetrain manufacturers in Michigan and Ohio specify density-calibrated felt bobs for gear-polishing workflows, pulling premium-grade volume through domestic distributors. EPA workplace dust-exposure limits and OSHA respiratory-protection standards constrain wool-fiber processing investments, particularly for producers serving metal-finishing end users. Spartan Felt leverages North American fulfillment speed through established distributor relationships across the Midwest industrial belt.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg mandate vegetable-tanned wool inputs to satisfy ECHA REACH Annex XVII restrictions on hexavalent chromium compounds. The KBA enforces material documentation standards for precision finishing tools used in EV component manufacturing. Stuttgart-area tool distributors now require full material safety data sheet disclosure, filtering out uncertified imports from non-EU suppliers.
India
Jewelry polishing workshops in Surat and Jaipur drive procurement of premium-grade felt bobs through B2B marketplaces that bypass traditional Mumbai trading houses. BIS textile-grade certifications create compliance thresholds for exporters serving South Asian precision-tool markets. Gujarat's felt-making belt controls over 60% of export-grade capacity, with mechanized carding cooperatives scaling to serve both domestic toolmakers and European automotive suppliers.
Japan
Precision component finishers in Aichi and Osaka prefectures specify density-graded felt bobs with documented lot traceability for aerospace and automotive applications. METI guidelines on sustainable manufacturing procurement increasingly favor chemical-footprint disclosures in supplier qualification. Nagoya-area automotive clusters source through specialized distributors who provide technical specification support and density calibration guidance.
Mexico
Taxco silver workshops currently rely on imported US felt bobs for jewelry finishing operations, creating white-space opportunity for localized distribution partnerships. The country's national manufacturing development programs support precision-tool sector expansion in Guanajuato and Querétaro industrial corridors. Mexican automotive assembly plants in Nuevo León and Baja California pull industrial-grade felt bobs through integrated North American supply chains.
Felt Bobs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where premium-grade consistency competes against fulfillment speed and price. The vendor base spans vertically integrated wool processors, specialized density calibration houses, and regional distribution-focused operators. Two strategic archetypes dominate: upstream-controlled producers with captive fiber-treatment capacity, and logistics-anchored players competing on North American delivery timelines. Competitive moves concentrate on supplier base requalification around REACH-compliant chemistry and direct mill-to-workshop platform development.
Among North American distribution-focused operators, Spartan Felt occupies a position emphasizing domestic fulfillment velocity. European specialists in precision density calibration include Moleroda Finishing Systems, which exemplifies the certification-heavy tier serving aerospace and automotive deburring applications. Gesswein represents the upstream-controlled archetype, with its vertically managed wool sourcing sustaining premium-grade consistency across jewelry-polishing product lines.
| Leading Market Players |
|---|
| Gesswein |
| Moleroda Finishing Systems |
| Wolter Corp |
| Forney Industries |
| Dico Products Corp |
| Kemet International |
| Spartan Felt |
| Caswell Australia |
| Ahuja Felts |
| Others |
Supply & Pricing Matrix
REACH Annex XVII compliance gates both supplier qualification and price differentiation across European felt bob procurement, compressing chromium-tanned fiber supply while awarding premiums to vegetable-tanned certified alternatives. German automotive finishers and Swiss watch-component manufacturers now structure purchase orders around chemical-footprint documentation, collapsing price convergence between certified and uncertified grades.
Pricing Analysis
Configured-to-order density calibrations command 15-20% premiums over standard-density SKUs in aerospace and jewelry-polishing applications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and lot traceability, with REACH-compliant vegetable-tanned inputs anchoring the top tier. Cost compression in standard-grade industrial bobs intensifies because polyester felt substitutes from Chinese manufacturers undercut natural wool pricing. Jewelry polishing workshops in India exhibit highest price sensitivity, while aerospace deburring operations in Germany and Japan tolerate premium positioning for documented calibration.
Supply Chain Analysis
India and China anchor felt bob manufacturing, with Gujarat's mechanized carding cooperatives supplying export-grade compressed wool and Chinese producers dominating synthetic fiber output. Raw material flows draw from Australian Merino wool auctions, chromium-tanned and vegetable-tanned fiber processing facilities, and polyester staple fiber petrochemical feedstocks. Single-region supply concentration in Gujarat exposes buyers to monsoon-disrupted logistics and regional labor actions. Distribution runs through B2B marketplaces fragmenting traditional Mumbai trading house control, particularly for Surat and Jaipur jewelry manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct mill-to-workshop platform economics are restructuring procurement relationships in felt bob distribution, with interoperability between Indian cooperatives and European automotive suppliers collapsing traditional intermediary margins.
For Market Incumbents: Secure vegetable-tanned fiber supply contracts ahead of REACH Annex XVII expansion timelines, locking in compliant chemistry before requalification costs spike. Backward integration into captive wool processing or certified supplier partnerships defends margin position against polyester substitution in non-critical deburring tiers. Density calibration technician training programs in Gujarat address capability scarcity as aging master craftsmen retire. For New Entrants and Emerging Players: Anchor in Taxco silver workshops and Guanajuato precision-tool corridors, where Mexican jewelry manufacturing remains underpenetrated by localized distribution. Aerospace deburring specialization for titanium airframe components offers white-space opportunity given documented lot traceability specifications few suppliers currently meet. Direct B2B marketplace participation bypasses established distributor relationships that incumbents dominate. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated felting line deployment, favoring scale operators over hand-loom workshops in competitive positioning. Long-term viability across the analysis window rests on certified sustainable supply chain control rather than commodity density grades. Acquisition target archetypes include mid-scale producers with dual BIS textile-grade and REACH compliance documentation. The signal to watch is ECHA substance evaluation roadmap expansion on formaldehyde-releasing agents and skin-sensitizing chemicals.| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Tanned Fiber Supply Agreement | REACH Annex XVII compliance secures German automotive and Swiss watch-component purchase orders. |
| Density Calibration Technician Training Program | Gujarat master craftsman knowledge transfer addresses automated felting line operator shortages. |
| Direct Mill-to-Workshop Platform Launch | B2B marketplace participation captures Surat and Jaipur jewelry manufacturer procurement shifting online. |
| Aerospace Lot Traceability Certification | Documented calibration protocols unlock titanium airframe component finishing specifications. |
| Mexican Distribution Partnership | Localized presence captures Taxco silver workshop demand currently served by US imports. |
Research Methodology
Initial hypotheses were tested against primary input from felt bob plant managers, jewelry workshop procurement leads, automotive Tier 1 supplier quality directors, and precision finishing tool distributors and refined through secondary validation. Bottom-up triangulation combined customs and trade data, BIS textile-grade certification records, ECHA REACH registration databases, and SEC filings from publicly traded industrial equipment manufacturers with top-down macroeconomic factor assessment.
Variance decomposition across the projection horizon isolates volume drivers by density grade tier, end-use application, certification level, and regional production hub. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Modeled inputs include Merino wool auction price trajectories, REACH substance restriction implementation timelines, and mechanized carding capacity expansion in Gujarat's felt-making belt.
Decision-makers should treat outputs as directional under stable regulatory implementation and raw material supply assumptions; material deviation would warrant model refresh. Specific risk factors include accelerated polyester substitution, monsoon disruption to Gujarat logistics, and ECHA formaldehyde-releasing agent restrictions ahead of current roadmap expectations. Recalibration cycles align with material shifts in REACH Annex XVII substance evaluations and Australian wool auction volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Silk Yarn Market