
 Cotton Processing Market | 2026-2036
Cotton Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Processing Market Intelligence
Medical product makers is repositioning demand toward combed cotton and sterilized fiber grades as healthcare textile standards tighten. Rieter leverages its rotor spinning technology leadership to capture premium machinery contracts in Asian markets. Toyota Industries Corporation sustains dominance in automated ginning systems through captive R&D in Nagoya. Lakshmi Machine Works Limited anchors South Asian market presence with localized service networks and cost-engineered equipment.
Cotton processing encompasses the mechanical and chemical transformation of harvested seed cotton into clean, graded lint and subsequent yarn through ginning, cleaning, carding, and drawing operations, with fiber length uniformity (measured in micronaire and staple length) determining downstream spinning efficiency and fabric quality. The primary commercial purpose centers on supplying standardized fiber inputs to textile manufacturers who convert processed cotton into woven, knitted, and nonwoven materials for consumer and industrial end uses. Combed cotton commands margin concentration among product types due to its superior strength and reduced nepp content for fine-count yarns. Ginning technology leads equipment investment cycles as processors retrofit for energy recovery and dust containment. Spun yarn applications in technical textiles represent the fastest-growing demand vector as industrial fabric specifications harden.
OSHA workplace exposure limits and EPA air quality standards govern dust and particulate emissions from ginning and opening operations in the United States, while India's BIS certification mandates fiber grade labeling for domestic and export market access. The EU's REACH framework restricts chemical finishing agents used in cotton preparation, redirecting processor investment toward enzymatic scouring and plasma surface treatments. Stakeholders must monitor evolving residue limits in multiple jurisdictions to avoid supply chain disqualification and secure long-term offtake contracts.
Market Dynamics
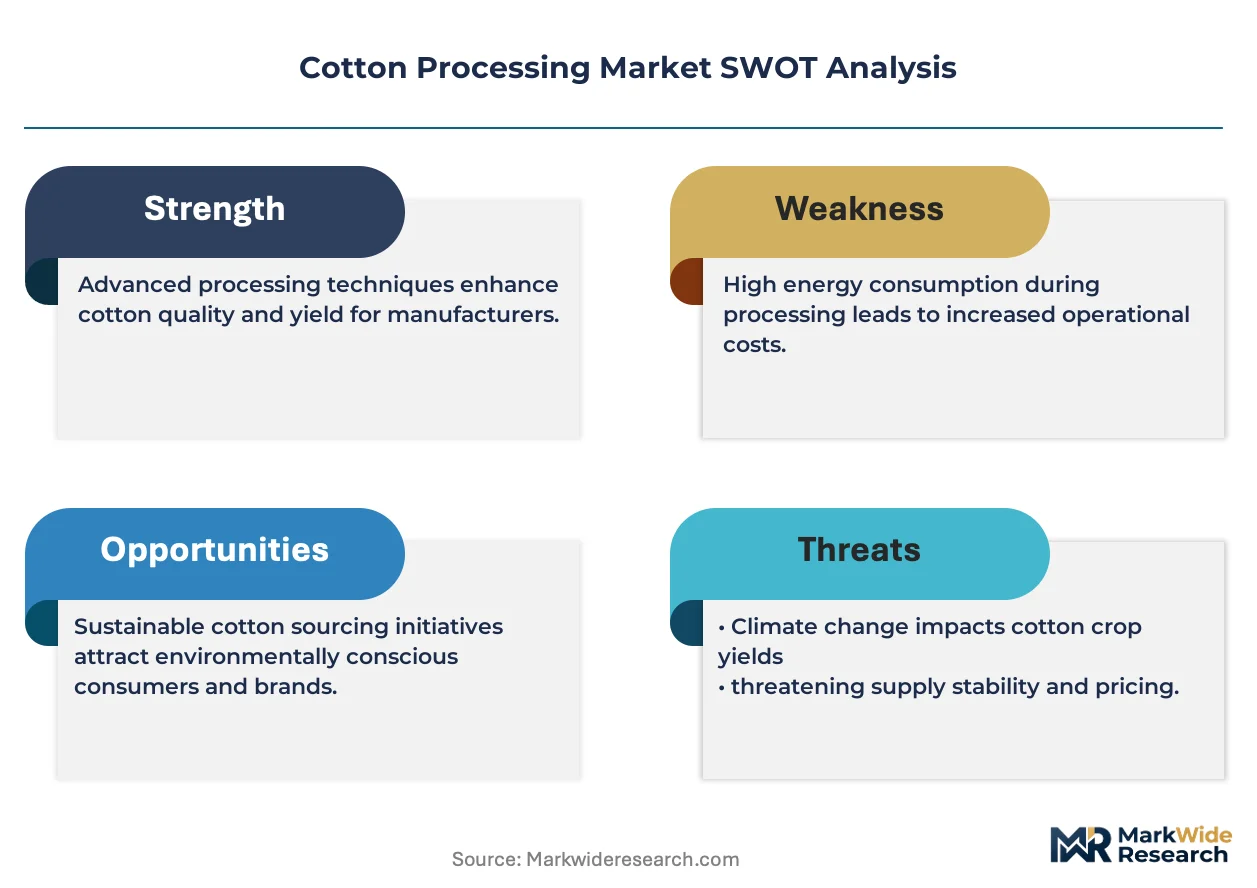
Apparel brands are scaling procurement of combed cotton for premium garment lines, while India's BIS fiber grading mandates tighten quality thresholds for export-bound lint. This dual pressure from demand upgrading and regulatory stringency is compressing margins for processors lacking advanced ginning and cleaning capabilities.
Growth Catalysts
- REACH chemical restrictions:The EU's REACH framework restricts conventional finishing agents, redirecting processor investment toward enzymatic scouring and plasma surface treatments that command premium pricing.
- Technical textile demand:Spun yarn applications in industrial fabrics represent expanding offtake as specifications for strength and uniformity harden across automotive and filtration end uses.
- Gujarat ginning cluster concentration:Spinners seeking proximity to raw material sources are consolidating procurement around Gujarat's integrated ginning facilities, reducing logistics friction.
Market Restraints
- Seed cotton price volatility:Input cost swings from weather-driven harvest variability constrain margin predictability for processors locked into annual supply contracts.
- Equipment supplier concentration:Automated ginning system manufacturing concentrates among a limited set of technology providers, creating procurement bottlenecks during capacity expansion cycles.
- Synthetic fiber substitution:Polyester and regenerated cellulose alternatives capture share in cost-sensitive apparel segments where fiber origin labeling carries less consumer weight.
Strategic Opportunities
- Medical-grade fiber certification:Healthcare textile standards tightening across multiple jurisdictions create white space for processors achieving sterilized fiber grades and pharmaceutical-grade cleanliness protocols.
- Rotor spinning technology convergence:Integration of automated feeding systems with rotor spinning platforms enables processors to capture premium machinery contracts in Asian markets.
- Energy recovery retrofit demand:Ginning facilities pursuing dust containment and thermal efficiency upgrades represent an emerging service revenue stream for equipment specialists.
Industry Challenges
- Multi-jurisdiction residue compliance:Processors must monitor evolving OSHA workplace exposure limits, EPA air quality standards, and BIS certification mandates simultaneously to avoid supply chain disqualification.
- Skilled technician scarcity:Operation of advanced carding and drawing equipment requires specialized training that outpaces vocational program output in major processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Processing Market |
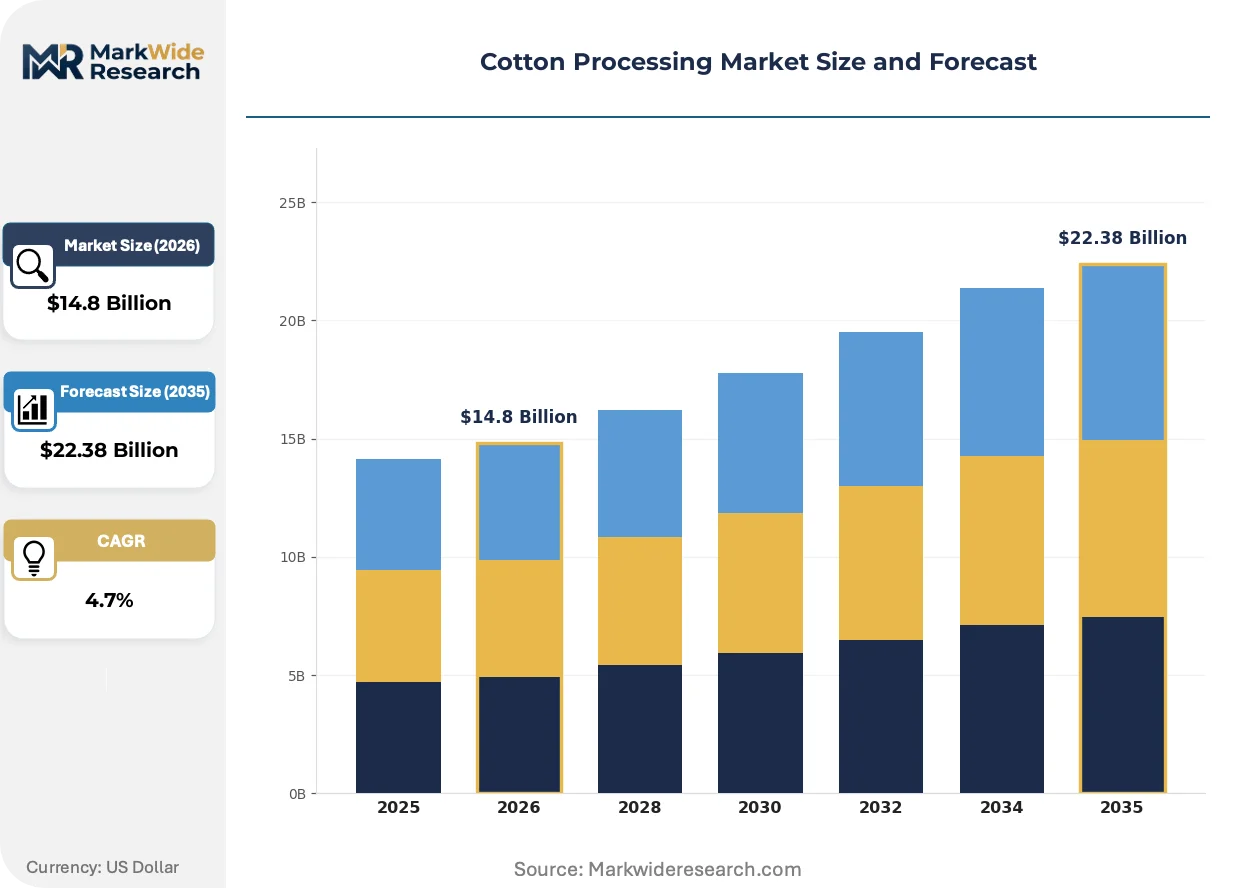
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.38 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cotton, Carded Cotton, Combed Cotton, Spun Yarn, Cotton Fibers Technology: Ginning, Combustion, Cleaning, Blending, Compacting Application: Textile Manufacturing, Home Furnishing, Apparel, Medical Supplies, Industrial Fabrics End User: Spinning Mills, Textile Manufacturers, Apparel Brands, Home Textile Producers, Medical Product Makers |
| Companies Covered | Lummus Corporation, Bajaj Steel Industries, NIPHA Exports Private Limited, Shandong Swan Cotton Industrial Machinery Stock, Cherokee Fabrication, Rieter, Toyota Industries Corporation, Lakshmi Machine Works Limited, Bühler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Processing Market Strategic Shifts & Innovations
Mechanical processing automation and chemical finishing substitution are actively compressing cost structures while elevating quality thresholds. These shifts favor capital-intensive operators capable of integrating energy recovery and contamination control systems.
Automated ginning systems with integrated dust containment and energy recovery modules are consolidating market position among large-scale processors. Mid-cap spinners in India and Turkey are retrofitting facilities at accelerated pace to meet BIS certification and export contract requirements. This technology is consolidating procurement power around equipment providers with localized service networks and captive R&D capabilities.
India's BIS fiber grade labeling mandate for domestic and export market access is forcing processors to invest in micronaire and staple length testing infrastructure. The regulation compresses timelines for quality verification and raises rejection risk for non-compliant shipments. Small-scale ginners in Maharashtra and Telangana face disproportionate compliance burden relative to integrated Gujarat clusters.
Healthcare procurement officers are mandating sterilized fiber grades and pharmaceutical cleanliness documentation for surgical textile inputs. This certification-driven preference shift displaces conventional commodity cotton in medical applications. The pattern is most visible in US and EU hospital supply chains where liability exposure drives specification stringency.
Cotton Processing Market Segmentation
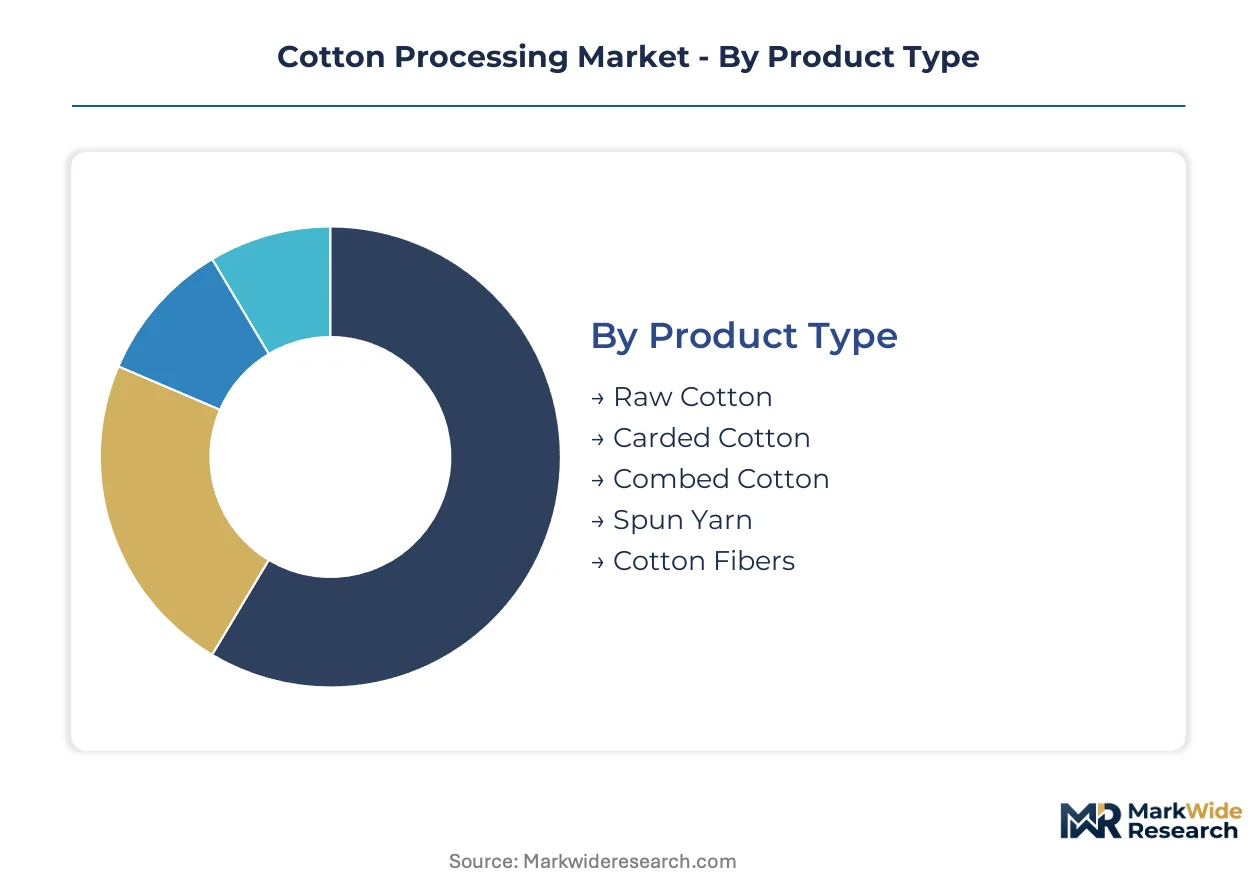
Cotton processing segmentation reflects divergent margin structures across fiber preparation intensity and downstream quality requirements. Processors configure equipment and labor deployment differently based on whether output serves commodity yarn markets or premium textile applications.
Product Type:
Customization intensity spans from bulk raw fiber handling to precision-combed outputs with certified micronaire specifications.
- Combed Cotton:Extra-long staple fibers undergo secondary carding and fine-combing to remove short fibers and neps. Apparel brands in premium garment lines are scaling procurement of this grade as fiber length uniformity specifications harden for fine-count yarn production.
- Spun Yarn:Continuous strands formed by twisting drawn cotton roving serve as direct inputs for weaving and knitting operations. Technical textile specifications for automotive and filtration end uses are concentrating demand around high-tenacity spun yarn grades with reduced hairiness indices.
- Raw Cotton:Harvested seed cotton prior to ginning and cleaning retains plant matter and moisture variability.
- Carded Cotton:Single-pass mechanical cleaning produces shorter-staple fiber suitable for medium-count yarns.
- Cotton Fibers:Discretely graded lint bales standardized by staple length and micronaire for spot market trading.
Most installed capacity flows through Carded Cotton. Expansion is steepest in Combed Cotton.
Technology:
Capital intensity escalates from thermal combustion systems through precision mechanical platforms with integrated contamination detection.
- Ginning:Saw and roller gin configurations separate lint from seed while preserving fiber length integrity. Automated ginning systems with dust containment modules are consolidating procurement around equipment providers with localized service networks in Gujarat and Telangana processing clusters.
- Cleaning:Multi-stage opening and carding sequences remove foreign matter and align fibers for downstream drawing. BIS fiber grading mandates in India are forcing retrofit investment in advanced cleaning lines with inline micronaire testing.
- Combustion:Thermal energy recovery from ginning waste streams powers facility operations.
- Blending:Homogeneous fiber mixing across bale lots ensures consistent processing characteristics.
- Compacting:Density compression of cleaned lint reduces storage footprint and transport costs.
Equipment deployment concentrates in Ginning. Technology refresh cycles are accelerating fastest in Cleaning.
Application:
End-use specifications range from commodity textile inputs to pharmaceutical-grade cleanliness protocols with liability-driven documentation requirements.
- Medical Supplies:Surgical textiles and wound care materials require sterilized fiber grades with pharmaceutical cleanliness documentation. Healthcare procurement officers in US and EU hospital supply chains are mandating certified fiber inputs as liability exposure drives specification stringency.
- Industrial Fabrics:Automotive interiors, filtration media, and geotextiles demand high-tenacity yarns with controlled elongation properties. Spun yarn applications in this segment are expanding as strength and uniformity specifications harden across filtration end uses.
- Textile Manufacturing:Woven and knitted fabric production for consumer goods.
- Home Furnishing:Upholstery, bedding, and decorative textile applications.
- Apparel:Garment manufacturing across mass-market and premium positioning tiers.
Volume throughput remains anchored in Textile Manufacturing. Certification requirements are tightening most aggressively in Medical Supplies.
End User:
Customer scale ranges from integrated multinational textile groups to fragmented regional spinning operations with diverging technical capabilities.
- Spinning Mills:Dedicated yarn production facilities purchase graded lint and intermediate sliver for ring and rotor spinning conversion. Proximity procurement patterns are concentrating demand around Gujarat's integrated ginning clusters as logistics friction reduction becomes a priority selection criterion.
- Medical Product Makers:Surgical textile and hygiene product manufacturers impose sterilized fiber grade requirements. Healthcare textile standards tightening across multiple jurisdictions are repositioning demand toward certified fiber grades with full pharmaceutical cleanliness protocols.
- Textile Manufacturers:Integrated fabric producers with captive spinning capacity.
- Apparel Brands:Vertical retailers specifying fiber grades for contracted manufacturing.
- Home Textile Producers:Bedding and furnishing specialists with bulk yarn procurement patterns.
Contract value concentrates with Textile Manufacturers. Specification upgrading is most pronounced among Medical Product Makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cotton processing investment toward jurisdictions with lower compliance friction and subsidized infrastructure. Processors are migrating capacity to exploit gaps between EPA dust standards and India's BIS fiber grading mandates.
United States
EPA air quality standards and OSHA workplace exposure limits govern ginning emissions across Texas and Mississippi processing corridors. The USDA maintains crop insurance programs that stabilize seed cotton supply for domestic processors. Automated ginning retrofits concentrate in Lubbock and the Mississippi Delta as facilities pursue energy recovery and dust containment upgrades.
India
BIS fiber grade labeling mandates for export market access are forcing micronaire testing infrastructure investment across Maharashtra and Telangana. The PLI scheme for textiles incentivizes integrated ginning-to-spinning capacity in designated clusters. Procurement gravity centers on Gujarat's ginning facilities as spinners seek logistics friction reduction and proximity to raw material sources.
China
GB standards for fiber quality and MIIT industrial upgrading directives shape processor investment in Xinjiang and Shandong ginning bases. Dual carbon goals are accelerating thermal efficiency retrofits and waste-to-energy systems in cotton processing plants. Yangtze River Delta spinners are consolidating procurement around Shandong Peninsula ginning clusters with integrated cleaning and testing capabilities.
Turkey
EU REACH chemical restrictions on finishing agents redirect Turkish processors toward enzymatic scouring and plasma surface treatments for EU-bound exports. The country's national textile regulator enforces fiber grade documentation aligned with European import requirements. Aegean Region ginning facilities near İzmir are retrofitting for contamination control to capture premium machinery contracts from European apparel brands.
Brazil
ANVISA pharmaceutical-grade cleanliness protocols are opening certification pathways for medical-grade cotton exports to US and EU hospital supply chains. The central bank's trade finance programs support processor investment in sterilized fiber grades. Mato Grosso ginning clusters are expanding automated systems to meet technical textile specifications for automotive and filtration end uses.
Cotton Processing Market Key Industry Players
Capacity expansion dominates the current landscape as processors retrofit for energy recovery and dust containment to meet tightening OSHA and EPA standards. The vendor base stratifies across three tiers: integrated multinational equipment providers with captive R&D, regional specialists with localized service networks, and commodity ginning machinery fabricators. Strategic archetypes include technology licensors pursuing premium machinery contracts, scale-driven operators consolidating procurement power, and compliance-focused specialists targeting medical-grade certification. M&A activity and strategic partnerships represent the dominant competitive moves as players seek geographic coverage and technology convergence.
Among Asian equipment specialists, Shandong Swan Cotton Industrial Machinery Stock and Lakshmi Machine Works Limited exemplify the regional-fabricator archetype with cost-engineered product positioning. Rieter occupies a position representing the technology-licensor tier with rotor spinning platform leadership. These three companies anchor the competitive structure without dominating share, leaving space for mid-cap specialists and integrated multinationals to contest premium segments through certification-driven differentiation and service network depth.
| Leading Market Players |
|---|
| Lummus Corporation |
| Bajaj Steel Industries |
| NIPHA Exports Private Limited |
| Shandong Swan Cotton Industrial Machinery Stock |
| Cherokee Fabrication |
| Rieter |
| Toyota Industries Corporation |
| Lakshmi Machine Works Limited |
| Bühler AG |
| Others |
Cost & Logistics Intelligence
Seed cotton price volatility from weather-driven harvest variability cascades through three-tier pricing structures across premium, standard, and economy levels, with combed cotton commanding substantial premiums over carded grades as BIS certification mandates harden quality verification thresholds in export markets.
Pricing Analysis
Distributor margins on automated ginning equipment compress as procurement concentrates around Gujarat-based service networks with localized technical support. Price differentiation hinges on micronaire certification tier and volume scale, with medical-grade sterilized fiber grades capturing substantial premiums over commodity lint. Pricing pressure stems from synthetic fiber substitution in cost-sensitive apparel segments, where polyester alternatives undercut cotton on unit economics. Small-scale spinners in Maharashtra exhibit highest price sensitivity, while integrated multinational textile groups absorb premium grades with minimal volume pushback.
Supply Chain Analysis
Direct-to-mill channels handle hyperscale demand from integrated spinning operations in Gujarat, Telangana, and Maharashtra processing clusters. Raw material flows draw from Mato Grosso ginning bases, Texas High Plains harvests, and Xinjiang production zones, with equipment components sourced from Nagoya R&D centers and Shandong fabrication facilities. Single-source vulnerability concentrates in automated ginning system manufacturing, where limited technology providers create procurement bottlenecks during capacity expansion cycles. Distribution runs through bale auction platforms and long-term offtake contracts with tiered pricing tied to staple length verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS fiber grade labeling mandate and EU REACH chemical restrictions simultaneously elevate compliance costs and premium pricing power for certified processors.
For Market Incumbents: Anticipate margin compression from mid-cap retrofitters in Turkey and India by accelerating energy recovery module deployment and dust containment upgrades ahead of tightening EPA and OSHA enforcement cycles. Defensive consolidation through captive R&D in rotor spinning platforms and backward integration into testing infrastructure protects pricing power as BIS certification timelines compress. For New Entrants and Emerging Players: Begin with medical-grade fiber certification as the most penetrable white space, targeting US and EU hospital supply chains where pharmaceutical cleanliness documentation commands substantial premiums over commodity grades. Capture share in sterilized surgical textile inputs through ANVISA-aligned protocols, then expand into technical textile specifications for automotive filtration end uses. For Investors and Strategic Acquirers: Roll-up economics work for regional ginning specialists with localized service networks because BIS compliance burdens disproportionately disadvantage small-scale operators in Maharashtra and Telangana relative to integrated Gujarat clusters. Monitor rotor spinning technology convergence with automated feeding systems as the inflection signal for premium machinery contract capture in Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Certification Investment | ANVISA and FDA-aligned sterilized fiber protocols open US and EU hospital supply chain access. |
| Energy Recovery Retrofit Deployment | Integrated dust containment and thermal efficiency modules satisfy tightening EPA air quality standards. |
| Rotor Spinning Technology Convergence | Automated feeding integration with Rieter platforms captures premium machinery contracts in Asian markets. |
| Backward Integration into Testing Infrastructure | Captive micronaire and staple length verification compresses BIS compliance timelines for export-bound lint. |
| Regional Service Network Expansion | Localized technical support in Gujarat and Telangana clusters defends equipment procurement share against multinational entrants. |
Research Approach
Direct dialogue with ginning facility operators, spinning mill procurement heads, equipment R&D directors, and BIS certification auditors grounded the qualitative foundation, cross-referenced with customs trade data, SEC filings from listed machinery manufacturers, USDA crop insurance program disclosures, and BIS regulatory notifications. Secondary validation drew from plant-level energy consumption benchmarks and hospital procurement database entries for surgical textile inputs. Bottom-up capacity estimates across Maharashtra, Telangana, and Gujarat processing clusters triangulated against top-down fiber consumption projections from textile manufacturer associations.
Bottom-up modeling aggregated installed ginning capacity by technology tier and automation level across the projection horizon, while top-down analysis traced apparel brand procurement commitments and medical device manufacturer fiber specifications. Segmentation dimensions spanned product type intensity, equipment technology vintage, application certification requirements, and end-user scale archetypes. CAGRs derived from regression against historical fiber price spreads and regulatory implementation timelines, with scenario weighting for BIS enforcement intensity and REACH chemical restriction expansion.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting seed cotton cross-border flows, climate events disrupting Mato Grosso or Texas harvest cycles, and synthetic fiber breakthroughs altering apparel brand procurement calculus. Forecasts reflect documented assumptions regarding BIS certification adoption curves and EPA enforcement consistency. Periodic stress-testing of base assumptions is recommended against hospital supply chain liability trendlines and automotive technical textile specification evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Cotton Bags Market