
 Fancy Yarn Market | 2026-2036
Fancy Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Fancy Yarn Market Analysis
Apparel brands and boutique fashion labels are rotating demand away from commodity yarns toward engineered fancy yarns with visual texture and performance blends. Vardhman Textiles leverages integrated spinning and dyeing capacity to serve export knitwear programs from Ludhiana. Toray Industries anchors premium synthetic fancy yarn supply through filament innovation in Japan and Southeast Asian manufacturing bases. Aditya Birla Yarn differentiates via sustainable viscose and specialty cellulosic blends targeting European compliance buyers.
Fancy yarn denotes intentionally irregular or structurally modified continuous strands produced through differential drafting, wrapping, or air-jet texturing to achieve slub, loop, bouclé, or metallic effects for decorative and functional textiles. These yarns typically incorporate nylon, polyester, or metallized films at 15-40 percent by weight to deliver abrasion resistance and dimensional stability in finished fabrics. Blended yarn and specialty yarn categories command the widest margin pools, as fashion designers and textile manufacturers pay premiums for certified colorfastness and low-pilling performance. Synthetic yarn competes on scale for mass-market knitwear, while natural fiber variants occupy artisanal and sustainable positioning in craft shop and online retail channels.
REACH and the EU Green Deal constrain azo dye formulations and perfluorinated chemistry in European-bound fancy yarn exports, forcing reformulation across South Asian supply chains. China's GB standards and MEE enforcement similarly tighten wastewater discharge limits for bleaching and dyeing operations in Shaoxing and Nantong clusters. India's BIS certification and PLI scheme for textiles incentivize domestic value addition in technical and decorative yarns. Stakeholders must monitor regulatory divergence between European chemical restrictions and Asian production incentives when locating dyeing capacity and qualifying suppliers for brand compliance programs.
Market Dynamics
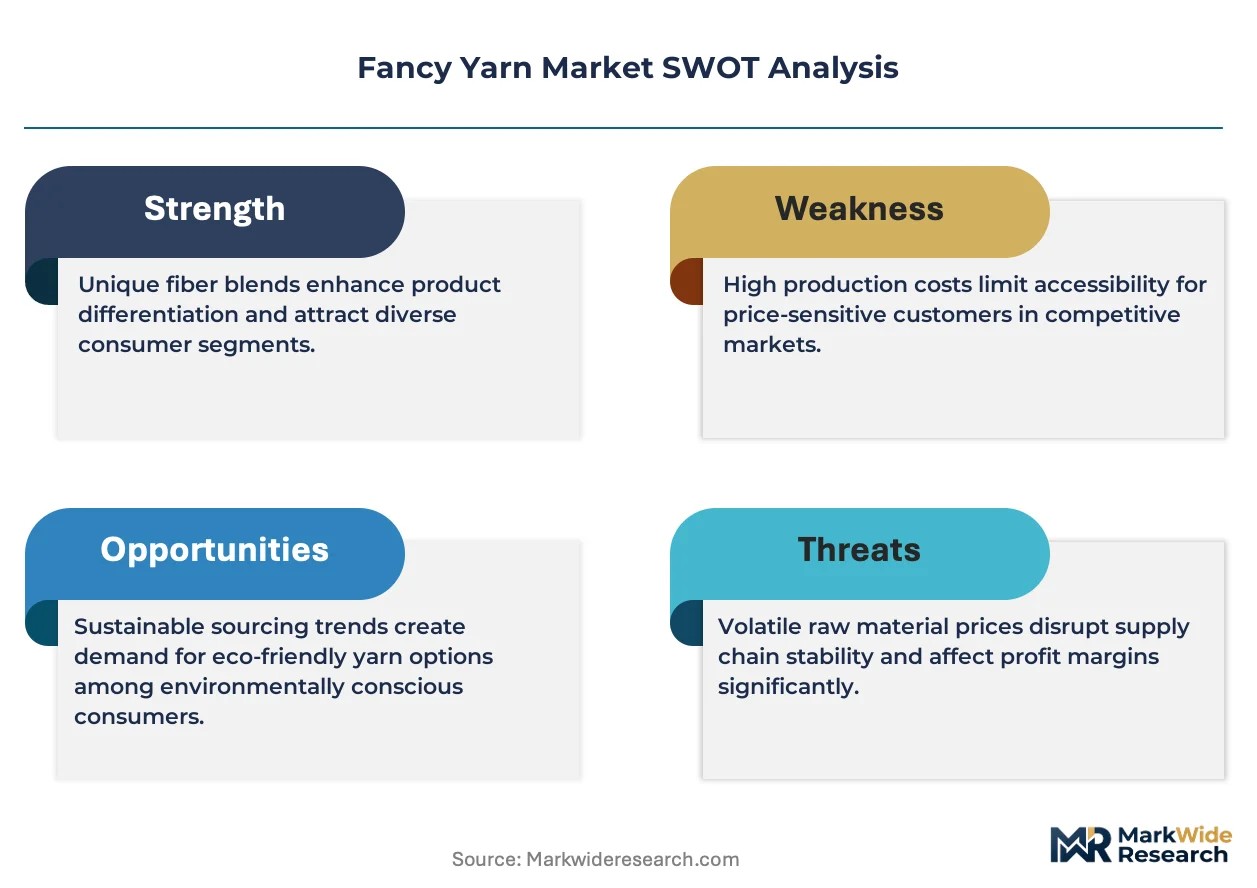
Fashion houses are consolidating fancy yarn sourcing around certified slub and bouclé specialists capable of delivering low-pilling performance under tightened European chemical disclosure mandates. This procurement concentration is compressing supplier margins while elevating technical qualification barriers for dyeing and texturing operations.
Growth Catalysts
- REACH chemical disclosure mandates:European apparel brands now require full azo dye traceability, pushing Tiruppur and Surat clusters to upgrade wastewater testing and documentation systems to retain export eligibility.
- Air-jet texturing advancement:Loop and metallic effect yarns produced through modified air-jet chambers achieve dimensional stability previously requiring mechanical twisting, opening premium positioning for mid-scale spinners.
- India PLI textile incentives:Domestic value-addition schemes for technical and decorative yarns are accelerating capital deployment into fancy yarn capacity expansion across Ludhiana and Surat manufacturing belts.
Market Restraints
- Metallized film input volatility:Nylon and polyester staple prices fluctuate with crude derivative markets, compressing blended yarn margins when petrochemical feedstocks spike.
- Shaoxing dyeing concentration:Wet processing for synthetic fancy yarns clusters heavily in Zhejiang province, creating single-point vulnerability to China's MEE wastewater enforcement actions.
- Cellulosic substitution ceiling:Viscose and lyocell blends cannot replicate the abrasion resistance of metallized synthetic structures in high-wear knitwear applications.
Strategic Opportunities
- Brazilian artisanal craft retail:Handloom and boutique channels in São Paulo and Minas Gerais remain underpenetrated by certified natural-fancy-yarn suppliers serving European compliance standards.
- Digital textile printing convergence:Fancy yarn bases engineered for direct-to-garment compatibility enable on-demand color customization without batch dyeing, reducing working capital requirements for small-batch producers.
- EU Green Deal circularity mandates:Upcoming design-for-recyclability standards will favor mono-material fancy yarns over complex multi-fiber constructions, rewarding early reformulation investments.
Industry Challenges
- Colorfastness certification timelines:ISO 105-C06 wash-fastness testing and REACH SVHC documentation now require 12-16 week qualification cycles, delaying new shade introductions for seasonal collections.
- Legacy ring-spinning retrofit costs:Conventional cotton spinning assets require substantial modification to produce differential-drafted slub effects, straining capital allocation for mid-tier mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fancy Yarn Market |
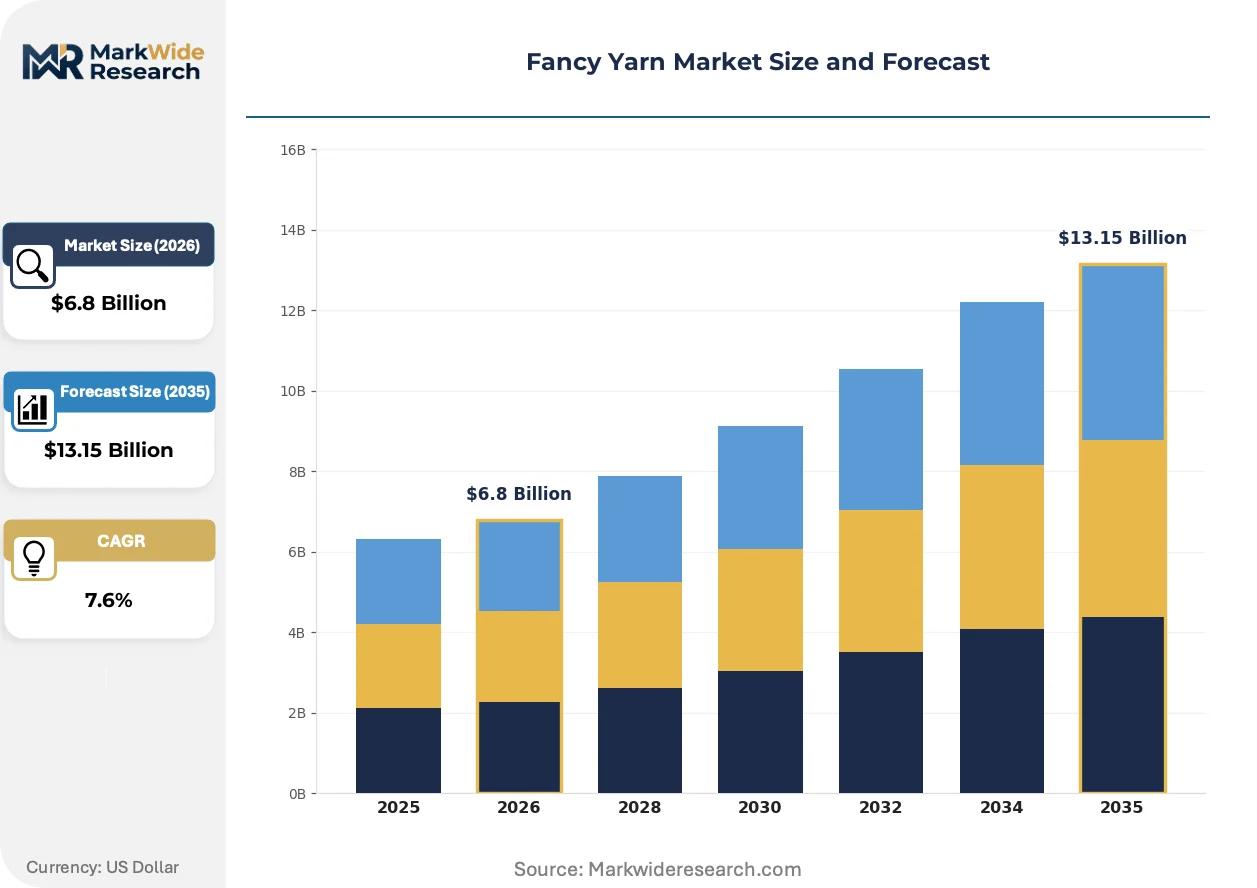
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber, Blended Yarn, Synthetic Yarn, Specialty Yarn Application: Knitwear, Weaving, Crochet, Embroidery Distribution Channel: Online Retail, Specialty Stores, Craft Shops, Wholesale End User: DIY Enthusiasts, Fashion Designers, Textile Manufacturers, Hobbyists |
| Companies Covered | Vardhman Textiles, Filatex India, Ease Loong Tech, Toray Industries, Aditya Birla Yarn, Jiangsu New Victor Industrial, KINGEAGLE, Kuraray, Yulin Yuefang Bleaching and Dyeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fancy Yarn Market Emerging Trajectories
Active bifurcation between mass-market synthetic texturing and premium natural-cellulosic positioning is fragmenting equipment investment strategies and reshaping supplier qualification protocols across European and Asian procurement offices.
Solution-dyed polyester filament is bifurcating the fancy yarn supply base. Waterless coloration eliminates post-spinning dyeing stages entirely. High-volume knitwear programs at European fast-fashion retailers are adopting these pre-pigmented structures for basic metallic and heather effects. The technology is bifurcating margin pools: commodity synthetic fancy yarns compress toward price-driven competition while wet-processed specialty yarns defend premium positioning through tactile irregularity.
China's GB 4287-2012 textile wastewater standard revisions and MEE enforcement protocols are forcing Shaoxing and Nantong dyeing clusters to install membrane bioreactor systems. Discharge limits for chemical oxygen demand and heavy metal content now match European directive stringency. Small-batch fancy yarn processors lacking capital for effluent treatment upgrades are exiting or consolidating into toll-dyeing arrangements with compliant centralized facilities.
Boutique fashion labels are consolidating vendor lists from fifteen-plus suppliers to three-to-four strategic partners capable of end-to-end color development and certified compliance documentation. This concentration transfers inventory risk upstream to yarn mills while demanding shorter lead times for custom shade matching. The shift is most pronounced in Italian and French luxury knitwear houses sourcing from Indian integrated spinners with captive dyeing capacity.
Fancy Yarn Market Segmentation
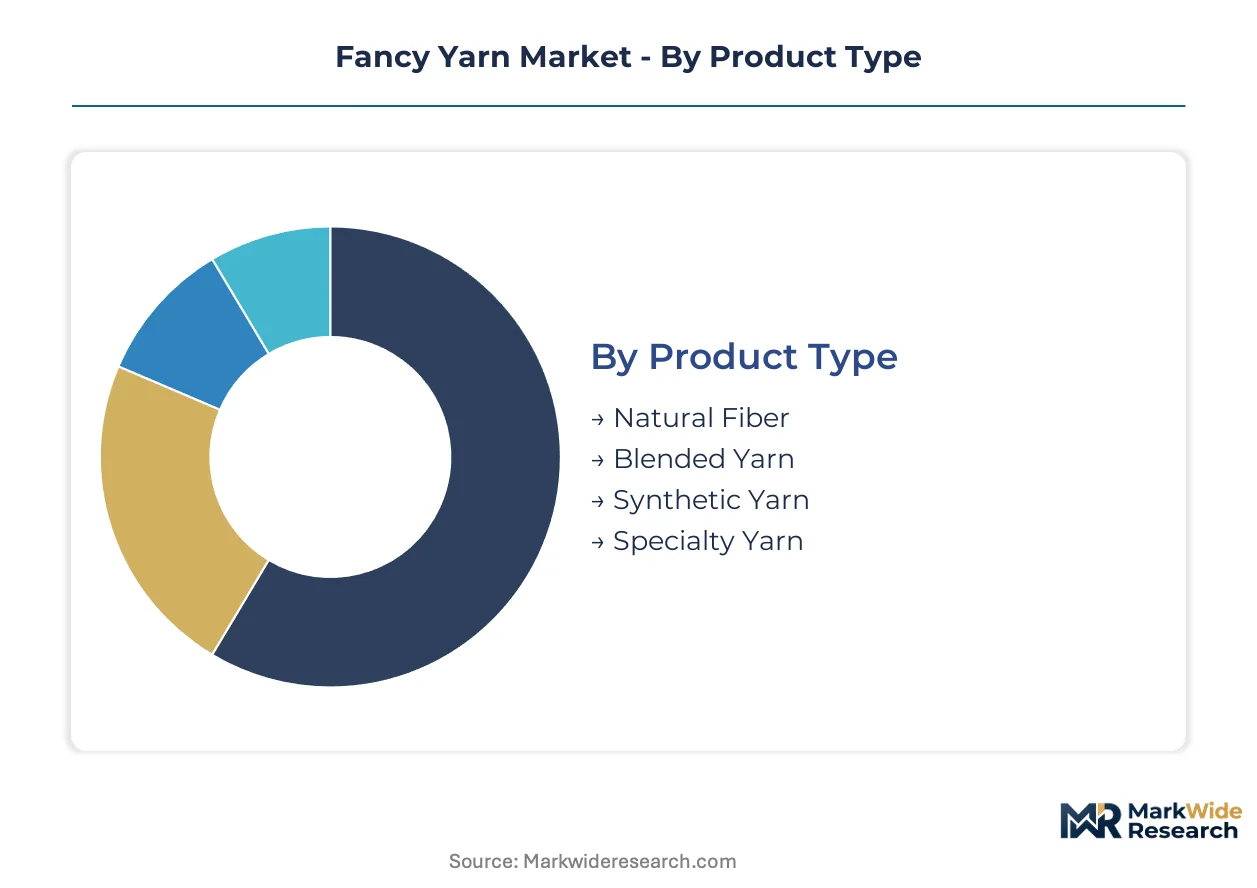
Fancy yarn procurement patterns diverge sharply between export-oriented apparel supply chains and domestic craft consumption. Segment boundaries blur as Tiruppur knitwear houses source specialty synthetics while European boutique labels commission small-batch natural fiber blends.
Product Type:
Domestic demand concentrates in natural and blended constructions serving handloom clusters; export programs favor synthetic and specialty variants engineered for REACH compliance.
- Blended Yarn:Cellulosic-synthetic constructions at 15-40 percent metallized fiber content deliver abrasion resistance for high-wear knitwear. Tiruppur and Surat mills are expanding differential-drafting capacity to serve European fast-fashion programs requiring low-pilling certification.
- Specialty Yarn:Intentionally irregular structures—slub, bouclé, loop—achieved through air-jet texturing or mechanical wrapping command premium positioning. Italian luxury houses consolidate sourcing around Indian integrated spinners with captive dyeing and ISO 105-C06 documentation.
- Natural Fiber:Cotton, wool, and silk bases occupy artisanal channels in Brazil and European craft retail, constrained by cellulosic substitution ceilings in performance applications.
- Synthetic Yarn:Nylon and polyester staple variants compete on scale for mass-market knitwear, exposed to petrochemical feedstock volatility.
Blended yarn holds the largest share; momentum sits with specialty yarn.
Application:
Volume concentration aligns with garment construction complexity and chemical disclosure burden.
- Knitwear:Sweater, scarf, and accessory programs drive bulk procurement of certified slub and metallic effects. Shaoxing dyeing clusters process synthetic fancy yarn bases for European fast-fashion retailers adopting solution-dyed filament to bypass wet-processing stages.
- Weaving:Upholstery and decorative textile applications require dimensional stability through filament innovation. Toray Industries anchors supply from Southeast Asian manufacturing bases serving Japanese and European contract furniture programs.
- Embroidery:Metallic and high-sheen thread variants for embellishment face REACH azo dye traceability requirements.
- Crochet:Hand-craft consumption channels in North America and Western Europe favor natural fiber positioning with sustainable viscose blends.
Knitwear dominates volume; weaving claims the steepest expansion trajectory as contract furniture reshoring accelerates.
Distribution Channel:
Channel selection reflects batch size, certification documentation, and working capital constraints.
- Wholesale:Bulk supply to integrated apparel manufacturers and textile converters concentrates in Surat and Ludhiana trading hubs. India's PLI textile incentives accelerate capital deployment into fancy yarn capacity expansion serving this channel.
- Online Retail:Direct-to-consumer platforms enable on-demand color customization for small-batch producers, bypassing 12-16 week REACH qualification cycles through digital textile printing convergence.
- Specialty Stores:Curated natural fiber assortments target DIY enthusiasts and hobbyists in São Paulo and Minas Gerais craft retail corridors.
- Craft Shops:Local brick-and-mortar channels remain underpenetrated by certified suppliers serving European compliance standards.
Wholesale retains the largest share; online retail is climbing the fastest as boutique labels reduce vendor counts.
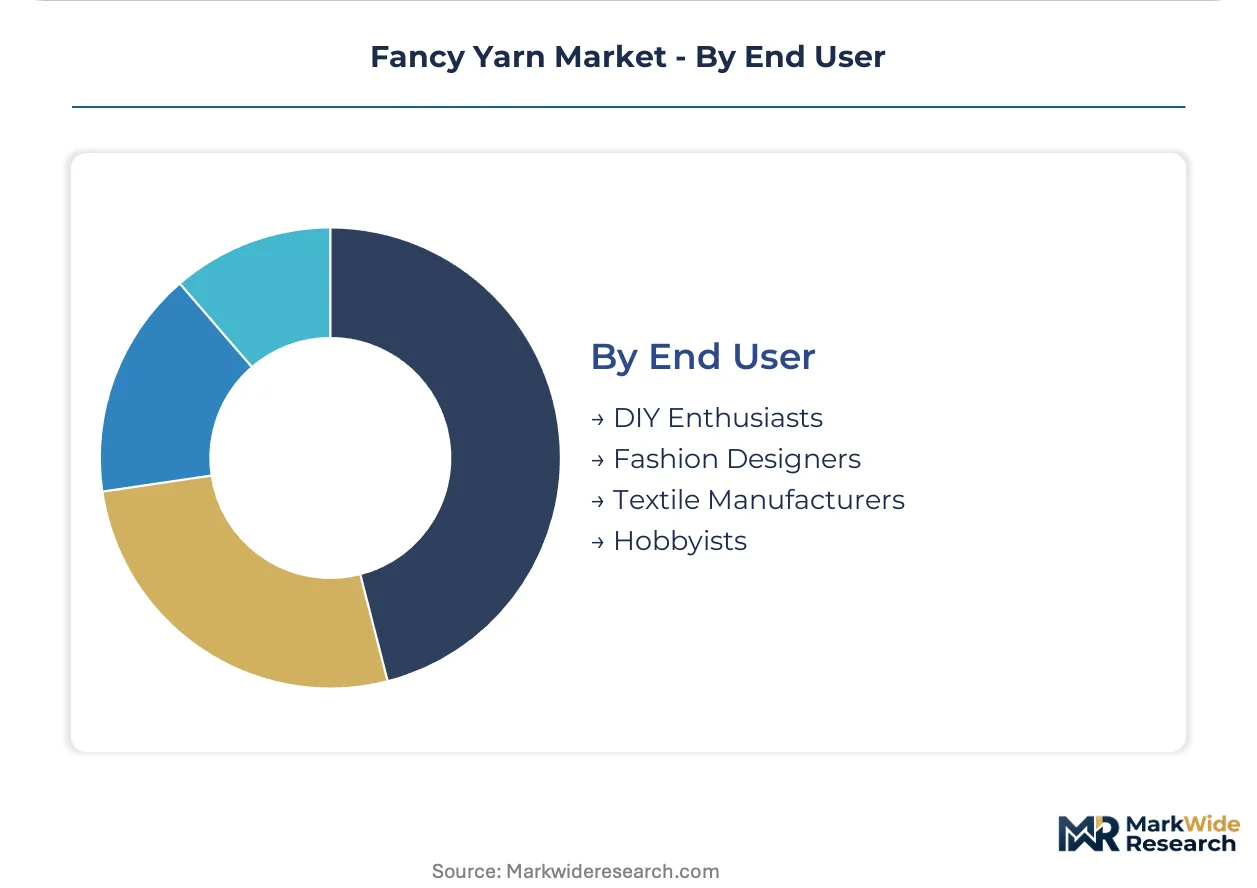
End User:
User sophistication determines specification stringency and margin capture.
- Textile Manufacturers:Integrated spinning and dyeing operations in Ludhiana supply export knitwear programs with full azo dye traceability. These processors absorb inventory risk transferred from consolidating European procurement offices.
- Fashion Designers:Boutique labels in Milan and Paris demand end-to-end color development from three-to-four strategic partners, compressing supplier margins while elevating technical qualification barriers.
- DIY Enthusiasts:Home craft consumption favors tactile irregularity and sustainable positioning over performance certification.
- Hobbyists:Price-sensitive segment served by commodity synthetic texturing with limited compliance documentation.
Textile manufacturers command the largest volume; fashion designers are gaining share fastest as vendor consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The JNPT-Mundra shipping corridor underwrites India's dominance in fancy yarn export logistics, connecting Tiruppur and Surat clusters to European knitwear houses.
India
Tiruppur knitwear exporters and Surat trading hubs drive bulk procurement of certified slub and bouclé constructions. BIS certification and PLI textile incentives accelerate capital deployment into differential-drafting capacity across Ludhiana manufacturing belts. Shaoxing dyeing clusters increasingly toll-process Indian-origin synthetic bases to bypass domestic wastewater enforcement.
China
Shaoxing and Nantong wet-processing centers handle synthetic fancy yarn coloration for European fast-fashion programs. GB standards and MEE enforcement protocols force membrane bioreactor installation, consolidating small-batch processors into toll-dyeing arrangements. Zhejiang province retains concentration risk for metallized filament supply chains.
Italy
Milan and Paris luxury houses consolidate vendor lists around three-to-four strategic partners with end-to-end color development. EU Green Deal circularity mandates and REACH azo dye traceability requirements elevate technical qualification barriers. Como silk district spinners increasingly source certified viscose blends from Indian integrated mills.
Japan
Toray Industries anchors premium synthetic fancy yarn supply through filament innovation from Southeast Asian manufacturing bases. METI-supported R&D programs advance air-jet texturing for dimensional stability without mechanical twisting. Nagoya-based technical textile converters serve contract furniture reshoring demand across European markets.
Brazil
São Paulo and Minas Gerais craft retail corridors remain underpenetrated by certified natural-fancy-yarn suppliers. ANVISA chemical disclosure frameworks lag European REACH stringency, creating compliance arbitrage for imported specialty constructions. Local handloom cooperatives drive artisanal demand for tactile irregularity in domestic apparel segments.
Fancy Yarn Market Vendor Landscape
Concentration sits with integrated spinners possessing captive dyeing capacity and documented REACH compliance. The supplier base fragments between mass-market synthetic texturers and premium natural-cellulosic specialists. Three archetypes dominate: Indian integrated mills with export certification, Japanese filament innovators with Southeast Asian manufacturing bases, and Chinese toll-dyeing processors serving fast-fashion volume programs. Competitive moves center on vendor list consolidation by European procurement offices and backward integration into solution-dyed filament capacity to bypass wet-processing stages.
Within the integrated-mill archetype, Vardhman Textiles and Aditya Birla Yarn exemplify Indian suppliers absorbing inventory risk transferred from consolidating European buyers. Toray Industries occupies a position representing Japanese filament innovation with regional manufacturing footprint. These three anchors illustrate the geographic and capability stratification shaping qualification protocols across Milan, Paris, and London procurement offices.
| Leading Market Players |
|---|
| Vardhman Textiles |
| Filatex India |
| Ease Loong Tech |
| Toray Industries |
| Aditya Birla Yarn |
| Jiangsu New Victor Industrial |
| KINGEAGLE |
| Kuraray |
| Yulin Yuefang Bleaching and Dyeing |
| Others |
Supply Flow & Price Mechanics
Shaoxing dyeing cluster scale economies at 40 percent regional concentration compress unit processing costs while elevating qualification barriers for smaller toll-processors. Tiruppur knitwear houses leverage captive spinning capacity to defend margin floors against petrochemical feedstock volatility in metallized filament supply.
Pricing Analysis
Volume-discount tiering separates certified REACH-compliant specialty constructions from commodity synthetic texturing and artisanal natural fiber positioning. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and captive dyeing capacity. Cost compression in standard synthetic tiers is intensifying because solution-dyed filament bypasses wet-processing stages entirely. DIY enthusiasts and hobbyists exhibit highest price sensitivity; Italian luxury houses sourcing through consolidated vendor lists show lowest.
Supply Chain Analysis
Inventory risk transferred upstream to Indian integrated mills has shortened effective lead times for European procurement offices while concentrating working capital demands on Ludhiana and Surat manufacturers. Shaoxing, Tiruppur, and Surat form the geographic core for wet processing and differential-drafting capacity. Metallized nylon filament, azo dye formulations, and cellulosic pulp constitute critical input dependencies. Single-source vulnerability concentrates in Zhejiang province dyeing infrastructure exposed to MEE enforcement actions. Distribution runs through wholesale trading hubs in Surat and Ludhiana feeding integrated apparel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air-jet texturing advancement represents a high-growth disruption reshaping competitive positioning as mechanical twisting becomes obsolete for dimensional stability. REACH and EU Green Deal circularity mandates accelerate this inflection by rewarding mono-material constructions and waterless coloration.
For Market Incumbents: Fortify captive dyeing capacity in Ludhiana and Surat to absorb inventory risk from consolidating European vendor lists. Invest in solution-dyed filament backward integration to bypass Shaoxing wet-processing concentration and defend margins against petrochemical volatility.
For New Entrants and Emerging Players: Lead with certified natural-fancy-yarn positioning in São Paulo and Minas Gerais craft retail corridors where ANVISA disclosure frameworks lag REACH stringency. Target digital textile printing convergence for on-demand color customization without 12-16 week qualification cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated Indian spinners with BIS certification and documented REACH compliance over fragmented toll-dyeing processors. Long-term viability hinges on mono-material reformulation readiness for EU design-for-recyclability standards. Watch solution-dyed polyester adoption rates in European fast-fashion programs as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solution-Dyed Filament | Eliminates Shaoxing wet-processing dependency and reduces REACH documentation burden for export programs. |
| Captive Dyeing Capacity Expansion | Absorbs inventory risk transferred from consolidating Milan and Paris luxury house procurement offices. |
| REACH Compliance Certification Investment | Secures vendor list eligibility as European brands consolidate around three-to-four strategic partners. |
| Digital Textile Printing Convergence | Enables on-demand color customization for small-batch producers bypassing lengthy ISO 105-C06 testing. |
| Mono-Material Yarn Reformulation | Positions suppliers ahead of EU Green Deal circularity mandates favoring recyclable single-fiber constructions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, BIS certification registries, and EU ECHA SVHC disclosure databases. Primary interviews with spinning mill operations directors, European knitwear procurement managers, and dyeing facility compliance officers informed capacity and qualification assessments. Secondary validation drew from textile industry association reports, SEC filings of listed fiber producers, and MEE wastewater enforcement records. Bottom-up capacity modeling triangulated against top-down trade flow analysis.
Segmentation dimensions modeled include product type, application, distribution channel, and end user sophistication across the analysis window. CAGRs derived from differential adoption curves by certification tier and regional regulatory cluster. Forecast inputs incorporated air-jet texturing penetration rates and solution-dyed filament substitution elasticities.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement stringency or petrochemical price stability would require recalibration. Forecasts reflect assumptions on regulatory divergence between European chemical restrictions and Asian production incentives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market