
 Linen Fabric Market | 2026-2036
Linen Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Linen Fabric Market Intelligence
The OEKO-TEX Standard 100 certification is collapsing the price premium previously held by specialist European mills, enabling broader competition. This allows large-scale manufacturers like Zhejiang Jiersheng Textile Technology Co., Ltd to compete directly on established quality benchmarks. Baird McNutt sustains its market position through its heritage brand and focus on Irish linen for the luxury apparel sector. Meanwhile, Lenzing Group differentiates with its TENCEL Lyocell and linen blends, offering enhanced softness and performance characteristics.
Linen fabric is a natural textile derived from the cellulose fibers of the flax plant, Linum usitatissimum. It is renowned for high tensile strength and exceptional absorbency, making it ideal for warm-weather clothing and home goods. The fashion apparel and home textiles segments represent the largest end-use categories for linen. Blended linen products, which combine flax with cotton or viscose, are gaining market share due to improved wrinkle resistance and greater cost-effectiveness.
Market access is governed by multiple regulatory frameworks. The EU's REACH regulation restricts the use of certain chemicals in textile processing, while the U.S. Federal Trade Commission (FTC) mandates accurate fiber content labeling. In China, GB standards for textiles ensure product safety and quality for consumers. Stakeholder success will hinge on securing stable access to high-quality flax fiber amidst climate-driven supply volatility and agricultural shifts.
Market Dynamics
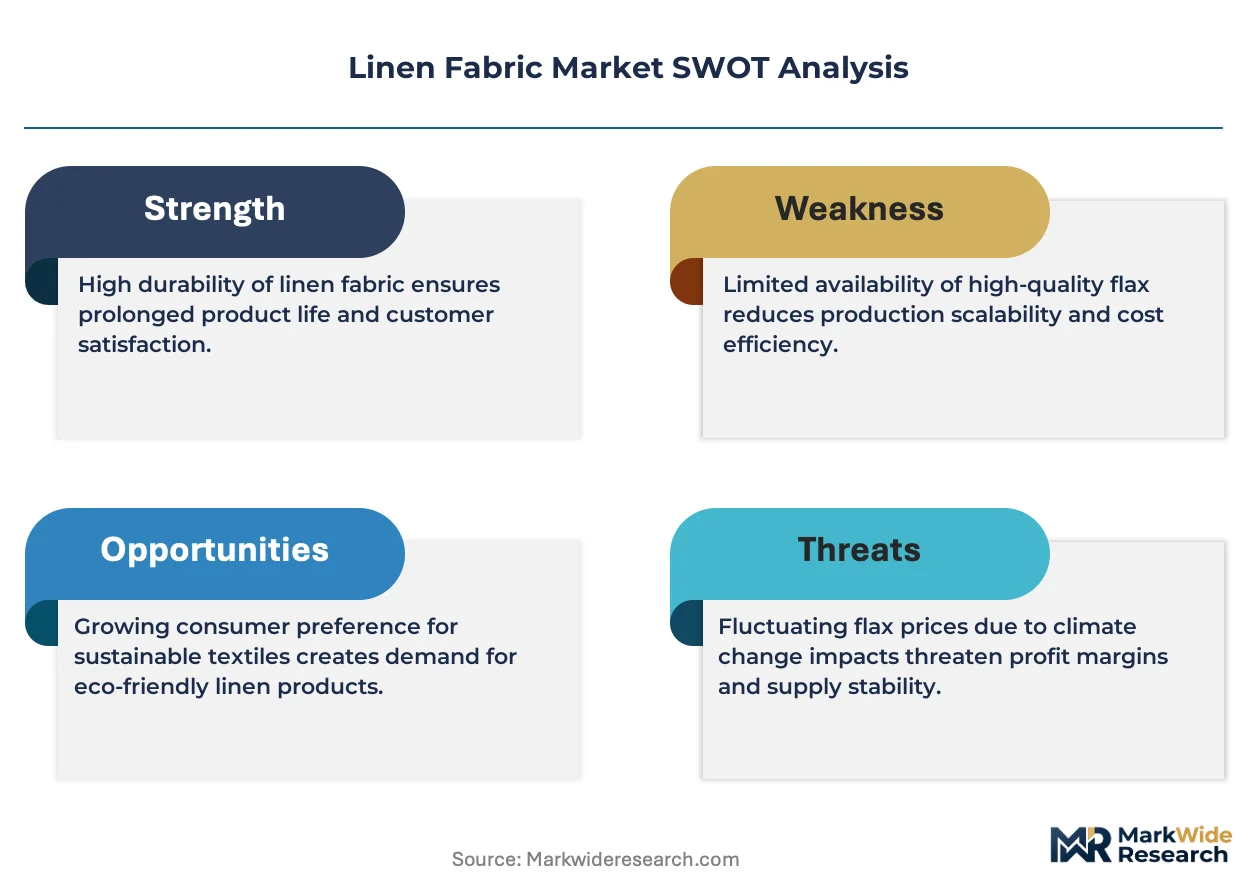
The linen fabric market is shaped by the fundamental tension between rising consumer demand for natural, sustainable textiles and the agricultural volatility of its core input, flax fiber. Climate variability directly impacts flax yields and quality, creating supply chain instability that contrasts with the steady pull from the home textiles and fashion sectors.
Growth Catalysts
- Sustainable Consumerism:A strong consumer preference for natural, biodegradable, and durable fibers in the home textiles and apparel segments acts as a primary demand driver, aligning with broader wellness and environmental trends.
- Processing Innovations:Advancements in enzymatic retting and modernized spinning technologies are enhancing production efficiency, improving fiber consistency, and reducing the environmental footprint of linen manufacturing.
- Quality Standardization:The adoption of certifications like OEKO-TEX Standard 100 provides a common quality benchmark, enabling new manufacturers to compete with established mills and increasing buyer confidence across international markets.
Market Restraints
- Input Supply Volatility:The cultivation of high-quality flax is geographically concentrated and highly susceptible to adverse weather conditions, leading to unpredictable raw material costs and supply disruptions.
- High Production Costs:Linen processing remains more labor-intensive and time-consuming compared to mass-produced textiles like cotton or polyester, contributing to a higher price point that can limit mass-market adoption.
- Substitution from Blends:The market faces competition from linen-blend fabrics, which often incorporate cotton or viscose to improve wrinkle resistance and lower costs, appealing to more price-sensitive consumers.
Strategic Opportunities
- Technical Textile Applications:Linen's inherent properties, such as high tensile strength and moisture absorbency, create opportunities for use in specialized applications like composites, geotextiles, or performance athletic wear.
- Advanced Material Blends:Developing innovative blends that combine linen with performance fibers like TENCEL Lyocell can create new product categories with enhanced softness, drape, and moisture management capabilities. *Emerging Market Penetration: Untapped demand exists in affluent consumer markets in the Middle East and Asia-Pacific, where the appeal of natural luxury fibers for fashion and interior design is expanding.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers face the complexity of adhering to disparate chemical and labeling regulations, such as the EU's REACH framework, U.S. FTC rules, and China's GB standards.
- Supply Chain Traceability:Establishing and verifying transparent farm-to-fabric supply chains to meet consumer demand for provenance is a significant operational and logistical challenge for global producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linen Fabric Market |
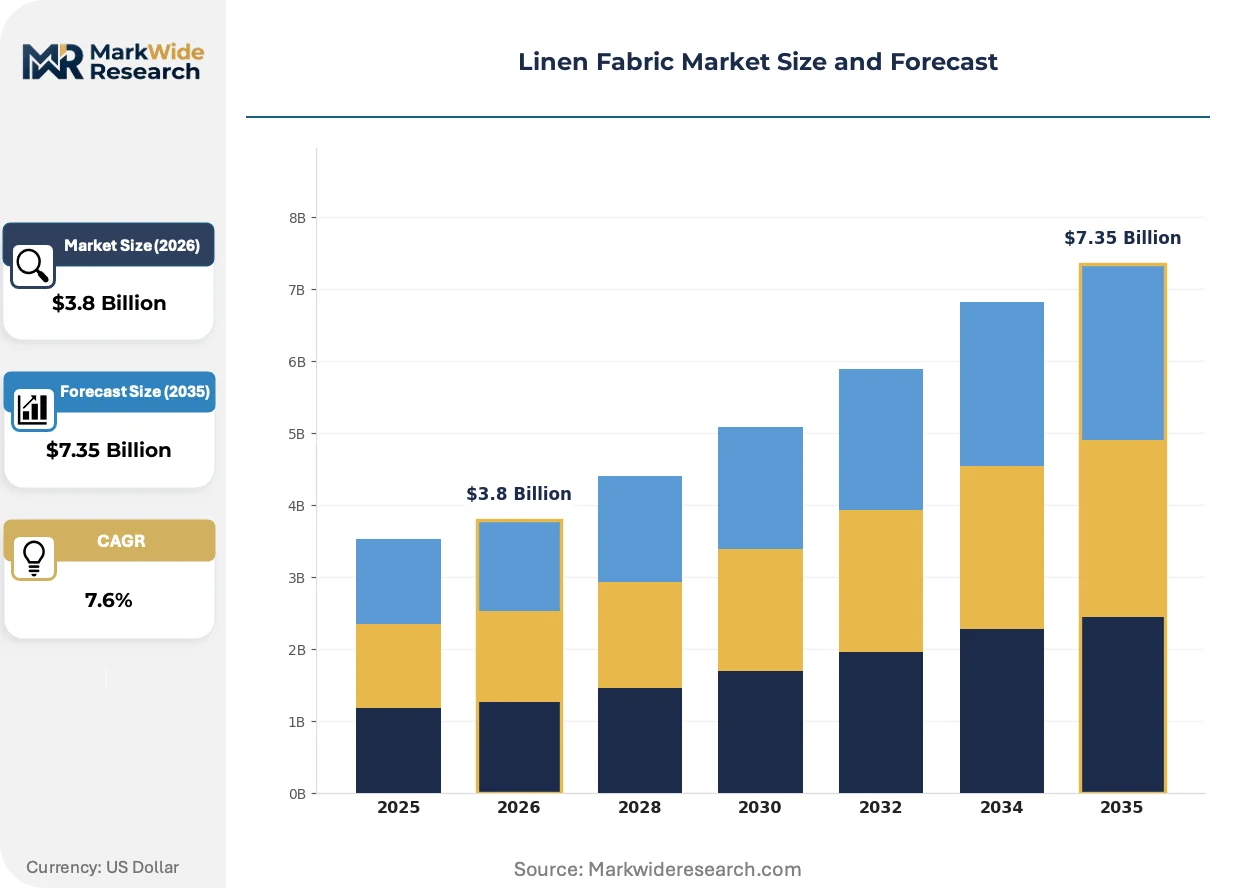
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yarn Dyed Linen, Washed Linen, Plain Linen, Slub Linen, Blended Linen End Use Industry: Home Textiles, Fashion Apparel, Industrial Textiles, Automotive Interiors, Hospitality Furnishings Fabric Weight: Lightweight, Medium Weight, Heavyweight, Ultra Heavy, Semi Sheer Distribution Channel: Wholesale Distributors, Online Retailers, Specialty Stores, Department Stores, Direct-to-Consumer |
| Companies Covered | Zhejiang Jiersheng Textile Technology Co., Ltd, Libeco, Baird McNutt, LinenMe, Camira Fabrics, Forster Rohner, Lenzing Group, Shanghai Jiahua Group Co., Ltd., Shandong Shengrun Textile Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linen Fabric Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards circularity and traceability, driven by technological advancements in fiber processing and stringent regulatory oversight. These forces are compelling a reevaluation of traditional production methods and supply chain structures, favoring transparency and sustainability.
Advanced bio-retting techniques, which use specific enzymes to break down the pectin binding flax fibers, are gaining traction. Eco-conscious brands in the fashion and home goods sectors are increasingly specifying fabrics made with these methods. This technology is decomposing the reliance on traditional, water-intensive dew or water retting processes, enabling faster, more controlled, and less polluting fiber separation.
The European Union’s REACH regulation is setting a de facto standard for chemical safety in textiles processed or sold within the bloc. This framework compels manufacturers to eliminate or substitute a wide range of restricted substances, requiring rigorous supply chain documentation. The home textiles and children's apparel segments are most directly impacted, accelerating the adoption of certifications to demonstrate compliance.
A distinct shift in buying behavior toward verifiable provenance is altering procurement strategies. This trend disrupts opaque, multi-layered distribution models, creating an advantage for suppliers who can offer farm-to-garment traceability. This demand for transparency is most pronounced in the European luxury apparel sector, where heritage and origin are critical components of brand value.
Linen Fabric Market Segmentation
Understanding the distinct segments within the linen fabric market reveals where value is created and where competitive pressures are most acute. Each category highlights specific material characteristics, end-user applications, or market access points that drive purchasing decisions and influence strategic investments.
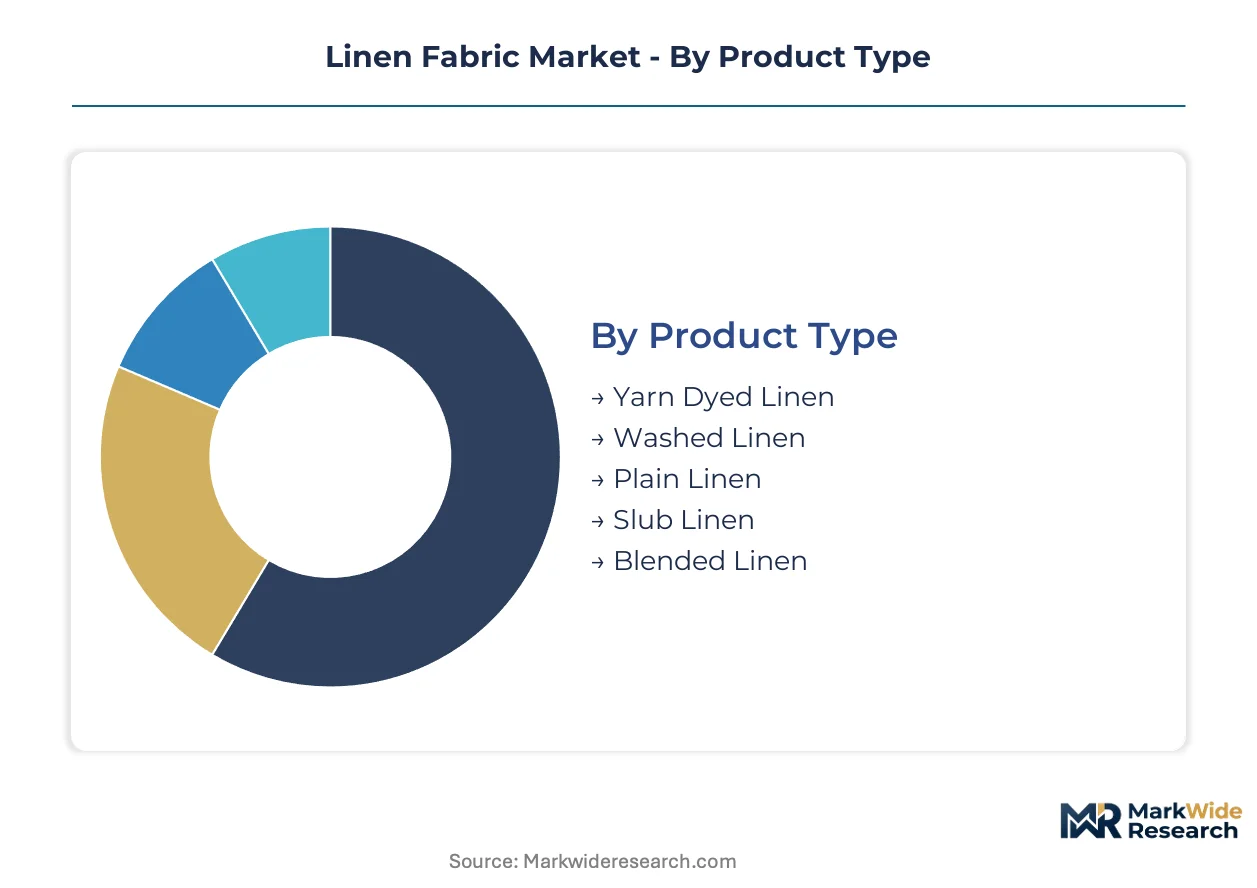
Product Type:
The product type segment faces substitution pressure from blended materials that offer enhanced properties or lower costs, challenging traditional pure linen offerings.
- Blended Linen:These fabrics combine flax fibers with cotton or viscose, enhancing wrinkle resistance and offering greater cost-effectiveness for mass-market applications. Demand concentrates in fashion apparel and home textiles, driven by consumer preference for practicality and affordability.
- Washed Linen:This linen undergoes a special finishing process to achieve enhanced softness, a relaxed drape, and a characteristic crinkled texture, making it highly desirable for luxury apparel and bedding in Europe. The process improves comfort and reduces initial stiffness, appealing to discerning consumers.
- Yarn Dyed Linen:Threads are dyed before weaving, creating intricate patterns and colorfastness often utilized in premium apparel and decorative home furnishings.
- Plain Linen:Unadorned and natural, this fundamental linen form is widely used in basic apparel, kitchen textiles, and as a base for further finishing.
- Slub Linen:Characterized by its intentionally irregular, textured surface, slub linen adds visual interest to casual wear and rustic home decor items.
Plain Linen retains volume leadership; Blended Linen holds the steepest expansion curve.
End Use Industry:
Demand concentration across end-use industries varies significantly, with consumer-facing sectors driving the largest volumes and specialized applications dictating niche growth.
- Home Textiles:This category encompasses bedding, upholstery, curtains, and kitchen linens, where linen's durability and absorbency are highly valued. Consumer preference for natural, sustainable materials in interior design drives demand in European markets like France and Italy.
- Fashion Apparel:Linen is a staple for warm-weather clothing, including shirts, dresses, and trousers, prized for its breathability and elegant drape. The luxury apparel sector, particularly in Europe, values linen's heritage and natural aesthetic.
- Industrial Textiles:Linen finds specialized use in applications requiring high tensile strength and moisture wicking, such as canvas, filtration fabrics, and technical reinforcements.
- Hospitality Furnishings:Hotels and restaurants utilize linen for tablecloths, napkins, and bed linens due to its durability, absorbency, and sophisticated appearance.
- Automotive Interiors:Limited but emerging applications for linen exist in automotive upholstery and trim, driven by sustainability trends and demand for natural fibers.
Demand for Home Textiles drives significant market volume, while Industrial Textiles presents specialized growth opportunities.
Fabric Weight:
Functional requirements and aesthetic preferences dictate the market's differentiation by fabric weight, influencing specific product applications.
- Lightweight:These fabrics, typically under 150 GSM, offer exceptional breathability and drape, making them ideal for summer clothing and delicate home accessories. Consumer demand in warmer climates drives this segment.
- Heavyweight:Fabrics above 250 GSM provide superior durability and structure, suitable for upholstery, outerwear, and industrial applications. Their robustness appeals to long-lasting product requirements.
- Medium Weight:Ranging from 150-250 GSM, this versatile category suits a broad array of apparel and home textile products, balancing drape with durability.
- Semi Sheer:Very fine and translucent linen fabrics are used for delicate curtains, overlays, and lightweight scarves, prized for their ethereal quality.
- Ultra Heavy:Exceeding 350 GSM, these dense linens are employed in highly demanding industrial uses, rugged upholstery, or specialized protective gear.
Lightweight linen caters to high-volume seasonal demand, whereas Heavyweight linen secures premium applications.
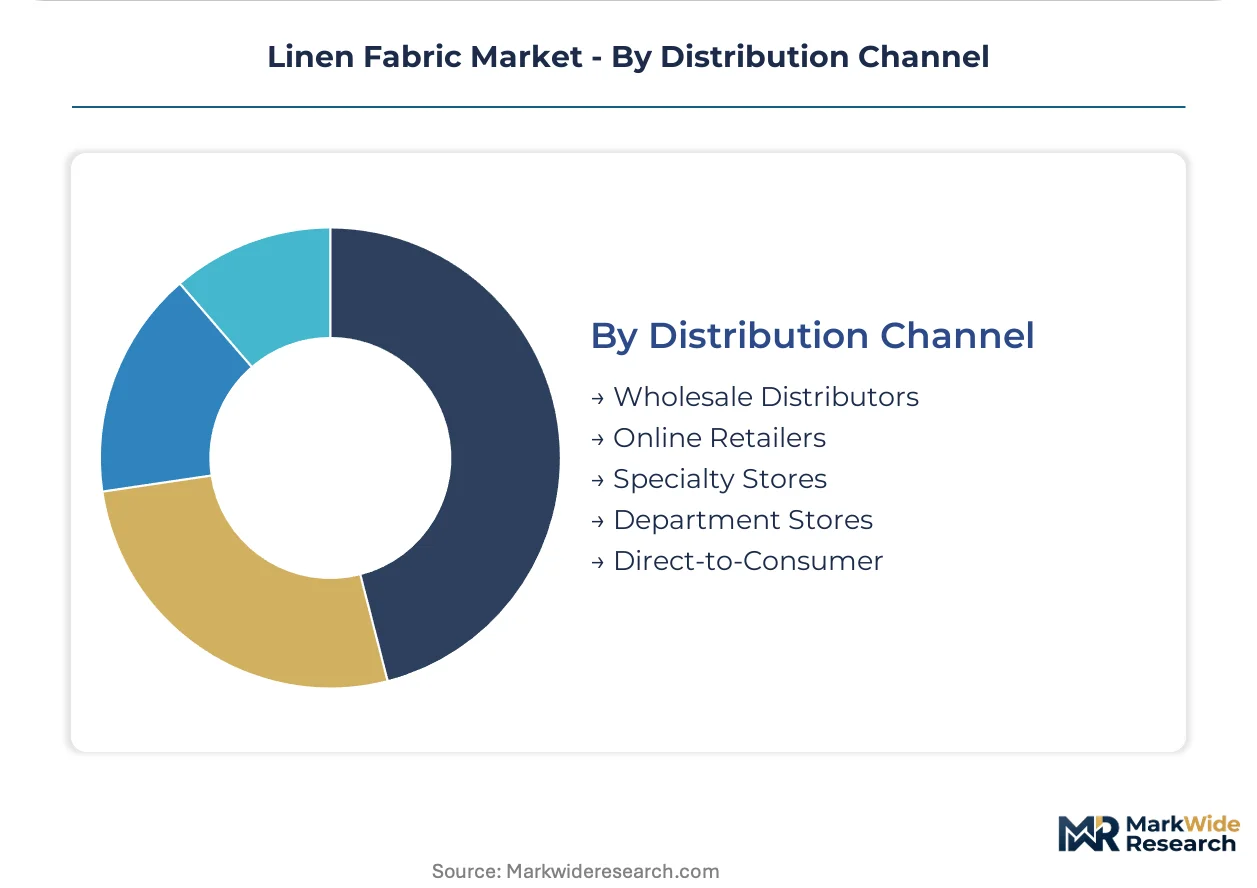
Distribution Channel:
Market access strategies through different distribution channels reflect varying customer segments and purchasing behaviors, from bulk procurement to direct consumer engagement.
- Online Retailers:This channel provides broad geographic reach and convenience, appealing to a tech-savvy consumer base seeking diverse product offerings. The digital storefronts enable manufacturers to bypass traditional intermediaries, offering competitive pricing.
- Wholesale Distributors:These entities manage large-volume transactions, supplying fabric to apparel manufacturers, home textile producers, and industrial users. This channel remains critical for efficient bulk procurement and supply chain management across global markets.
- Specialty Stores:These boutiques focus on curated selections of high-end linen products, often emphasizing craftsmanship and unique designs for discerning consumers.
- Department Stores:Offering a wide range of linen products from various brands, department stores serve a broad customer base looking for convenience and brand variety.
- Direct-to-Consumer:Brands increasingly use their own websites and flagship stores to sell directly, fostering brand loyalty and capturing higher margins.
Wholesale Distributors channels dominate market reach, but Online Retailers capture emerging consumer preferences for direct engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for linen fabric skews heavily towards European markets, driven by established textile industries and strong consumer preferences for natural fibers. These regions often dictate quality benchmarks and sustainability standards for the global market. Demand also expands in key Asian and North American consumer bases.
France
Demand for high-quality linen in France is driven by its strong heritage in luxury fashion and home textiles. The EU Green Deal encourages sustainable textile production practices. Northern France, particularly Normandy, remains a key flax cultivation and processing region, supporting local textile mills.
Italy
Italian consumers value linen for its aesthetic appeal and breathability in high-end fashion apparel and sophisticated home furnishings. REACH regulations influence chemical usage in Italian textile manufacturing. The Lombardy region, with its textile clusters, integrates linen into diverse fabric blends for designers.
China
China's large domestic market drives demand for both pure and blended linen, especially in fashion apparel and home goods. GB standards for textiles ensure product safety and quality across the country. Zhejiang and Shandong provinces house significant textile manufacturing hubs, including large-scale linen producers.
United States
Consumer preference for natural and sustainable home textiles and casual apparel fuels linen demand in the United States. The U.S. Federal Trade Commission (FTC) mandates accurate fiber content labeling for all textile products. Major retail hubs like New York City and Los Angeles influence design trends and material sourcing for linen products.
Linen Fabric Market Key Industry Players
Player mix skews toward a tiered structure, with established European mills competing alongside large-scale Asian manufacturers and specialized blend innovators. The market exhibits characteristics of both fragmentation at the lower end and consolidation among premium players. Strategic partnerships and technology licensing are common competitive moves.
Scale-driven manufacturers like Zhejiang Jiersheng Textile Technology Co., Ltd. represent a significant force, leveraging efficient production to meet broad market demand. Baird McNutt exemplifies a heritage brand, focusing on premium Irish linen for luxury segments. Lenzing Group, known for its TENCEL Lyocell, innovates through advanced material blends, enhancing linen's performance characteristics for new applications.
| Leading Market Players |
|---|
| Zhejiang Jiersheng Textile Technology Co., Ltd |
| Libeco |
| Baird McNutt |
| LinenMe |
| Camira Fabrics |
| Forster Rohner |
| Lenzing Group |
| Shanghai Jiahua Group Co., Ltd. |
| Shandong Shengrun Textile Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Six-month raw material lead times for flax fiber directly influence the linen fabric market's supply chain shape and pricing power. This extended cultivation and processing cycle creates inherent volatility, impacting manufacturers' ability to secure stable input costs and influencing final product pricing for consumers.
Pricing Analysis
Cost-plus contracts, often indexed to flax fiber prices, define a significant portion of bulk linen transactions. Price differentiation stems from quality grade, with OEKO-TEX Standard 100 certification commanding a premium, and heritage brand value, as seen with Baird McNutt. Pricing pressure intensifies for mass-market blended linen products due to competition from alternative fibers. Luxury apparel and high-end home textiles, however, exhibit lower buyer price sensitivity, prioritizing quality and provenance over cost.
Supply Chain Analysis
France and Belgium anchor high-quality flax cultivation and initial processing, feeding European textile clusters. The linen fabric supply chain draws from specific raw material dependencies on flax fiber and specialized retting enzymes. Climate variability poses a significant supply chain risk, leading to unpredictable raw material availability and cost fluctuations. Distribution runs through wholesale distributors for large-volume transactions, while online retailers increasingly serve direct-to-consumer preferences for finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by a strong consumer demand-side shift towards natural, sustainable, and traceable textiles, creating distinct niches across product types and end-use applications.
For Market Incumbents: Fortify existing market positions by investing in advanced bio-retting technologies to reduce environmental impact and improve fiber consistency. Secure long-term flax fiber supply agreements to mitigate input supply volatility, a persistent threat to stable production. Expand OEKO-TEX certification across product lines to reinforce quality benchmarks against large-scale manufacturers like Zhejiang Jiersheng Textile Technology Co., Ltd.
For New Entrants and Emerging Players: Differentiate on verifiable provenance and eco-conscious branding to target the growing sustainable home textiles segment. Focus on developing advanced material blends, such as linen with TENCEL Lyocell, to penetrate the performance apparel market. Untapped demand in affluent Middle Eastern and Asia-Pacific consumer bases offers a white-space target for luxury linen products, emphasizing natural fibers and design aesthetics.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainable materials play because consumer preferences for natural, biodegradable fibers continue to strengthen globally. Target acquisition profiles include vertically integrated flax processors with proprietary retting technologies or specialized manufacturers of innovative linen blends. The expansion of EU REACH-like chemical safety regulations to new geographies will serve as a critical signal to watch for broader market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Retting Technology | Enhances fiber quality and reduces the environmental footprint of flax processing. |
| Develop Advanced Linen Blends | Creates new product categories with enhanced performance characteristics for diverse applications. |
| Expand OEKO-TEX Certification | Strengthens market access and buyer confidence by meeting global quality benchmarks. |
| Secure Long-Term Flax Supply | Mitigates raw material price volatility and ensures production stability for manufacturers. |
| Target Emerging Luxury Markets | Captures untapped demand for natural, high-end textiles in the Middle East and Asia-Pacific. |
Research Approach
Initial hypotheses were tested against primary input from flax farmers, textile mill operators, fashion designers, home textile buyers, and regulatory affairs specialists, then refined through iterative analysis. This approach combined in-depth interviews with industry stakeholders and rigorous secondary validation. Bottom-up and top-down triangulation ensured comprehensive market sizing and segmentation accuracy.
Variance decomposition across the analysis window informed the forecast framework, modeling growth drivers and restraints for each segment. Segment dimensions included product type, end-use industry, fabric weight, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected demand shifts, and key forecast inputs like flax yield data and consumer sustainability preference indices.
Material uncertainties — including climate change impact on flax cultivation and global economic downturns affecting luxury spending — sit outside the modeled envelope, influencing potential market shifts. Forecasts reflect assumptions documented in the full report. Recalibration cycles align with material shifts in climate patterns and consumer purchasing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Knitted Fabric Market