
 Outdoor Fabric Market | 2026-2036
Outdoor Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Fabric Market Analysis
Direct-to-contractor distribution is tilting as specialty textile mills bypass traditional distributors to serve large hospitality and marine OEMs directly. Glen Raven leverages its vertically integrated manufacturing base in North Carolina to control quality from fiber to finished coated fabric. Serge Ferrari Group anchors its competitive stance through advanced PVDF and silicone surface treatments for architectural membrane applications. Sattler AG competes from its Austrian production hub, emphasizing precision coating lines for premium awning and marine segments.
Outdoor fabric denotes engineered textile substrates—typically woven polyester, solution-dyed acrylic, or vinyl-laminated scrims—treated with fluoropolymer or acrylic coatings to achieve water repellency, UV stability, and fungal resistance for prolonged exterior exposure. These materials serve as protective barriers in architectural shading, marine enclosures, and recreational shelters where dimensional stability under cyclic loading and photodegradation determines service life. Awning fabric and marine canvas represent mature, high-margin categories where specification-grade certifications command pricing premiums from architects and boat builders. Polyester and acrylic materials dominate volume, though vinyl-coated polyester is gaining specification share in commercial tenting and industrial tarp applications where weldability and chemical resistance outweigh breathability requirements.
The EU Green Deal and REACH chemical registration frameworks restrict per- and polyfluoroalkyl substance use in textile coatings, compelling reformulation toward C6 fluorocarbon or silicone-based alternatives. In the United States, the EPA administers TSCA Section 5 premanufacture notification requirements for novel coating chemistries, while California's Proposition 65 labeling mandates influence national product liability exposure. Stakeholders must monitor evolving state-level chemical disclosure rules and third-party certification migrations from OEKO-TEX Standard 100 to bluesign-approved supply chains.
Market Dynamics
REACH chemical registration frameworks and the EU Green Deal are forcing reformulation of fluoropolymer coatings across the supply base, compressing margins for mills dependent on legacy C8 chemistries while creating first-mover advantages for silicone and C6 fluorocarbon specialists.
Growth Catalysts
- EU Green Deal product sustainability requirements:Mandates for recycled content and bio-based feedstocks are pulling polyester and acrylic manufacturers toward circular production models certified under bluesign and OEKO-TEX Standard 100.
- Hospitality canopy procurement:Coastal restaurant operators in Spain, Italy, and Greece are expanding covered outdoor dining footprints, driving specification-grade awning fabric volumes for marine-grade UV resistance.
- Solution-dyed acrylic technology:Pigment-in-fiber processes eliminate post-weave dyeing, reducing water consumption and enabling darker colorfast shades for architectural membrane applications.
Market Restraints
- PTA and MEG feedstock volatility:Purified terephthalic acid and monoethylene glycol prices track naphtha and paraxylene markets, compressing polyester fabric margins when oil benchmarks spike.
- Coating chemical supply concentration:Fluoropolymer resin production clusters in Japan and Germany, exposing mills to single-source risk and extended lead times for PVDF and FEVE dispersions.
- Weldability-breathability tradeoff:Vinyl-coated polyester achieves RF and hot-air weld seams for commercial tenting but traps condensation, limiting specification in humid-climate marine enclosures.
Strategic Opportunities
- Bio-based acrylic chemistry development:Fermentation-derived acrylonitrile from agricultural waste streams offers pathway to petroleum-independent fiber production for premium awning segments.
- Direct-to-OEM distribution bypass:Specialty mills are establishing captive sales forces to serve large hospitality and marine original equipment manufacturers, capturing distributor margins.
- Municipal marina refurbishment in Germany:Federal and state infrastructure programs sustain marine canvas and tarp fabric demand for dock canopy replacement and boat cover OEM supply.
Industry Challenges
- Coating reformulation timeline compression:REACH sunset dates for long-chain fluorocarbons force simultaneous R&D on C6 and silicone alternatives without guaranteed performance parity.
- Certification migration complexity:Mills must maintain dual OEKO-TEX and bluesign supply chain audits during transition periods, diverting quality assurance resources from production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Fabric Market |
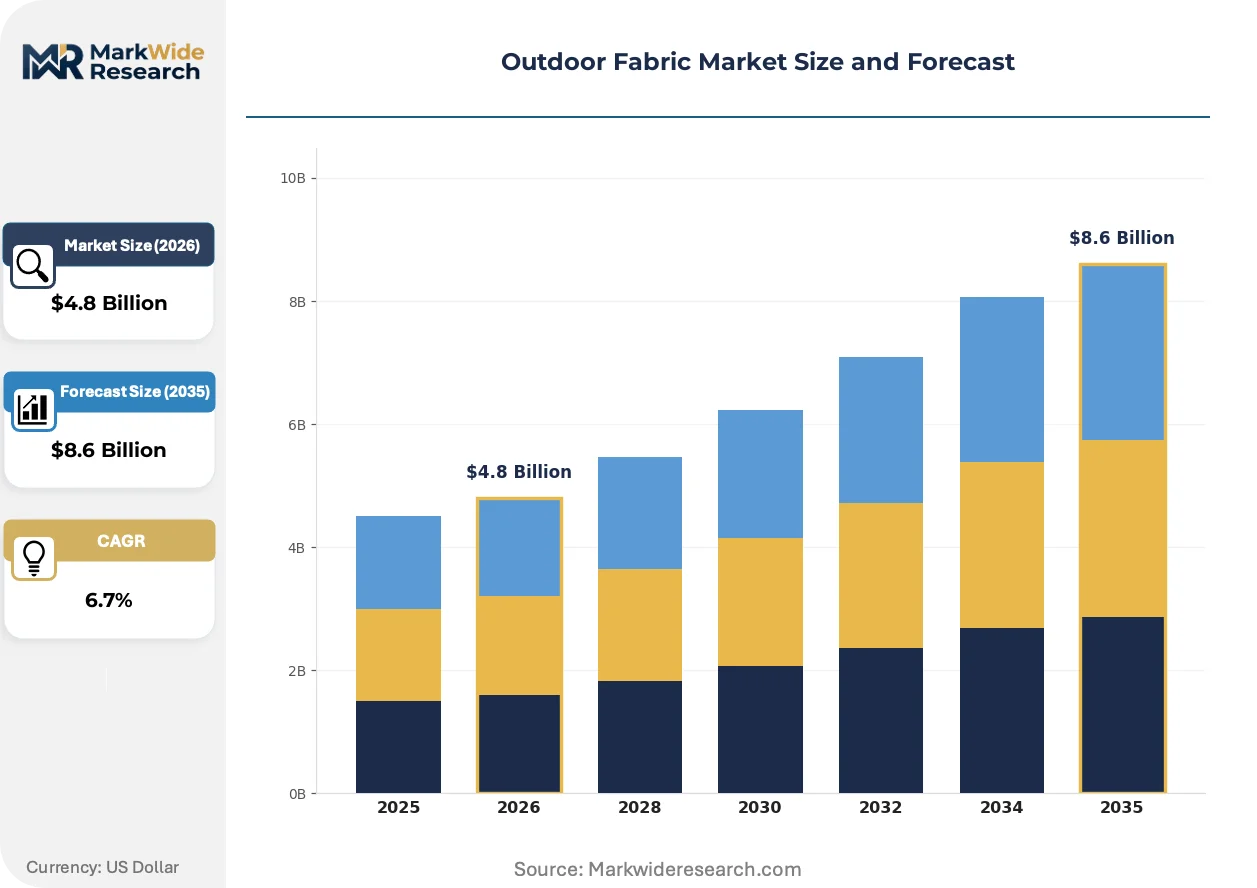
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canopy Fabric, Awning Fabric, Marine Canvas, Tarp Fabric Material: Polyester, Acrylic, Vinyl, Canvas Application: Tents, Cushions, Umbrellas, Outdoor Furniture End User: Residential, Commercial, Hospitality, Automotive |
| Companies Covered | Glen Raven, Serge Ferrari Group, Sattler AG, Sauleda, Dickson Constant, Mehler Texnologies, Twitchell Corporation, Herculite Products, Recasens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Fabric Market Emerging Trajectories
Coating chemistry migration and distribution channel restructuring are reshaping competitive positioning. Mills that control formulation IP and direct buyer relationships are capturing margin from legacy distributor-dependent competitors.
Perfluorinated coating technology is migrating from C8 fluorocarbon architectures toward C6 and silicone-based surface treatments. German and Austrian specialty mills are accelerating adoption to maintain EU market access ahead of substance restrictions. This chemistry shift is compressing the addressable market for mills without in-house formulation capabilities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorocarbon options for textile finishing. The regulation forces coating houses to validate alternative chemistries through accelerated weathering and fungal resistance testing. Architectural membrane and marine canvas segments face the steepest compliance timelines and certification costs.
Buyer concentration among large hospitality and marine OEMs is consolidating procurement decisions toward direct mill relationships. Distributors serving mid-scale awning fabricators and boat builders are losing volume to manufacturer sales forces. This channel shift is most visible in Germany, where municipal procurement rules favor supplier direct bidding for public infrastructure projects.
Outdoor Fabric Market Segmentation
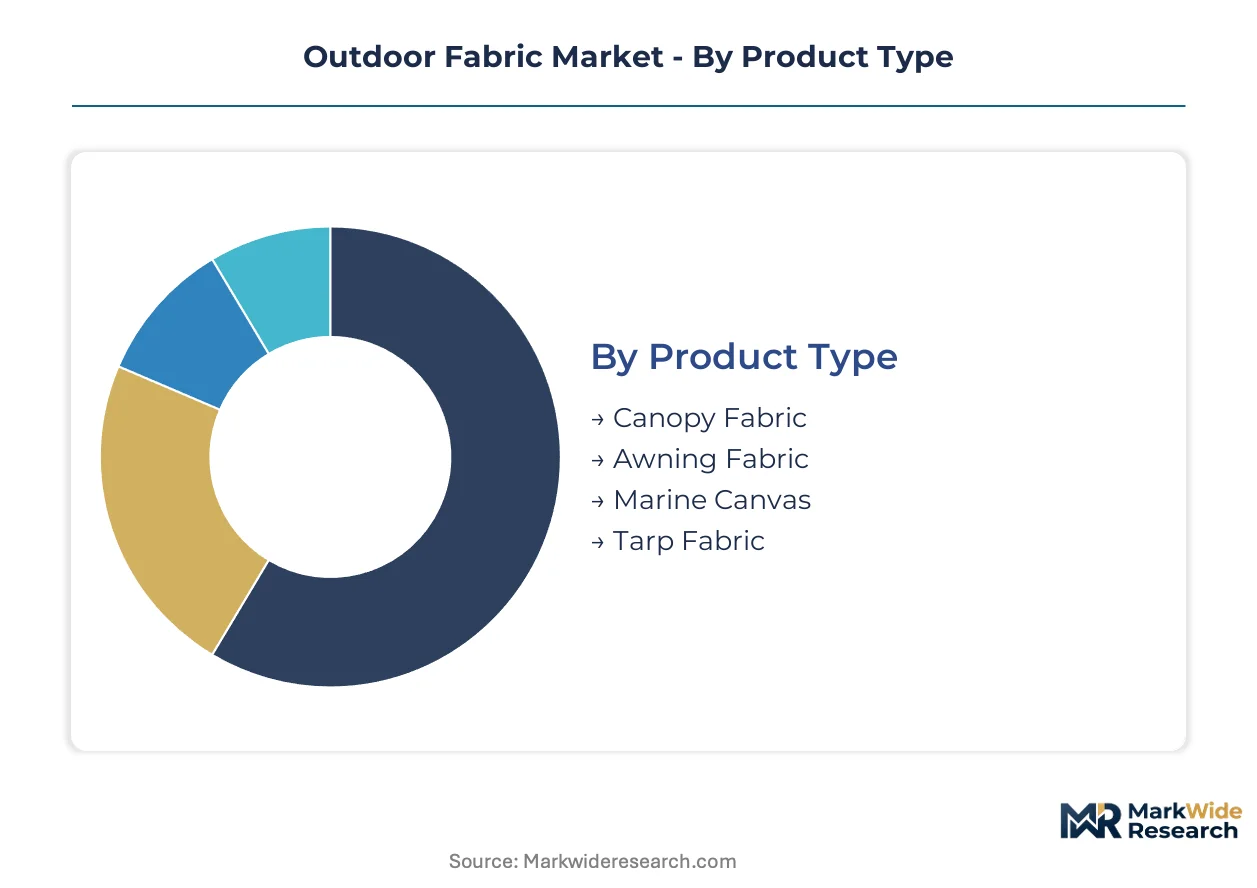
Outdoor fabric demand fragments across protective shelter, marine enclosure, and decorative cushioning applications where material specifications diverge on UV stability, weldability, and breathability requirements. Procurement patterns in this market track end-use durability standards and regional regulatory compliance timelines rather than commodity pricing alone.
Product Type:
The use-case spectrum spans permanent architectural shading, mobile marine protection, and temporary weather barriers with distinct performance certification requirements.
- Canopy Fabric:Woven polyester or vinyl-laminated scrims treated with fluoropolymer coatings achieve structural load-bearing capacity for tensioned membrane structures. Municipal procurement in Germany for marina dock coverings and public pavilion installations sustains specification-grade orders requiring 10-year colorfast warranties.
- Awning Fabric:Solution-dyed acrylic dominates fixed and retractable architectural shading where pigment-in-fiber construction eliminates post-weave dyeing. Coastal hospitality operators in Spain, Italy, and Greece are expanding covered dining footprints, pulling marine-grade UV-resistant specifications.
- Marine Canvas:Acrylic and coated polyester blends engineered for salt spray resistance and dimensional stability under cyclic wind loading. Breathability requirements in humid-climate enclosures constrain vinyl-coated alternatives despite superior weld seam strength.
- Tarp Fabric:Vinyl-coated polyester or polyethylene laminates prioritize RF weldability and chemical resistance over aesthetic performance. Industrial and commercial tenting applications specify these materials where rapid deployment and hose-down cleaning outweigh breathability concerns.
Established volume favors awning fabric; emerging adoption favors canopy fabric as municipal infrastructure investment accelerates.
Material:
Cost tier stratification separates petroleum-derived synthetics from natural fiber alternatives with divergent coating compatibility and end-of-life pathways.
- Polyester:Purified terephthalic acid and monoethylene glycol polymerization yields high-tenacity filament yarns for coated scrim constructions. Feedstock volatility tied to naphtha and paraxylene benchmarks compresses margins during oil price spikes.
- Acrylic:Acrylonitrile-based fibers with solution-dyed coloration achieve superior UV resistance and fungal immunity for premium awning and marine segments. REACH restrictions on fluoropolymer coatings are forcing simultaneous reformulation of fiber substrates and surface treatments.
- Vinyl:Polyvinyl chloride coatings laminated to polyester base fabrics enable hot-air and RF welding for commercial tenting and industrial tarp applications. The weldability-breathability tradeoff limits specification in marine enclosures where condensation management is critical.
- Canvas:Cotton or cotton-blend natural fibers retain heritage specification in recreational and decorative segments where tactile aesthetics outweigh synthetic durability. Bio-based coating compatibility and compostability appeal to sustainability-certified procurement channels.
Polyester and acrylic capture volume leadership; canvas is climbing the fastest as circular economy requirements penetrate specification standards.
Application:
Customer type and replacement cycle frequency separate temporary event infrastructure from permanent residential installations.
- Tents:Commercial and event tenting specifies vinyl-coated polyester for weld seam integrity and rapid deployment logistics. RF welding compatibility enables modular frame systems with sealed weatherproof joints.
- Cushions:Upholstery-grade acrylic and solution-dyed polyester serve outdoor furniture and marine seating where stain resistance and quick-dry performance determine replacement intervals. Pigment saturation depth affects colorfastness under prolonged UV exposure.
- Umbrellas:Cantilever and market umbrella canopies demand lightweight acrylic with high tensile strength for spanning unsupported spans. Coastal hospitality procurement concentrates specification for wind-load resistance and marine-grade hardware compatibility.
- Outdoor Furniture:Sling and cushion fabrics require abrasion resistance and dimensional stability under body weight loading and temperature cycling. Solution-dyed constructions eliminate surface pigment layers vulnerable to wear-through.
Tents and cushions dominate current procurement; umbrella applications are gaining share fastest as hospitality outdoor dining expansion accelerates.
End User:
Volume scale and specification authority concentrate among institutional buyers with multi-year framework agreements versus fragmented residential replacement demand.
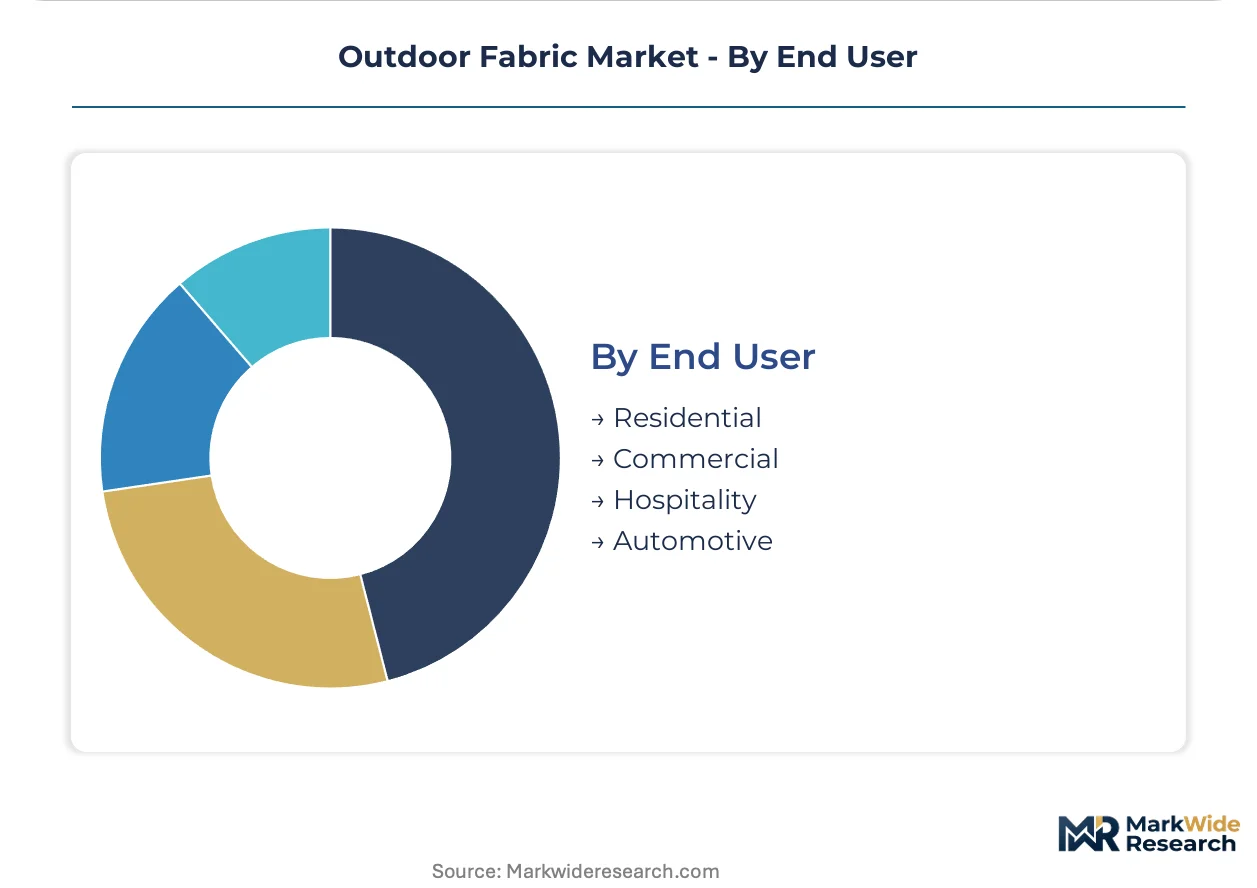
- Residential:Individual consumers purchase through retail and specialty dealer channels for patio furniture, recreational vehicle covers, and domestic awnings. Price sensitivity and seasonal purchasing patterns characterize this segment.
- Commercial:Corporate facilities managers procure branded shading and signage fabrics with corporate identity color matching requirements. Framework agreements with national awning installers consolidate supplier selection.
- Hospitality:Hotel and restaurant groups specify marine-grade performance for coastal properties with salt spray and intense UV exposure. Direct mill relationships are displacing distributor intermediaries for large portfolio operators.
- Automotive:Convertible top and recreational vehicle cover manufacturers demand coated fabrics with precise elongation characteristics for automated cutting and sewing lines. OEM qualification timelines extend 18-24 months for new material approvals.
Hospitality and commercial procurement concentrate volume authority; residential demand remains fragmented across seasonal replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mills command specification-grade pricing premiums for marine canvas and architectural membrane fabrics, while Chinese producers compete on vinyl-coated polyester volume for commercial tenting and industrial tarp applications.
Germany
Federal marina refurbishment programs and municipal outdoor infrastructure investment sustain demand for dock canopy and public pavilion fabrics. The EU Green Deal's product sustainability requirements push manufacturers toward recycled polyester and bio-based acrylic chemistries certified under bluesign standards. Production concentrates in North Rhine-Westphalia and Bavaria, where precision coating lines serve premium awning and marine segments.
United States
Coastal hospitality operators in Florida and California expand covered outdoor dining footprints, driving marine-grade UV-resistant awning procurement. The EPA administers TSCA Section 5 premanufacture notification requirements for novel coating chemistries, while California's Proposition 65 labeling mandates influence national product liability exposure. North Carolina hosts vertically integrated manufacturing bases controlling quality from fiber to finished coated fabric.
Spain
Mediterranean restaurant and hotel groups specify salt-spray-resistant marine canvas for coastal property portfolios. REACH chemical registration frameworks restrict per- and polyfluoroalkyl substance use in textile coatings, compelling reformulation toward C6 fluorocarbon alternatives. Barcelona and Valencia anchor specification-grade fabric distribution serving hospitality OEMs across the Iberian Peninsula.
China
Commercial tenting and event infrastructure manufacturers source vinyl-coated polyester for RF-weldable modular frame systems. The country's national chemical regulator enforces dual carbon goals and industrial emissions standards affecting coating house operations. Production clusters in Zhejiang and Jiangsu provinces supply weldable scrim constructions for rapid-deployment weather barriers.
Italy
Lake Como and Adriatic marina operators drive replacement demand for breathable marine enclosures and decorative outdoor furniture fabrics. ECHA substance restrictions under REACH Annex XVII eliminate long-chain fluorocarbon finishing options, accelerating silicone-based surface treatment adoption. Lombardy and Veneto host specialty mills serving premium architectural shading and recreational shelter segments.
Outdoor Fabric Market Vendor Landscape
Vertically integrated textile mills and specialty coating houses split the market between specification-grade premium tiers and volume-driven standard segments. Three archetypes dominate: North American integrated manufacturers controlling fiber-to-fabric production, European precision coating specialists serving architectural membrane applications, and Asian volume producers of weldable vinyl laminates. Competitive moves concentrate on direct-to-OEM distribution bypass and coating chemistry reformulation to maintain EU market access.
Among European coating specialists, Serge Ferrari Group exemplifies the advanced surface treatment archetype through its position in architectural membrane applications, while Sattler AG occupies a comparable tier from its Austrian production hub. Glen Raven anchors the North American integrated manufacturer archetype, representing backward integration from polymer production through finished fabric conversion. These three companies illustrate how formulation IP and captive supply chain control separate premium-tier competitors from distributor-dependent rivals.
| Leading Market Players |
|---|
| Glen Raven |
| Serge Ferrari Group |
| Sattler AG |
| Sauleda |
| Dickson Constant |
| Mehler Texnologies |
| Twitchell Corporation |
| Herculite Products |
| Recasens |
| Others |
Supply Flow & Price Mechanics
PTA and MEG feedstock volatility determines both pricing tier spreads and supply chain shape, compressing polyester fabric margins during oil price spikes while pushing mills toward backward integration into polymer production or captive acrylonitrile sourcing.
Pricing Analysis
Configured-to-order pricing for specification-grade architectural membrane fabrics commands substantial premiums over standard awning fabric SKUs. Pricing stratifies across premium, standard, and economy tiers based on certification grade (bluesign versus OEKO-TEX Standard 100) and volume scale. Cost compression in standard-grade vinyl-coated polyester is intensifying because Chinese volume producers are expanding weldable scrim capacity. Hospitality OEMs exhibit the lowest price sensitivity due to multi-year framework agreements, while residential replacement buyers remain highly elastic.
Supply Chain Analysis
Purified terephthalic acid and monoethylene glycol polymerization feeds from naphtha and paraxylene benchmarks in Germany, China, and the United States. Fluoropolymer resin production draws from Japanese and German specialty chemical houses, creating single-source vulnerability for PVDF and FEVE dispersions. Distribution runs through direct mill relationships with large hospitality and marine OEMs, bypassing traditional fabric distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in REACH-compliant coating formulations creates sustainable barriers against commodity competitors.
For Market Incumbents: Build formulation IP moats by accelerating silicone-based and C6 fluorocarbon coating validation ahead of REACH sunset dates. Secure backward integration into acrylonitrile production or fermentation-derived feedstock partnerships to buffer against petroleum price volatility. Defend against emerging Asian volume producers by embedding specification-grade certifications into municipal procurement frameworks.
For New Entrants and Emerging Players: Pursue bio-based acrylic chemistry white space in premium awning segments where petroleum-independent fiber production commands sustainability premiums. Target German municipal marina refurbishment programs with direct-bid positioning under public infrastructure rules. Leverage bluesign certification as a go-to-market wedge against legacy mills with dual-audit transition burdens.
For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape toward coating houses with validated C6 and silicone alternative portfolios. Long-term viability centers on mills controlling captive fiber-to-fabric production rather than distributor-dependent converters. Watch for ECHA substance restriction enforcement acceleration as the inflection signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH Annex XVII compliance secures EU market access for architectural membrane producers. |
| Backward Integration into Polymer Production | Captive PTA/MEG supply buffers German mills against naphtha price volatility. |
| Direct-to-OEM Distribution Buildout | Bypassing intermediaries captures margin from large hospitality portfolio operators. |
| Bio-Based Acrylic Fiber Development | Fermentation-derived acrylonitrile from agricultural waste enables petroleum-independent premium positioning. |
| Dual Certification Maintenance | Simultaneous OEKO-TEX and bluesign audits divert quality resources from production-constrained competitors. |
Methodological Framework
Operator-level perspectives from textile mill coating directors, hospitality procurement managers, marine OEM supply chain leads, and municipal infrastructure planners anchored the qualitative base. Primary interview findings triangulated against secondary sources including ECHA substance restriction databases, customs trade data for coated fabric imports, and SEC filings from vertically integrated manufacturers. Bottom-up volume modeling across material-grade segments reconciled with top-down market sizing from trade association production statistics.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type (canopy, awning, marine canvas, tarp), material substrate (polyester, acrylic, vinyl, canvas), and end-use application (tents, cushions, umbrellas, outdoor furniture). CAGRs derived from elasticity-adjusted demand curves incorporating hospitality construction permits, marina refurbishment program allocations, and REACH compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in oil benchmark trajectories or ECHA enforcement intensity would shift the trajectory. Cross-checking against German federal infrastructure budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Knitting Cam Market