
 Carpet Yarn Market | 2026-2036
Carpet Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Yarn Market Analysis
China's polyester filament expansion is reconfiguring raw material availability for downstream carpet weavers. Shaw Industries Group, Inc. leverages captive polymerization to secure cost visibility across its Georgia-based tufting operations. Mohawk Industries, Inc. anchors North American distribution through direct dealer networks that bypass traditional distributor markups. Beaulieu International Group specializes in bulked continuous filament systems that reduce pilling in high-traffic commercial installations.
Carpet yarn comprises twisted or heatset fibers engineered to withstand abrasion, crushing, and UV degradation under sustained foot traffic, with denier counts typically ranging from 800 to 3,600 for residential and commercial grades. Nylon retains dominant share in commercial applications where resilience and recovery justify premium positioning, while polyester captures volume in residential replacement cycles through lower price points and broader color availability. Tufted manufacturing dominates output due to speed and material efficiency, though woven constructions persist in luxury hospitality segments where dimensional stability commands specification priority.
EPA oversight of per- and polyfluoroalkyl substance discharge limits water-repellent chemistry options for US-based yarn finishers, while EU REACH compliance costs filter smaller European spinners from specification-driven contract segments. OSHA workplace exposure thresholds for fiber dust influence automation investment in US carding and spinning halls. Stakeholders must monitor bio-based polymer validation timelines and certifier acceptance before committing capital to alternative feedstock transitions.
Market Dynamics
Solution-dyed nylon capacity expansion is restructuring competitive positioning as hospitality procurement teams prioritize stain resistance specifications over first-cost considerations, forcing spinners to recalibrate coloration investments.
Growth Catalysts
- REACH dye-intermediate restrictions:European manufacturers are redirecting capital toward waterless coloration technologies, accelerating adoption of solution-dyed systems that eliminate effluent treatment liabilities.
- Hospitality sector procurement:Hotel operators in India's commercial real estate corridors specify extended replacement cycles, creating pull-through demand for high-denier nylon constructions.
- Polymerization technology:Captive polymer production is digitizing cost visibility across integrated spinning operations, compressing working capital cycles for large-scale tufting feedstock suppliers.
Market Restraints
- Crude-linked input volatility:Caprolactam and purified terephthalic acid prices track naphtha spreads, exposing non-integrated spinners to margin compression during upstream petrochemical cycles.
- EPA PFAS discharge limits:Water-repellent finish chemistry options are narrowing for US-based yarn processors, constraining product differentiation in commercial specification segments.
- Hard flooring substitution:Luxury vinyl tile and engineered wood are capturing residential square footage, displacing broadloom carpet in new construction and replacement cycles.
Strategic Opportunities
- India's domestic tufting corridor:Gujarat and Tamil Nadu clusters serve both local builders and export-oriented carpet producers, offering scale advantages for feedstock suppliers with regional polymer access.
- EU Green Deal alignment:Bio-based polyamide validation timelines are creating first-mover positioning for spinners that secure ISCC PLUS certification ahead of mass-market acceptance thresholds.
- Direct dealer networks:Bypassing traditional distributor markups is digitizing margin capture for manufacturers with sufficient SKU breadth to justify dedicated sales infrastructure.
Industry Challenges
- OSHA fiber dust exposure thresholds:Carding and spinning hall automation requires capital deployment that smaller European spinners cannot absorb, filtering participants from specification-driven contract segments.
- Certifier acceptance timelines:Third-party validation of recycled content claims lags brand marketing cycles, creating liability exposure for premature sustainability positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Yarn Market |
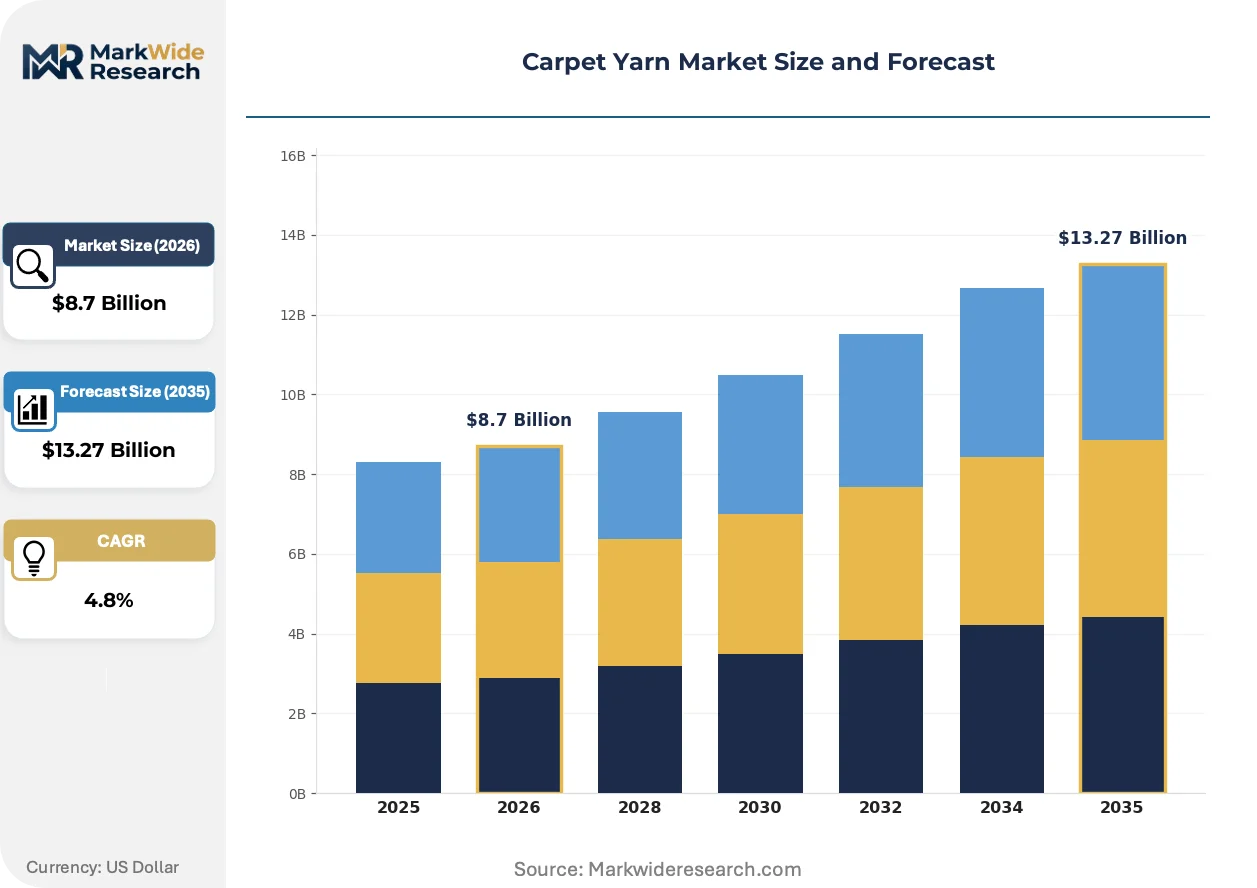
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Yarn Type: Nylon, Polyester, Wool, Polypropylene Manufacturing Process: Tufted, Woven, Knotted, Needlefelt Application: Residential, Commercial, Hospitality, Automotive Color Finish: Solid, Multi-Color, Patterned, Textured |
| Companies Covered | Interface, Inc., Balta Industries NV, Shaw Industries Group, Inc., Dixie Group, Milliken & Company, Mohawk Industries, Inc., Tarkett, Engineered Floors, Beaulieu International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Yarn Market Emerging Trajectories
Digital color matching and predictive maintenance systems are compressing lead times while regulatory chemistry restrictions are forcing reformulation of performance finishes across multiple jurisdictions simultaneously.
Solution-dyed bulked continuous filament technology is digitizing color consistency control by embedding pigments at the polymer melt stage rather than post-extrusion dyeing. Hospitality specifiers in Dubai and Singapore are adopting these systems for high-traffic installations where stain resistance warranties determine vendor selection. The technology is compressing batch-to-batch variation to sub-delta-E thresholds that wet-dyeing cannot replicate.
EU REACH restrictions on specific azo dye intermediates are eliminating certain colorant chemistries from European supply chains, forcing reformulation of traditional space-dyed aesthetics. German and Belgian spinners are absorbing ECHA compliance costs that filter smaller competitors from architectural specification segments. Italian luxury hospitality weavers are responding by accelerating partnerships with solution-dyed specialists in Turkey and Egypt.
Buyer concentration among national hotel chains is digitizing procurement leverage, compressing supplier margins through centralized specification and volume commitments. Direct sourcing agreements are displacing traditional distributor relationships in the North American commercial segment. This concentration is most visible in extended-stay and select-service verticals where capital expenditure cycles synchronize across property portfolios.
Carpet Yarn Market Segmentation
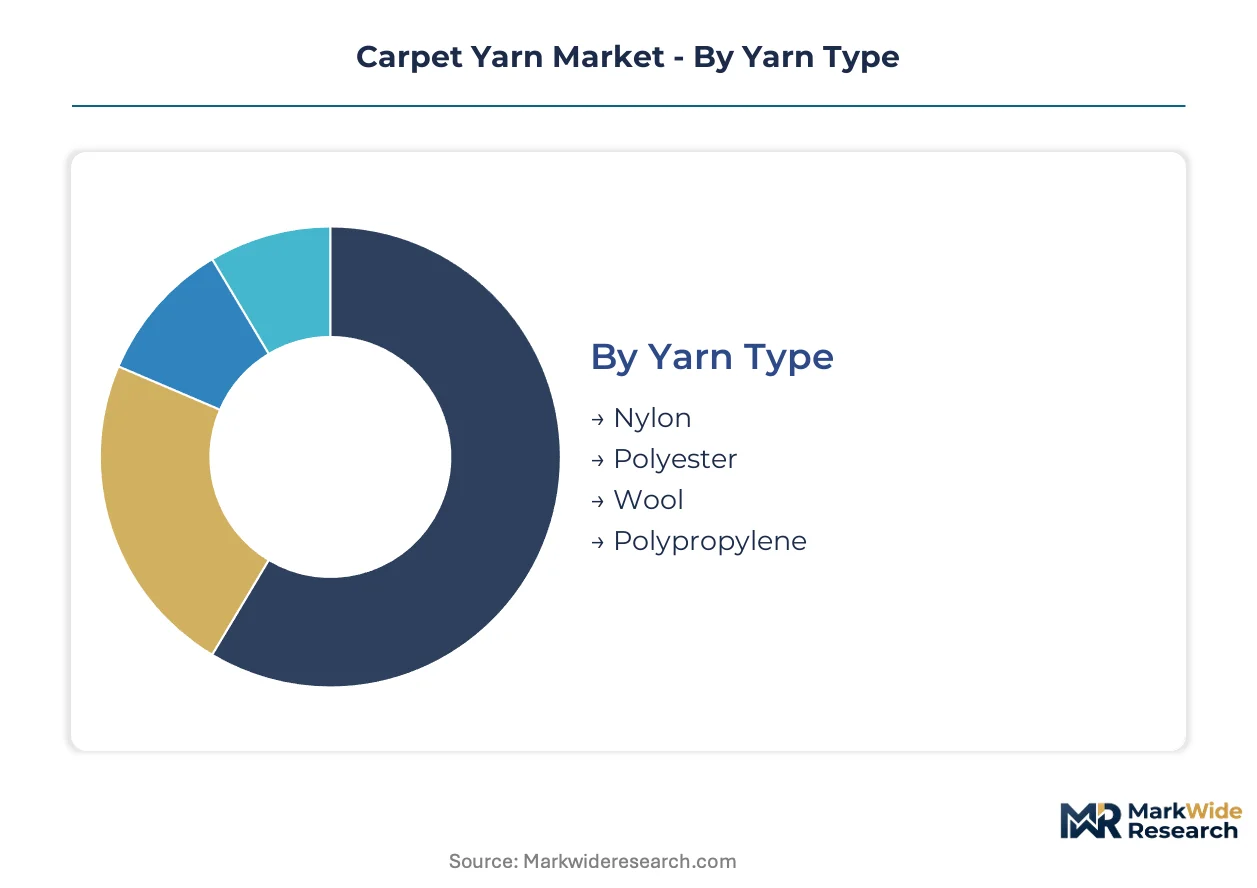
Carpet yarn segmentation reflects divergent performance requirements across end-use environments. Material selection, manufacturing method, and surface finish each create distinct value tiers that shape procurement behavior and margin structures.
Yarn Type:
Performance demands span from high-traffic commercial resilience to residential budget constraints, with fiber chemistry determining durability, stain resistance, and recovery characteristics.
- Nylon:Polyamide 6 and 6,6 polymers deliver superior abrasion resistance and crush recovery under sustained foot traffic. Hospitality procurement teams in Dubai and Singapore specify high-denier nylon constructions where extended replacement cycles justify premium positioning against polyester alternatives.
- Polyester:PET filament systems offer broader color gamut and lower first-cost positioning for residential replacement cycles. India's commercial real estate corridors are absorbing expanding volumes as domestic tufting capacity scales to serve both local builders and export-oriented carpet producers.
- Wool:Natural fiber retains specification in luxury hospitality segments where dimensional stability and flame resistance command priority.
- Polypropylene:Olefin yarns provide moisture and chemical resistance for outdoor and marine applications with limited resilience requirements.
The dominant share belongs to Nylon, while Polyester is closing the gap fastest.
Manufacturing Process:
Production speed and material efficiency separate high-volume commodity supply from precision-engineered architectural specifications.
- Tufted:Needle-punch technology dominates output volume through speed and yarn economy, with Georgia-based operations leveraging captive polymerization for cost visibility. Woven: Axminster and Wilton constructions persist in luxury hospitality where dimensional stability determines specification priority.
- Knotted:Hand-tied techniques serve artisanal and heritage restoration segments with limited scalability.
- Needlefelt:Entangled fiber mats address cost-sensitive commercial installations with moderate traffic expectations.
Tufted manufacturing commands volume leadership, though Woven constructions defend the highest margin tier.
Application:
End-use environments impose distinct durability, aesthetic, and regulatory requirements that filter supplier capabilities.
- Residential:Replacement-driven demand favors polyester volume and broader color availability at accessible price points.
- Commercial:Office and institutional procurement prioritizes wear warranties and maintenance protocols over first-cost considerations.
- Hospitality:Hotel operators specify solution-dyed nylon for stain resistance in high-traffic lobbies and corridors.
- Automotive:OEM and aftermarket carpet applications require compression-molding compatibility and odor control specifications.
Commercial applications generate the most stable demand base, while Hospitality is expanding most quickly.
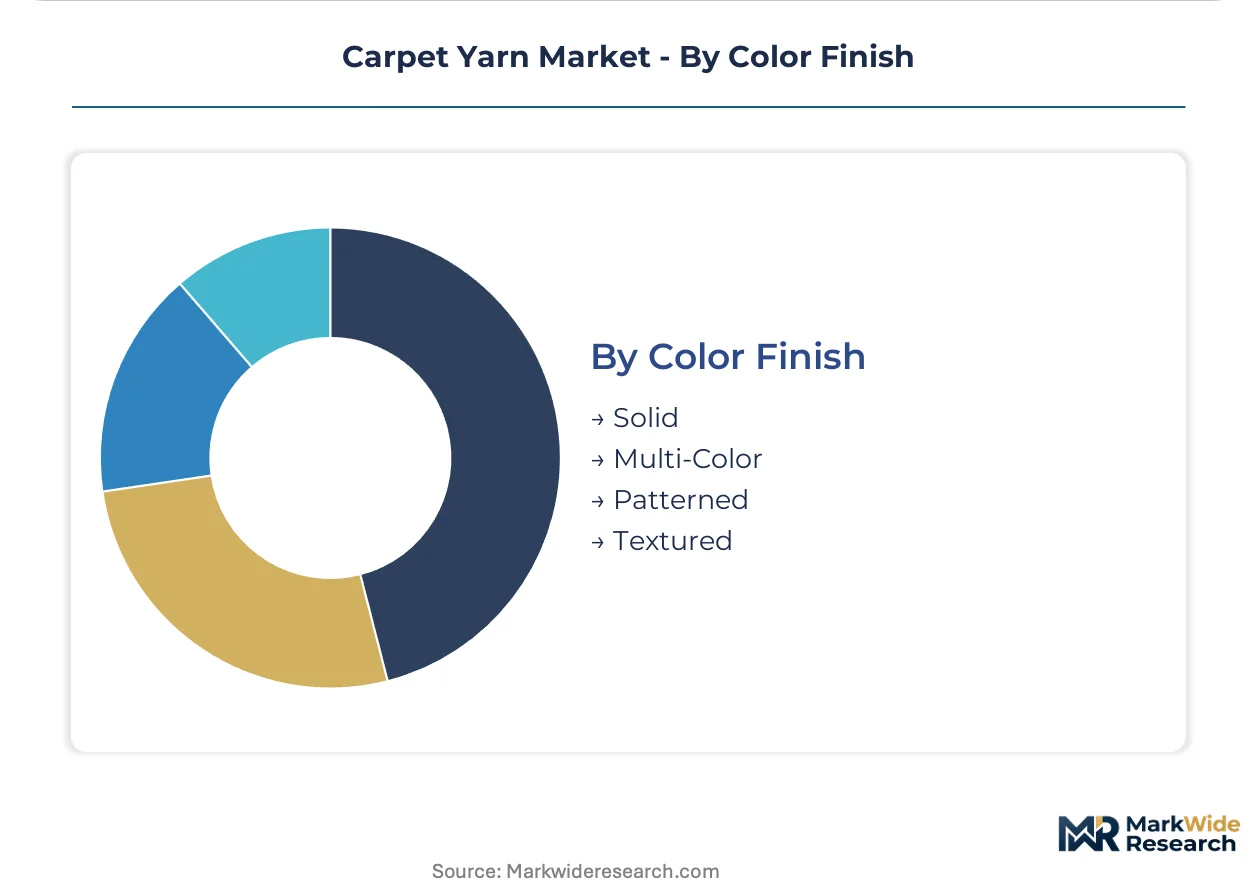
Color Finish:
Coloration technology determines batch consistency, effluent treatment liability, and design flexibility across specification segments.
- Solid:Uniform coloration dominates commercial specifications where consistency across large installations is mandatory.
- Multi-Color:Space-dyed and solution-dyed variations create visual texture without pattern complexity.
- Patterned:Precision dye placement supports hospitality and residential design differentiation.
- Textured:Cut-and-loop constructions combine surface variation with color depth for premium residential positioning.
Solid finishes retain specification dominance, while Textured surfaces are gaining share fastest in residential premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between hospitality-driven specification markets and residential replacement cycles, with procurement teams in Dubai and Singapore prioritizing stain resistance warranties while Indian builders absorb volume-oriented polyester feedstock.
United States
Georgia-based tufting operations leverage captive polymerization to compress working capital cycles for commercial feedstock supply. EPA PFAS discharge limits constrain water-repellent finish options for yarn processors serving specification-driven contract segments. Dalton, Georgia anchors North American carpet manufacturing, with integrated spinning-to-tufting corridors serving hospitality and institutional procurement teams.
China
Polyester filament expansion in Zhejiang and Jiangsu provinces reconfigures raw material availability for downstream carpet weavers serving export markets. MIIT industrial standards govern fiber quality classifications for domestic and export-oriented production. The Yangtze River Delta cluster concentrates spinning capacity that feeds both local tufting operations and Southeast Asian carpet assembly.
Germany
ECHA compliance costs for azo dye intermediate restrictions filter smaller spinners from architectural specification segments. REACH regulations redirect capital toward waterless coloration technologies that eliminate effluent treatment liabilities. The Baden-Württemberg corridor hosts precision spinning operations serving luxury hospitality weavers across Europe.
India
Domestic tufting capacity in Gujarat and Tamil Nadu serves both local commercial real estate builders and export-oriented carpet producers. BIS fiber quality standards shape procurement specifications for institutional and hospitality installations. The Surat-Bhagalpur belt concentrates solution-dyed nylon spinning for hotel operators prioritizing extended replacement cycles.
UAE
Hospitality procurement teams in Dubai specify high-denier nylon constructions where stain resistance warranties determine vendor selection for high-traffic lobbies and corridors. MOHAP product safety frameworks govern interior material specifications for hotel and commercial developments. Jebel Ali industrial zones host finishing operations that serve Gulf Cooperation Council specification markets.
Carpet Yarn Market Vendor Landscape
Capability concentration sits with integrated polymer-to-yarn specialists; scale advantage sits with diversified flooring conglomerates. The vendor base separates into three tiers: captive polymerization operators with cost visibility, solution-dyed technology specialists with hospitality specification access, and regional spinners serving price-sensitive residential replacement. Dominant competitive moves include backward integration into polymer production and direct dealer network establishment that bypasses traditional distributor markups.
Among North American flooring conglomerates, Shaw Industries Group, Inc. and Mohawk Industries, Inc. exemplify the integrated-scale archetype, while Beaulieu International Group occupies a position within the European specialty tier focused on bulked continuous filament systems. These three anchors represent divergent strategic postures across the capability-scale spectrum.
| Leading Market Players |
|---|
| Interface, Inc. |
| Balta Industries NV |
| Shaw Industries Group, Inc. |
| Dixie Group |
| Milliken & Company |
| Mohawk Industries, Inc. |
| Tarkett |
| Engineered Floors |
| Beaulieu International Group |
| Others |
Supply Flow & Price Mechanics
Dalton, Georgia's integrated spinning-to-tufting corridor compresses working capital cycles for commercial feedstock suppliers, translating captive polymerization into downstream pricing leverage against non-integrated competitors. The concentration of solution-dyed nylon capacity in this cluster allows large-scale operators to absorb caprolactam volatility more effectively than regional spinners serving price-sensitive residential replacement cycles.
Pricing Analysis
Price spreads between US and Asian polyester filament markets reflect divergent naphtha-linked input cost structures and tariff exposure on purified terephthalic acid imports. Contract-based long-term offtake agreements dominate hospitality procurement, where solution-dyed nylon specifications command premium positioning based on stain resistance warranties and batch consistency guarantees. Price differentiation hinges on denier grade and REACH compliance certification, with EU-architectural specification tiers absorbing ECHA-driven reformulation costs that filter smaller competitors. Cost compression in residential polyester segments is intensifying because China's Zhejiang-Jiangsu filament expansion floods export markets with lower-first-cost alternatives. Budget-conscious residential replacement buyers exhibit highest price sensitivity, while Dubai and Singapore hospitality specifiers prioritize extended replacement cycle performance over first-cost considerations.
Supply Chain Analysis
Extended payment terms from hospitality procurement teams in Dubai and Singapore strain working capital for mid-scale spinners without supply-chain finance facilities. Raw material supply concentrates in China, the United States, and India, with caprolactam and purified terephthalic acid availability tethered to naphtha spread volatility and regional petrochemical cycles. The supply chain draws from polymerization hubs in Georgia, Zhejiang, and Gujarat, with downstream distribution running through direct dealer networks that bypass traditional distributor markups for large-scale commercial accounts. Single-source vulnerability persists in solution-dyed pigment masterbatch supply, where specialized colorant formulators in Germany and Turkey serve architectural specification segments with limited qualified alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solution-dyed nylon warranties and predictive maintenance service contracts are expanding faster than commodity yarn volume, creating recurring-revenue layers that justify premium positioning beyond hardware margins. After-sales technical support for hospitality installation specification is becoming a decisive vendor selection criterion in Dubai and Singapore procurement frameworks.
For Market Incumbents: Harden specification-driven contract access by securing ISCC PLUS certification ahead of EU Green Deal bio-based polyamide validation timelines. Deepen backward integration into caprolactam production to insulate margin structures from naphtha-linked input volatility that compresses non-integrated spinner competitiveness. Capacity addition in Gujarat's domestic tufting corridor captures India's commercial real estate expansion while serving export-oriented carpet producers with regional polymer access. For New Entrants and Emerging Players: Establish a beachhead in India's commercial real estate corridors by partnering with Tamil Nadu and Gujarat tufting clusters that lack captive spinning capacity. Target hospitality aftermarket service contracts in Dubai and Singapore where stain resistance warranty fulfillment creates vendor stickiness beyond initial installation. Pursue a go-to-market angle centered on digital color matching and predictive maintenance systems that compress lead times for specification-driven procurement teams. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OSHA fiber dust exposure thresholds and REACH compliance costs are filtering smaller European spinners from specification-driven contract segments, creating acquisition targets with distressed valuation multiples. Vertically integrated operators with captive polymerization and solution-dyed technology access represent the most defensible positioning. Monitor bio-based polyamide certifier acceptance timelines as the inflection signal for alternative feedstock transition capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Captive caprolactam production insulates Shaw Industries and Mohawk from naphtha spread volatility. |
| Solution-Dyed Capacity Expansion | Waterless coloration eliminates REACH effluent liabilities for European spinners serving architectural specifications. |
| Direct Dealer Network Establishment | Bypassing distributor markups digitizes margin capture for manufacturers with sufficient SKU breadth. |
| ISCC PLUS Certification Investment | First-mover positioning in bio-based polyamide validation ahead of EU Green Deal mass-market thresholds. |
| Automation of Carding and Spinning Halls | OSHA fiber dust compliance filters smaller competitors from specification-driven contract segments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement managers, commercial real estate developers, spinning plant managers, and carpet tufting operations directors. Secondary validation drew from customs and trade data, SEC 10-K filings of listed flooring conglomerates, MIIT industrial standards documentation, and ECHA regulatory submission databases. Bottom-up volume modeling across yarn type, manufacturing process, and application segments was triangulated against top-down macroeconomic indicators for the floor covering industry.
Calibration against historical capacity utilization rates and polymer price spread relationships anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include fiber chemistry tier, denier grade classification, coloration technology type, end-use environment, and regional regulatory cluster. CAGRs were derived from regression analysis of input-output relationships and elasticity estimates for hospitality versus residential demand substitution. Industry-specific forecast inputs incorporated REACH compliance cost absorption rates and domestic tufting capacity expansion timelines in India.
Stress conditions across naphtha spread volatility, PFAS regulatory restriction severity, and hard flooring substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding polymerization technology adoption curves and certifier acceptance timelines for bio-based alternatives. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market