
 North America Cotton Market | 2026-2036
North America Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cotton Market Analytics
Texas cotton acreage is rebalancing after drought-induced contraction, with ginning capacity consolidating in the High Plains and Rolling Plains regions. Cargill leverages its grain-handling infrastructure to anchor cotton logistics across the southern supply corridor. Dunavant Enterprises sustains merchant dominance through long-standing relationships with domestic textile mills. Hanesbrands Inc. controls a significant share of North American apparel demand through vertical manufacturing from fiber to finished goods.
North America cotton comprises cellulose fibers harvested from Gossypium species, with upland varieties constituting the majority of commercial production at staple lengths of 27-32 millimeters and micronaire readings between 3.5 and 4.9. The fiber serves as the principal raw material for spun yarns used in woven and knitted textile products across consumer and industrial applications. Upland cotton occupies the mature volume position, while organic cotton captures the fastest expansion as brands respond to chemical-free certification requirements. The textiles end-use segment concentrates margin pools in premium spinning operations, whereas industrial applications compete on throughput scale rather than fiber quality differentiation.
The USDA Agricultural Marketing Service administers cotton classification standards that determine loan rate eligibility and export competitiveness, while the EPA regulates pesticide applications under FIFRA provisions that constrain chemical-intensive farming practices. The Federal Trade Commission enforces textile labeling rules under the Textile Fiber Products Identification Act, mandating accurate fiber content disclosure that shapes consumer purchasing decisions and brand compliance costs. Stakeholders must monitor water rights allocation disputes in the Ogallala Aquifer region and evolving organic certification thresholds as dual pressures on sustainable supply security.
Market Dynamics
Water scarcity in the Ogallala Aquifer is forcing acreage consolidation toward drip-irrigated operations and pressuring ginning capacity economics across the Texas High Plains.
Growth Catalysts
- USDA Classification Standards:The Agricultural Marketing Service's loan rate eligibility framework stabilizes farmer revenue predictability and underwrites export competitiveness against Brazilian and Australian supply.
- Apparel Brand Sustainability Mandates:Chemical-free certification requirements from North American clothing retailers are pulling acreage conversion toward organic cultivation protocols and regenerative soil management.
- Texas Production Concentration:Ginning infrastructure clustering in the Rolling Plains creates scale economies in logistics and quality standardization that lower unit processing costs for merchant aggregators.
Market Restraints
- Input Cost Volatility:Fertilizer and diesel price swings compress operating margins for dryland farmers who lack irrigation buffers against yield variability.
- Supply Concentration Risk:Overreliance on Texas acreage exposes the regional crop to localized drought events and aquifer depletion that ripple through domestic textile supply security.
- Regulatory Friction:EPA FIFRA pesticide application constraints limit chemical-intensive farming practices and extend compliance timelines for conventional growers transitioning acreage.
Strategic Opportunities
- Canadian Organic Acreage Expansion:Prairie provinces offer untapped chemical-free cultivation potential with established grain-handling infrastructure adaptable to cotton logistics.
- Industrial Nonwoven Applications:Medical and hygiene product manufacturers are sourcing North American cellulose for supply chain regionalization away from Asian viscose dependence.
- USDA Conservation Programs:EQIP and CSP incentive payments subsidize cover cropping and water-efficient irrigation retrofits that lower transition costs for sustainable production.
Industry Challenges
- Organic Certification Timelines:The three-year land conversion requirement for USDA organic status locks up working capital and creates revenue gaps during transition periods.
- Ginning Capacity Reconfiguration:Drought-induced acreage contraction in western Texas is stranding fixed assets and forcing cooperative consolidation decisions among independent processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cotton Market |
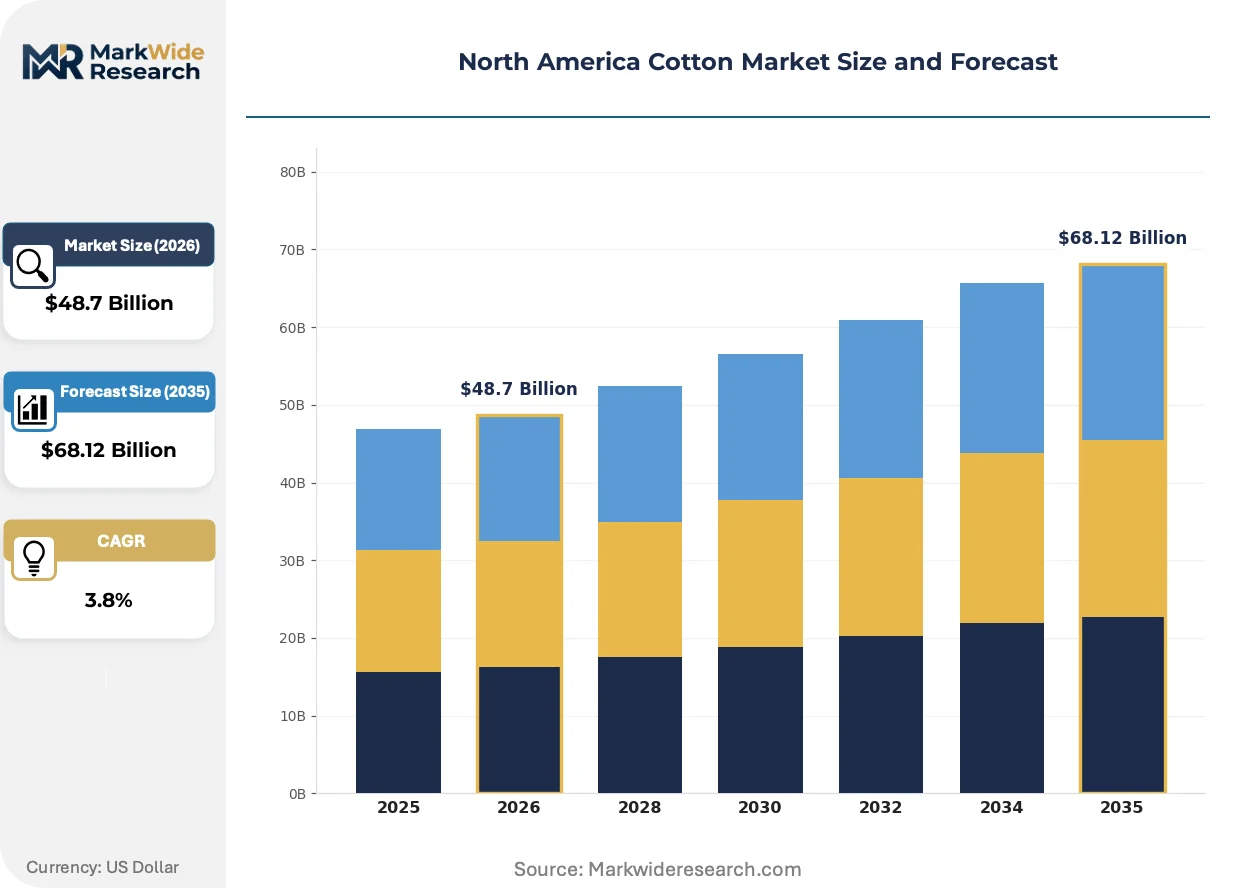
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upland, Pima, Organic, Fleece End Use Industry: Textiles, Apparel, Home Furnishing, Industrial Distribution Channel: Online, Retail, Wholesale, Direct Sales Application: Dyeing, Spinning, Weaving, Knitting |
| Companies Covered | Patagonia, Inc., Hanesbrands Inc., Eileen Fisher Inc., Coyuchi, Pact Apparel, Allenberg, Dunavant Enterprises, Cargill, Olam International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cotton Market Evolving Landscape
Precision agriculture and fiber traceability systems are compressing quality variance and enabling premium segmentation that rewards verified sustainable production at origin.
Sensor-based variable-rate irrigation is absorbing capital deployment across the Texas Panhandle as growers optimize water application per acre-foot costs. Large-scale operations with contiguous holdings are retrofitting center-pivot systems with soil-moisture telemetry. The technology is absorbing risk premiums previously embedded in crop insurance and forward contracting.
EPA enforcement of FIFRA buffer-zone requirements is tightening chemical application windows during critical growth stages. Cotton producers in the High Plains are narrowing pesticide selection to lower-toxicity alternatives that preserve beneficial insect populations. The regulatory pressure is compressing conventional input cost structures relative to organic transition economics.
Direct contracting between apparel brands and grower cooperatives is displacing traditional merchant intermediation in premium fiber segments. Hanesbrands and similar vertical manufacturers are establishing origin-verified supply lines that bypass spot-market price exposure. The procurement model shift concentrates most visibly in California's San Joaquin Valley organic operations.
North America Cotton Market Segmentation
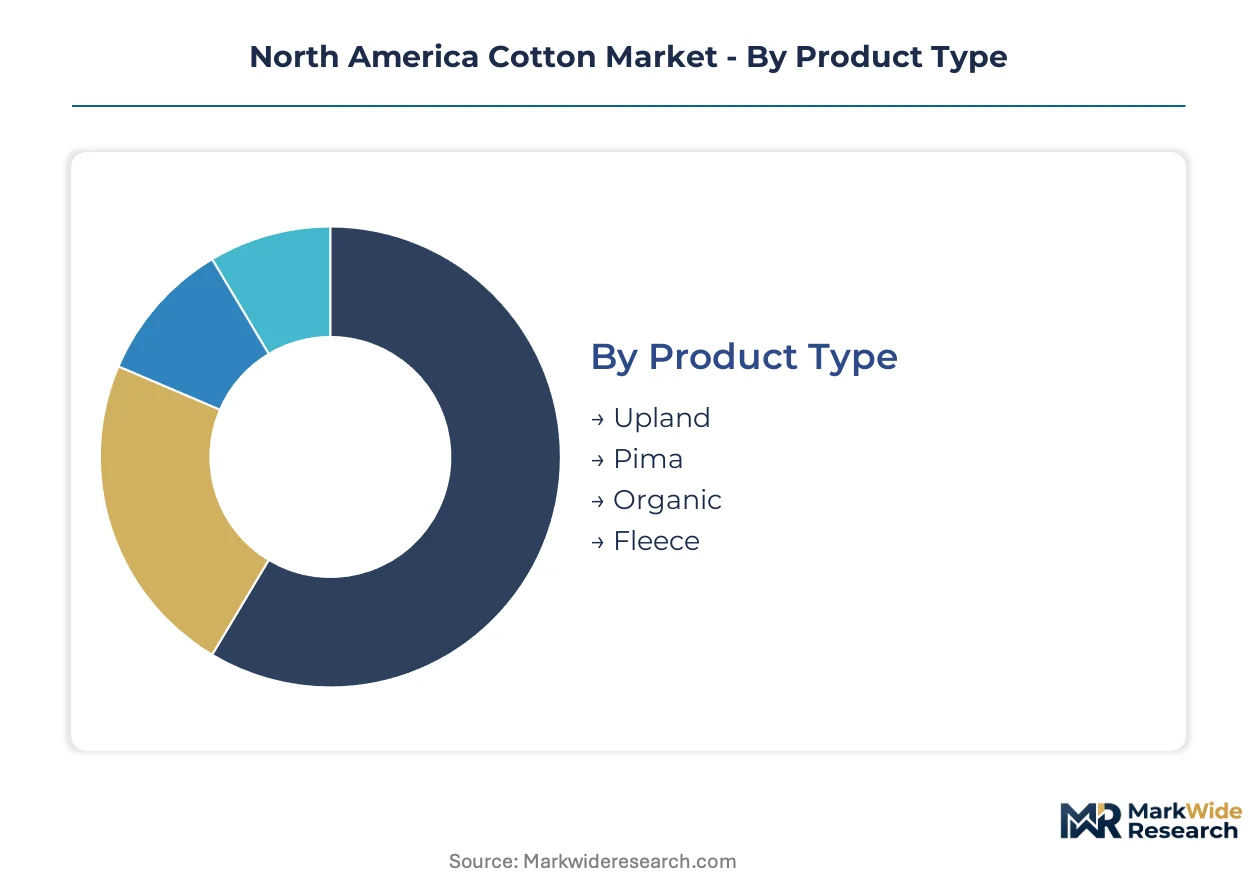
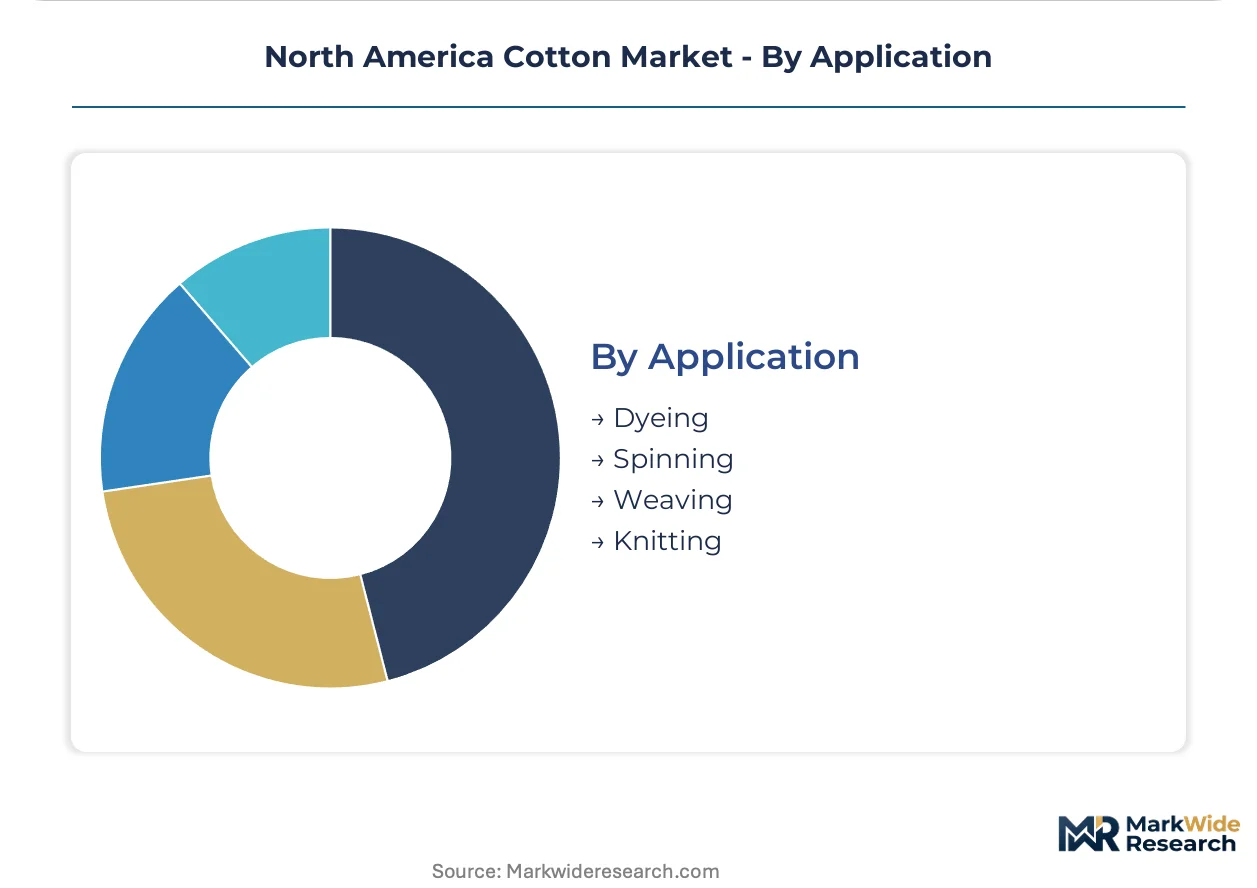
Segmentation in North American cotton reveals how fiber specifications, end-use requirements, and channel economics fragment margin capture across the value chain. Understanding these divisions exposes where premium pricing adheres and where commoditization erodes returns.
Product Type:
Supply concentration in Texas upland production shapes how fiber grades compete for spinner contracts and export slots.
- Upland:Gossypium hirsutum varieties dominate commercial volumes with staple lengths of 27-32 millimeters and micronaire readings between 3.5 and 4.9. Texas High Plains gins process the majority of this grade for domestic textile mills and export merchants.
- Organic:Chemical-free certification under USDA National Organic Program standards requires three-year land conversion and restricts synthetic inputs. California's San Joaquin Valley and emerging Prairie province acreage in Canada are pulling brand procurement away from conventional supply.
- Pima:Extra-long staple fiber from Gossypium barbadense species commands premium positioning in fine-count spinning for luxury apparel.
- Fleece:Brushed cotton fabric grades serve activewear and loungewear manufacturers seeking moisture-management properties.
Today's leader: Upland. Tomorrow's challenger: Organic.
End Use Industry:
Margin pools concentrate where fiber quality specifications create technical barriers to substitution.
- Textiles:Spun yarn producers in the Southeast and Mexico integrate upland cotton into woven sheeting and denim, competing on throughput scale and dye-house proximity to cut logistics costs.
- Apparel:Vertical manufacturers like Hanesbrands source origin-verified fiber to meet chemical-free mandates from North American retailers, bypassing spot-market exposure through direct grower contracts.
- Home Furnishing:Towel and bedding producers absorb medium-grade upland for bulk consumption with lower micronaire sensitivity.
- Industrial:Medical nonwovens and hygiene products are sourcing regional cellulose for supply chain regionalization away from Asian viscose dependence.
Apparel commands premium fiber allocation. Industrial applications are climbing the fastest as regional sourcing mandates take hold.
Distribution Channel:
Channel structure determines price transparency and working capital requirements for growers and merchants.
- Wholesale:Merchant aggregators like Dunavant Enterprises consolidate gin deliveries for mill contracts, anchoring liquidity in the Texas-Oklahoma supply corridor.
- Direct Sales:Apparel brands contract directly with grower cooperatives for traceable organic supply, displacing traditional intermediation in premium segments.
- Online:Digital platforms connect specialty spinners with certified organic lots for small-batch procurement.
- Retail:Farm-gate and cooperative storefronts serve local craft producers and specialty yarn shops.
Wholesale retains volume dominance. Direct sales are gaining share fastest as sustainability verification requirements intensify.
Application:
Processing stage determines fiber preparation standards and contamination thresholds.
- Spinning:Ring and open-end systems require precise trash content and length uniformity for efficient yarn formation, concentrating demand at USDA-classified grades above Strict Low Middling.
- Dyeing:Preparation for color absorption demands controlled wax and pectin removal, favoring gins with advanced lint cleaning.
- Weaving:Warp yarn production requires higher tenacity fiber to withstand loom tension stresses.
- Knitting:Weft-oriented circular and flat-bed systems tolerate shorter staple with softer hand requirements.
Spinning anchors fiber specification standards. Dyeing is expanding most quickly as water-efficient processing technologies reduce environmental compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling cotton cultivation toward jurisdictions with lower water-access costs and streamlined organic certification pathways, reshaping acreage allocation across the continent.
United States
Texas High Plains gins process the majority of domestic upland volume, while California's San Joaquin Valley anchors premium organic fiber contracts with apparel brands. The USDA Agricultural Marketing Service administers classification standards that determine loan rate eligibility and export competitiveness. Ginning infrastructure clustering in the Rolling Plains creates scale economies that lower unit processing costs for merchant aggregators.
Canada
Prairie provinces offer untapped chemical-free cultivation potential with established grain-handling infrastructure adaptable to cotton logistics. Health Canada regulates pesticide applications through the Pest Management Regulatory Agency, constraining chemical-intensive farming practices. Alberta and Saskatchewan are emerging as testbeds for organic acreage expansion backed by federal sustainable agriculture incentive programs.
Mexico
The Bajío Region and northern border states are absorbing spillover demand from US textile mills seeking shorter supply lines and preferential trade access. Mexico's national agricultural regulator, SADER, oversees phytosanitary standards that align with USDA protocols for cross-border fiber movement. Ginner cooperatives in Chihuahua and Sonora are retrofitting equipment to handle smaller organic lots for direct brand contracting.
North America Cotton Market Competitive Landscape
Texas producers anchor one tier; California specialists hold premium organic positioning through direct brand relationships. The market structures around three functional layers: merchant aggregators consolidating gin deliveries, vertical manufacturers controlling fiber-to-garment supply lines, and international traders arbitraging regional price spreads. Two dominant competitive moves are reshaping positioning: cooperative consolidation among independent gins to defend processing margins, and backward integration by apparel brands into origin-verified sourcing agreements.
Among merchant aggregators, Dunavant Enterprises and Cargill exemplify the logistics-anchored archetype, leveraging long-standing relationships with domestic textile mills and grain-handling infrastructure respectively. Hanesbrands Inc. occupies a position within the vertical-manufacturing tier, sourcing fiber through direct grower contracts that bypass spot-market exposure. These three entities represent distinct competitive postures: merchant dominance through relationship density, infrastructure-driven logistics control, and captive supply integration from fiber to finished goods.
| Leading Market Players |
|---|
| Patagonia, Inc. |
| Hanesbrands Inc. |
| Eileen Fisher Inc. |
| Coyuchi |
| Pact Apparel |
| Allenberg |
| Dunavant Enterprises |
| Cargill |
| Olam International |
| Others |
Value Network & Pricing Analysis
Organic-to-conventional grade divergence splits North American cotton into two pricing regimes with fundamentally different supply chain architectures. Premium organic lots command origin-verified contracting through direct brand relationships, while commodity upland flows through merchant aggregators anchored in Texas ginning clusters. This bifurcation concentrates margin capture in California's San Joaquin Valley and emerging Canadian Prairie acreage, while compressing returns in drought-exposed High Plains operations dependent on spot-market liquidity.
Pricing Analysis
Distributor margins in wholesale channels absorb basis risk between gin delivery and mill contract settlement, while direct-to-brand sales bypass traditional markup layers for certified organic supply. Three-tier pricing structure across premium, standard, and economy levels reflects USDA grade classification, organic certification status, and geographic proximity to textile processing hubs. Cost compression in conventional upland is intensifying because drought-induced yield variability forces growers to accept forward discounts against crop insurance benchmarks. Smallholder dryland operators exhibit highest price sensitivity due to working capital constraints, whereas vertical manufacturers like Hanesbrands demonstrate lowest sensitivity through captive supply integration.
Supply Chain Analysis
Single-source vulnerability sits with Texas High Plains production concentration, where aquifer depletion threatens ginning infrastructure economics across the Rolling Plains corridor. Geographic supply draws from the United States, Canada, and Mexico, with cross-border fiber movement governed by aligned USDA-SADER phytosanitary protocols. Raw material dependencies center on irrigation water access, synthetic fertilizer inputs, and diesel fuel for mechanical harvesting operations. Tariff exposure on textile imports from Asian competitors creates demand volatility for domestic spinners. Distribution runs through merchant aggregators consolidating gin deliveries for Southeast and Mexican mill contracts, with direct contracting displacing intermediation in premium organic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American cotton rests on water-efficient cultivation retrofits and organic certification premiums that shift acreage toward higher-value contracting structures. Drip irrigation technology deployment and regenerative soil management protocols are compressing input cost structures while opening brand-direct procurement channels.
For Market Incumbents: Deepen cooperative consolidation among independent gins to defend processing margins against stranded asset risk from drought-induced acreage contraction. Invest in USDA EQIP-subsidized precision agriculture retrofits to lower per-acre water costs and secure eligibility for premium organic transition programs. Vertical integration into origin-verified supply lines insulates against merchant margin compression.
For New Entrants and Emerging Players: Launch via direct contracting with apparel brands seeking chemical-free certification, bypassing established merchant channels in the Texas-Oklahoma corridor. Target Canadian Prairie provinces for organic acreage expansion, leveraging existing grain-handling infrastructure adaptable to cotton logistics. Pursue medical nonwoven applications as the fastest-climbing industrial segment for regional cellulose sourcing.
For Investors and Strategic Acquirers: Consolidation pressure builds where drought-exposed ginning assets face stranded capacity economics and cooperative boards seek exit liquidity. Mid-scale organic operators with established brand relationships represent prime acquisition targets for vertical integration strategies. Watch EPA FIFRA enforcement intensity as the signal indicating acceleration of conventional-to-organic transition economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Contracts | Apparel brands like Hanesbrands bypass spot-market exposure through origin-verified supply lines. |
| Precision Irrigation Retrofit Programs | USDA EQIP subsidies absorb capital deployment for sensor-based variable-rate water application. |
| Organic Certification Acceleration | Three-year land conversion timelines lock up working capital but unlock premium brand-direct channels. |
| Ginning Cooperative Consolidation | Scale economies in Texas Rolling Plains lower unit processing costs for merchant aggregators. |
| Industrial Nonwoven Market Entry | Medical and hygiene manufacturers source North American cellulose away from Asian viscose dependence. |
Research Methodology
Direct dialogue with gin operators, merchant aggregators, textile mill procurement managers, and apparel brand sustainability directors grounded qualitative findings in operational reality. Secondary validation drew from USDA Agricultural Marketing Service classification data, EPA FIFRA enforcement records, customs trade statistics, and textile industry association capacity reports. Bottom-up acreage and yield estimates triangulated against top-down consumption forecasts from spinner demand surveys.
Segmented outputs across product type, end-use industry, distribution channel, and application dimensions informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking scenario weighting. Forecast inputs incorporated Ogallala Aquifer depletion trajectories and organic certification conversion rates as industry-specific demand shifters.
Several conditions sit outside the modeled scope, including extreme drought events exceeding historical frequency, abrupt trade policy shifts affecting cross-border fiber movement, and breakthrough synthetic fiber substitution in core textile applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Natural Fibers Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Sugarcane Fiber Bowls Market