
 Menstrual Health Apps Market | 2026-2036
Menstrual Health Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Menstrual Health Apps Market Intelligence
Clinical-grade algorithm certification is rotating from a niche advantage to a baseline market requirement. Flo Health leverages its large biometric dataset to sustain predictive accuracy claims across irregular cycle populations. Natural Cycles anchors its position through FDA clearance for contraceptive use, a regulatory moat competitors struggle to replicate. Clue specializes in endometriosis symptom correlation, occupying a therapeutic adjacency that general trackers cannot easily penetrate.
Menstrual health apps are software platforms that collect self-reported physiological data—cycle length, basal body temperature, cervical mucus consistency, mood markers, and pain scores—to generate predictive analytics for fertility, contraception, or gynecological monitoring, with accuracy contingent on algorithm training set diversity and user protocol adherence. Their primary commercial purpose is reducing unplanned pregnancy rates, shortening diagnostic delays for conditions like polycystic ovary syndrome, and lowering healthcare system costs through earlier intervention. The freemium subscription model captures the widest user base while concentrating profitability in annual subscriptions where churn rates drop substantially below monthly plans. AI-driven features represent the fastest-growing technology segment as large language models enable conversational symptom triage, though wearable device integration retains higher per-user revenue through hardware-software bundling.
FDA 510(k) oversight and the EU Medical Device Regulation classify high-risk fertility apps as Class II medical devices, forcing developers to submit clinical validation data that smaller entrants cannot afford to generate. GDPR and HIPAA compliance costs are rising as apps integrate with electronic health record systems and employer wellness platforms, creating a compliance barrier that favors well-capitalized incumbents. Stakeholders must monitor whether national health technology assessment bodies begin reimbursing app subscriptions as preventive care, a shift that would restructure competitive dynamics toward clinical evidence depth rather than consumer marketing spend.
Market Dynamics
Algorithmic validation requirements from FDA and EMA are compressing competitive margins as clinical-grade certification becomes mandatory for fertility-tracking claims, forcing capital reallocation toward evidence generation rather than user acquisition.
Growth Catalysts
- Smartphone penetration in emerging economies:Young adult women across India, Brazil, and Indonesia now access menstrual tracking through low-cost Android devices, expanding addressable populations beyond legacy North American and European user bases.
- Wearable integration protocols:Continuous temperature and heart-rate variability monitoring through Apple Watch and Oura Ring APIs enables passive data collection that improves cycle prediction accuracy without manual logging friction.
- EU Medical Device Regulation clarity:MDR classification guidance for fertility apps creates regulatory certainty that attracts institutional investment previously deterred by ambiguous compliance pathways.
Market Restraints
- Clinical validation cost inflation:FDA 510(k) submissions for contraceptive indications require prospective cohort studies exceeding $2 million, eliminating bootstrap-funded entrants from high-revenue use cases.
- Biometric dataset concentration:Predictive accuracy depends on training data diversity that incumbent platforms have accumulated through decade-long user retention, creating data moats that new algorithms cannot replicate.
- Hardware-software bundling dependency:Premium revenue increasingly requires wearable device partnerships where Apple and Samsung extract 15-30% platform fees, compressing developer margins on highest-ARPU segments.
Strategic Opportunities
- Endometriosis diagnostic adjacency:Symptom correlation algorithms trained on pain-score patterns can shorten diagnostic delays from 7 years to 18 months, opening reimbursement pathways through employer wellness contracts.
- Germany DiGA fast-track:Digital Health Applications approval under BfArM creates statutory reimbursement for menstrual health apps prescribed by gynecologists, converting consumer discretionary spend into insured benefit.
- Large language model triage:Conversational AI integration enables symptom-to-specialist routing that captures referral fees from health systems seeking to reduce unnecessary emergency department visits.
Industry Challenges
- Algorithmic bias in irregular cycles:PCOS and perimenopausal populations exhibit pattern variance that degrades prediction accuracy, exposing developers to liability claims when contraceptive failures occur in underrepresented training demographics.
- EHR interoperability fragmentation:HL7 FHIR implementation varies across Epic, Cerner, and Meditech installations, requiring bespoke integration engineering for each health system deployment rather than scalable API connections.
- User protocol adherence decay:Basal body temperature logging compliance drops 60% after 90 days, undermining the input data quality that algorithmic accuracy depends upon for clinical-grade claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menstrual Health Apps Market |
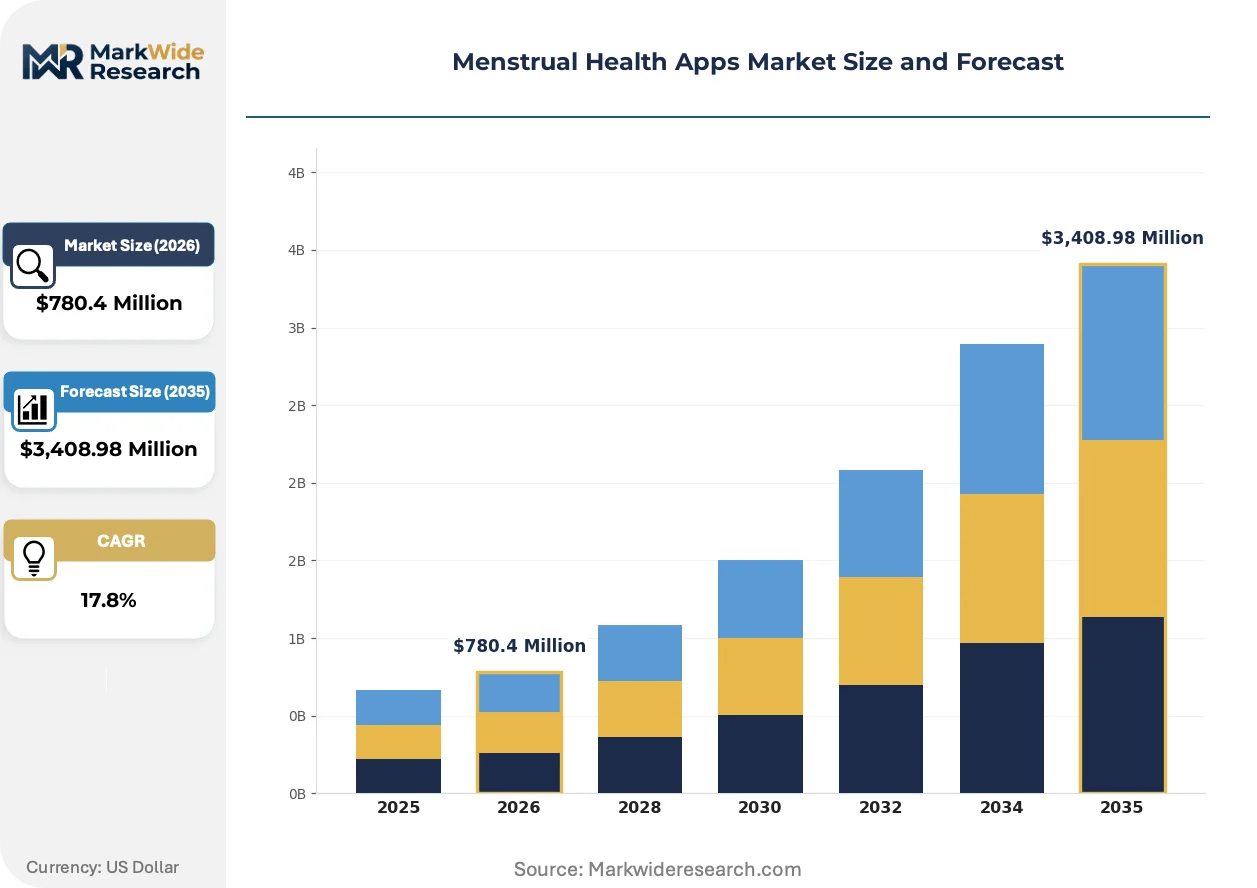
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $3,408.98 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Tracking, Education, Symptoms Management, Community Support User Demographic: Adolescents, Adults, Reproductive Health Professionals, Postmenopausal Users Technology: Mobile Apps, Wearable Devices, Web Platforms, AI-Driven Features Subscription Model: Free, Freemium, Monthly Subscription, Annual Subscription |
| Companies Covered | Ovia Health, Natural Cycles, Flo Health, Bellabeat, Ava Science, Clue, Apple, Hormona, Glow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menstrual Health Apps Market Strategic Shifts & Innovations
Passive sensing technologies and regulatory clarity are converging to transform menstrual health apps from consumer wellness tools into clinically validated diagnostic platforms, restructuring competitive advantage around evidence depth rather than marketing efficiency.
Continuous glucose monitoring sensors are decomposing the manual data entry bottleneck that has constrained cycle prediction accuracy. Women with insulin-resistant PCOS adopt CGM-integrated tracking at accelerating rates through partnerships with Levels and Nutrisense. This sensor convergence is decomposing the subscription-only revenue model by enabling hardware-software bundles that capture 3-4x per-user lifetime value.
EMA's 2023 guidance on software-as-medical-device classification clarifies contraceptive algorithm validation requirements for European market entry. Manufacturers must now submit post-market surveillance protocols demonstrating real-world effectiveness data across diverse cycle populations. German and French notified bodies are processing certification applications 40% faster than 2021 baselines, accelerating commercial timelines for compliant developers.
Employer wellness procurement now mandates menstrual health benefits as standard reproductive care coverage. Large self-insured corporations in the United States negotiate direct contracts with app developers, bypassing consumer app store distribution. This channel migration concentrates revenue in annual enterprise licenses with 85% retention rates, displacing the high-churn monthly subscription model that dominated 2018-2022 consumer growth phases.
Menstrual Health Apps Market Segmentation
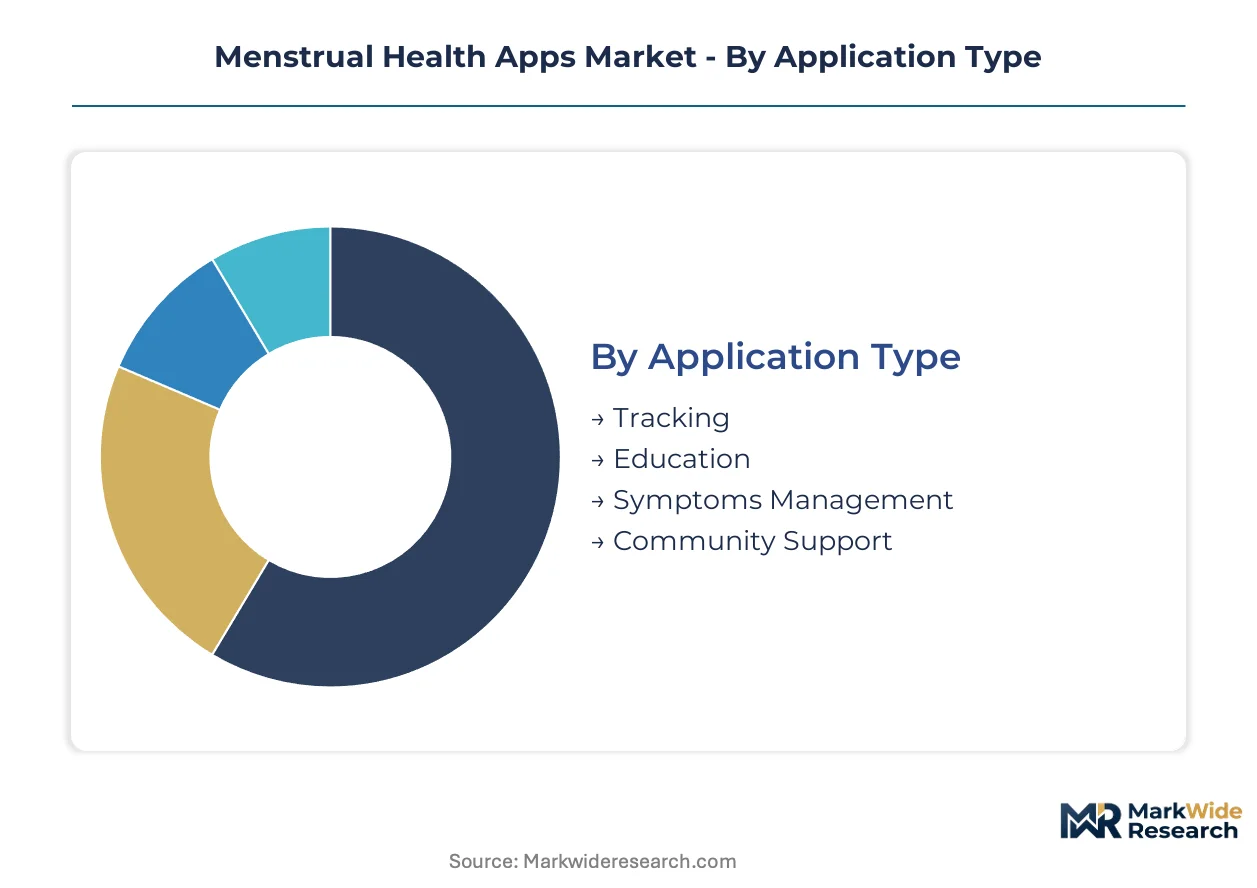
Segmentation in menstrual health apps determines which use cases attract clinical validation investment versus consumer marketing spend. Application type and subscription model together shape unit economics, while technology integration depth separates premium tiers from commodity tracking tools.
Application Type:
Tracking functions face intensifying substitution pressure from general wellness platforms adding cycle logging, forcing differentiation through diagnostic-grade accuracy claims.
- Tracking:Core cycle prediction algorithms process basal body temperature, cervical mucus, and symptom logs to forecast fertile windows. Demand concentrates among users seeking contraceptive precision in the United States and Germany, where FDA and BfArM clearance commands premium pricing power.
- Education:Curated content libraries covering menstrual health literacy, hormonal biology, and reproductive anatomy serve adolescent onboarding and healthcare provider training. Schools and employer wellness programs in South Korea and Brazil drive institutional licensing growth as digital health curricula expand.
- Symptoms Management:Pain-score logging and medication reminders for endometriosis, PCOS, and dysmenorrhea support therapeutic monitoring between clinical visits.
- Community Support:Peer forums and moderated discussion groups reduce isolation for rare condition patients but face moderation cost pressures and platform liability exposure.
Tracking anchors the volume base while Symptoms Management gains share at the steepest rate through diagnostic adjacency partnerships.
User Demographic:
Cost tier stratification separates ad-supported free tiers from enterprise-licensed professional tools with EHR integration capabilities.
- Adolescents:Privacy-first designs with parental control bypass features and school-friendly content filters capture first-time smartphone users. India's low-cost Android ecosystem and Indonesia's rising teen smartphone penetration expand this segment fastest.
- Adults:Fertility planning and contraceptive management dominate usage intensity, with basal body temperature protocol adherence highest among 25-34 age cohorts seeking pregnancy prevention or achievement.
- Reproductive Health Professionals:Clinical dashboard versions enable gynecologists to monitor patient-reported outcomes between visits, requiring HIPAA and GDPR-compliant data architectures that only well-capitalized developers sustain.
- Postmenopausal Users:Perimenopausal symptom tracking and hormone therapy monitoring represent an underserved niche with lower protocol adherence but higher willingness to pay for specialist integration.
Adults generate the revenue core while Adolescents expand most quickly through emerging market smartphone penetration.
Technology:
Supply concentration in wearable hardware partnerships determines which software developers capture premium ARPU through bundled sensor ecosystems.
- Mobile Apps:Native iOS and Android applications remain the dominant distribution channel, with manual data entry friction constraining long-term retention. South Korean and German developers lead in clinical interface design for medical device classification compliance.
- Wearable Devices:Continuous temperature and heart-rate variability monitoring through Apple Watch and Oura Ring APIs enables passive data collection. Hardware-software bundles command 3-4x lifetime value but face 15-30% platform fee extraction.
- Web Platforms:Browser-based access serves enterprise wellness deployments and healthcare system integrations requiring SSO authentication and EHR connectivity.
- AI-Driven Features:Large language models power conversational symptom triage and predictive health coaching, attracting development investment despite hallucination liability risks in medical contexts.
Mobile Apps sustain the installed base while Wearable Devices climb fastest through sensor convergence and premium bundling strategies.
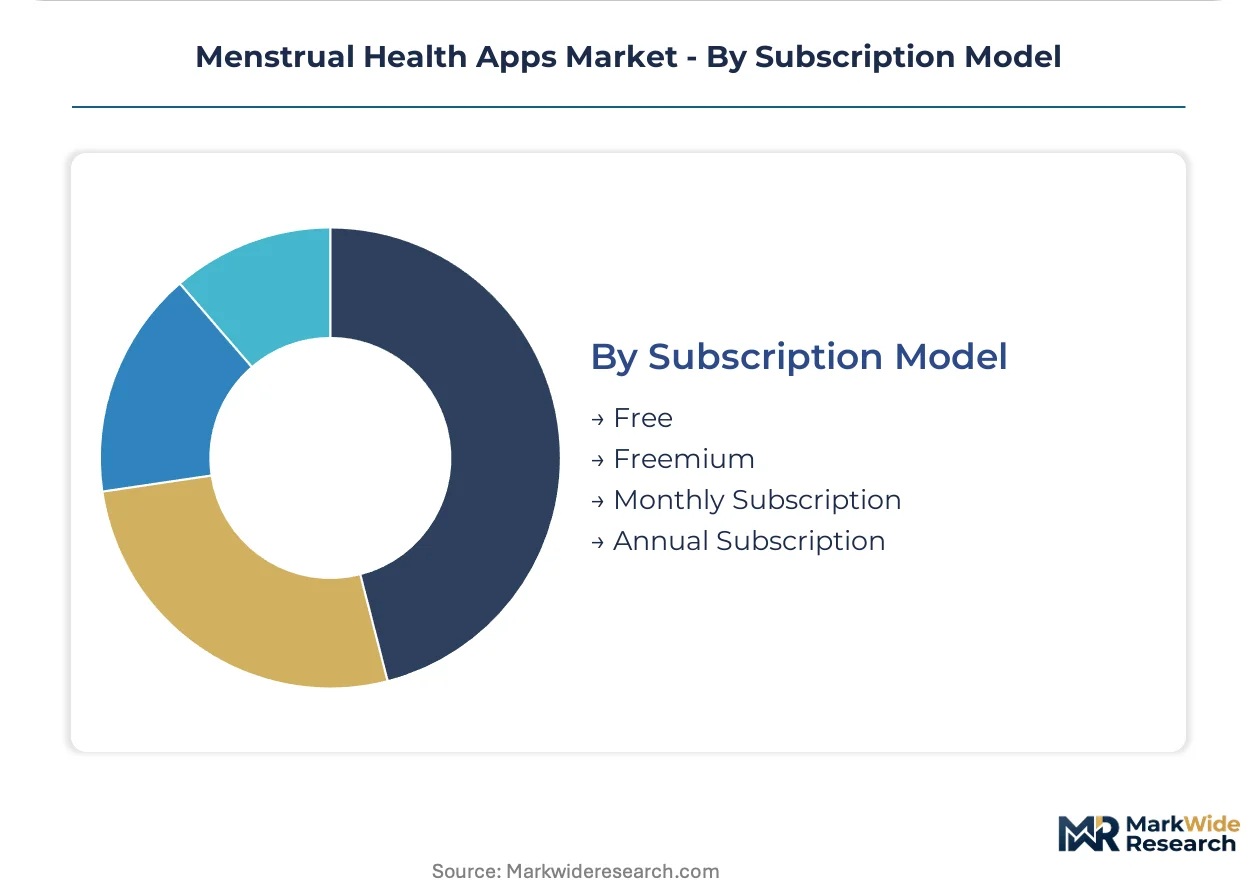
Subscription Model:
Maturity gradients separate established annual subscription retention models from experimental enterprise licensing structures.
- Free:Ad-supported basic tracking with limited prediction horizons serves user acquisition funnels but generates minimal revenue per active user.
- Freemium:Tiered feature gates convert 3-5% of users to paid tiers through advanced analytics and export capabilities, dominating 2018-2022 growth phases.
- Monthly Subscription:Flexible commitment terms attract trial users but exhibit 60%+ churn within 90 days, undermining lifetime value calculations.
- Annual Subscription:Prepaid commitments reduce churn below 15% and concentrate profitability, now supplemented by employer wellness direct contracts bypassing app store distribution.
Annual Subscription anchors developer cash flows while employer-bundled Freemium conversions emerge as the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer headquarters cluster in jurisdictions with mature digital health reimbursement pathways, while user acquisition investments target emerging economies where smartphone penetration is accelerating fastest.
United States
Employer wellness procurement mandates and FDA 510(k) clearance requirements concentrate premium revenue in enterprise channels. HIPAA compliance costs exceed $500,000 annually for EHR-integrated platforms, filtering out undercapitalized entrants. Boston and San Francisco anchor clinical validation partnerships with academic medical centers.
Germany
BfArM DiGA fast-track approval converts consumer subscriptions into statutory reimbursement, with gynecologists prescribing certified apps as preventive care. EU MDR classification guidance provides regulatory certainty that attracts institutional investment. Berlin and Munich host the majority of notified body consulting expertise for software-as-medical-device certification.
South Korea
MFDS digital health framework and national health insurance pilot programs create reimbursement infrastructure ahead of regional peers. K-beauty and femtech convergence drives hardware-software bundling innovation. Seoul Capital Area concentrates developer talent and venture capital deployment for wearable integration protocols.
India
Low-cost Android penetration among young adult women expands addressable populations beyond legacy markets. Data localization requirements under pending digital health legislation increase compliance engineering costs. Bangalore and Hyderabad clusters specialize in AI-driven symptom triage development for irregular cycle populations.
Brazil
ANVISA medical device classification for fertility apps remains ambiguous, delaying institutional investment despite large user populations. Private health insurance expansion creates indirect reimbursement channels through employer wellness contracts. São Paulo anchors Portuguese-language content development and Latin American market entry strategies.
Menstrual Health Apps Market Key Industry Players
Concentration sits with FDA-cleared platforms that have accumulated decade-long biometric datasets, while freemium challengers compete on user acquisition efficiency without clinical validation moats. Three archetypes dominate: regulated medical device developers with contraceptive indications, wellness-originated platforms pivoting toward diagnostic claims, and hardware-integrated specialists capturing premium bundling revenue. M&A activity targets data-rich user bases rather than technology assets, while strategic partnerships with wearable manufacturers determine ARPU ceiling.
Within the regulated medical device tier, Natural Cycles and Flo Health exemplify divergent competitive positioning—one anchoring contraceptive clearance as a regulatory moat, the other leveraging scale effects across irregular cycle populations. Clue occupies a therapeutic adjacency specialization that general trackers cannot easily replicate. These three entities collectively represent the evidence-generation standard that reimbursement bodies and employer wellness procurement now require as table stakes.
| Leading Market Players |
|---|
| Ovia Health |
| Natural Cycles |
| Flo Health |
| Bellabeat |
| Ava Science |
| Clue |
| Apple |
| Hormona |
| Glow |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance and EU MDR certification simultaneously gate supply-side qualification and stratify price tiers, forcing developers to absorb multimillion-dollar clinical validation costs that separate regulated medical device platforms from ad-supported consumer trackers.
Pricing Analysis
FDA 510(k) dictates the pricing tier structure by mandating prospective cohort studies for contraceptive indications, creating a three-tier pricing structure across premium, standard, and economy levels. Certification grade and algorithmic accuracy claims drive price differentiation, with BfArM DiGA-cleared apps commanding statutory reimbursement premiums. Cost compression in the freemium tier intensifies as general wellness platforms add cycle logging without clinical validation. Adolescents in emerging economies exhibit highest price sensitivity, while employer wellness contracts in Germany and the United States show lowest sensitivity due to insured benefit structures.
Supply Chain Analysis
Apple HealthKit and Google Fit API access underwrites downstream distribution control for wearable-integrated platforms, creating platform dependency chokepoints. Software development concentrates in the United States, Germany, and South Korea, with AI model training anchored in India and cloud infrastructure resting on Amazon Web Services and Microsoft Azure. Single-source vulnerability runs through Apple and Samsung hardware partnerships where 15-30% platform fees extract developer margins. Distribution runs through direct enterprise licensing to employer wellness programs, bypassing consumer app store channels for highest-ARPU segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in clinical-grade algorithm validation expertise concentrates competitive advantage among entities that have already absorbed FDA and EMA compliance costs, leaving late entrants to compete on marketing efficiency rather than evidence depth.
For Market Incumbents: Secure biometric dataset moats through decade-long user retention programs that new algorithms cannot replicate, while deepening wearable hardware partnerships to capture 3-4x lifetime value through bundled sensor ecosystems. Defend against wellness-platform substitution by accelerating endometriosis and PCOS diagnostic adjacency claims that require clinical validation barriers.
For New Entrants and Emerging Players: Lead with perimenopausal symptom tracking in employer wellness channels, a white-space segment with lower competitive density and higher willingness to pay for specialist integration. Target India's low-cost Android ecosystem through privacy-first adolescent designs with parental control bypass features, leveraging the country's AI development clusters for irregular cycle algorithm training.
For Investors and Strategic Acquirers: Carve-out targets emerge from wellness-originated platforms pivoting toward diagnostic claims but lacking capital for FDA 510(k) submission. Long-term viability hinges on reimbursement pathway capture rather than consumer subscriber growth alone. Watch Germany's DiGA expansion and United States employer wellness procurement mandates as inflection signals for enterprise channel migration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Contraceptive indication clearance creates regulatory moats that bootstrap-funded entrants cannot replicate. |
| BfArM DiGA Certification | Statutory reimbursement in Germany converts consumer discretionary spend into insured benefit streams. |
| Wearable Integration Partnership | Apple Watch and Oura Ring API access enables passive data collection with 3-4x lifetime value capture. |
| Employer Wellness Contract | Direct enterprise licensing bypasses app store distribution with 85% annual retention rates. |
| Endometriosis Diagnostic Adjacency | Symptom correlation algorithms shorten diagnostic delays and open reimbursement through wellness contracts. |
Research Approach
Cross-validation between primary interviews with femtech executives, regulatory affairs specialists, and employer wellness procurement officers and secondary validation through FDA 510(k) filings, EMA MDR submissions, and BfArM DiGA approval databases anchors the qualitative findings. Bottom-up triangulation incorporates app store download estimates and enterprise licensing disclosures, while top-down analysis cross-checks against digital health reimbursement policy frameworks across the United States, Germany, and South Korea.
Sensitivity analysis across algorithm accuracy assumptions, user protocol adherence decay curves, and wearable hardware penetration rates shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include application type, user demographic, technology integration depth, and subscription model tier. CAGRs derive from smartphone penetration trajectories in emerging economies and reimbursement pathway maturation timelines. Forecast inputs incorporate FDA enforcement intensity and EU MDR notified body processing speeds.
The analysis sits within stated boundaries; outcomes outside sustained regulatory clarity and employer wellness procurement expansion would require recalibration. Forecasts reflect documented assumptions about algorithm training set diversity and user protocol adherence. Practitioners should keep alternative scenarios live as FDA 510(k) enforcement intensity and EU MDR certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Menopause Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Maternal Health Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Devices Market
Women's Health
Women's Health App Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Women's Digital Health Market
Women's Health
Women Health Care Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Software Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Mother and Child Healthcare Market
Women's Health
US Womens Health Market
Women's Health
Menstrual Cup Foam Wash Market