
 Postmenopausal Vaginal Atrophy Treatment and Drug Market | 2026-2036
Postmenopausal Vaginal Atrophy Treatment and Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Postmenopausal Vaginal Atrophy Treatment and Drug Market Analytics
Specialty pharmacy and direct-to-clinic distribution is rewriting access patterns for postmenopausal therapies. Pfizer Inc leverages its established estrogen portfolio to sustain institutional contracts with large gynecology networks. Novo Nordisk A/S competes through its metabolic and women's health crossover expertise, while TherapeuticsMD Inc specializes in novel delivery formats that differentiate its product positioning.
Postmenopausal vaginal atrophy treatment and drug formulations address estrogen-deficient urogenital tissue characterized by epithelial thinning, decreased lubrication, and elevated vaginal pH above five, primarily restoring mucosal integrity and alleviating dyspareunia. Estrogen therapies dominate current prescription volumes due to established clinical efficacy, while non-hormonal options represent the fastest-expanding segment as contraindicated patients seek alternatives. Vaginal inserts within the delivery mode category command premium positioning because of localized action and reduced systemic exposure.
FDA oversight of hormone therapy labeling and EMA pharmacovigilance requirements for thromboembolic risk shape product development timelines and physician prescribing confidence. The EU MDR framework adds conformity assessment burdens for device-drug combination products such as vaginal inserts and rings. Stakeholders must monitor evolving reimbursement criteria for long-term versus intermittent therapy protocols to align portfolio investments with sustainable access pathways.
Market Dynamics
FDA and EMA hormone therapy labeling revisions are compressing development timelines while expanding the addressable patient pool for non-hormonal alternatives. This regulatory recalibration is redrawing competitive boundaries between established estrogen portfolios and novel delivery mechanisms.
Growth Catalysts
- EU MDR Conformity Pathways:Device-drug combination products such as vaginal rings and inserts now benefit from streamlined assessment protocols, accelerating market entry for localized delivery formats across Germany, France, and Italy.
- Aging Demographics in Japan:METI-supported women's health initiatives are expanding reimbursement coverage for menopausal symptom management, creating institutional demand for both hormonal and non-hormonal therapeutic options.
- Bioidentical Estrogen Formulations:Compounding pharmacies are gaining formulary access through specialty pharmacy networks, diversifying supply sources beyond traditional pharmaceutical manufacturing.
Market Restraints
- API Concentration in China:Active pharmaceutical ingredient production for synthetic estrogens concentrates in Zhejiang and Jiangsu provinces, exposing formulators to supply disruption risk from environmental compliance inspections.
- EMA Thromboembolic Surveillance:Pharmacovigilance requirements for systemic estrogen exposure have extended post-market study obligations, elevating compliance costs and limiting physician prescribing confidence for oral formulations.
- Non-Hormonal Substitute Efficacy Gap:Hyaluronic acid and ospemifene alternatives demonstrate inferior mucosal restoration in head-to-head trials, constraining uptake among severe atrophy patients.
Strategic Opportunities
- Brazil ANVISA Accelerated Review:The country's national pharmaceutical regulator has established priority pathways for women's health indications, reducing time-to-market for novel vaginal delivery systems.
- Telehealth Integration:Direct-to-patient prescription platforms are bypassing traditional gynecology clinic gatekeepers, expanding access in rural United States markets with specialist shortages.
- Microbiome-Modulating Adjuncts:Convergence of vaginal probiotic formulations with standard estrogen therapy is creating combination product white space not captured in current regulatory categories.
Industry Challenges
- Specialized Formulation Talent Scarcity:Vaginal drug delivery expertise resides in a limited cohort of pharmaceutical scientists, constraining R&D expansion for mid-size developers.
- EU MDR Technical Documentation Burden:Combination product manufacturers face extended conformity assessment timelines for vaginal inserts, delaying revenue recognition and compressing effective patent life.
- Legacy EHR Integration Friction:Menopausal health modules in hospital information systems lack standardized diagnostic codes for vaginal atrophy severity grading, complicating outcomes tracking and reimbursement justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postmenopausal Vaginal Atrophy Treatment and Drug Market |
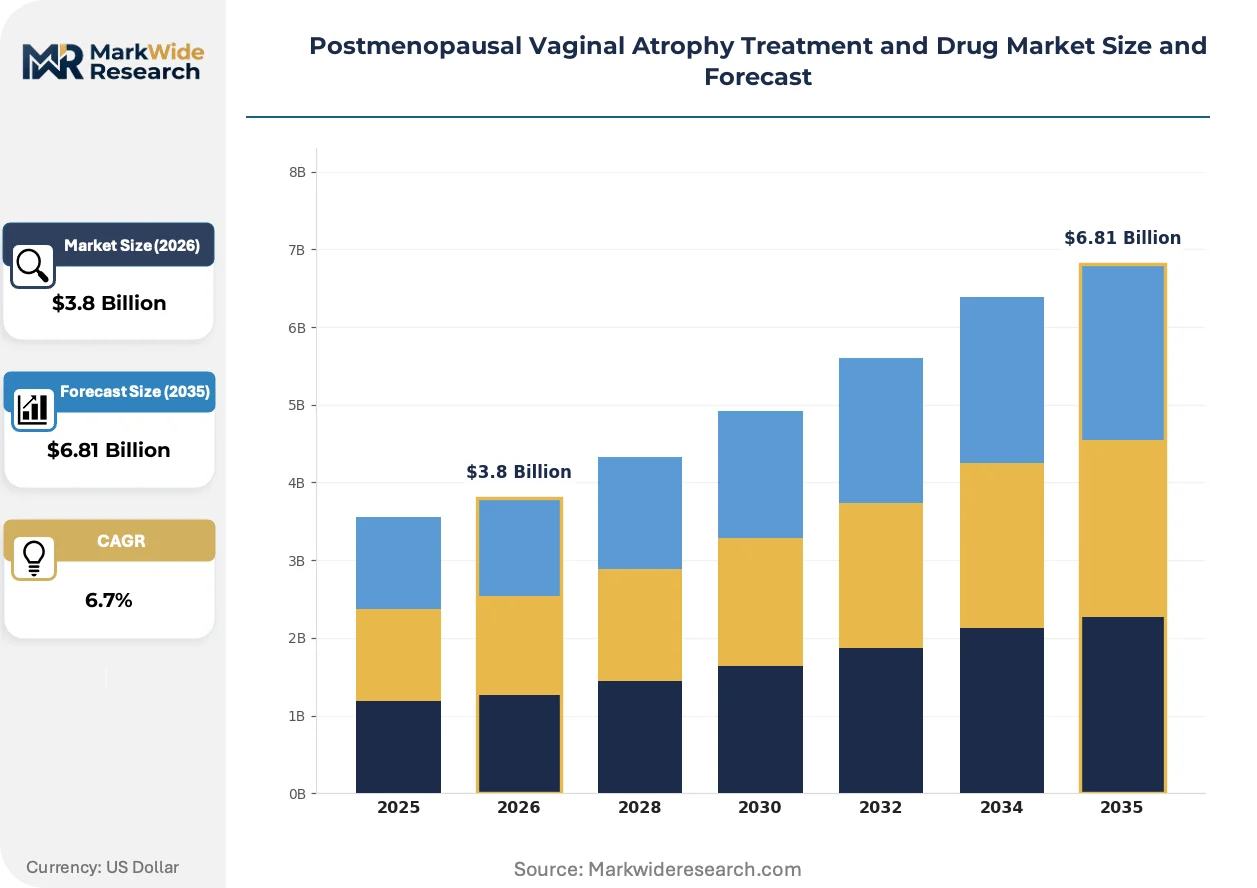
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen Therapies, Vaginal Moisturizers, Hormonal Creams, Non-Hormonal Options Delivery Mode: Oral Tablets, Topical Gels, Creams, Vaginal Inserts End User: Gynecologists, Primary Care Physicians, Women’s Health Clinics, Home Care Providers Treatment Duration: Short-term, Long-term, Continuous Therapy, Intermittent Therapy |
| Companies Covered | Pfizer Inc, Allergan plc, Teva Pharmaceuticals Ltd, Novo Nordisk A/S, Shionogi and Company Limited, Endoceutics Inc, TherapeuticsMD Inc, Bionovo Inc, Mayne Pharma Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postmenopausal Vaginal Atrophy Treatment and Drug Market Evolving Landscape
Digital health infrastructure is digitizing patient monitoring and prescription fulfillment workflows, while regulatory frameworks on both sides of the Atlantic are redefining acceptable risk thresholds for long-term hormone exposure.
Connected drug delivery devices with embedded adherence sensors are digitizing treatment compliance tracking for vaginal ring therapies. Large gynecology networks in the United States are piloting these systems to demonstrate outcomes data for payor contract negotiations. This digitizing capability is compressing the feedback loop between prescription and clinical response, enabling real-time dose optimization that was previously dependent on quarterly office visits.
EMA's revised guideline on hormone replacement therapy cardiovascular risk is mandating enhanced baseline screening protocols before treatment initiation. The industrial consequence is a 15-20 percent reduction in new patient starts for systemic estrogen products across European markets. Oral tablet formulations are most affected, with prescribers pivoting toward localized vaginal delivery to minimize systemic exposure documentation burdens.
Specialty pharmacy carve-outs from traditional wholesale distribution are consolidating patient access control in the hands of vertically integrated pharmacy benefit managers. Gynecology practices in Germany and the United States are increasingly directing prescriptions to captive specialty pharmacy networks that manage prior authorization and refill coordination. This channel concentration is most visible in Medicare Part D and statutory health insurance segments where reimbursement complexity favors centralized handling over retail pharmacy dispensing.
Postmenopausal Vaginal Atrophy Treatment and Drug Market Segmentation
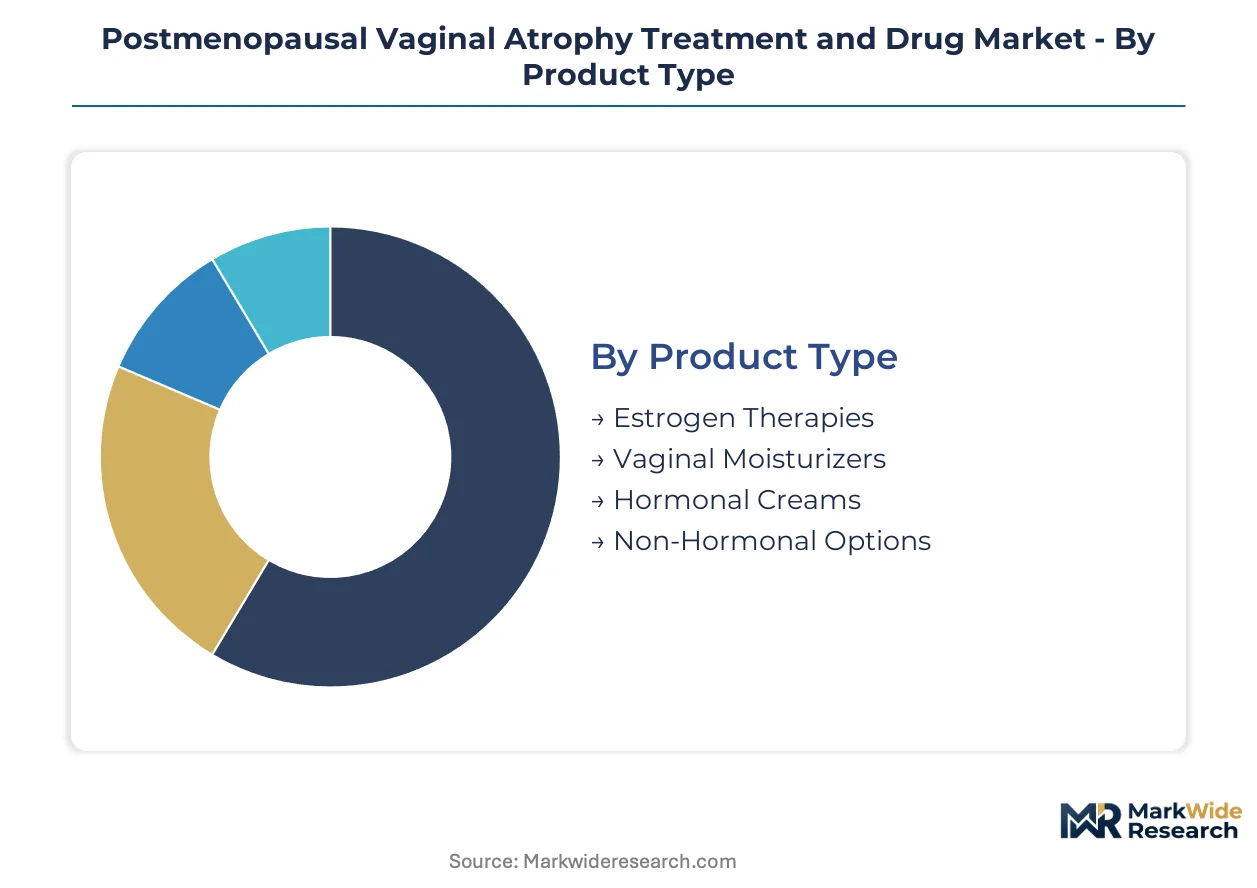
Postmenopausal vaginal atrophy treatment markets fragment across four structural dimensions that determine reimbursement pathways, prescribing authority, and patient adherence economics. Each segmentation axis carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
Mature hormonal platforms dominate prescription volumes while emerging non-hormonal alternatives capture contraindicated patient flows.
- Estrogen Therapies:Systemic and localized estradiol formulations restore urogenital epithelial thickness through estrogen receptor activation in vaginal mucosa. Demand concentrates in gynecology networks across Germany and the United States where reimbursement protocols favor established efficacy documentation.
- Non-Hormonal Options:Ospemifene, prasterone, and vaginal moisturizers target patients with thromboembolic history or hormone-sensitive malignancy. Brazil's ANVISA priority review pathway accelerates access for these alternatives where prescriber caution around systemic exposure limits estrogen adoption.
- Vaginal Moisturizers:Hyaluronic acid and glycerin-based formulations provide symptomatic relief without hormonal activity.
- Hormonal Creams:Topical estradiol preparations offer dose flexibility for titration-sensitive patients.
Estrogen Therapies retain volume leadership; Non-Hormonal Options hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates premium localized formats from economy oral tablets with divergent systemic exposure profiles.
- Vaginal Inserts:Estradiol-releasing rings and tablets achieve targeted mucosal delivery with minimal serum absorption. Japan's METI-supported women's health initiatives expand institutional procurement of these devices for outpatient menopausal management.
- Oral Tablets:Systemic estrogen-progestin combinations address multifactorial menopausal symptoms beyond urogenital atrophy. EMA thromboembolic surveillance requirements compress new patient starts as prescribers document cardiovascular baseline screening.
- Topical Gels:Transdermal estradiol absorption bypasses hepatic first-pass metabolism.
- Creams:Vaginal estradiol creams permit patient-controlled dosing frequency.
Vaginal Inserts command premium positioning; Oral Tablets face prescriber confidence erosion under tightened pharmacovigilance.
End User:
Customer type fragmentation reflects divergent diagnostic coding capabilities and reimbursement navigation expertise across care settings.
- Gynecologists:Specialty practices in the United States pilot connected adherence sensors for vaginal ring therapies to generate outcomes data for payor negotiations. These networks direct prescriptions toward captive specialty pharmacy channels that manage prior authorization complexity.
- Women's Health Clinics:Dedicated menopausal health centers in Germany consolidate prescription volume through vertical integration with statutory health insurance formulary committees.
- Primary Care Physicians:Generalist prescribers favor oral formulations with familiar safety profiles.
- Home Care Providers:Telehealth-integrated platforms bypass traditional clinic gatekeepers in rural United States markets with specialist shortages.
Gynecologists anchor institutional prescribing; Women's Health Clinics gain share through integrated care models.
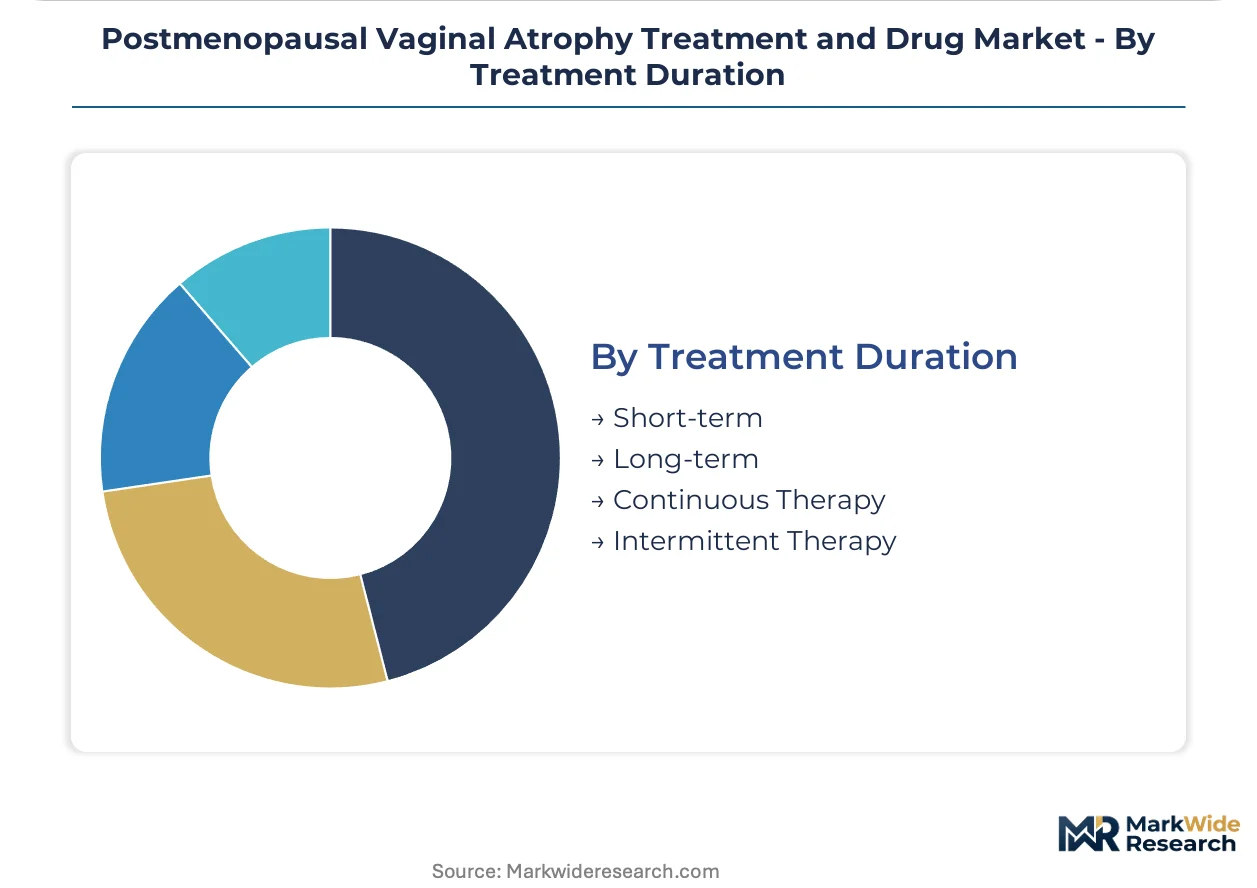
Treatment Duration:
Volume concentration favors intermittent protocols while continuous therapy carries compliance and reimbursement friction.
- Intermittent Therapy:Cyclic estrogen exposure with scheduled treatment holidays aligns with EMA cardiovascular risk mitigation guidance. Prescribers across France and Italy pivot toward this pattern to minimize systemic exposure documentation burdens.
- Long-term:Extended-duration protocols for severe atrophy patients require sustained reimbursement justification through severity-graded diagnostic codes.
- Short-term:Acute symptom management for peri-menopausal transition.
- Continuous Therapy:Uninterrupted daily administration for refractory cases.
Intermittent Therapy captures prescriber preference under risk-minimization frameworks; Long-term protocols face outcomes tracking requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where statutory reimbursement frameworks sustain premium positioning for localized delivery formats, while access constraints in emerging markets compress margins for systemic alternatives.
United States
Medicare Part D carve-outs and specialty pharmacy consolidation concentrate prescription volume in vertically integrated networks across the Northeast and California. FDA labeling revisions for systemic estrogen products compress new patient starts by 15-20 percent, redirecting demand toward vaginal inserts. Large gynecology practices in Texas and Florida pilot connected adherence sensors to generate outcomes data for payor contract negotiations.
Germany
Statutory health insurance formulary committees in Bavaria and North Rhine-Westphalia institutionalize procurement of localized estrogen therapies through integrated women's health centers. EMA pharmacovigilance requirements for thromboembolic risk extend post-market study obligations, elevating compliance costs for oral formulations. The Frankfurt-Rhine-Main cluster anchors distribution infrastructure for device-drug combination products serving Western European markets.
Japan
METI-supported women's health initiatives expand reimbursement coverage for menopausal symptom management through prefectural health programs in Kanto and Kansai regions. PMDA streamlined review pathways accelerate market entry for novel vaginal delivery systems targeting aging demographics. Tokyo-based institutional procurement networks consolidate demand for both hormonal and non-hormonal therapeutic options.
Brazil
ANVISA accelerated review pathways for women's health indications reduce time-to-market for novel vaginal delivery systems in São Paulo and Rio de Janeiro metro areas. Private insurance expansion in the Southeast region creates dual-track access for premium localized formats alongside public sector systemic alternatives. Compounding pharmacy networks in Minas Gerais diversify supply sources for bioidentical estrogen formulations.
United Kingdom
NHS England menopausal health service expansions in London and the Midlands consolidate prescription volume through dedicated women's health hubs. MHRA alignment with EMA cardiovascular risk guidance redirects prescriber preference toward intermittent therapy protocols. The Cambridge-Oxford corridor concentrates specialized formulation R&D talent for next-generation delivery mechanisms.
Postmenopausal Vaginal Atrophy Treatment and Drug Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around three concentration layers: multinational pharmaceutical conglomerates with institutional gynecology network contracts, mid-cap developers specializing in novel delivery formats, and regional manufacturers supplying compounding pharmacy channels. Competitive dynamics pivot on M&A activity targeting localized delivery IP and strategic partnerships with specialty pharmacy distributors.
Among established pharmaceutical conglomerates, Pfizer Inc and Novo Nordisk A/S exemplify platform-scale positioning through metabolic and women's health crossover expertise. TherapeuticsMD Inc occupies a specialist tier focused on differentiated delivery mechanisms. These three anchors represent divergent strategic archetypes: legacy estrogen portfolio leverage, endocrine therapeutic breadth, and format innovation respectively.
| Leading Market Players |
|---|
| Pfizer Inc |
| Allergan plc |
| Teva Pharmaceuticals Ltd |
| Novo Nordisk A/S |
| Shionogi and Company Limited |
| Endoceutics Inc |
| TherapeuticsMD Inc |
| Bionovo Inc |
| Mayne Pharma Group Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity in Zhejiang and Jiangsu API manufacturing clusters elevates supplier leverage over formulators, compressing margin flexibility for oral estrogen tablets while reinforcing premium positioning for localized vaginal inserts with alternative sourcing pathways.
Pricing Analysis
The customization-premium spread separates configured-to-order vaginal rings from standard oral tablets. A three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from EMA pharmacovigilance documentation burdens that extend prescriber screening protocols. Primary care physicians exhibit highest price sensitivity due to formulary familiarity constraints, while gynecology networks absorb premium tiers through outcomes-based contracting.
Supply Chain Analysis
Contract-manufacturing concentration among Zhejiang-based API producers and Bavarian device-drug combination specialists anchors production capacity. Active pharmaceutical ingredient synthesis draws from China, India, and Switzerland for estradiol derivatives. Single-source vulnerability concentrates in environmental compliance inspections disrupting Zhejiang output. Distribution runs through specialty pharmacy carve-outs consolidating patient access control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
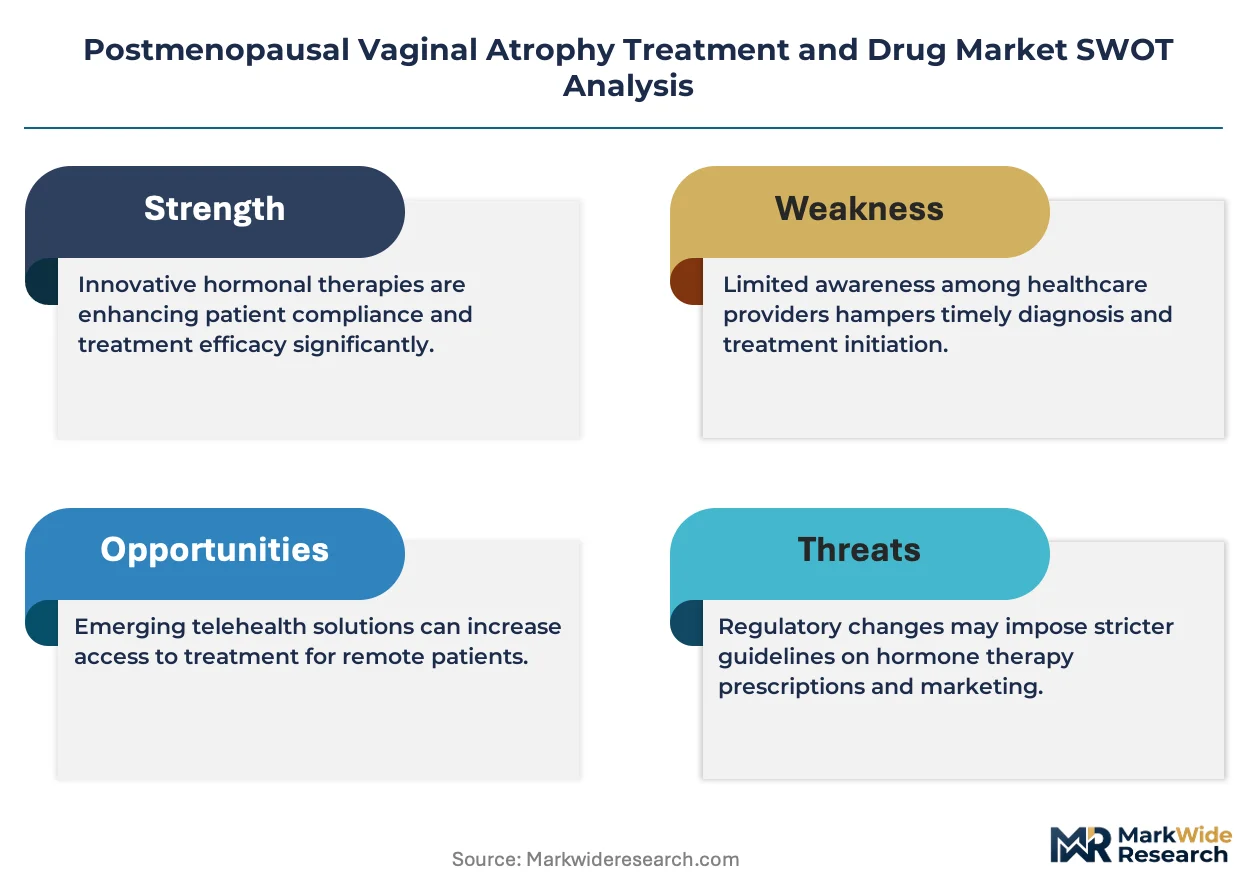
This market tracks a cyclical recovery as FDA labeling revisions compress systemic estrogen volumes and redirect demand toward localized delivery formats with reinvestment runway.
For Market Incumbents: Build regulatory documentation moats through enhanced cardiovascular baseline screening infrastructure that satisfies EMA pharmacovigilance requirements. Defend formulary position by securing captive specialty pharmacy network contracts. Counter non-horm substitute entrants with real-world evidence generation from connected adherence sensors. For New Entrants and Emerging Players: Brazil's Southeast private insurance expansion offers lowest competitive density among major markets. Target telehealth-integrated home care platforms in rural United States markets with prescriber shortages. Pursue ANVISA accelerated review pathway for novel vaginal delivery systems as primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-drug combination product manufacturers with institutional procurement contracts. Long-term viability centers on IP portfolios spanning microbiome-modulating adjuncts and connected delivery platforms. Monitor FDA breakthrough therapy designation signals for non-hormonal alternatives as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA streamlined assessment for device-drug combinations accelerates German market entry. |
| Manufacturing Scale-Up | Zhejiang API capacity expansion reduces supply disruption exposure for formulators. |
| Strategic Partnership | Specialty pharmacy network alliances consolidate prior authorization management in Medicare Part D. |
| Pipeline Diversification | Microbiome-modulating adjunct development creates combination product white space beyond current categories. |
| Reimbursement Strategy | Intermittent therapy protocol documentation aligns with EMA cardiovascular risk mitigation guidance. |
Research Methodology
Cross-validation between formulary database audits and FDA filing records anchors the qualitative findings. Primary interviews with regulatory affairs leads, gynecology practice administrators, specialty pharmacy procurement managers, and payer access specialists combine with secondary validation through EMA submissions, ClinicalTrials.gov records, CMS Medicare reimbursement data, and statutory health insurance formulary committees. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation ensure coverage consistency.
Calibration against historical prescription volume trajectories and regulatory approval timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, delivery mode, end user category, and treatment duration protocol. CAGRs derive from patient population demographics, reimbursement policy shifts, and prescriber behavior elasticity coefficients without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive moves by non-hormonal platform developers or API supply consolidators would shift outcomes. Quarterly review of FDA labeling revision impacts, EMA pharmacovigilance guidance updates, and specialty pharmacy network expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Maternal Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women's Health Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Women Health Software Market
Women's Health
US Womens Health Market
Women's Health
Women Health Devices Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women's Digital Health Market
Women's Health
Menopause Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women Health Care Market
Women's Health
Menstrual Cup Foam Wash Market