
 Health Coaching Market | 2026-2036
Health Coaching Market Size, Share, and Industry Trends Forecast 2026-2036
Health Coaching Market Analysis
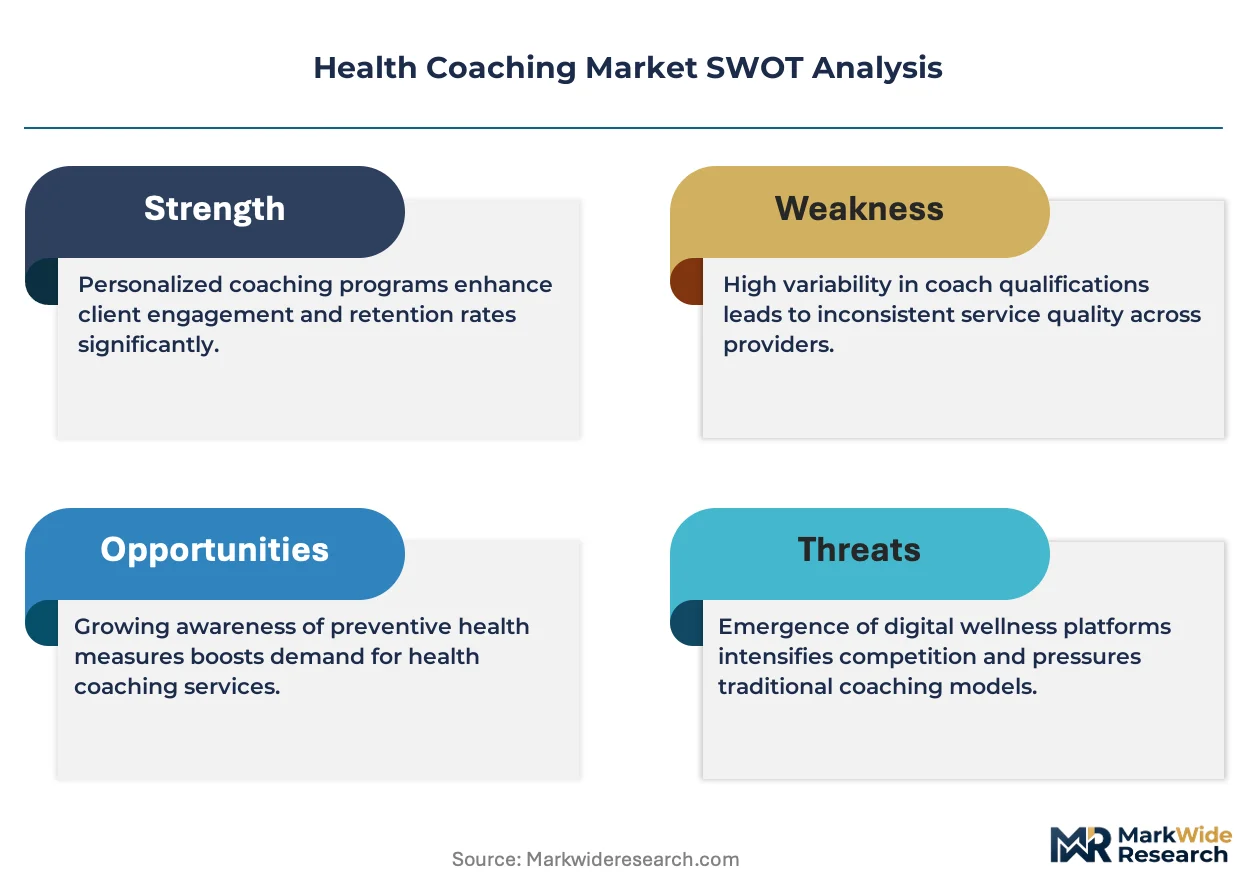
AI-driven personalization is broadening the addressable base for health coaching by replacing generic diet-and-exercise templates with metabolomic and behavioral data integration. Noom, Inc. leverages proprietary algorithms to sustain user engagement through psychology-based habit formation protocols. Omada Health Inc. anchors its competitive position in chronic disease prevention, while Lark Technologies, Inc. specializes in AI-powered chatbot delivery for diabetes and hypertension management.
Health coaching encompasses structured behavioral interventions delivered by certified professionals to modify lifestyle factors affecting chronic disease risk, metabolic function, and psychological resilience; platforms typically integrate biometric tracking, goal-setting protocols, and accountability mechanisms to produce measurable clinical outcomes. Personalized Coaching commands premium pricing due to higher perceived accountability and customized protocol design, whereas Virtual delivery mode captures the fastest expansion as asynchronous telehealth infrastructure matures and reimbursement frameworks adapt. Corporate Wellness segments accumulate concentrated margin pools through multi-year employer contracts and scalable population health dashboards.
FDA scrutiny of software-as-medical-device claims, HIPAA privacy mandates, and state-level scope-of-practice regulations for health coaches collectively determine platform compliance costs and market access barriers across jurisdictions. The Centers for Medicare & Medicaid Services continues evaluating coaching reimbursement codes, with coverage decisions poised to reshape provider economics and consumer price sensitivity. Stakeholders must monitor evolving regulatory distinctions between general wellness guidance and regulated medical advice, as classification determinations will dictate capital requirements and competitive moats for emerging platforms.
Market Dynamics
AI-powered behavioral analytics is compressing the cost curve for personalized health interventions while FDA software-as-medical-device classifications are redefining compliance boundaries for coaching platforms.
Growth Catalysts
- Employer-sponsored wellness mandates:Large corporations in the United States are embedding health coaching into benefits packages to reduce medical claims exposure and improve workforce productivity metrics.
- HIPAA-aligned data infrastructure:Secure cloud architectures enable biometric data sharing between coaches, wearable devices, and electronic health records without privacy liability.
- Metabolomic testing integration:At-home lab kits now feed real-time glucose, cortisol, and microbiome data into coaching algorithms for precision protocol adjustment.
Market Restraints
- State-level scope-of-practice fragmentation:Health coaches face inconsistent licensure requirements across California, Texas, and New York that limit interstate service delivery.
- Reimbursement code uncertainty:CMS has not finalized dedicated CPT codes for non-physician coaching, leaving revenue dependent on employer contracts and direct-to-consumer payments.
- Credential inflation:Proliferation of competing certification bodies dilutes quality signals and raises consumer confusion about coach qualifications.
Strategic Opportunities
- Medicare Advantage penetration:Supplemental benefit carve-outs for chronic disease management create a reimbursable channel for diabetes and hypertension coaching programs.
- Behavioral health integration:Coaching platforms that incorporate cognitive behavioral therapy protocols can capture spend from employers addressing workplace mental health crises.
- Asynchronous chatbot scale:AI-driven coaching delivery eliminates human labor bottlenecks and enables unit economics that support low-income consumer segments.
Industry Challenges
- Clinical outcomes measurement standardization:Platforms struggle to prove ROI without consensus metrics for weight loss maintenance, medication adherence, or hospitalization reduction.
- Coach recruitment and retention:Certified health coaches command premium wages that compress margins for platforms competing on price.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Coaching Market |
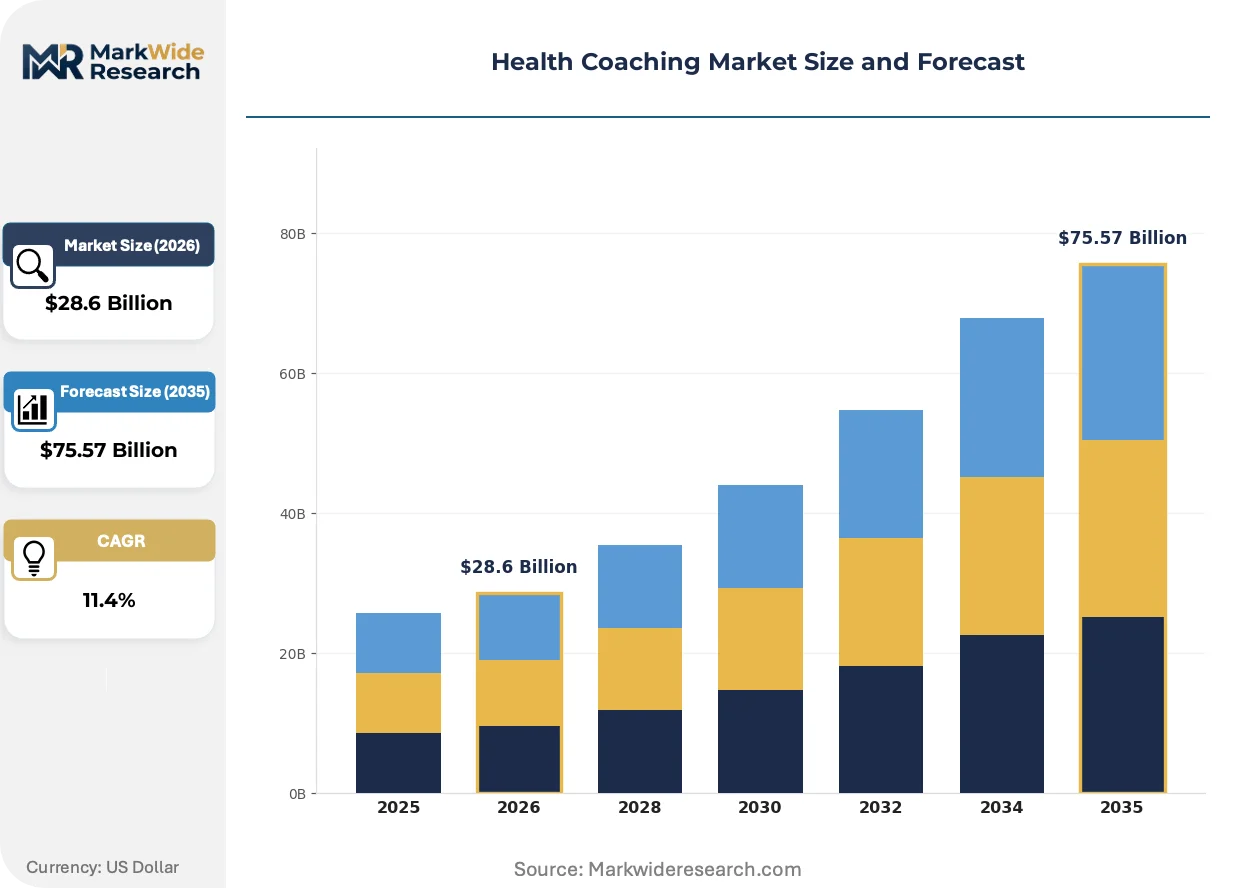
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personalized Coaching, Group Coaching, Online Sessions, Corporate Wellness Coaching Focus: Nutrition, Fitness, Mental Wellness, Chronic Disease Management Client Type: Individuals, Corporates, Healthcare Providers, Insurance Companies Delivery Mode: In-Person, Virtual, Hybrid, Mobile App |
| Companies Covered | Noom, Inc., Omada Health Inc., Lark Technologies, Inc., Wellcoaches Corporation, Advanced Wellness Systems, Wellness Coaches USA, Health Coach Institute, Precision Nutrition, Institute for Integrative Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Coaching Market Emerging Trajectories
Digital biomarker streams and predictive analytics are transforming coaching from reactive check-ins into preemptive health interventions that intercept metabolic decline before clinical symptoms manifest.
Continuous glucose monitors paired with microbiome sequencing is rewriting how metabolic coaching protocols are calibrated. Employers with self-insured health plans are adopting these integrated sensor-to-coach pipelines fastest. The technology is compressing the feedback loop between biological data and behavioral nudges from weeks to hours.
FDA draft guidance on software-as-medical-device determinations is forcing coaching platforms to reclassify their risk profiles. Products making specific disease management claims now face 510(k) clearance requirements that add eighteen to twenty-four months to launch timelines. Corporate wellness segments are responding by stripping diagnostic language from marketing materials while retaining clinical coaching protocols.
Benefit managers are unbundling coaching from traditional health plan administration and contracting directly with specialized platforms. This disintermediation bypasses insurance intermediaries and redirects premium dollars toward outcomes-contingent coaching fees. The shift is most visible in technology sector employers with concentrated workforces and high health cost sensitivity.
Health Coaching Market Segmentation
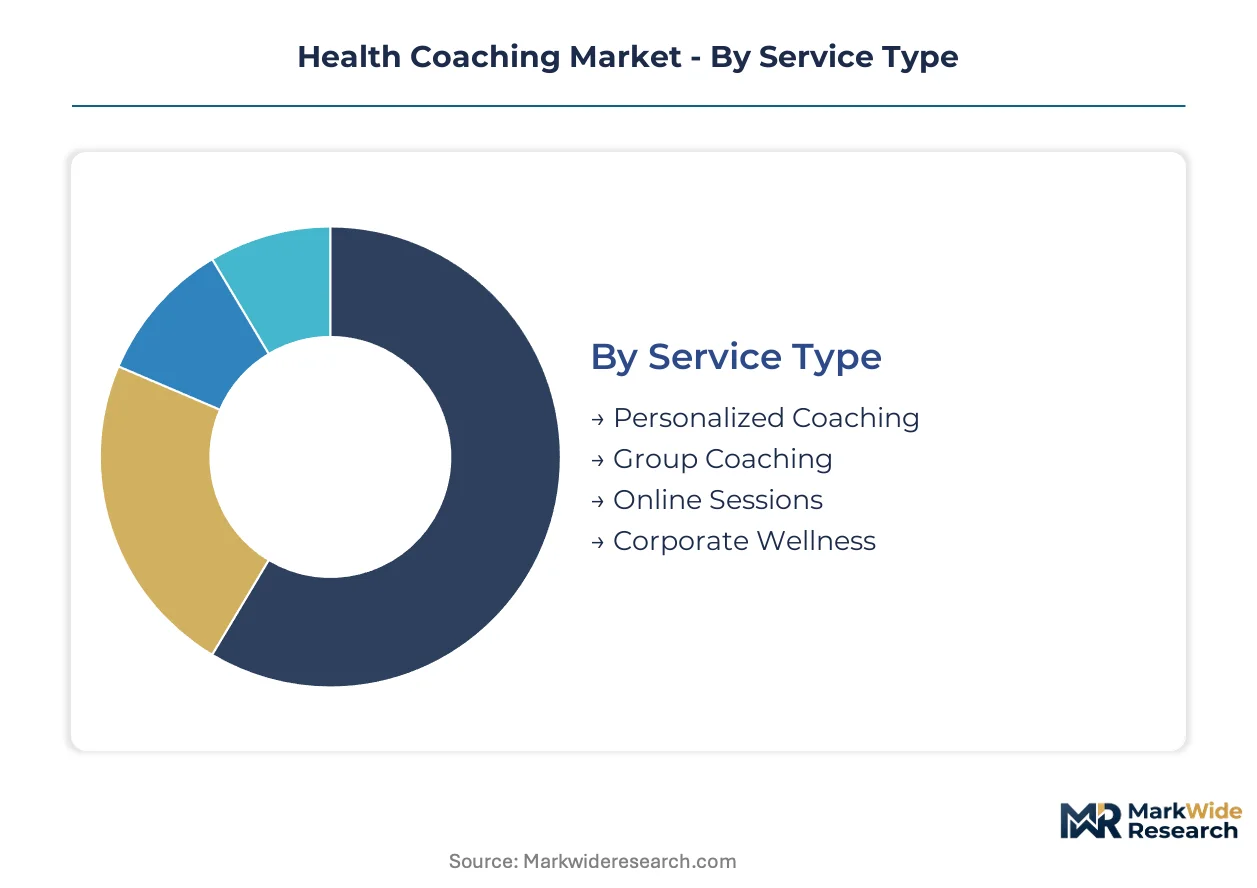
Health coaching platforms architect revenue streams around four distinct segmentation axes that determine pricing power, client acquisition costs, and regulatory exposure. Each category reflects divergent operational models—from high-touch personalized services to automated digital delivery—that reshape margin structures and competitive moats.
Service Type:
Customization intensity spans from bespoke one-on-one protocols to templated population health dashboards, with premium tiers commanding accountability premiums and standardized offerings scaling through employer contracts.
- Personalized Coaching:One-to-one behavioral interventions calibrated to individual biometrics, genetic markers, and lifestyle constraints. United States employers with self-insured health plans absorb premium pricing to reduce claims exposure and improve workforce productivity metrics. Higher perceived accountability sustains pricing power despite labor cost inflation.
- Corporate Wellness:Population-scale coaching embedded within multi-year employer contracts featuring scalable dashboards and outcomes-contingent fee structures. Technology sector employers with concentrated workforces and high health cost sensitivity drive fastest adoption through direct platform contracting that bypasses traditional insurance intermediaries.
- Group Coaching:Cohort-based behavioral interventions delivered to shared-goal participants at reduced per-capita cost.
- Online Sessions:Scheduled synchronous video coaching accessed through subscription or pay-per-session models.
Most installed capacity flows through Corporate Wellness. Expansion is steepest in Personalized Coaching.
Coaching Focus:
Clinical risk stratification determines reimbursement eligibility and regulatory scrutiny, with disease management claims triggering FDA software-as-medical-device classifications while general wellness guidance operates under lighter oversight.
- Chronic Disease Management:Structured interventions targeting diabetes, hypertension, and metabolic syndrome progression through continuous biomonitoring and medication adherence protocols. Medicare Advantage supplemental benefit carve-outs in the United States create reimbursable channels that reshape provider economics and consumer price sensitivity.
- Mental Wellness:Cognitive behavioral therapy integration and stress resilience protocols addressing workplace mental health crises. United States employers facing rising disability claims and absenteeism concentrate demand for coaching platforms that incorporate licensed behavioral health components.
- Nutrition:Dietary protocol design ranging from macro tracking to metabolomic-personalized meal planning.
- Fitness:Exercise programming and movement optimization delivered through wearable-integrated feedback loops.
Revenue concentrates in Chronic Disease Management. Mental Wellness climbs the fastest as employer behavioral health mandates expand.
Client Type:
Procurement authority and budget scale separate fragmented individual purchasers from institutional buyers with multi-year contracting horizons and population health risk pools.
- Corporates:Self-insured employers and benefits managers contracting directly with coaching platforms for workforce health optimization. Direct platform relationships redirect premium dollars toward outcomes-contingent fees that bypass traditional health plan administration markups.
- Insurance Companies:Payers integrating coaching as supplemental benefits or chronic care management riders. Coverage decisions by the Centers for Medicare & Medicaid Services reshape provider economics and consumer price sensitivity across United States markets.
- Individuals:Direct-to-consumer purchasers absorbing full out-of-pocket costs for preventive services.
- Healthcare Providers:Health systems and physician groups embedding coaching into care coordination workflows.
Contract volume peaks with Corporates. Insurance Companies gain share fastest as reimbursement frameworks mature.
Delivery Mode:
Human labor intensity versus automation depth defines unit economics, with synchronous formats constrained by coach supply and asynchronous platforms achieving marginal cost near zero.
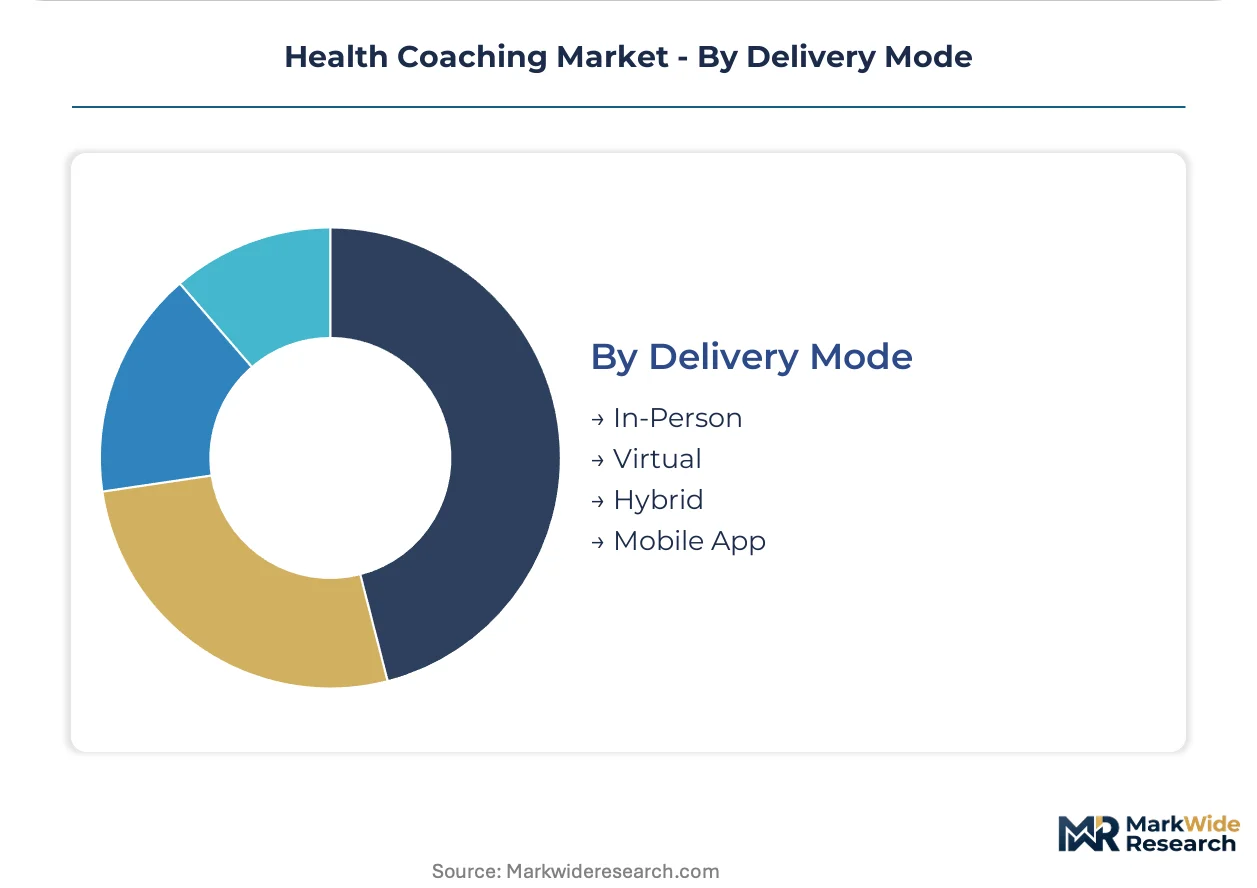
- Virtual:Asynchronous telehealth infrastructure enabling scheduled video sessions and digital messaging between coaches and clients. HIPAA-aligned cloud architectures permit biometric data sharing without privacy liability, while reimbursement code uncertainty from CMS leaves revenue dependent on employer contracts and direct payments.
- Mobile App:AI-driven chatbot delivery eliminating human labor bottlenecks through natural language coaching interfaces. Lark Technologies and similar platforms achieve unit economics supporting low-income consumer segments through algorithmic personalization that replaces generic diet-and-exercise templates.
- In-Person:Face-to-face coaching delivered at clinics, gyms, or employer sites with highest accountability perception.
- Hybrid:Blended human-AI delivery combining periodic live sessions with continuous digital touchpoints.
User volume flows predominantly through Virtual channels. Mobile App delivery expands most quickly as AI behavioral analytics compress intervention costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley employers anchor employer-sponsored coaching adoption through direct platform contracting that bypasses traditional health plan intermediaries. Self-insured corporations in technology clusters drive demand for outcomes-contingent wellness fees. Regulatory divergence across national jurisdictions fragments service delivery models.
United States
Employer-sponsored health benefits and elevated out-of-pocket medical costs concentrate consumer willingness to pay for preventive coaching services. FDA draft guidance on software-as-medical-device classifications imposes eighteen to twenty-four month delays for platforms making specific disease management claims. Boston and San Francisco Bay Area technology employers lead direct contracting with specialized coaching platforms.
Germany
Corporate wellness mandates under occupational health regulations expand reimbursable coaching channels for chronic disease prevention. EMA oversight of digital health applications elevates compliance requirements for platforms integrating biometric monitoring. Berlin and Munich health tech clusters attract coaching platforms seeking EU market entry through stringent regulatory pathways.
United Kingdom
NHS long-term plan integration of social prescribing creates referral pathways for lifestyle coaching interventions. MHRA software-as-medical-device classifications align with FDA trajectories, compressing launch timelines for platforms with diagnostic claims. London fintech and professional services employers drive private sector demand through supplemental benefit carve-outs.
Japan
Metabolic syndrome screening mandates expand employer liability for employee health outcomes, accelerating corporate wellness procurement. PMDA digital therapeutics frameworks create reimbursement codes for coaching platforms demonstrating clinical efficacy. Tokyo and Osaka metropolitan employers concentrate demand for integrated biometric-to-coach service pipelines.
Australia
Private health insurance ancillary coverage expansion creates reimbursable channels for preventive coaching services. TGA software-based medical device regulations require risk stratification for platforms making disease management claims. Sydney and Melbourne corporate headquarters drive adoption through self-insured workforce health optimization programs.
Health Coaching Market Vendor Landscape
Global majors compete with regional champions across employer contracting channels and regulatory compliance capabilities. Market structure fragments across psychology-based engagement platforms, chronic disease prevention specialists, and AI-native chatbot delivery systems. Three archetypes dominate: algorithmic personalization engines, human-coach accountability networks, and hybrid human-AI blended models. Dominant competitive moves include direct employer contracting that disintermediates traditional health plans and FDA risk reclassification to avoid medical device clearance timelines.
Within the algorithmic personalization tier, Noom, Inc. and Lark Technologies, Inc. exemplify platforms leveraging proprietary behavioral analytics to compress intervention costs. Omada Health Inc. occupies a position among chronic disease prevention specialists targeting metabolic syndrome progression through continuous biomonitoring integration. These three companies represent divergent strategic bets on automation depth versus human accountability in coaching delivery economics.
| Leading Market Players |
|---|
| Noom, Inc. |
| Omada Health Inc. |
| Lark Technologies, Inc. |
| Wellcoaches Corporation |
| Advanced Wellness Systems |
| Wellness Coaches USA |
| Health Coach Institute |
| Precision Nutrition |
| Institute for Integrative Nutrition |
| Others |
Supply Flow & Price Mechanics
Employer mandates for measurable health outcomes are forcing coaching platforms to restructure service delivery around biometric integration and accountability protocols, compressing margins for undifferentiated offerings while rewarding investments in AI-driven personalization infrastructure.
Pricing Analysis
Certified coach wages and metabolomic testing kit costs pass through directly to end-user subscription tiers. The dominant model is three-tier pricing structure across premium, standard, and economy levels, with price differentiation driven by coach credential level and real-time biomonitoring inclusion. Cost compression in the standard tier is intensifying because AI chatbot delivery eliminates human labor overhead. Self-insured employers show lowest price sensitivity; direct-to-consumer individuals absorb full cost burden with highest sensitivity.
Supply Chain Analysis
Continuous glucose monitor hardware rests on Taiwanese semiconductor foundries and South Korean sensor manufacturers for core chip components. Software development draws from Indian engineering centers and United States-based behavioral psychology research institutions. Single-source vulnerability concentrates in FDA-cleared medical device integrations. Distribution runs through employer benefits administrators and direct platform contracting that disintermediates traditional insurance intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The health coaching market compounds steadily as chronic disease prevalence and employer cost containment imperatives create durable demand for preventive behavioral interventions.
For Market Incumbents: To counter AI-native entrants compressing unit economics, incumbents should deepen backward integration into metabolomic testing infrastructure and secure multi-year employer contracts with outcomes-contingent pricing that locks in revenue visibility. FDA software-as-medical-device clearance investments create regulatory moats that delay challenger launch timelines. For New Entrants and Emerging Players: Medicare Advantage supplemental benefit carve-outs in the United States open a window for chronic disease management platforms to capture reimbursable revenue streams. White-space concentrates in asynchronous mental wellness coaching for mid-market employers and AI-native delivery for Medicaid-eligible populations. Go-to-market should anchor in direct benefits manager relationships rather than payer channel dependence. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid human-AI platforms that have demonstrated clinical outcome validation through employer pilots. Long-term viability hinges on reimbursement code finalization and FDA risk classification clarity. Acquisition targets should show installed employer bases with renewal rates above category norms. The signal to watch is CMS coverage decision timing for non-physician coaching services.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical device classification unlocks disease management claims and employer risk tolerance. |
| Employer Direct Contracting | Bypassing insurance intermediaries redirects premium dollars toward outcomes-contingent coaching fees. |
| AI Behavioral Analytics Integration | Proprietary algorithms compress intervention costs while sustaining engagement through psychology-based protocols. |
| Metabolomic Testing Partnership | Real-time glucose and microbiome data feeds precision protocol adjustment and premium pricing justification. |
| Reimbursement Strategy Development | Dedicated CPT code advocacy reshapes provider economics and consumer price sensitivity across United States markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with health coaching platform executives, employer benefits managers, certified health coaches, and FDA regulatory consultants with secondary validation against SEC filings, CMS reimbursement databases, and employer wellness program disclosures. Bottom-up employer contract analysis and top-down market sizing triangulated volume estimates.
Segment-weighted modeling distributed value across service type, coaching focus, client type, and delivery mode dimensions throughout the forecast period. CAGRs derived from employer adoption curve analysis and reimbursement framework evolution assumptions. Forecast inputs incorporated biometric sensor penetration rates and AI coaching platform user acquisition cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software-as-medical-device reclassification delays or CMS coverage denial scenarios. Forecasts reflect documented assumptions on employer self-insurance trends and chronic disease prevalence trajectories. A small set of named triggers—regulatory clearance timelines, reimbursement code finalization, and employer contract renewal rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Interdental Brush Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Menopause Wellness Market
Personal Health
Health Check-Up Market
Personal Health
Corporate Wellness Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Sleep Mask Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
South America Hair Loss Treatment Products Market
Personal Health
Earwax Removal Products Market
Personal Health
Patient Health Management Market
Personal Health
Tick Repellent Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Piercing Aftercare Spray Market