
 Menstrual Cup Foam Wash Market | 2026-2036
Menstrual Cup Foam Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Menstrual Cup Foam Wash Market Foresight
Plant-derived surfactant chemistry is reshaping formulation architecture across menstrual cup foam wash production. Diva International Inc. leverages its North American manufacturing base to anchor supply of pH-balanced cleansers. Sirona Hygiene Pvt. Ltd. competes through specialized distribution across Indian pharmacies and digital channels. Saalt LLC differentiates via concentrated unscented and organic SKUs targeting ingredient-sensitive users.
Menstrual cup foam wash comprises mild, non-ionic surfactant solutions typically formulated between pH 3.8 and 4.5 to preserve silicone integrity while eliminating residue and biofilm. These cleansers serve the commercial purpose of extending cup lifespan and reducing infection risk through compatible chemical action. Organic formulations command premium positioning as consumers scrutinize INCI lists for sulfates and synthetic preservatives. Online retail channels capture the fastest growth trajectory, while specialty stores sustain higher margin pools through personalized education and bundling with cup purchases.
FDA oversight of cosmetic cleansing claims and EPA guidance on antimicrobial ingredient safety shape permissible marketing and formulation pathways in the United States. The EU REACH framework and ECHA restrictions on certain preservatives constrain European formulation choices, pushing brands toward disclosed, minimal ingredient decks. Stakeholders must monitor evolving state-level chemical disclosure laws and certification standards from bodies such as USDA Organic and COSMOS to anticipate compliance costs and premium positioning thresholds.
Market Dynamics
Plant-derived surfactant chemistry is forcing wholesale reformulation across menstrual cup foam wash production, as manufacturers abandon petroleum-based ethoxylates to meet ECHA restrictions and consumer ingredient scrutiny.
Growth Catalysts
- EU REACH Phase-Down of Synthetic Preservatives:ECHA restrictions on MIT/CMIT and formaldehyde releasers push brands toward disclosed, minimal ingredient decks that command premium shelf positioning.
- Silicone Integrity Science:pH-balanced formulations between 3.8 and 4.5 extend cup lifespan, creating recurring cleanser demand tied to durable goods replacement cycles.
- Millennial Eco-Consciousness:Zero-waste lifestyle adoption concentrates volume in Germany and Scandinavian markets where certified organic personal care commands household budget priority.
Market Restraints
- Coconut-Derived Surfactant Price Volatility:Lauryl glucoside and decyl glucoside inputs fluctuate with Philippine and Indonesian agricultural yields, compressing margin on organic SKUs.
- Single-Source Concentration in India:Sirona Hygiene dominates pharmacy distribution, creating channel dependency risk for competing brands seeking equivalent retail penetration.
- Antimicrobial Claim Restrictions:EPA guidance on benzalkonium chloride and triclosan eliminates efficacy marketing pathways, forcing reliance on mechanical cleaning narratives.
Strategic Opportunities
- Subscription-First Digital Channels:Direct-to-consumer bundling with cup purchases captures recurring revenue and reduces customer acquisition cost versus retail shelf competition.
- USDA Organic Certification Gap:Few current formulations meet full organic standards, creating white space for first-mover brands to establish premium tier dominance.
- Convergence of Cup and Cleanser Manufacturing:Backward integration into in-house foam wash production enables margin capture and supply security for cup specialists.
Industry Challenges
- COSMOS Certification Timeline Compression:European brands face 12-18 month approval cycles for organic claims, delaying product launches against faster conventional competitors.
- Formulation Chemist Scarcity:Specialized expertise in silicone-compatible, pH-stable surfactant systems commands premium salaries, constraining R&D bandwidth at mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menstrual Cup Foam Wash Market |
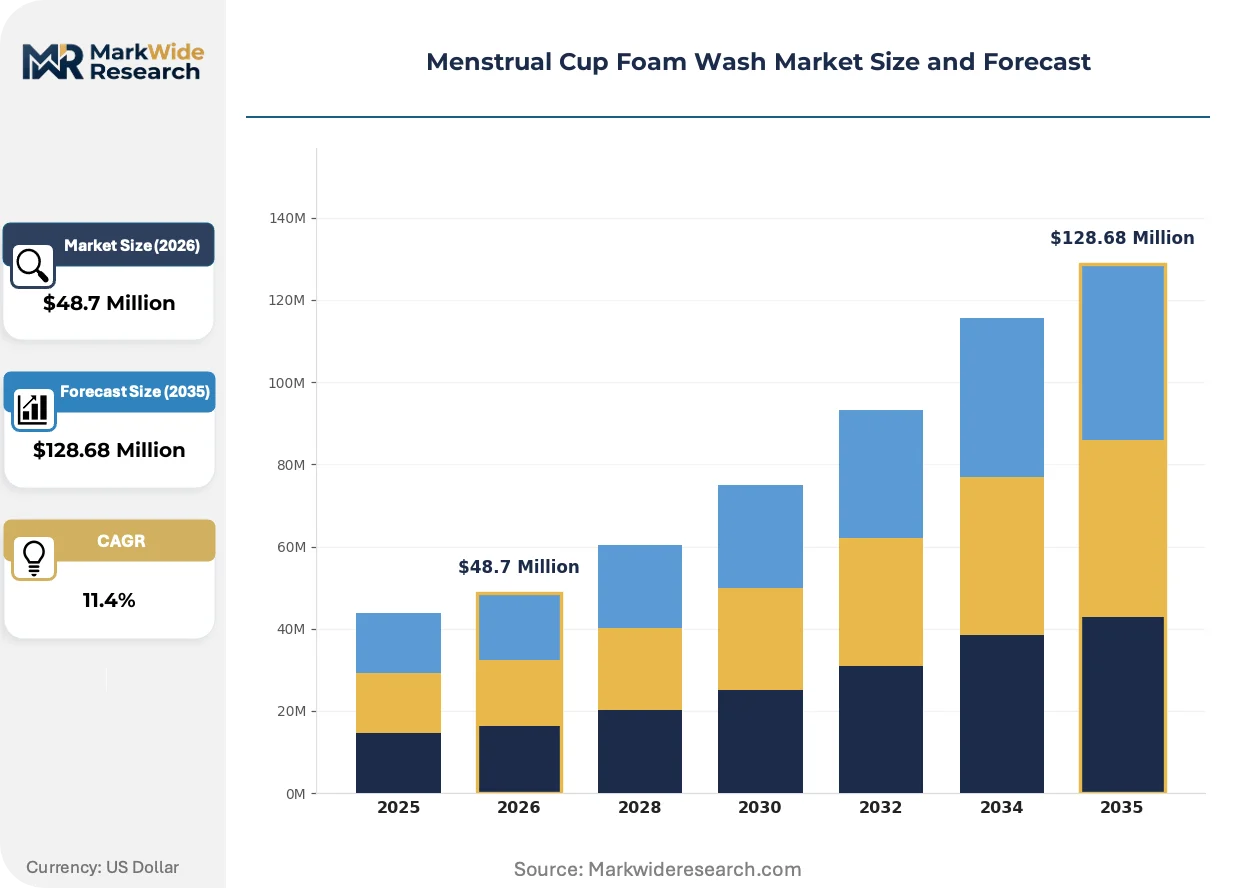
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Antibacterial, Scented, Unscented Packaging Type: Bottle, Refill Pack, Travel Size, Bulk Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Consumer Type: First-time Users, Regular Users, Eco-conscious Buyers, Gift Seekers |
| Companies Covered | Lunette, Diva International Inc., Saalt LLC, The Flex Company, Sirona Hygiene Pvt. Ltd., Procter & Gamble, Kimberly-Clark Corporation, Mooncup Ltd., INTIMINA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menstrual Cup Foam Wash Market Shifts & Advancements
Formulation architecture is migrating from synthetic preservative systems toward bio-based stabilization, while distribution models compress traditional retail margins through direct channel expansion.
Non-ionic surfactant chemistry is migrating from petroleum-derived ethoxylates toward plant-based alkyl polyglucosides. German and French formulators lead adoption, driven by ECHA hazard classification updates and retailer blacklisting of ethoxylated alcohols. This migration is compressing acceptable ingredient deck length from 15-20 INCI entries to 8-12 disclosed components.
EU F-Gas Regulation and REACH Annex XIV restrictions are eliminating per- and polyfluoroalkyl substances from associated personal care packaging. Manufacturers now specify fluorine-free barrier coatings for foam wash bottles, with German converters investing in alternative oxygen-scavenging technologies. Organic-certified SKUs face the steepest compliance cost escalation.
Ingredient transparency preferences are shifting purchasing toward QR-code-linked supply chain disclosure. German and Austrian consumers scan packaging to verify coconut sourcing and fair-trade certification, bypassing traditional brand loyalty. Specialty stores respond with in-store education terminals, while pure-play e-commerce captures volume through subscription bundling with menstrual cup purchases.
Menstrual Cup Foam Wash Market Segmentation
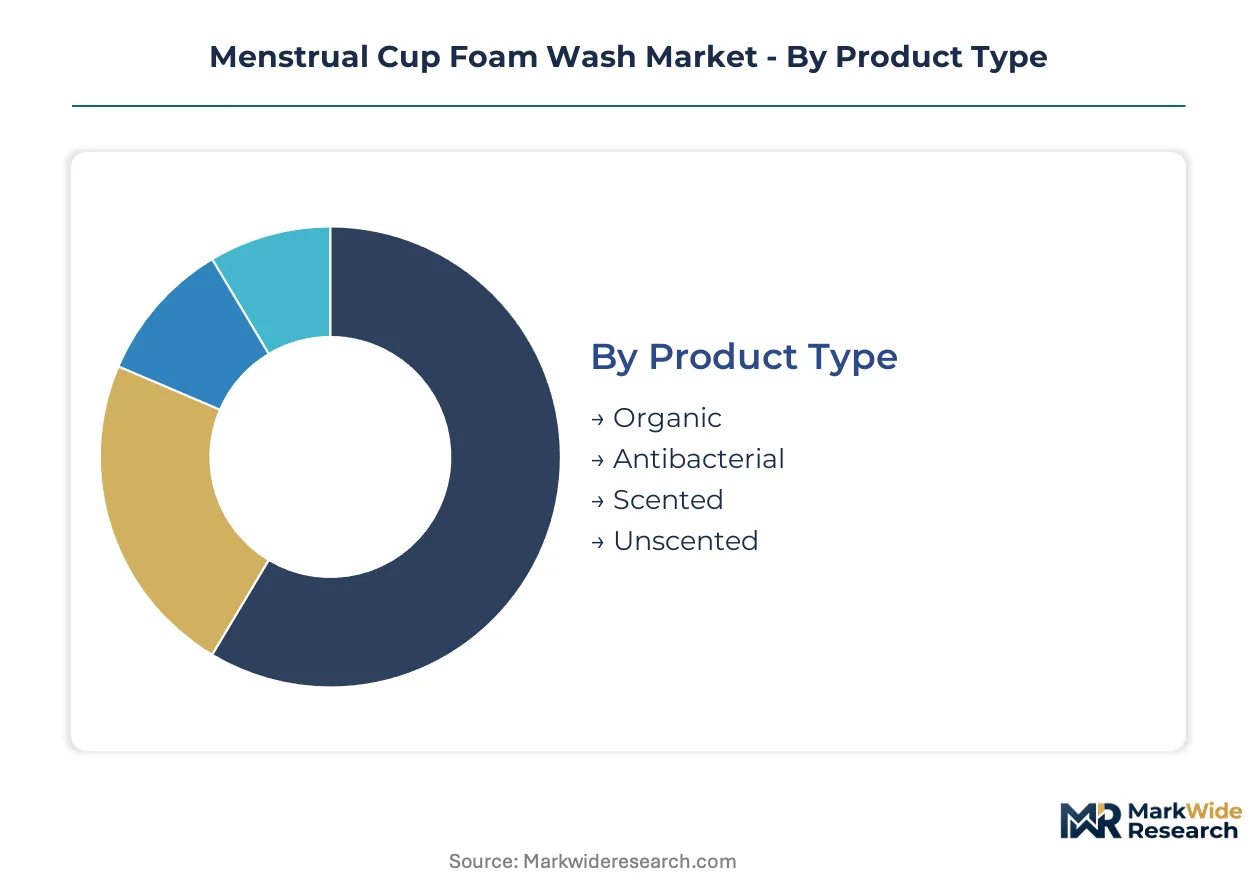
Segmentation in menstrual cup foam wash reflects divergent consumer priorities across ingredient transparency, purchase occasion, and channel convenience. Manufacturers calibrate formulation complexity and packaging formats against distinct usage patterns and loyalty potential.
Product Type:
After-sales service intensity varies sharply across formulation tiers, with organic SKUs demanding supply chain traceability support and unscented variants requiring ingredient education to justify premium positioning.
- Organic:Formulations certified under USDA Organic or COSMOS standards exclude synthetic preservatives and petroleum-derived surfactants. German consumers concentrate demand here, driven by ECHA hazard classifications and retailer blacklisting of ethoxylated alcohols.
- Antibacterial:Previously marketed with benzalkonium chloride or triclosan, these formulations now rely on mechanical cleaning claims after EPA guidance eliminated antimicrobial efficacy pathways. Regulatory compression has shifted volume toward pH-balanced alternatives.
- Scented:Botanical fragrance systems using essential oil blends target users prioritizing sensory experience over ingredient minimalism.
- Unscented:Concentrated, fragrance-free SKUs serve ingredient-sensitive users and silicone compatibility purists, with Saalt LLC establishing positioning leadership.
By volume, unscented formulations lead due to broad compatibility appeal. By growth pace, organic certification is climbing the fastest as disclosure requirements tighten.
Packaging Type:
Cost tier stratification drives format selection, with premium bottle designs commanding shelf differentiation while refill packs capture recurring revenue at lower per-unit margins.
- Bottle:Standard dispenser formats with fluorine-free barrier coatings comply with EU F-Gas Regulation and REACH Annex XIV restrictions on PFAS-associated packaging. German converters lead alternative oxygen-scavenging technology adoption.
- Refill Pack:Concentrated or dilutable formulations reduce per-use packaging cost and support subscription bundling models through direct channels.
- Travel Size:TSA-compliant volumes under 100ml target mobile users and trial conversion, with airport retail and specialty store placement.
- Bulk:Institutional and co-op purchasing formats serve zero-waste retailers and menstrual cup manufacturers pursuing backward integration into in-house cleanser production.
By volume, bottles dominate current shipment mix. By growth pace, refill packs are gaining share fastest through subscription-first digital channels.
Distribution Channel:
Application context shapes channel strategy, with online retail capturing convenience-driven replenishment while specialty stores sustain education-intensive first-time purchases.
- Online Retail:Direct-to-consumer platforms enable QR-code-linked supply chain disclosure and subscription bundling with cup purchases. German and Austrian consumers scan packaging to verify coconut sourcing and fair-trade certification.
- Pharmacies:Indian pharmacy networks concentrate volume through Sirona Hygiene's specialized distribution, creating channel dependency risk for competing brands.
- Supermarkets:Mass retail placement requires formulation standardization and price compression, favoring conventional over certified organic SKUs.
- Specialty Stores:In-store education terminals and personalized bundling with cup purchases sustain higher margin pools through expertise differentiation.
By volume, specialty stores anchor premium tier sales. By growth pace, online retail shows the steepest expansion trajectory through recurring revenue models.
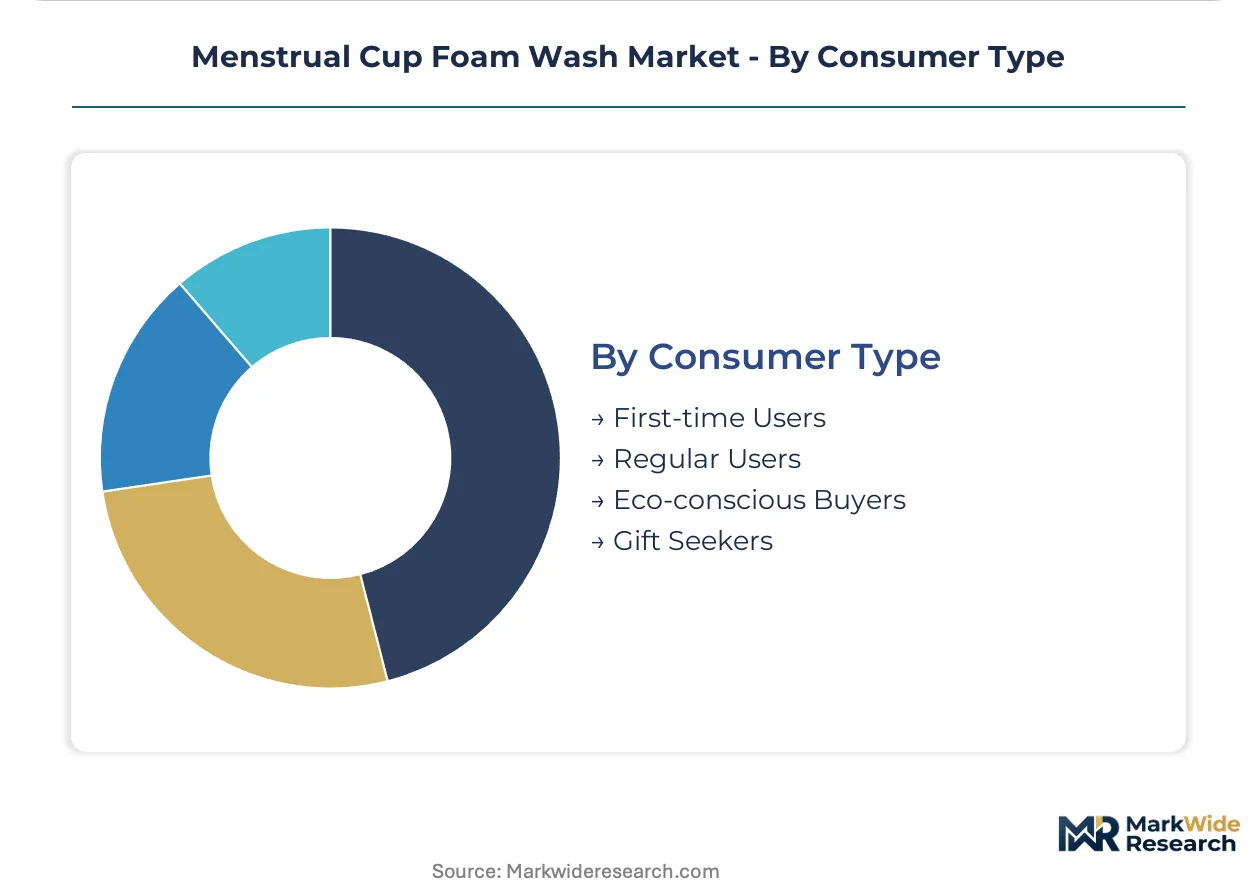
Consumer Type:
Customer maturity and purchase motivation determine messaging architecture, with eco-conscious buyers demanding certification transparency and gift seekers prioritizing aesthetic packaging over technical specification.
- First-time Users:Education-intensive segment requiring pH science explanation and silicone compatibility assurance to establish cleansing routines alongside cup adoption.
- Regular Users:Habituated replenishment purchasers with established brand loyalty or subscription commitments, driving predictable revenue baselines.
- Eco-conscious Buyers:Zero-waste lifestyle adopters concentrate in Germany and Scandinavian markets, where certified organic personal care commands household budget priority and QR-code verification behavior is most prevalent.
- Gift Seekers:Occasional purchasers responding to bundled cup-and-cleanser sets, with seasonal concentration and lower repeat conversion rates.
By volume, regular users sustain baseline demand. By growth pace, eco-conscious buyers are expanding most quickly as millennial zero-waste adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eco-conscious millennials concentrate demand in Germany, where certified organic personal care commands household budget priority. Indian pharmacy networks anchor volume through specialized distribution channels. North American consumers drive subscription-first digital adoption.
Germany
Zero-waste lifestyle adoption concentrates millennial demand for COSMOS-certified formulations. ECHA restrictions on MIT/CMIT and formaldehyde releasers push brands toward disclosed, minimal ingredient decks. Berlin and Hamburg host specialty retailers deploying in-store education terminals for QR-code-linked supply chain verification.
United States
Ingredient-sensitive users drive unscented SKU preference through direct-to-consumer channels. FDA oversight of cosmetic cleansing claims and EPA guidance on antimicrobial ingredient safety constrain permissible marketing pathways. California and New York metro areas anchor subscription bundling models with menstrual cup purchases.
India
First-time cup adopters create education-intensive demand for pH-balanced cleansers. CDSCO and FSSAI frameworks govern personal care product safety standards. Mumbai and Delhi-NCR concentrate pharmacy distribution networks where specialized retail penetration dominates volume capture.
United Kingdom
Organic formulation preference aligns with retailer blacklisting of ethoxylated alcohols. REACH compliance requirements drive reformulation toward plant-derived surfactant systems. London and Manchester host zero-waste retailers bundling cleansers with cup purchases through personalized education.
France
Botanical fragrance systems attract consumers prioritizing sensory experience alongside silicone compatibility. ANSM and CNIL oversight intersect with EU REACH frameworks for cosmetic safety and data transparency. Paris anchors demand for premium-tier certified organic SKUs with shortened INCI disclosure.
Menstrual Cup Foam Wash Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans multinational hygiene conglomerates, dedicated menstrual wellness brands, and regional pharmacy distributors. Three archetypes dominate: cup-specialists with backward integration capability, mass-market hygiene conglomerates leveraging retail shelf access, and regional distributors commanding localized pharmacy networks. Competitive moves concentrate on subscription-first digital channel construction and COSMOS certification acquisition for premium tier establishment.
Within the cup-specialist tier, Diva International Inc., Saalt LLC, and Sirona Hygiene Pvt. Ltd. occupy distinct positioning vectors. Diva International Inc. represents North American manufacturing-anchored supply capability. Saalt LLC exemplifies concentrated unscented and organic SKU specialization for ingredient-sensitive segments. Sirona Hygiene Pvt. Ltd. anchors Indian pharmacy distribution concentration with digital channel expansion. These three entities illustrate the competitive spectrum from geographic manufacturing control through formulation differentiation to channel dominance.
| Leading Market Players |
|---|
| Lunette |
| Diva International Inc. |
| Saalt LLC |
| The Flex Company |
| Sirona Hygiene Pvt. Ltd. |
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Mooncup Ltd. |
| INTIMINA |
| Others |
Supply & Pricing Matrix
Philippine and Indonesian coconut processing clusters anchor surfactant feedstock capacity, with lauryl glucoside price fluctuations transmitting directly to organic SKU margins and compressing pricing power for brands lacking long-term offtake agreements.
Pricing Analysis
Cost-plus contracts indexed to coconut oil futures dominate raw material procurement, with Philippine agricultural yields driving quarterly adjustments. Three-tier pricing structure across premium, standard, and economy levels separates COSMOS-certified organic formulations from conventional pH-balanced alternatives and private-label economy tiers. Pricing pressure stems from coconut-derived surfactant volatility, which is squeezing margins on certified SKUs. First-time users exhibit highest price sensitivity, while eco-conscious German buyers demonstrate lowest elasticity due to certification-driven loyalty.
Supply Chain Analysis
Upstream feedstock flows from Philippine and Indonesian coconut plantations, with German and French formulators converting alkyl polyglucosides into finished cleansers. Raw material dependencies center on lauryl glucoside, decyl glucoside, and fluorine-free barrier coatings for compliant packaging. Single-source concentration in Indian pharmacy distribution creates channel vulnerability for competing brands. Distribution runs through direct-to-consumer subscription platforms, specialty retail education terminals, and pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Phase-Down of synthetic preservatives constitutes a regulatory inflection, forcing wholesale reformulation and creating first-mover advantage windows for brands achieving COSMOS certification ahead of compliance deadlines.
For Market Incumbents: Build certification moats through accelerated COSMOS approval investment to outpace 12-18 month timeline compression. Backward integration into captive surfactant production insulates margin from Philippine yield volatility. Channel control through pharmacy network expansion counters Sirona Hygiene's Indian dominance. For New Entrants and Emerging Players: US pharmacy and mass retail channels show geographic underpenetration relative to digital-native competitors, offering white-space entry through education-intensive first-time user targeting. USDA Organic certification gap enables premium tier establishment with minimal incumbent saturation. Direct-to-consumer bundling with menstrual cup manufacturers provides lowest customer acquisition cost pathway. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue personal care play because subscription-first digital channels capture habituated replenishment with predictable lifetime value. Acquisition targets should display COSMOS certification progress, captive formulation capability, or controlled pharmacy distribution. Monitor ECHA hazard classification updates for reformulation cost inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| COSMOS Certification Acquisition | Establishes premium tier positioning ahead of REACH compliance deadlines in German retail. |
| Backward Integration into Surfactant Production | Captures margin compression from coconut oil volatility and secures supply continuity. |
| Subscription-First Digital Channel Launch | Reduces customer acquisition cost through menstrual cup bundling and recurring revenue capture. |
| Pharmacy Network Expansion | Penetrates education-intensive first-time user segments in underrepresented geographies. |
| Fluorine-Free Packaging Transition | Ensures EU F-Gas Regulation compliance and accesses German zero-waste retailer placement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA hazard classifications, FDA cosmetic claim filings, and customs trade data for coconut-derived surfactant flows. Primary interviews engaged formulation chemists at silicone-compatible cleanser manufacturers, procurement leads at German personal care retailers, and regulatory affairs specialists navigating REACH Annex XIV restrictions. Secondary validation drew from EU F-Gas Regulation implementation reports, USDA Organic certification databases, and Indian CDSCO personal care safety standards. Bottom-up volume modeling triangulated against top-down category spend estimates.
Forecast inputs incorporate formulation migration timelines from synthetic to plant-derived surfactants, certification adoption curves across German and Scandinavian markets, and channel shift velocity from specialty retail to subscription platforms. Segmentation dimensions span formulation type, packaging format, distribution channel, and consumer maturity stage. CAGRs derive from installed base of menstrual cup users, replacement cycle frequency, and cleanser attach rates.
Practitioners should monitor ECHA preservative restriction updates, Philippine coconut harvest forecasts, and state-level chemical disclosure law progressions for early signals requiring forecast revision. Cross-checking against customs import data for lauryl glucoside volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Women Health Devices Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women Health Care Market
Women's Health
Women's Health App Market
Women's Health
US Womens Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
Women's Health Market
Women's Health
Maternal Health Market
Women's Health
Menopause Market
Women's Health
Women's Digital Health Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
North America Womens Health Diagnostics Market