
 Dysfunctional Uterine Bleeding Market | 2026-2036
Dysfunctional Uterine Bleeding Market Size, Share, and Industry Trends Forecast 2026-2036
Dysfunctional Uterine Bleeding Market Analysis
Extended-cycle hormonal formulations is bifurcating the Dysfunctional Uterine Bleeding landscape into premium and standard tiers. AbbVie Inc. leverages its endometriosis-hormonal crossover pipeline to sustain clinical credibility. Bayer AG anchors European distribution through its long-standing gynecology franchise. Pfizer Inc. differentiates via manufacturing scale across oral and injectable delivery formats.
Dysfunctional uterine bleeding denotes abnormal menstrual bleeding unrelated to structural uterine lesions, typically managed through pharmacologic suppression of endometrial proliferation or surgical reduction of bleeding surface area. The condition's primary commercial purpose centers on reducing transfusion dependency, anemia-related hospitalization, and hysterectomy rates in premenopausal patients. Hormonal therapies occupy the largest revenue pool given chronic administration cycles, while device treatments represent the fastest-expanding margin segment as outpatient ablation protocols displace inpatient surgery. Ambulatory Surgical Centers are capturing volume share from hospitals as reimbursement shifts toward same-day procedural settings.
FDA oversight of levonorgestrel-releasing intrauterine systems and EMA pharmacovigilance requirements for thromboembolic risk labeling constrain product development timelines and marketing claims. The EU MDR reclassification of surgical ablation devices has extended conformity assessment periods for manufacturers seeking CE marking renewal. Stakeholders must monitor evolving CMS and national payer coverage determinations for non-hysterectomy alternatives to anticipate volume shifts between pharmaceutical and interventional modalities.
Market Dynamics
Outpatient ablation protocols are compressing hospital admission windows for dysfunctional uterine bleeding interventions, forcing pharmaceutical and device manufacturers to restructure their go-to-market assumptions around ambulatory reimbursement pathways.
Growth Catalysts
- CMS coverage expansion:Medicare reimbursement for same-day hysteroscopic procedures in the United States accelerates facility-level investment in office-based surgical suites.
- Extended-cycle oral contraceptives:Reduced bleeding frequency protocols improve patient compliance metrics and extend prescription renewal cycles for chronic hormonal management.
- Japan:PMDA streamlined review pathways for levonorgestrel-releasing systems shorten time-to-market for next-generation intrauterine devices.
Market Restraints
- EU MDR conformity costs:Surgical ablation device reclassification under the Medical Device Regulation extends CE marking renewal timelines and compliance expenditures for European manufacturers.
- Thromboembolic labeling:EMA pharmacovigilance requirements for combined hormonal therapies constrain marketing claims and narrow prescriber confidence in estrogen-containing formulations.
- Specialized hysteroscopic training:Gynecologist proficiency gaps in thermal balloon and radiofrequency ablation techniques limit procedural adoption outside academic medical centers.
Strategic Opportunities
- Germany:Regional sickness fund contracting for non-hysterectomy alternatives creates procurement volume for outpatient device manufacturers establishing ambulatory surgical center partnerships.
- Digital therapeutics integration:Bleeding diary applications paired with hormonal adherence tracking enable pharmaceutical differentiation through outcomes data capture.
- Biodegradable implant delivery:Convergence of polymer science and sustained-release formulation technology opens subcutaneous depot alternatives to daily oral regimens.
Industry Challenges
- ISO 13485 quality system audits:Device manufacturers face extended certification timelines as notified bodies prioritize EU MDR transition workloads over routine surveillance.
- Legacy EHR interoperability:Ablation procedure documentation standards vary across hospital systems, complicating outcomes registry participation and payer contract negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysfunctional Uterine Bleeding Market |
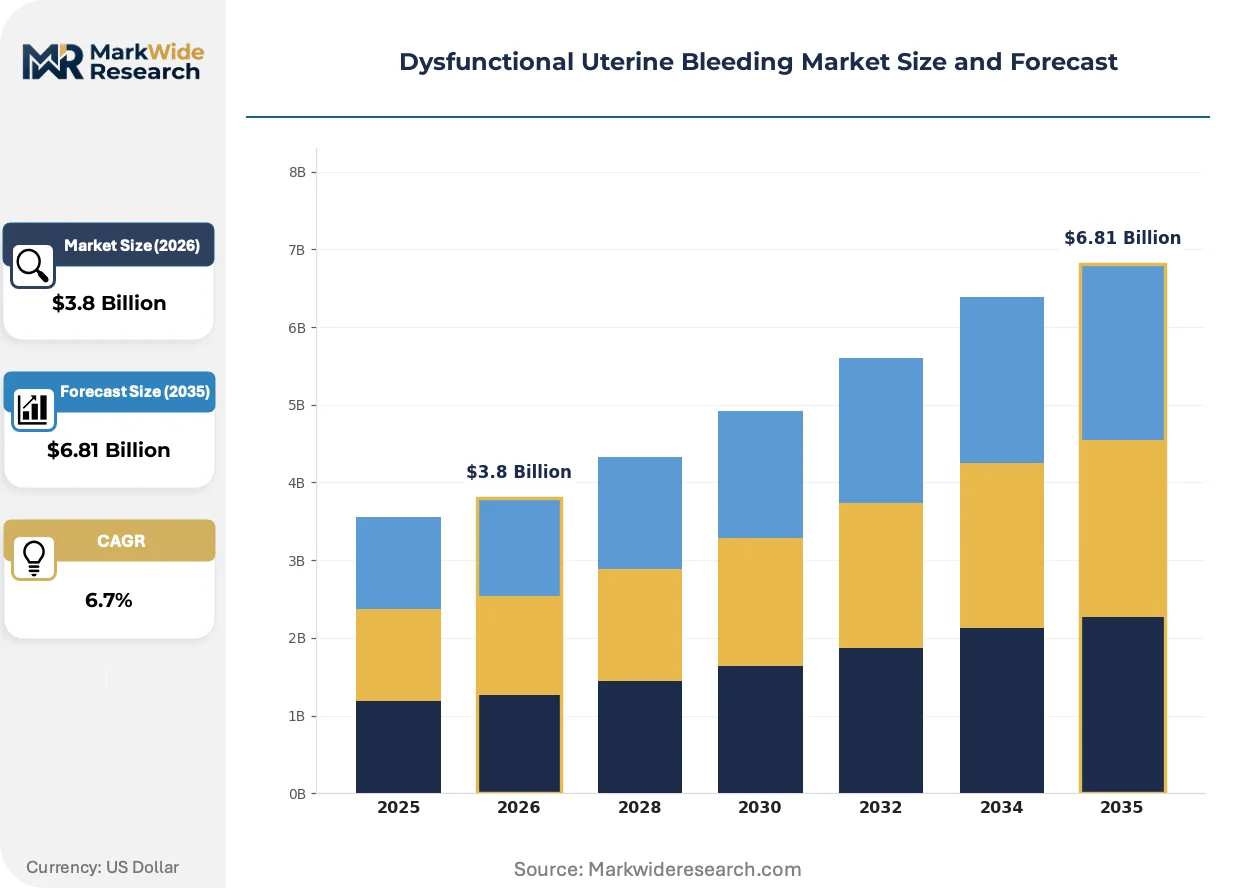
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Non-Hormonal Medications, Surgical Interventions, Device Treatments End User: Clinics, Hospitals, Ambulatory Surgical Centers, Homecare Settings Therapy Area: Gynecology, Obstetrics, Endocrinology, Reproductive Health Application: Symptom Management, Diagnostic Procedures, Surgery, Patient Monitoring |
| Companies Covered | Ferring Pharmaceuticals, Merck & Co., Inc., AbbVie Inc., Amgen Inc., Hologic, Inc., Bayer AG, Johnson & Johnson, Zydus Cadila, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysfunctional Uterine Bleeding Market Emerging Trajectories
Radiofrequency endometrial ablation systems are compressing the boundary between office-based and hospital-based intervention tiers, creating new competitive terrain for device portfolios previously segmented by care setting.
Cryoablation platforms with integrated suction-aspiration functionality reduce periprocedural pain scores and enable conscious sedation protocols. Ambulatory surgical centers in Texas and Florida are adopting these systems faster than hospital outpatient departments, bifurcating the market into premium thermal technologies and standard electrosurgical alternatives.
EMA pharmacovigilance guidance on progestin-only contraceptives tightens post-market surveillance requirements for thromboembolic event reporting. Manufacturers must expand risk management systems and prescriber education programs. Combined oral contraceptive portfolios face the steepest compliance burden, driving reformulation toward lower-estrogen or progestin-only alternatives.
Patient-initiated switching between hormonal and interventional modalities compresses traditional therapeutic pathway loyalty. Gynecology practices in California and New York are unbundling consultation from procedure scheduling, enabling direct-to-specialist referral for ablation evaluation. This channel fragmentation pressures primary care gatekeeper models that historically controlled hormonal therapy initiation.
Dysfunctional Uterine Bleeding Market Segmentation
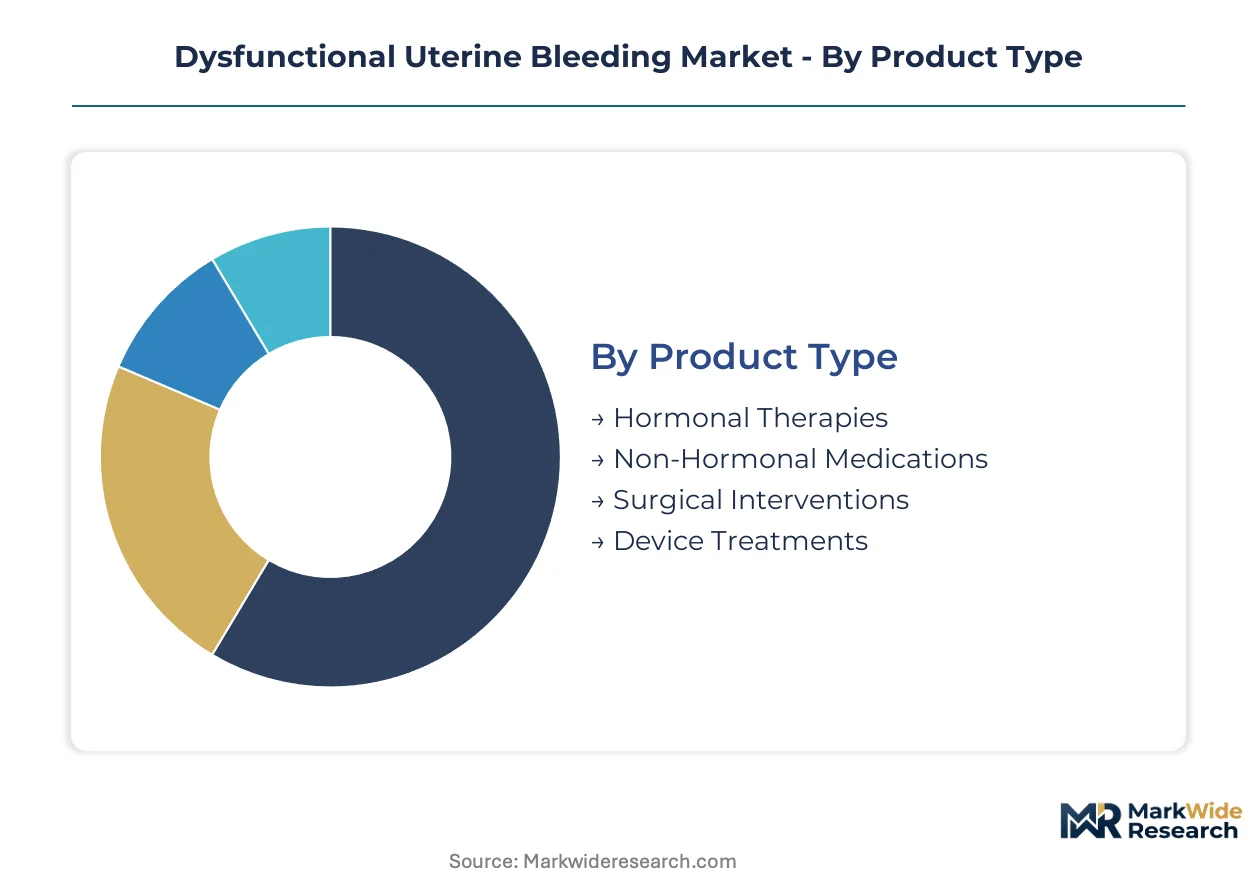
Dysfunctional uterine bleeding treatment pathways fragment across pharmacologic suppression and mechanical intervention modalities. Segmentation reveals how reimbursement architecture and care setting economics reshape competitive boundaries between chronic medication and procedural alternatives.
Product Type:
Domestic manufacturing concentration varies sharply across this category, with hormonal formulations produced largely in-country while surgical devices rely on cross-border supply chains.
- Hormonal Therapies:Levonorgestrel-releasing intrauterine systems and extended-cycle oral contraceptives dominate prescription volumes through chronic administration protocols. United States demand concentrates in managed care formularies where prior authorization requirements favor established hormonal brands over novel entrants.
- Device Treatments:Radiofrequency and thermal balloon ablation systems enable same-day procedural resolution. Ambulatory surgical centers in Texas and Florida capture disproportionate volume as CMS reimbursement shifts toward office-based intervention tiers.
- Non-Hormonal Medications:Tranexamic acid and NSAID protocols serve contraindicated patients or bridge therapy gaps.
- Surgical Interventions:Hysteroscopic resection and dilation-and-curettage retain inpatient coding for complex cases.
Hormonal therapies command the established base. The steepest expansion runs through device treatments.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean ambulatory models.
- Ambulatory Surgical Centers:Standalone facilities in California and New York unbundle consultation from procedure scheduling, enabling direct-to-specialist referral pathways that bypass primary care gatekeepers. Reimbursement differentials between ASC and hospital outpatient departments accelerate capital deployment into office-based surgical suites.
- Hospitals:Academic medical centers maintain complex case volume for hysteroscopic resection and complication management. Gynecology departments face margin compression as same-day protocols displace overnight admissions.
- Clinics:Community-based practices initiate hormonal therapy and coordinate referral handoffs.
- Homecare Settings:Self-administered hormonal regimens and remote monitoring applications expand chronic management reach.
Hospitals retain the complex case base. The steepest volume shift runs through ambulatory surgical centers.
Therapy Area:
Application maturity varies from well-established gynecology protocols to emerging endocrinology crossovers.
- Gynecology:Hysteroscopic and ablative techniques originated within this specialty and retain procedural standard-of-care status. Fellowship training programs in academic medical centers concentrate proficiency in thermal and radiofrequency modalities.
- Reproductive Health:Fertility-preserving hormonal suppression protocols serve patients delaying definitive surgical intervention. Patient-initiated switching between modalities compresses traditional therapeutic loyalty within this segment.
- Obstetrics:Postpartum hemorrhage protocols and peripartum bleeding management extend into dysfunctional uterine bleeding adjacencies.
- Endocrinology:Polycystic ovary syndrome and metabolic syndrome comorbidities drive cross-specialty referral patterns.
Gynecology commands the procedural base. The steepest interdisciplinary expansion runs through reproductive health.
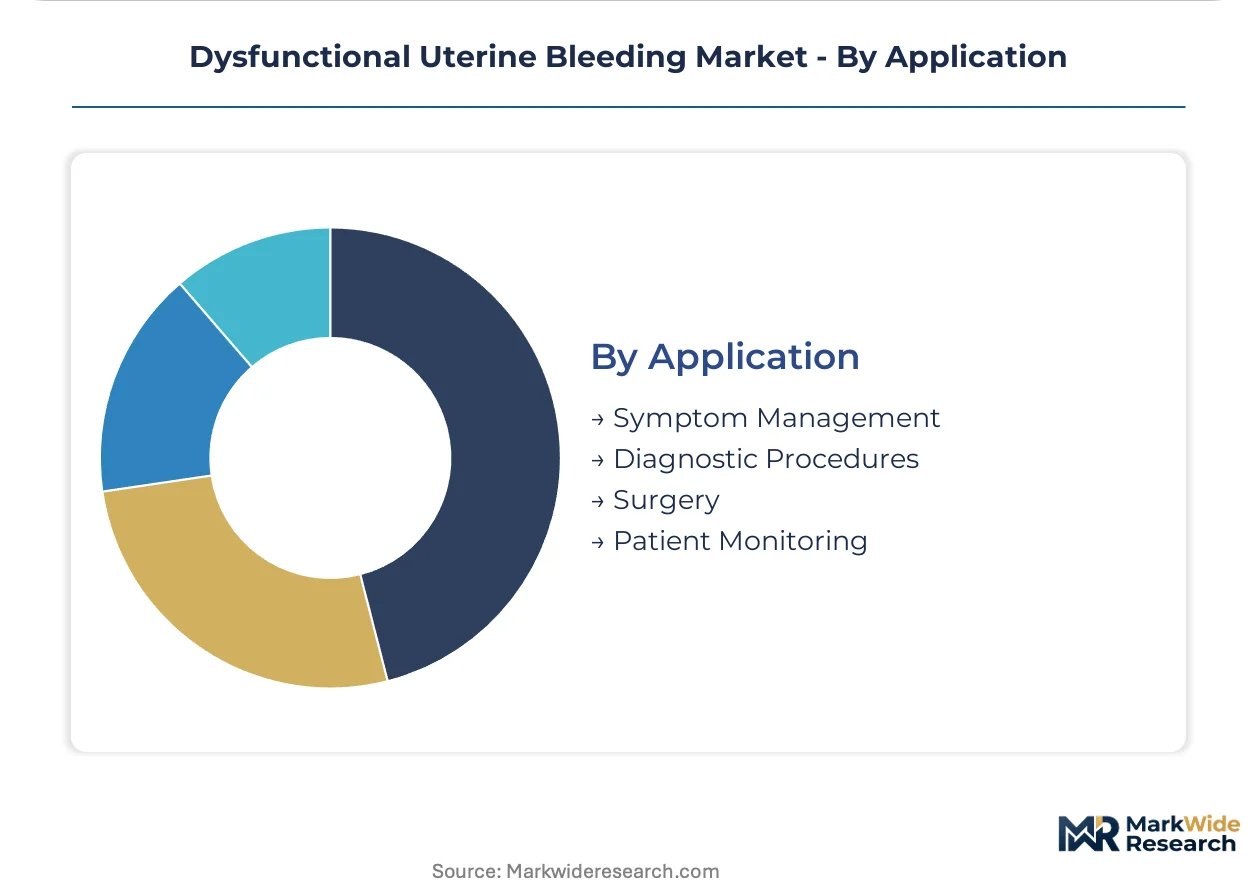
Application:
Volume concentration sits with chronic symptom management while margin expansion concentrates in procedural intervention.
- Symptom Management:Chronic hormonal suppression and hemostatic medication reduce transfusion dependency and anemia-related hospitalization. Prescription renewal cycles extend commercial value capture across multi-year patient relationships.
- Surgery:Definitive ablation and hysteroscopic techniques eliminate bleeding surface area through outpatient protocols. Facility fee structures and device procurement contracts determine profitability across hospital and ambulatory settings.
- Diagnostic Procedures:Hysteroscopic evaluation and endometrial sampling rule out structural lesions prior to therapy initiation.
- Patient Monitoring:Bleeding diary applications and adherence tracking enable outcomes data capture for value-based contracting.
Symptom management commands the chronic revenue base. The steepest margin expansion runs through surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany and the United States while pharmaceutical formulation capacity spreads across Switzerland, Ireland, and India. Regulatory divergence between FDA and EMA pathways shapes geographic deployment strategies for hormonal and interventional portfolios alike.
United States
CMS reimbursement expansion for same-day hysteroscopic procedures drives ambulatory surgical center investment in Texas and Florida. FDA oversight of levonorgestrel-releasing intrauterine systems tightens post-market surveillance requirements for thromboembolic risk. The Dallas-Fort Worth metroplex anchors radiofrequency ablation device distribution networks serving the Southwest corridor.
Germany
Regional sickness fund contracting for non-hysterectomy alternatives concentrates procurement volume in Bavaria and North Rhine-Westphalia. EU MDR reclassification of surgical ablation devices extends CE marking renewal timelines for manufacturers seeking market access. The Munich-Stuttgart corridor hosts precision electrosurgical equipment fabrication serving European hospital networks.
Japan
PMDA streamlined review pathways for levonorgestrel-releasing systems accelerate time-to-market for next-generation intrauterine devices. METI industrial policy supports domestic production of minimally invasive surgical platforms. The Osaka-Kobe manufacturing belt concentrates thermal balloon ablation device assembly for Asia-Pacific distribution.
United Kingdom
NICE technology appraisals for endometrial ablation procedures influence commissioning decisions across NHS England integrated care systems. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for device manufacturers. The Cambridge-London corridor attracts digital therapeutics development for bleeding diary and adherence tracking applications.
India
CDSCO accelerated approval pathways for hormonal formulations expand access to extended-cycle oral contraceptives in tier-1 urban markets. PLI scheme incentives for medical device manufacturing attract contract fabrication investment. The Hyderabad-Bengaluru pharma cluster supplies active pharmaceutical ingredients for global hormonal therapy supply chains.
Dysfunctional Uterine Bleeding Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dysfunctional uterine bleeding market. Swiss and German pharmaceutical conglomerates anchor premium hormonal therapy portfolios through endocrinology franchise depth. American device specialists concentrate interventional innovation in radiofrequency and cryoablation platforms. Competitive dynamics center on M&A activity consolidating gynecology-focused assets and strategic partnerships bridging pharmaceutical and device delivery ecosystems.
Within the integrated pharmaceutical tier, Bayer AG and Pfizer Inc. represent archetypes of manufacturing scale across oral and injectable hormonal formats. AbbVie Inc. occupies a position exemplifying endometriosis-hormonal crossover pipeline leverage. Among device-focused specialists, Hologic, Inc. anchors the minimally invasive surgical platform segment.
| Leading Market Players |
|---|
| Ferring Pharmaceuticals |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Amgen Inc. |
| Hologic, Inc. |
| Bayer AG |
| Johnson & Johnson |
| Zydus Cadila |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements between ambulatory surgical centers and radiofrequency ablation device manufacturers lock in supply access while stabilizing per-procedure pricing visibility across United States and German procurement networks. These contractual structures insulate high-volume facilities from spot-market volatility in polymer and electrosurgical component costs.
Pricing Analysis
FDA premarket approval requirements dictate the pricing tier structure across hormonal and interventional modalities. Three-tier pricing structure across premium, standard, and economy levels separates branded extended-cycle formulations from generic oral contraceptives and value-positioned thermal balloon systems. Cost compression in standard-tier device categories is intensifying because EU MDR conformity assessment delays are extending manufacturer overhead recovery periods. Community-based clinics exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcomes data over acquisition cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate device manufacturing, though strategic stockpiling of levonorgestrel APIs buffers against Indian pharmaceutical export volatility. Active pharmaceutical ingredient production concentrates in India and China, while precision electrosurgical equipment fabrication centers on Germany and the United States. Raw material dependencies include medical-grade polymers, radiofrequency generators, and sustained-release hormone matrices. Single-source vulnerability in thermal balloon catheter supply creates exposure to logistics chokepoints at Rotterdam and Los Angeles ports. Distribution runs through specialized gynecology device distributors and pharmaceutical wholesale networks serving hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dysfunctional uterine bleeding market functions as a defensive-moat arena where regulatory entrenchment protects established hormonal therapy franchises against rapid generic substitution. FDA and EMA approval pathways create multi-year barriers that sustain incumbent pricing power.
For Market Incumbents: Fortify market position through backward integration into sustained-release polymer manufacturing and expanded CE marking investment for next-generation ablation platforms. Radiofrequency device commoditization from Asian contract manufacturers threatens margin structures in the United States and Germany. Priority levers include captive supply of medical-grade polymers and direct ambulatory surgical center contracting to displace distributor intermediaries. For New Entrants and Emerging Players: PMDA streamlined review pathways offer the fastest certification fast-track for levonorgestrel-releasing system entrants seeking Asia-Pacific market access. White-space concentration sits in biodegradable implant delivery formats and digital therapeutics integration for bleeding diary applications. California and New York ambulatory surgical centers represent the most penetrable geography given unbundled referral pathways. Go-to-market execution should target direct-to-specialist channels that bypass primary care gatekeeper models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extended-cycle hormonal formulation portfolios with managed care formulary placement. Long-term viability across the projection horizon favors manufacturers with dual pharmaceutical-device revenue streams and reimbursement strategy expertise. Acquisition targets should display EU MDR transition completion and CMS coverage determination alignment. The signal to watch is ambulatory surgical center same-day procedure volume acceleration as a predictor of device manufacturer pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Extended-Cycle Formulation | Premarket approval anchors formulary placement with United States managed care networks. |
| CE Marking Pathway for Radiofrequency Platform | EU MDR conformity assessment enables German and French hospital system procurement. |
| Hospital System Partnership for Outpatient Suites | Texas and Florida ASC alliances capture CMS reimbursement shift toward same-day protocols. |
| Software Companion Development for Adherence Tracking | Bleeding diary applications enable pharmaceutical differentiation through outcomes data capture. |
| Reimbursement Strategy for Non-Hysterectomy Alternatives | NICE and CMS coverage determinations dictate volume splits between hormonal and interventional modalities. |
Methodological Framework
Cross-validation between gynecology department purchasing committee interviews and FDA 510(k) filing databases anchors the qualitative findings in documented regulatory pathways. Primary fieldwork encompassed drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across United States, German, and Japanese markets. Secondary validation drew from ClinicalTrials.gov, EMA assessment reports, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast outputs against alternative regulatory timelines and reimbursement scenario assumptions across the projection horizon. Segmentation dimensions modeled include therapy modality, delivery format, care setting tier, patient population severity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to procedure volume and prescription renewal data. Industry-specific inputs encompassed PMDA review duration statistics, EU MDR notified body capacity constraints, and ambulatory surgical center capital expenditure surveys.
The analysis sits within stated boundaries; outcomes outside sustained CMS same-day procedure reimbursement or EMA pharmacovigilance stability would require recalibration. Forecasts reflect assumptions regarding regulatory pathway continuity and ambulatory facility investment trajectories. Revision becomes warranted when EU MDR transition bottlenecks or thromboembolic labeling requirements cross thresholds that materially alter manufacturer compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Maternal Health Market
Women's Health
Women's Digital Health Market
Women's Health
Women's Health Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Menstrual Health Apps Market
Women's Health
US Womens Health Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women Health Software Market
Women's Health
Women's Health App Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Devices Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Menopause Market