
 Women Health Devices Market | 2026-2036
Women Health Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Women Health Devices Market Analysis
Home users is redrawing demand patterns away from traditional clinic-dependent models. Hologic leverages its installed base in diagnostic imaging to defend institutional channels. GE Healthcare Technologies anchors premium ultrasound portfolios across hospital networks. Koninklijke Philips N.V. competes through integrated mother-and-child care ecosystems spanning pregnancy through postpartum.
Women health devices encompass instruments, consumables, and software systems engineered for physiological monitoring, diagnostic screening, and therapeutic intervention specific to female biology, typically operating within precision ranges of 0.1°C for basal temperature tracking or sub-millimeter resolution for breast imaging. Their commercial purpose centers on early detection of gynecological conditions, fertility optimization, and autonomous management of menstrual and postpartum health. Wearable devices and mobile applications are capturing margin pools through recurring subscription revenue and data network effects, while diagnostic imaging remains the value anchor in acute and oncology settings. Telehealth platforms are expanding fastest by collapsing geographic barriers between patients and specialists, though pregnancy test kits retain volume leadership in retail pharmacy channels.
FDA Software as a Medical Device guidance and HIPAA privacy mandates shape product architecture and go-to-market timelines for connected devices in the United States. The EU MDR and GDPR impose parallel conformity and data governance burdens for market access across European member states. Stakeholders must weigh regulatory capital requirements against the pace of AI-enabled diagnostic claims to calibrate R&D portfolios and geographic sequencing.
Market Dynamics
Direct-to-consumer fertility tracking apps are collapsing the traditional clinic gatekeeper model, forcing incumbent diagnostic manufacturers to defend institutional channels through integrated platform strategies.
Growth Catalysts
- Software as a Medical Device pathway:FDA's streamlined clearance framework for connected women's health tools accelerates commercialization timelines for algorithm-driven diagnostics.
- Home-based physiological monitoring:Wearable basal temperature sensors with 0.1°C precision enable autonomous fertility optimization without clinical intermediaries.
- Telehealth platform expansion:Virtual specialist consultations collapse geographic barriers between rural patients and reproductive endocrinologists.
Market Restraints
- Input cost volatility:Specialized MEMS sensors for wearable temperature tracking face supply concentration among Taiwanese foundries.
- Regulatory friction:EU MDR clinical evidence requirements for Class IIa gynecological devices extend conformity assessment timelines by 12-18 months.
- Substitution threat:Smartphone camera-based ovulation prediction algorithms displace dedicated hardware for cost-sensitive consumer segments.
Strategic Opportunities
- Underpenetrated rural India:Community health worker-deployable point-of-care cervical screening devices address diagnostic access gaps outside urban hospital networks.
- AI-ultrasound convergence:Deep learning-enabled fetal anomaly detection algorithms integrated into portable ultrasound systems enable frontline prenatal screening.
- Subscription revenue models:Recurring data analytics fees for longitudinal menstrual health tracking transform one-time device sales into predictable income streams.
Industry Challenges
- Biometric data governance complexity:HIPAA compliance for fertility app data sharing with third-party analytics providers requires specialized legal infrastructure.
- Legacy system integration friction:Hospital EHR connectivity for connected maternal monitoring devices demands HL7 FHIR interface development.
- Clinical validation timelines:Prospective studies for AI-enabled breast imaging algorithms require multi-site recruitment extending regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Health Devices Market |
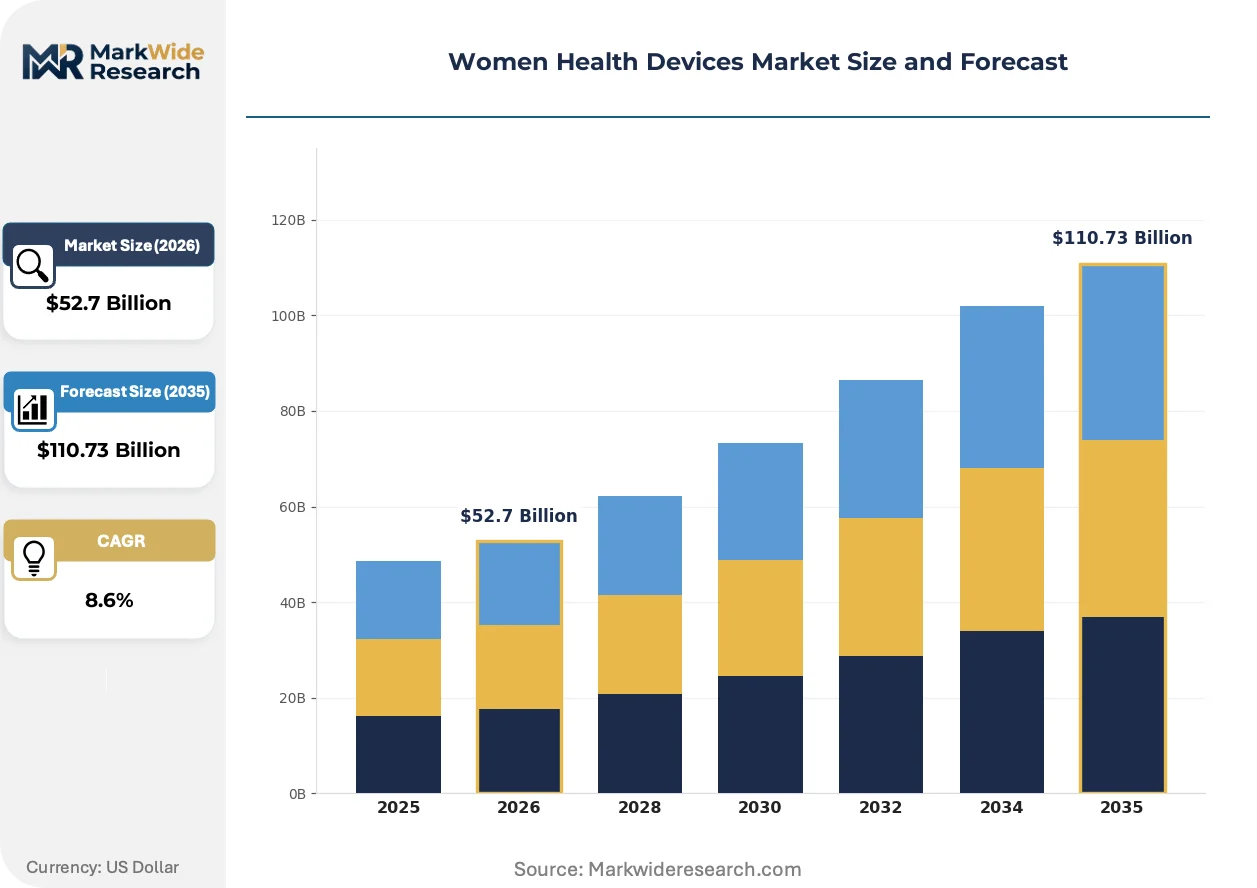
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pregnancy Test Kits, Ovulation Test Kits, Menstrual Cups, Breast Pumps Technology: Wearable Devices, Mobile Applications, Diagnostic Imaging, Telehealth Platforms End User: Hospitals, Home Users, Clinics, Healthcare Providers Application: Fertility Monitoring, Postpartum Care, Menstrual Health, Gynecological Disorders |
| Companies Covered | Hologic, GE Healthcare Technologies, Koninklijke Philips N.V., Boston Scientific Corporation, Samsung Electronics, F. Hoffmann-La Roche, Medtronic, Coloplast A/S, The Cooper Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Health Devices Market Emerging Trajectories
Algorithmic diagnostic capabilities are redrawing competitive boundaries between consumer wellness apps and regulated medical devices, creating new compliance obligations for software-native entrants.
Continuous glucose monitoring technology adapted for menstrual cycle hormonal profiling is bifurcating the fertility tracking landscape. Digitally engaged millennials in the United States and Germany are adopting multi-parameter biosensors at triple the rate of single-modal basal thermometers. This convergence is compressing margins for standalone ovulation predictor kit manufacturers while expanding addressable market boundaries for metabolic health platforms.
EU AI Act risk classification requirements for medical device software are reshaping product architecture decisions for European market entrants. Manufacturers must now embed conformity assessment documentation into algorithm development workflows rather than retrofitting post-validation. High-risk reproductive health AI applications face mandatory human oversight provisions, slowing deployment timelines for fully automated diagnostic interpretations.
Subscription-based fertility coaching bundled with connected hardware is displacing transactional retail pharmacy purchases. Young professionals in urban United States markets prioritize personalized algorithmic insights over standalone test strip accuracy. This behavioral pivot forces traditional diagnostic brands to build direct consumer relationships or cede margin to platform intermediaries.
Women Health Devices Market Segmentation
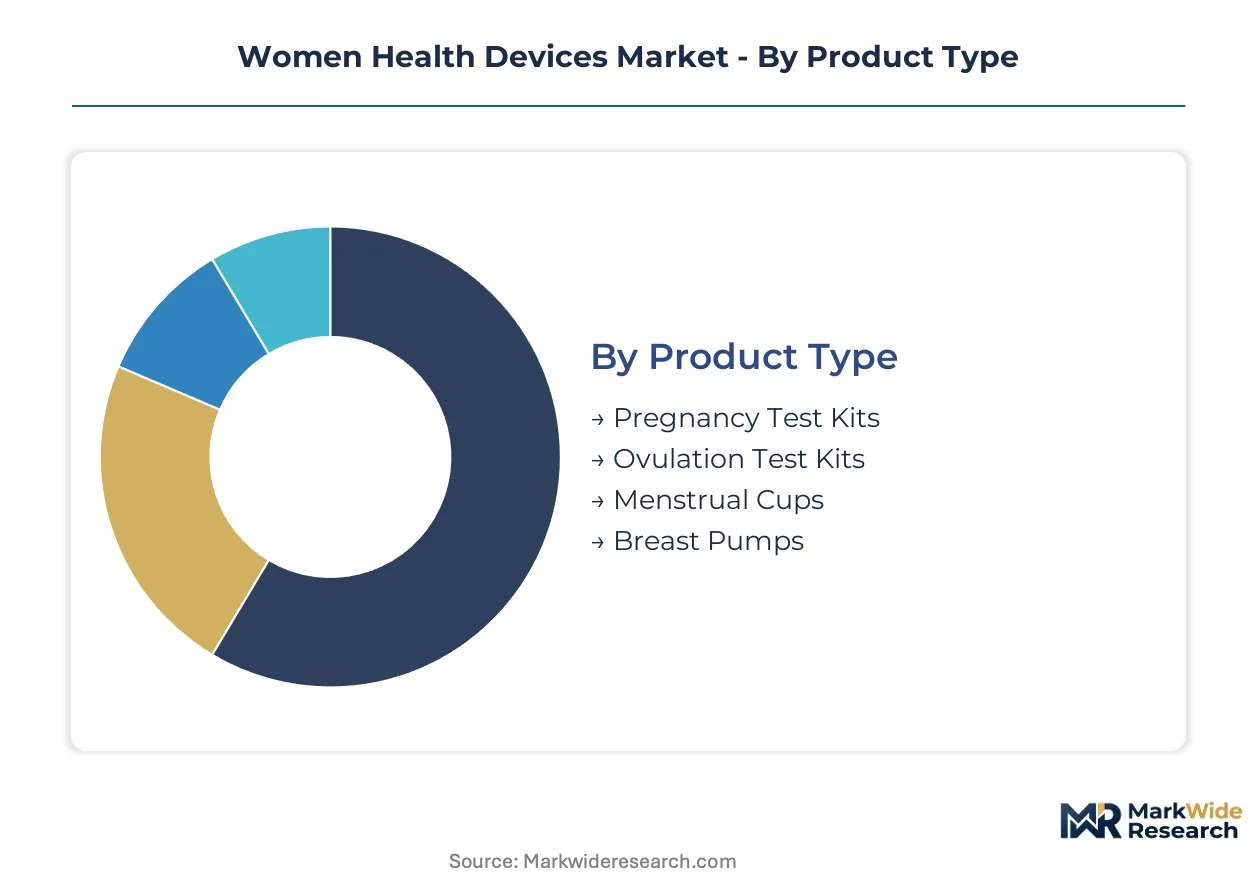
Segmentation in women's health devices reveals how margin pools have shifted from institutional procurement toward recurring consumer subscriptions. Product architecture decisions now hinge on whether devices target acute diagnostic accuracy or longitudinal physiological tracking.
Product Type:
Margin concentration sits with consumables that generate repeat purchases, while durable hardware competes on brand loyalty and ecosystem lock-in.
- Pregnancy Test Kits:Lateral flow immunoassay strips detecting hCG at 25 mIU/mL sensitivity dominate retail pharmacy volume. Home users in the United States drive demand through direct-to-consumer subscription services that bundle test strips with app-based cycle tracking.
- Ovulation Test Kits:LH surge detection strips and digital readers with smiley-face result displays capture fertility-conscious millennials seeking conception timing precision. German consumers exhibit highest per-capita spending on connected ovulation monitors with Bluetooth synchronization.
- Menstrual Cups:Medical-grade silicone collection devices offering 12-hour wear time address sustainability-motivated users reducing disposable product waste.
- Breast Pumps:Hospital-grade electric pumps with closed-system hygiene protocols serve NICU discharge planning and workplace lactation accommodation mandates.
Pregnancy test kits hold installed capacity. Ovulation test kits are rotating up the share rankings.
Technology:
Technology segmentation tracks where regulatory capital converts to pricing power versus commodity hardware margins.
- Wearable Devices:Skin-worn sensors measuring basal temperature, heart rate variability, and bioimpedance for fertility algorithm inputs. United States FDA 510(k) clearances for wrist-worn temperature trackers are accelerating commercialization timelines for algorithm-driven cycle predictions.
- Mobile Applications:Software-only fertility tracking using manual data entry and camera-based ovulation strip analysis. Indian consumers in tier-2 cities adopt these as zero-hardware entry points to fertility awareness.
- Diagnostic Imaging:Ultrasound and mammography systems with AI-assisted lesion detection command premium pricing in oncology screening protocols.
- Telehealth Platforms:Virtual consultation infrastructure connecting patients to reproductive endocrinologists collapses geographic access barriers for rural United States populations.
Diagnostic imaging holds installed capacity. Wearable devices are rotating up the share rankings.
End User:
End user segmentation exposes the tension between institutional procurement scale and direct-to-consumer margin expansion.
- Home Users:Self-directed consumers purchasing through Amazon, pharmacy retail, and brand-direct websites. United States reimbursement code G2013 for remote patient monitoring devices is expanding insurance coverage for connected maternal health tools.
- Hospitals:Integrated delivery networks negotiating enterprise contracts for diagnostic imaging and surgical devices. Academic medical centers in Boston and San Francisco anchor premium ultrasound placements.
- Clinics:Independent gynecology practices and fertility centers selecting point-of-care devices for rapid diagnostic turnaround.
- Healthcare Providers:Individual physician practices and community health workers deploying portable screening tools in underpenetrated regions.
Hospitals hold installed capacity. Home users are rotating up the share rankings.
Application:
Application segmentation maps clinical urgency against consumer willingness to pay for autonomous management tools.
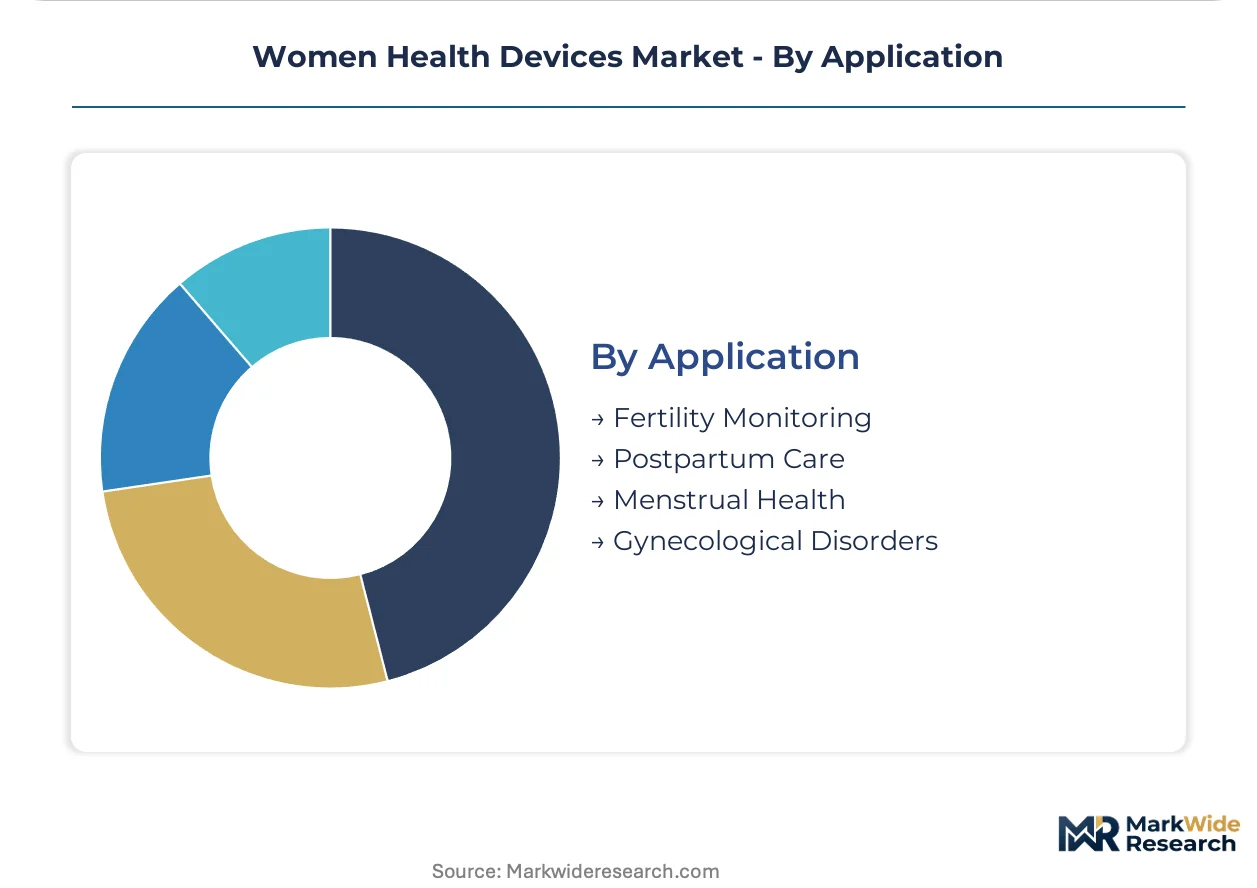
- Fertility Monitoring:Pre-conception cycle tracking combining basal temperature, cervical mucus observation, and hormone testing. German statutory health insurance reimbursement for fertility apps is expanding addressable market boundaries beyond out-of-pocket spenders.
- Postpartum Care:Lactation support, perineal healing monitoring, and mood disorder screening in the 12 weeks following delivery. United States Medicaid expansion for doula services is creating new device procurement channels through community-based organizations.
- Menstrual Health:Dysmenorrhea management, heavy bleeding tracking, and endometriosis symptom documentation for specialist referral preparation.
- Gynecological Disorders:Cervical cancer screening, STI detection, and pelvic floor dysfunction therapeutic devices deployed in clinical settings.
Gynecological disorders hold installed capacity. Fertility monitoring is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export diagnostic imaging systems to hospital networks across Germany and the United Kingdom, establishing transatlantic trade corridors for premium women's health technologies. This bilateral flow concentrates regulatory capital in FDA-cleared devices before EU MDR conformity assessments enable European market entry.
United States
Direct-to-consumer fertility apps and connected wearable sensors capture accelerating demand among millennials in urban coastal markets. FDA Software as a Medical Device guidance streamlines 510(k) clearance pathways for algorithm-driven cycle tracking tools. Boston and San Francisco anchor academic medical center procurement of AI-enabled ultrasound systems for maternal-fetal medicine.
Germany
Statutory health insurance reimbursement for digital fertility applications expands addressable market boundaries beyond out-of-pocket consumer spend. EU MDR clinical evidence requirements for Class IIa gynecological devices extend conformity assessment timelines. Munich and Frankfurt clusters concentrate R&D investment for integrated mother-and-child care platforms spanning pregnancy through postpartum.
India
Community health worker-deployable point-of-care cervical screening devices address diagnostic access gaps outside metropolitan hospital networks. CDSCO medical device regulations impose phased registration requirements for imported women's health technologies. Karnataka and Maharashtra sub-regions concentrate manufacturing capacity for low-cost pregnancy test kits serving domestic and export markets.
China
Domestic demand for portable ultrasound systems accelerates through county-level hospital infrastructure expansion programs. NMPA medical device registration pathways prioritize clinical evidence from multi-center domestic trials. Yangtze River Delta industrial clusters integrate MEMS sensor fabrication for wearable temperature tracking devices.
United Kingdom
NHS long-term plan commitments to maternal health digitization drive procurement of remote patient monitoring devices for postpartum care. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for AI-enabled diagnostic software. London and Cambridge ecosystems concentrate venture investment for femtech startups developing algorithmic fertility prediction tools.
Women Health Devices Market Vendor Landscape
Listed leaders compete with private specialists across regulatory capital intensity and channel access dimensions. The vendor base fragments across three tiers: diversified medical technology conglomerates with institutional imaging portfolios, mid-cap diagnostic specialists defending niche fertility segments, and venture-backed software-native entrants capturing direct-to-consumer margin pools. Strategic moves concentrate on platform integration bundling hardware with subscription analytics, and geographic licensing partnerships accelerating emerging market penetration.
Within the diversified conglomerate tier, Hologic, GE Healthcare Technologies, and Koninklijke Philips N.V. exemplify scale-driven positioning through installed base defense in diagnostic imaging and integrated care ecosystems. Hologic leverages its Massachusetts-based manufacturing footprint to anchor institutional channel relationships. GE Healthcare Technologies occupies a position bridging premium hospital networks with point-of-care expansion. Koninklijke Philips N.V. represents the integrated platform archetype spanning pregnancy through postpartum monitoring.
| Leading Market Players |
|---|
| Hologic |
| GE Healthcare Technologies |
| Koninklijke Philips N.V. |
| Boston Scientific Corporation |
| Samsung Electronics |
| F. Hoffmann-La Roche |
| Medtronic |
| Coloplast A/S |
| The Cooper Companies |
| Others |
Supply Flow & Price Mechanics
Installed capacity utilization across Taiwanese MEMS foundries sits above 85 percent, compressing lead times for wearable temperature sensors while simultaneously hardening price floors for precision basal tracking hardware. This scale concentration cascades into finished device economics, where manufacturers with captive sensor supply command margin advantages over assembly-only competitors.
Pricing Analysis
Next-generation AI-enabled ultrasound systems command 40-60 percent premiums over conventional imaging hardware, while prior-generation digital fertility trackers face commoditization pressure from smartphone-based algorithm substitutes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from wellness-grade consumer hardware and unregulated app-only solutions. Pricing pressure stems from software-native entrants collapsing subscription fees for cycle tracking analytics. Home users in tier-2 Indian cities exhibit highest price sensitivity, while academic medical centers in Boston and San Francisco show lowest sensitivity for AI-assisted maternal-fetal imaging.
Supply Chain Analysis
Inventory cycles for medical-grade silicone components stretch 14-20 weeks, constraining menstrual cup and breast pump manufacturers during demand surges. Manufacturing concentrates in China for MEMS sensor fabrication, Taiwan for precision temperature sensing modules, and Malaysia for final device assembly. Raw material dependencies span lithium-ion cells for wearable power management, optical glass for imaging systems, and biocompatible polymers for intimate-use devices. Single-source vulnerability concentrates in Taiwanese foundries supplying 0.1°C precision temperature sensors. Distribution runs through Amazon and pharmacy retail for home users, GPO contracts for hospital networks, and community health worker deployment for rural screening programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Women's health devices sit in early-cycle expansion as direct-to-consumer channels displace traditional clinic gatekeepers, with FDA Software as a Medical Device guidance accelerating algorithm-driven product commercialization timelines.
For Market Incumbents: Shield installed base relationships in diagnostic imaging through integrated platform bundling of hardware with longitudinal analytics subscriptions. Acquire software-native fertility tracking capabilities to neutralize direct-to-consumer substitution threats. Prioritize certification investment for EU MDR Class IIa compliance to preempt 12-18 month conformity assessment delays. For New Entrants and Emerging Players: Differentiate on AI-enabled diagnostic claims cleared through FDA 510(k) pathways rather than wellness-grade positioning vulnerable to regulatory reclassification. Target community health worker-deployable cervical screening devices in rural India where diagnostic access gaps exceed 70 percent penetration deficits. Pursue hospital system partnership go-to-market models for remote patient monitoring reimbursement under United States code G2013. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-native entrants with subscription fertility coaching bundled to connected hardware, offering superior cash flow predictability against transactional diagnostic device manufacturers. Five-to-ten year viability favors platforms spanning pregnancy through postpartum monitoring with integrated mother-and-child care ecosystems. Monitor FDA enforcement discretion against smartphone-only ovulation apps making diagnostic claims as inflection signal for regulatory reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Accelerates 510(k) clearance timelines for algorithm-driven fertility tracking tools in United States markets. |
| EU MDR CE Marking Pathway | Enables European market access for Class IIa gynecological devices despite extended clinical evidence requirements. |
| Hospital System Partnership | Secures GPO contract access for AI-enabled ultrasound placements in academic medical centers. |
| Software Companion Development | Transforms one-time hardware sales into recurring subscription revenue through longitudinal menstrual health analytics. |
| Reimbursement Strategy | Expands insurance coverage for connected maternal health tools under United States remote patient monitoring codes. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and reproductive endocrinologists and refined through secondary validation against FDA 510(k) filings, CDSCO registration databases, CMS Medicare reimbursement schedules, and EU MDR conformity assessment records. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated with top-down market sizing from trade flow analysis and installed base estimates.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation dimensions spanning diagnostic imaging versus wearable hardware, institutional versus direct-to-consumer channels, and acute diagnostic versus longitudinal monitoring applications. CAGRs were derived from logistic adoption curves fitted to penetration benchmarks in comparable connected health device categories. Forecast inputs incorporate reimbursement code expansion timelines and regulatory clearance velocity assumptions for algorithm-driven diagnostics.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement discretion for software-native entrants or prolonged EU MDR assessment delays would require recalibration. Forecasts reflect documented assumptions regarding telehealth platform expansion rates and smartphone camera substitution thresholds. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Menopause Market
Women's Health
Women's Health Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Software Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women's Health App Market
Women's Health
Maternal Health Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Care Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women's Digital Health Market
Women's Health
Dysfunctional Uterine Bleeding Market