
 Global Menopausal Hot Flashes Market | 2026-2036
Global Menopausal Hot Flashes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Menopausal Hot Flashes Market Foresight
Gynecologist workforce shortages in rural healthcare networks is bifurcating patient access between metropolitan specialty centers and telehealth platforms. Pfizer Inc. leverages its established hormone therapy manufacturing infrastructure to sustain supply chain reliability across North American markets. Bayer AG anchors its competitive position through integrated pharmaceutical and consumer health divisions. Novo Nordisk A/S specializes in metabolic and hormonal research pipelines that extend into menopausal symptom management.
Menopausal hot flashes constitute recurrent thermoregulatory disturbances characterized by sudden peripheral vasodilation, profuse sweating, and elevated skin conductance, typically triggered by declining ovarian estrogen output affecting hypothalamic set-point stability. Hormone therapy remains the clinical standard with demonstrated efficacy in reducing vasomotor episode frequency, though non-hormonal therapy segments are gaining fastest traction among patients with contraindications to estrogen. Distribution through online retailers is capturing disproportionate volume growth as direct-to-consumer platforms reduce pharmacy visit friction for recurring prescription fulfillment.
The FDA maintains stringent oversight of estrogen-progestin combination products through its Division of Bone, Reproductive and Urologic Products, while Europe's MDR framework imposes elevated clinical evidence requirements on cooling devices marketed for symptomatic relief. Japan's PMDA evaluates novel non-hormonal compounds through accelerated review pathways for unmet needs in aging populations. Stakeholders must monitor evolving reimbursement criteria for digital therapeutic adjuncts and hormone-free alternatives across these regulatory jurisdictions.
Market Dynamics
Non-hormonal therapeutic pathways are fragmenting patient flows away from traditional gynecology clinics toward direct-to-consumer platforms and wearable cooling technologies, forcing incumbents to reconfigure distribution architectures and clinical trial endpoints simultaneously.
Growth Catalysts
- FDA Division of Bone, Reproductive and Urologic Products pathway modernization:Accelerated review timelines for neurokinin-3 receptor antagonists reduce development-to-commercialization cycles for novel vasomotor symptom interventions.
- Japan PMDA unmet needs designation:Aging female demographics in Tokyo, Osaka, and Nagoya metropolitan corridors qualify novel compounds for priority assessment, compressing regulatory lag.
- Hypothalamic kisspeptin-neurokinin B-dynorphin pathway modulation:Biopharmaceutical pipelines targeting KNDy neuron circuits offer mechanistic alternatives to estrogen receptor agonism with reduced thromboembolic liability profiles.
Market Restraints
- Europe MDR clinical evidence elevation:Cooling garments and wearable thermoregulatory devices now require Class IIa conformity assessments with post-market surveillance obligations, extending certification timelines by 18-24 months.
- Active pharmaceutical ingredient concentration:Synthetic estrogen and progestin precursor manufacturing clusters in Zhejiang Province and Gujarat create single-source dependencies for hormone therapy formulation.
- Pharmacovigilance infrastructure asymmetry:Rural healthcare networks in the United States lack adverse event reporting density to support real-world evidence generation for non-hormonal alternatives.
Strategic Opportunities
- Brazil ANVISA harmonization with FDA standards:Convergence in bioequivalence protocols for transdermal estrogen patches enables parallel submission strategies across Latin America's largest pharmaceutical market.
- Digital therapeutic adjunct integration:Cognitive behavioral therapy applications paired with physiological monitoring wearables create reimbursable bundled interventions for employer-sponsored health plans.
- Menopause-specific service line expansion:Gynecology clinics in Germany's university hospital networks are establishing dedicated vasomotor symptom centers with nurse practitioner-led follow-up protocols.
Industry Challenges
- Thermoregulatory physiology modeling expertise:Computational biologists capable of translating skin conductance and peripheral blood flow data into regulatory-acceptable endpoints remain concentrated in Boston and Basel talent pools.
- Legacy electronic health record interoperability:Menopause symptom severity scales lack standardized coding in ICD-10-CM and SNOMED CT implementations, fragmenting outcome tracking across health system silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Menopausal Hot Flashes Market |
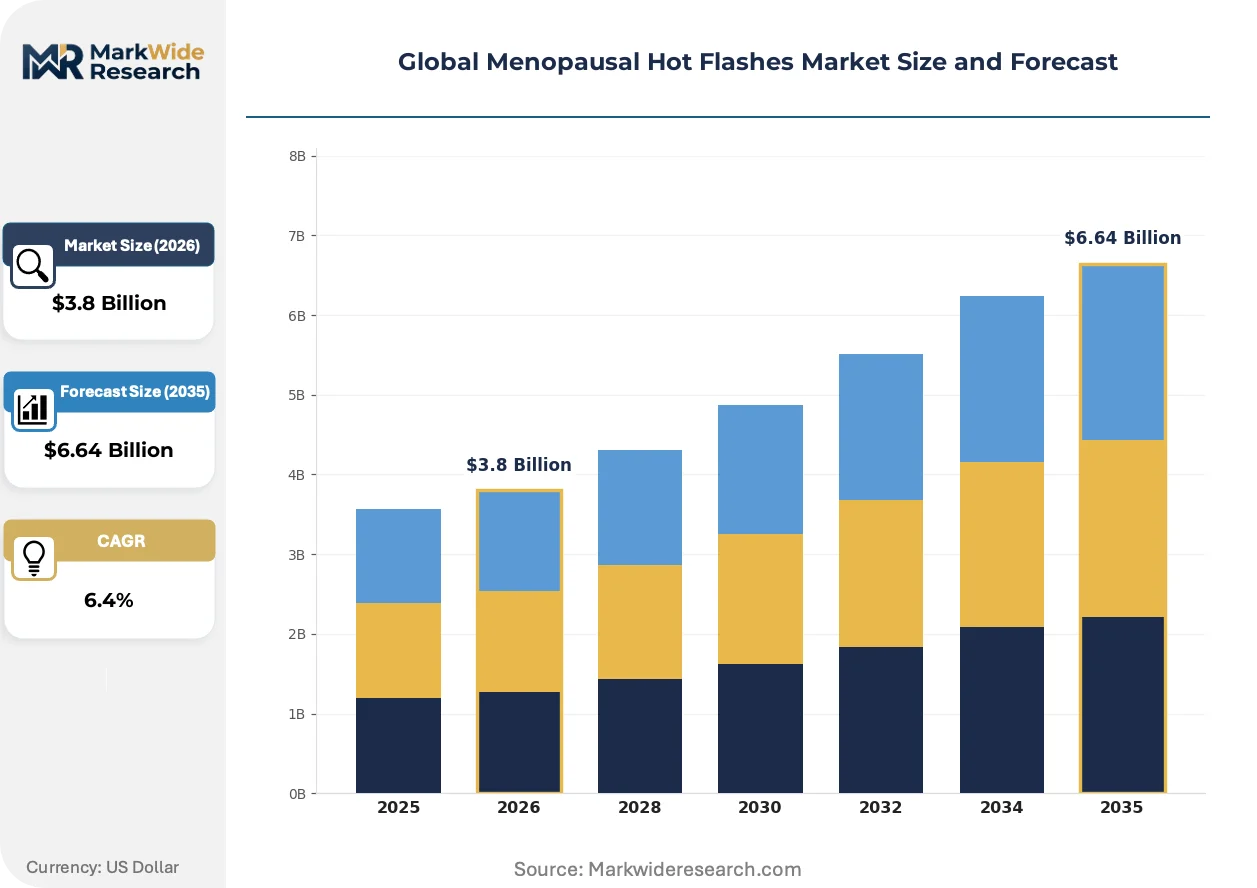
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Therapy, Non-Hormonal Therapy, Herbal Supplements, Cooling Devices, Homeopathic Remedies Therapy Area: Vasomotor Symptoms, Sleep Disorders, Mood Swings, Osteoporosis Prevention, Cardiovascular Health End User: Gynecology Clinics, Wellness Centers, Pharmaceutical Companies, Alternative Medicine Practitioners Distribution Channel: Pharmacies, Online Retailers, Specialty Stores, Healthcare Providers, Direct-to-Consumer |
| Companies Covered | Pfizer Inc., AbbVie Inc., Bayer AG, Teva Pharmaceutical Industries Ltd., Novo Nordisk A/S, Astellas Pharma, Hisamitsu Pharmaceutical Co. Inc., TherapeuticsMD Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Menopausal Hot Flashes Market Shifts & Advancements
Wearable cooling technologies and algorithm-driven thermal comfort systems are displacing passive symptom management, creating new device categories that sit between pharmaceuticals and consumer wellness products.
Personalized cooling garments with phase-change material integration are decomposing the traditional binary choice between hormone therapy acceptance and untreated symptom burden. Early adopters in Silicon Valley and Singapore's biomedical corridor are prescribing these devices as first-line interventions for patients with cardiovascular contraindications. The technology is decomposing reimbursement boundaries between durable medical equipment and over-the-counter wellness categories, forcing payers to develop novel coverage determination frameworks.
Europe's MDR post-market clinical follow-up requirements for thermoregulatory devices now mandate real-world performance data collection through patient-reported outcome instruments. Manufacturers must maintain post-authorization safety studies with minimum two-year follow-up periods for cooling vests and localized cryotherapy systems. German notified bodies are interpreting these obligations most stringently, creating competitive differentiation for firms with established pharmacovigilance infrastructure.
Subscription-based direct-to-consumer platforms are capturing recurring prescription fulfillment for non-hormonal therapies, bypassing traditional pharmacy benefit manager formularies. Telehealth-integrated delivery models in the United States and United Kingdom are displacing quarterly in-person gynecology visits for stable patients. This channel migration is most pronounced among employed women aged 45-55 in metropolitan healthcare corridors with same-day delivery logistics density.
Global Menopausal Hot Flashes Market Segmentation
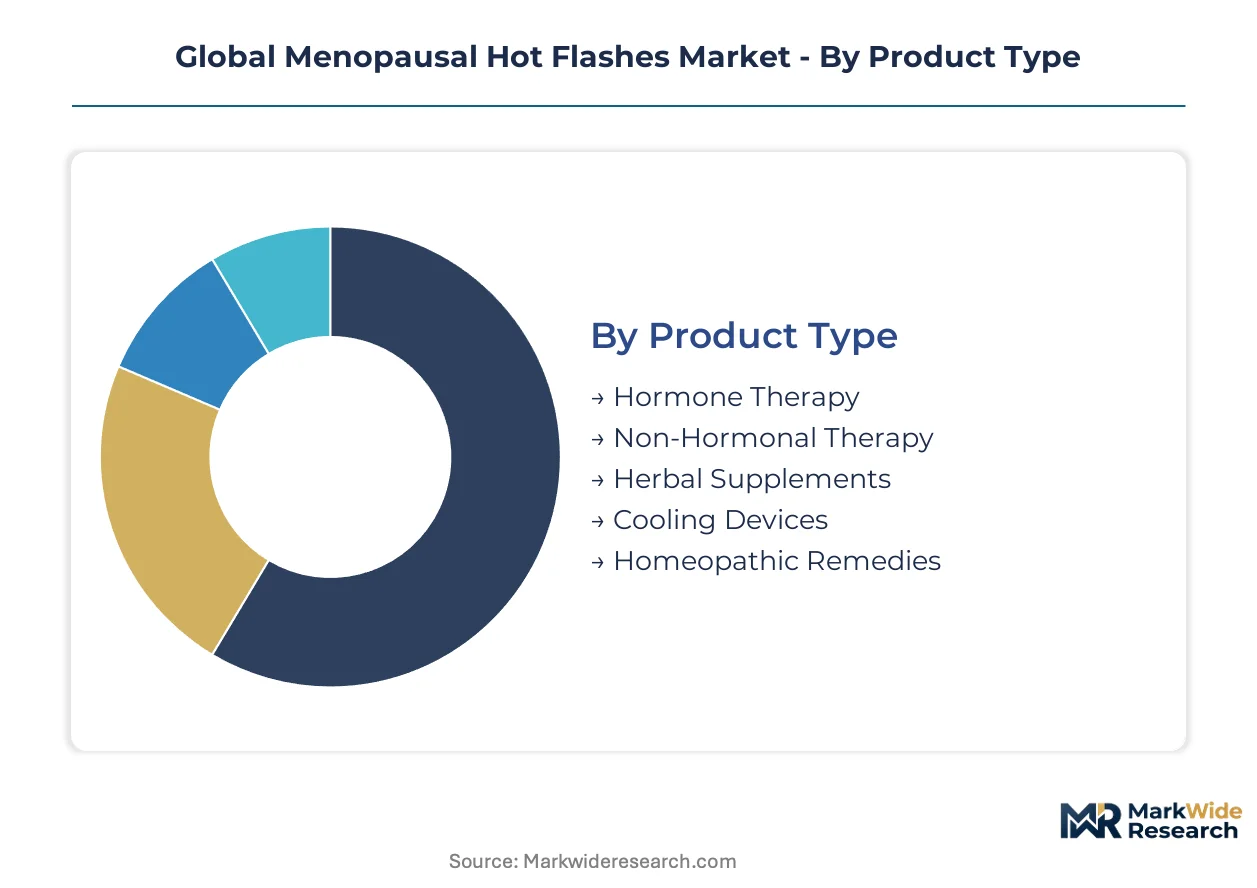
Segmentation in the menopausal hot flashes market reflects divergent regulatory pathways and patient risk profiles. FDA's Division of Bone, Reproductive and Urologic Products maintains distinct review standards for hormonal versus non-hormonal modalities, while Europe's MDR imposes device-specific conformity requirements on cooling technologies. These jurisdictional variations create asymmetric competitive barriers across product categories.
Product Type:
FDA estrogen-progestin oversight versus MDR Class IIa device certification defines competitive entry costs across therapeutic modalities.
- Hormone Therapy:Synthetic estrogen and progestin formulations administered via oral, transdermal, or vaginal routes. Demand concentrates in North American metropolitan healthcare corridors where gynecology clinic density supports prescription monitoring protocols. FDA's REMS requirements for certain estrogen products sustain incumbent manufacturer advantages through compliance infrastructure investments.
- Non-Hormonal Therapy:Neurokinin-3 receptor antagonists and selective serotonin reuptake inhibitors targeting hypothalamic KNDy neuron circuits. Adoption accelerates fastest among patients with thromboembolic contraindications in Tokyo, Osaka, and Nagoya metropolitan corridors qualifying for Japan PMDA priority review pathways.
- Herbal Supplements:Phytoestrogen compounds and black cohosh extracts positioned between pharmaceutical and wellness regulatory categories.
- Cooling Devices:Phase-change material garments and wearable thermoregulatory systems requiring Europe MDR post-market surveillance obligations.
- Homeopathic Remedies:Highly diluted natural preparations distributed primarily through specialty retail channels with minimal clinical evidence requirements.
Established volume favors Hormone Therapy; emerging adoption favors Non-Hormonal Therapy.
Therapy Area:
Symptom severity scoring instruments drive reimbursement eligibility and prescribing patterns across clinical indications.
- Vasomotor Symptoms:Recurrent hot flashes and night sweats constituting the primary diagnostic criterion for menopausal transition. Severe episode frequency in Germany's university hospital networks is prompting dedicated service line investments with nurse practitioner-led follow-up protocols.
- Sleep Disorders:Thermoregulatory disturbance-related insomnia disrupting sleep architecture and daytime functioning. Digital therapeutic adjuncts pairing cognitive behavioral applications with physiological monitoring wearables are gaining reimbursable status in employer-sponsored United States health plans.
- Mood Swings:Estrogen fluctuation-associated affective dysregulation overlapping with perimenopausal depression presentations.
- Osteoporosis Prevention:Bone mineral density preservation through estrogen receptor agonism in long-term hormonal strategies.
- Cardiovascular Health:Metabolic and vascular risk modification considerations influencing therapy selection in patients with contraindications.
Clinical trial investment concentrates in Vasomotor Symptoms; digital health integration is expanding most quickly in Sleep Disorders.
End User:
Workforce distribution between metropolitan specialty centers and rural telehealth platforms fragments patient access geometries.
- Gynecology Clinics:Traditional site of diagnosis and prescription initiation with established hormone therapy protocols. Germany's university hospital networks are establishing dedicated vasomotor symptom centers with specialized nursing infrastructure.
- Wellness Centers:Lifestyle and complementary intervention delivery outside pharmaceutical reimbursement frameworks. Silicon Valley and Singapore biomedical corridor adoption of cooling garments as first-line cardiovascular-contraindicated patient management is reshaping referral patterns.
- Pharmaceutical Companies:Internal therapeutic development and medical affairs functions supporting clinical evidence generation.
- Alternative Medicine Practitioners:Herbal and homeopathic remedy provision operating under distinct regulatory classifications across jurisdictions.
Prescription volume concentrates in Gynecology Clinics; patient-initiated access is climbing the fastest in Wellness Centers.
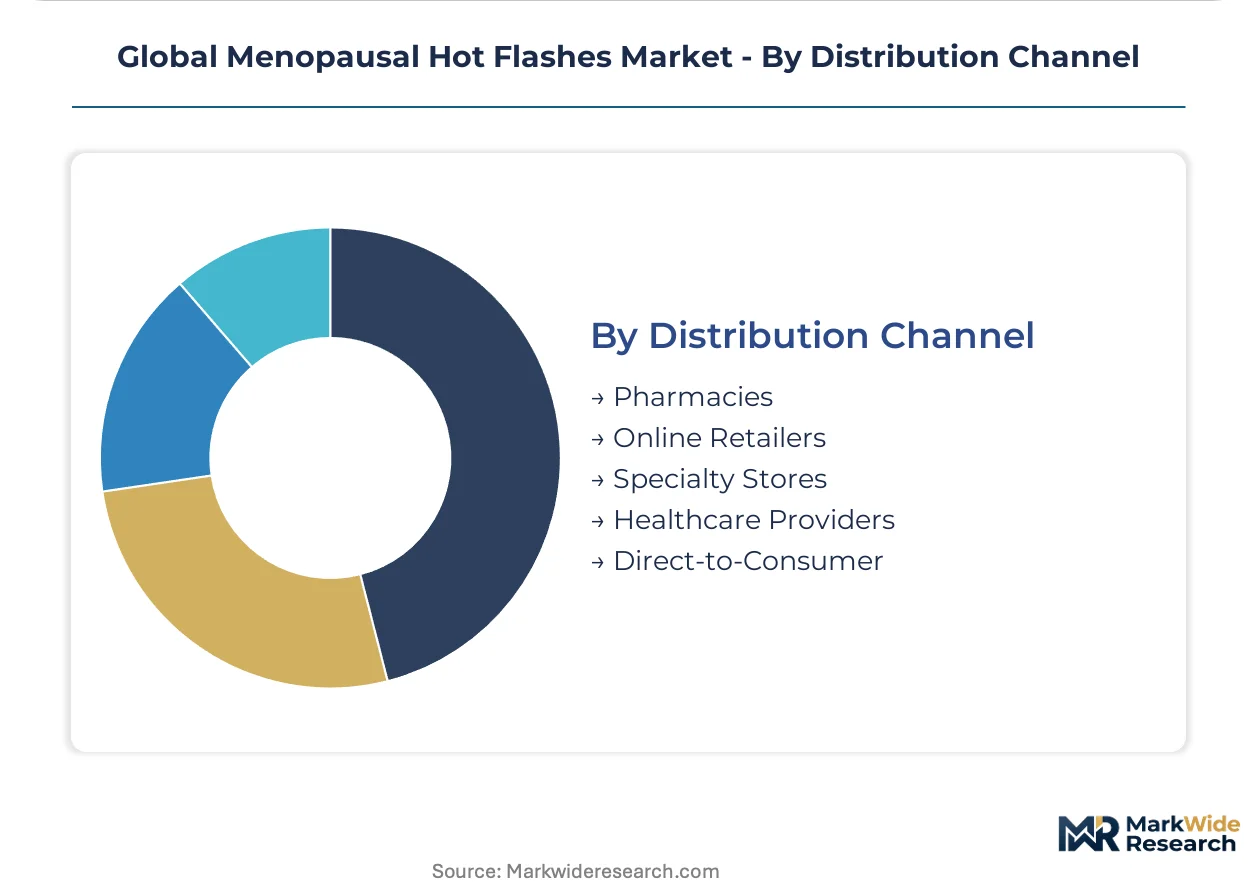
Distribution Channel:
Logistics density and pharmacy benefit manager formulary positioning determine channel economics.
- Pharmacies:Brick-and-mortar dispensing with established cold chain and counseling infrastructure. Zhejiang Province and Gujarat API manufacturing clusters create single-source dependencies for hormone therapy supply security.
- Online Retailers:Direct-to-consumer platforms reducing pharmacy visit friction for recurring prescription fulfillment. Same-day delivery density in United States and United Kingdom metropolitan corridors is displacing quarterly in-person gynecology visits for stable patients.
- Specialty Stores:Wellness-focused retail environments for device and supplement categories.
- Healthcare Providers:Institutional procurement and dispensing within integrated delivery networks.
- Direct-to-Consumer:Subscription-based models bypassing traditional pharmacy benefit manager formulary restrictions.
Transaction volume favors Pharmacies; recurring subscription economics are gaining share fastest in Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metropolitan corridors while manufacturing cost advantages cluster in Indian pharmaceutical clusters, creating divergent margin structures across therapeutic categories.
United States
Employer-sponsored health plans in metropolitan healthcare corridors drive premium reimbursement for digital therapeutic adjuncts. FDA's Division of Bone, Reproductive and Urologic Products maintains accelerated review pathways for neurokinin-3 receptor antagonists. Boston and Silicon Valley talent pools concentrate computational biologists translating thermoregulatory physiology into regulatory endpoints.
Germany
University hospital networks are establishing dedicated vasomotor symptom centers with nurse practitioner-led protocols. Europe's MDR framework imposes Class IIa conformity assessments on cooling devices with 18-24 month certification timelines. Notified bodies in Berlin and Munich interpret post-market surveillance obligations most stringently.
Japan
Aging female demographics in Tokyo, Osaka, and Nagoya metropolitan corridors qualify novel compounds for PMDA priority assessment. Japan's pharmaceutical regulator compresses regulatory lag for unmet needs in menopausal symptom management. Domestic manufacturers leverage accelerated review pathways to outpace Western competitors in non-hormonal therapy segments.
India
Active pharmaceutical ingredient manufacturing clusters in Gujarat and Zhejiang Province create single-source dependencies for hormone therapy precursors. The country's national pharmaceutical regulator harmonizes bioequivalence protocols with FDA standards for transdermal patch submissions. Hyderabad and Ahmedabad facilities supply synthetic estrogen formulations to North American markets.
Brazil
ANVISA convergence with FDA bioequivalence standards enables parallel submission strategies across Latin America's largest pharmaceutical market. Middle-class expansion in São Paulo and Rio de Janeiro drives patient-initiated access to non-hormonal alternatives. Domestic distributors are bypassing traditional pharmacy benefit manager structures through direct-to-consumer platforms.
Global Menopausal Hot Flashes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across hormonal and non-hormodal therapeutic segments. The market structure consolidates around established pharmaceutical manufacturers with compliance infrastructure investments while fragmenting among wearable cooling device specialists. Three archetypes dominate: integrated pharmaceutical conglomerates with hormone therapy manufacturing scale, metabolic research specialists extending into menopausal indications, and direct-to-consumer platform operators bypassing traditional pharmacy channels. Dominant competitive moves include strategic partnerships with telehealth platforms and portfolio diversification into digital therapeutic adjuncts.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Bayer AG occupy positions anchored by established manufacturing infrastructure and dual pharmaceutical-consumer health divisions. Novo Nordisk A/S exemplifies the metabolic research specialist archetype, with hormonal research pipelines extending into symptom management applications. These three entities represent the spectrum from diversified healthcare conglomerates to focused metabolic science organizations competing across overlapping therapeutic territories.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Novo Nordisk A/S |
| Astellas Pharma |
| Hisamitsu Pharmaceutical Co. Inc. |
| TherapeuticsMD Inc. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month MDR certification timelines for cooling devices in Germany compress inventory turns and amplify pricing power for established manufacturers with notified body relationships, while API concentration in Gujarat and Zhejiang Province creates asymmetric cost structures across hormonal versus non-hormonal therapeutic tiers.
Pricing Analysis
Metropolitan United States corridors command 40-60% premiums over Indian pharmaceutical clusters for identical hormone therapy formulations. Three-tier pricing structure across branded originators, authorized generics, and unbranded alternatives separates reimbursement-eligible prescriptions from cash-pay wellness categories. Cost compression in cooling devices is intensifying because Europe's MDR post-market surveillance obligations force compliance infrastructure investments. Employer-sponsored health plans exhibit lowest price sensitivity; rural cash-pay patients in Brazil and India face highest out-of-pocket burden.
Supply Chain Analysis
Strategic stockpiling of synthetic estrogen precursors dominates over just-in-time preferences given single-source dependencies in Zhejiang Province and Gujarat. Active pharmaceutical ingredient manufacturing draws from petrochemical feedstocks and specialized fermentation capacity concentrated in China and India. Single-source vulnerability for hormone therapy precursors creates supply interruption exposure from environmental compliance actions or export restriction shifts. Distribution runs through pharmacy benefit manager formularies in North America, direct-to-consumer platforms in metropolitan United Kingdom corridors, and hospital procurement systems in Germany's university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurokinin-3 receptor antagonist approvals through FDA accelerated pathways signal a regulatory inflection disrupting decades of estrogen-centric therapeutic paradigms, creating asymmetric opportunity for non-hormodal modality specialists.
For Market Incumbents: Secure formulary positioning for hormone therapy portfolios through REMS compliance infrastructure investments that emerging competitors cannot replicate. Deepen pharmacovigilance capabilities in Boston and Basel talent pools to capture real-world evidence generation for cooling device post-market surveillance obligations. Defend against direct-to-consumer platform disintermediation by integrating subscription fulfillment capabilities with telehealth partnerships. For New Entrants and Emerging Players: Anchor in cardiovascular-contraindicated patient segments where cooling garments and wearable thermoregulatory devices bypass pharmaceutical reimbursement complexity. Target sleep disorder digital therapeutic adjuncts in employer-sponsored United States health plans where cognitive behavioral therapy applications pair with physiological monitoring wearables for bundled intervention reimbursement. Pursue nurse practitioner-led protocol licensing from Germany's university hospital vasomotor symptom centers as clinical credibility anchor. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-capture play because aging female populations in Tokyo, Osaka, and Nagoya metropolitan corridors guarantee sustained demand expansion regardless of therapeutic modality shifts. Acquisition target archetype: metabolic research specialists with KNDy neuron circuit intellectual property extending beyond diabetes into menopausal symptom management. Watch FDA Division of Bone, Reproductive and Urologic Products neurokinin-3 receptor antagonist approval velocity as inflection indicator for non-hormonal therapy segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Certification Pathway | European notified body relationships in Berlin and Munich create 18-24 month competitive moats for cooling device manufacturers. |
| PMDA Priority Review Designation | Tokyo, Osaka, and Nagoya aging demographics qualify novel compounds for compressed regulatory timelines against Western competitors. |
| Digital Therapeutic Adjunct Integration | Cognitive behavioral therapy applications paired with wearables secure reimbursable status in employer-sponsored United States health plans. |
| Direct-to-Consumer Platform Launch | Subscription models bypass pharmacy benefit manager formulary restrictions and capture recurring prescription fulfillment economics. |
| KNDy Neuron Circuit Patent Estate | Hypothalamic kisspeptin-neurokinin B-dynorphin pathway intellectual property extends metabolic research pipelines into menopausal indications. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads at FDA and PMDA, formulary directors in employer-sponsored health plans, and hospital procurement managers in Germany's university hospital networks converged on the working assumptions underlying therapeutic modality demand projections. Secondary validation drew from FDA Division of Bone, Reproductive and Urologic Products filings, Japan PMDA submission databases, ClinicalTrials.gov neurokinin-3 receptor antagonist protocols, and Europe MDR notified body conformity assessment records. Bottom-up prescription volume modeling and top-down demographic expenditure analysis triangulated on segment-level estimates.
Segmentation dimensions modeled span product type, therapy area, end user, and distribution channel across the projection horizon. Hormone therapy, non-hormonal therapy, herbal supplements, cooling devices, and homeopathic remedies constituted product type splits. CAGRs derived from patient population epidemiology, regulatory approval probability-weighted revenue forecasts, and channel shift elasticity parameters. Forecast inputs incorporated hypothalamic KNDy neuron circuit clinical trial readouts, MDR certification timeline distributions, and telehealth platform penetration curves in metropolitan healthcare corridors.
Material uncertainties — regulatory approval delays for neurokinin-3 receptor antagonists, MDR notified body capacity constraints extending certification timelines, API manufacturing cluster environmental compliance actions — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement criteria evolution for digital therapeutic adjuncts and hormone-free alternatives. Revision becomes warranted when FDA accelerated review pathway utilization rates or Japan PMDA priority designation grant frequencies cross threshold shifts indicating regulatory sentiment inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women Health Devices Market
Women's Health
US Womens Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
Maternal Health Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women's Digital Health Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Software Market
Women's Health
Women's Health App Market
Women's Health
Women Health Care Market
Women's Health
Menopause Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Women's Health Market