
 Women Health Disease Diagnosis and Treatment Market | 2026-2036
Women Health Disease Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Women Health Disease Diagnosis and Treatment Market Analytics
Subscription-based software layers for imaging analytics and remote monitoring is hardening into a standard revenue component alongside device sales. Hologic, Inc. leverages its installed base of mammography systems to sustain recurring service income. Siemens Healthineers AG anchors its competitive position through deep integration of AI-assisted diagnostic workflows. Thermo Fisher Scientific Inc. differentiates via molecular diagnostics specialization for reproductive and oncology applications.
Women health disease diagnosis and treatment encompasses clinical systems for detecting, monitoring, and managing conditions including reproductive disorders, cardiovascular disease, hormonal imbalances, and cancers specific to female physiology, utilizing imaging modalities operating at 3-7 MHz ultrasound frequencies and molecular assays detecting circulating biomarkers. The primary commercial purpose is to enable earlier intervention and personalized therapeutic pathways that reduce morbidity and healthcare system costs. Imaging Systems command substantial capital allocation from hospital procurement committees due to replacement cycles and regulatory upgrade mandates. Molecular Diagnostics represents the fastest-expanding technology segment as liquid biopsy and PCR-based platforms penetrate routine gynecological screening. Telemedicine deployment within Home Care Settings is reshaping access models for hormone therapy management and post-treatment monitoring.
The FDA governs premarket clearance for diagnostic devices and AI-enabled software through 510(k) and De Novo pathways, directly shaping product development timelines and clinical evidence requirements. The EMA's Medical Device Regulation enforces stricter post-market surveillance and clinical performance standards for devices distributed across European member states. The WHO's guidelines on cervical and breast cancer screening establish reference frameworks that national health ministries adapt into reimbursement and procurement policies. Stakeholders must monitor how regulatory convergence on software-as-a-medical-device classification reshapes competitive barriers and partnership strategies.
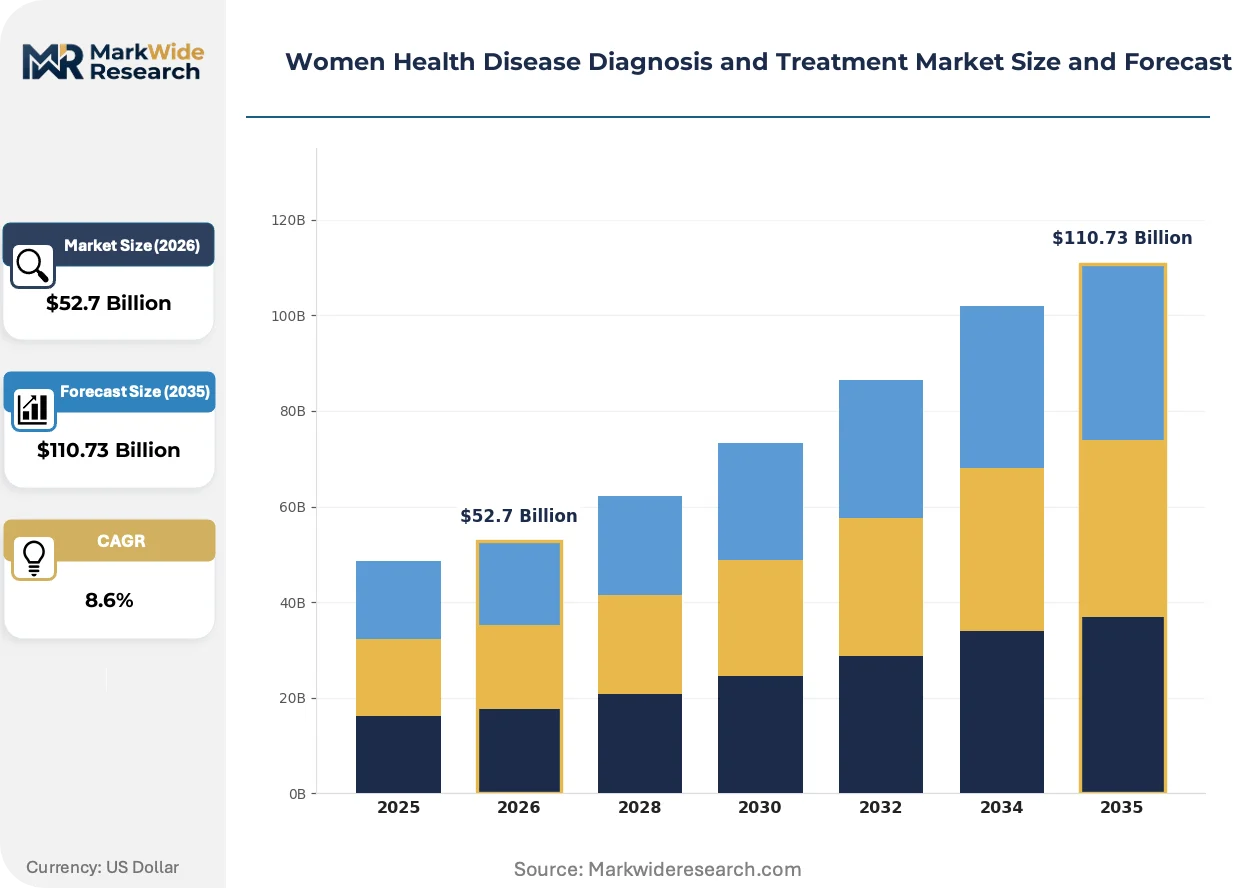
Market Dynamics
Hospital procurement committees now prioritize integrated diagnostic platforms that bundle imaging hardware with AI-enabled analytics software, compressing traditional equipment replacement cycles and elevating software validation to a core purchasing criterion.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined premarket review for AI-assisted diagnostic devices accelerates commercialization timelines for algorithm-driven mammography and cervical screening tools.
- Home Care Telemedicine Infrastructure:Remote hormone monitoring platforms expand addressable patient populations beyond hospital-centric delivery models into ambulatory and residential settings.
- Specialized Women's Health Centers:Concentrated capital deployment in the United States, Germany, and Japan creates anchor demand for high-throughput molecular diagnostics and multimodal imaging systems.
Market Restraints
- Clinical Evidence Generation Costs:FDA De Novo and EMA MDR pathways demand extensive prospective validation studies that extend development timelines and consume R&D budgets.
- Supply Concentration in Imaging Detectors:Dependence on specialized semiconductor foundries for ultrasound transducer arrays and digital radiography sensors creates input vulnerability.
- Interoperability Friction:Legacy hospital information systems resist seamless integration with cloud-native diagnostic platforms, forcing costly middleware development.
Strategic Opportunities
- Liquid Biopsy Penetration in Gynecological Oncology:Circulating tumor DNA assays for ovarian and endometrial cancer monitoring remain underdeployed relative to breast cancer applications.
- EU AI Act Compliance Services:Conformity assessment requirements for high-risk medical AI create adjacent revenue streams in algorithm auditing and documentation automation.
- Subscription Revenue Architecture:Per-procedure pricing models for AI analytics layers atop installed imaging bases transform capital equipment vendors into recurring service providers.
Industry Challenges
- Computational Pathology Talent Scarcity:Shortage of clinicians cross-trained in machine learning model validation delays regulatory submission preparation.
- Multi-Site Clinical Trial Coordination:Recruitment across dispersed women's health centers complicates endpoint standardization and data harmonization for PMA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Health Disease Diagnosis and Treatment Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Therapeutic Devices, Monitoring Devices, Imaging Systems Application: Reproductive Health, Cardiovascular Health, Hormone Therapy, Cancer Treatment End User: Clinics, Hospitals, Research Institutions, Home Care Settings Technology: Telemedicine, Artificial Intelligence, Wearable Technology, Molecular Diagnostics |
| Companies Covered | Hologic, Inc., F. Hoffmann-La Roche Ltd., Quest Diagnostics Incorporated, GE Healthcare, Koninklijke Philips N.V., Abbott, Siemens Healthineers AG, Thermo Fisher Scientific Inc., BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Health Disease Diagnosis and Treatment Market Evolving Landscape
Artificial intelligence is embedding into diagnostic workflows at every layer, from image acquisition optimization through automated report generation, while regulatory frameworks race to codify validation standards for continuously learning algorithms.
Deep learning algorithms for mammography and ultrasound lesion detection now operate at sensitivity thresholds matching experienced radiologists. Academic medical centers in the United States and Japan deploy these tools for triage and second-read applications. Siemens Healthineers is integrating AI-assisted diagnostic workflows into its imaging platforms, compressing interpretation time and reducing inter-reader variability.
The EMA's Medical Device Regulation enforces stricter post-market surveillance and clinical performance documentation across European member states. Manufacturers must maintain active safety monitoring systems and periodic safety update reports for software-as-a-medical-device classifications. Molecular diagnostics vendors with PCR-based platforms face heightened scrutiny of analytical validity claims under MDR Annex XIV clinical evidence requirements.
Hospital procurement committees increasingly unbundle equipment acquisition from service and analytics subscriptions, treating AI software layers as separate line items with independent renewal cycles. Imaging system vendors respond with modular pricing architectures that decouple hardware warranties from algorithm access fees. This behavioral shift is most pronounced in German hospital networks consolidating purchasing through centralized procurement cooperatives.
Women Health Disease Diagnosis and Treatment Market Segmentation
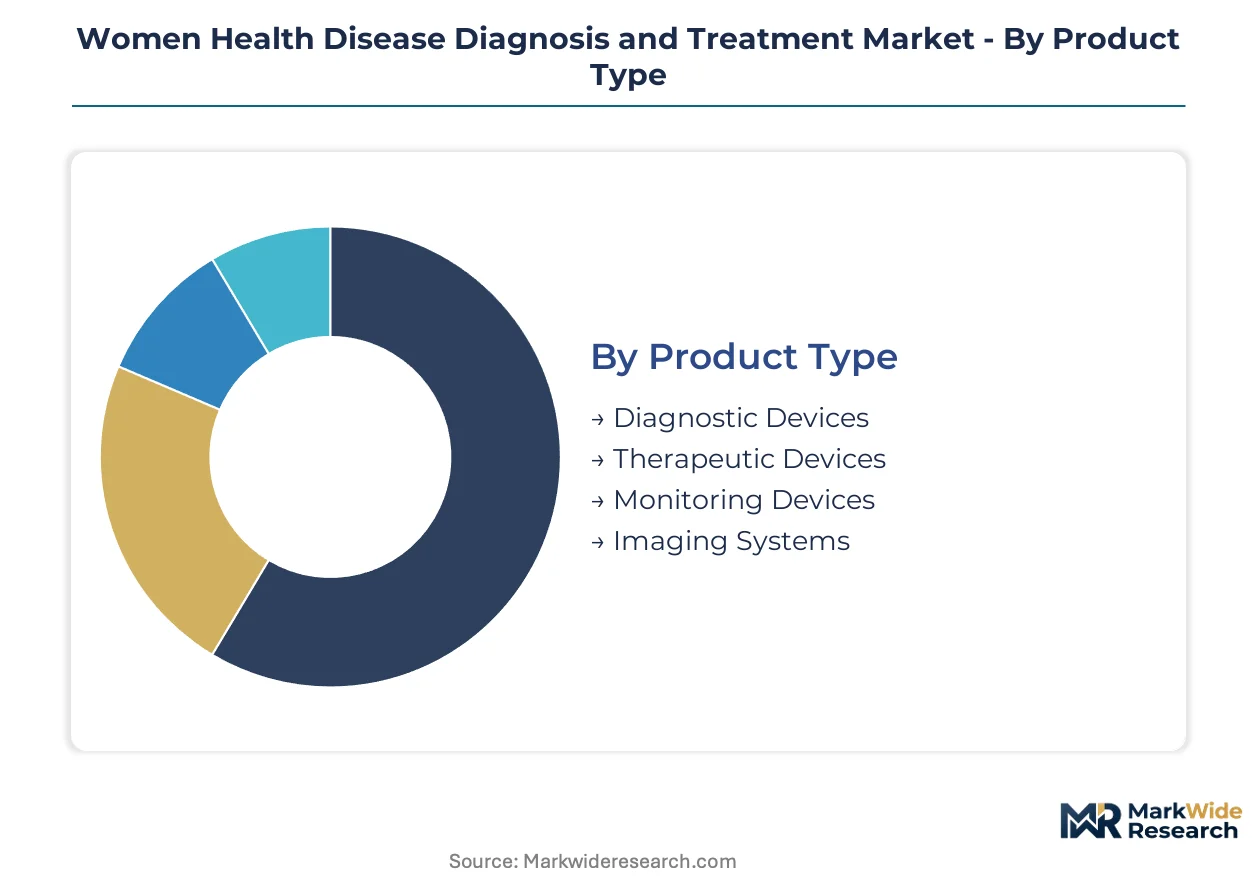
Segmentation in women's health diagnostics reveals how capital allocation, clinical workflow integration, and patient access models diverge across hardware, software, and service layers. Procurement patterns vary sharply between acute care institutions and ambulatory settings, while technology adoption curves separate established imaging modalities from emerging AI-enabled platforms.
Product Type:
Hospital procurement committees distinguish equipment categories by replacement cycle length, software attach rates, and regulatory recertification burden.
- Imaging Systems:Mammography, ultrasound, and MRI platforms operating at 3-7 MHz frequencies anchor capital budgets through 7-10 year depreciation schedules. United States hospital networks concentrate demand here as they modernize fleets to meet FDA AI-validation requirements for mammography screening.
- Diagnostic Devices:Biopsy systems, colposcopes, and specimen collection instruments command mid-tier procurement priority with shorter 3-5 year refresh cycles. German hospital cooperatives bundle these with imaging purchases to secure volume discounts on integrated diagnostic platforms.
- Therapeutic Devices:Minimally invasive surgical systems and radiation delivery equipment for gynecological oncology applications.
- Monitoring Devices:Continuous glucose monitors, blood pressure cuffs, and fertility tracking hardware for ambulatory and residential deployment.
Volume sits with Imaging Systems; growth tilts toward Diagnostic Devices.
Application:
Clinical specialization depth determines reimbursement rates and equipment utilization intensity across therapeutic domains.
- Cancer Treatment:Screening, staging, and monitoring workflows for breast, cervical, ovarian, and endometrial malignancies drive the highest equipment throughput per installed unit. Japanese specialized women's health centers prioritize multimodal imaging integration for oncology pathways.
- Reproductive Health:Fertility assessment, prenatal screening, and menopause management applications span ultrasound, hormone assay, and genetic testing modalities. United States fertility clinic chains expand molecular diagnostics capacity for preimplantation genetic screening.
- Cardiovascular Health:Sex-specific risk stratification and diagnostic protocols for ischemic heart disease in female patients.
- Hormone Therapy:Endocrine monitoring and therapeutic adjustment for polycystic ovary syndrome, thyroid disorders, and menopausal symptom management.
Revenue concentrates in Cancer Treatment; expansion accelerates most rapidly in Reproductive Health.
End User:
Site-of-care economics and patient acuity levels reshape vendor go-to-market strategies and pricing architectures.
- Hospitals:Integrated delivery networks with centralized procurement functions negotiate enterprise-wide imaging contracts bundling hardware, software subscriptions, and AI analytics layers. These institutions absorb the highest per-site capital deployment and generate recurring service revenue for installed base vendors.
- Home Care Settings:Remote hormone monitoring, fertility tracking, and post-treatment surveillance platforms bypass facility-based infrastructure entirely. Telemedicine infrastructure expansion in Germany and Japan accelerates patient migration toward residential diagnostic models.
- Clinics:Independent gynecological practices and ambulatory surgical centers with limited capital budgets.
- Research Institutions:Academic medical centers conducting clinical trials for novel diagnostic algorithms and biomarker validation.
Capital deployment peaks at Hospitals; patient volume is shifting fastest toward Home Care Settings.
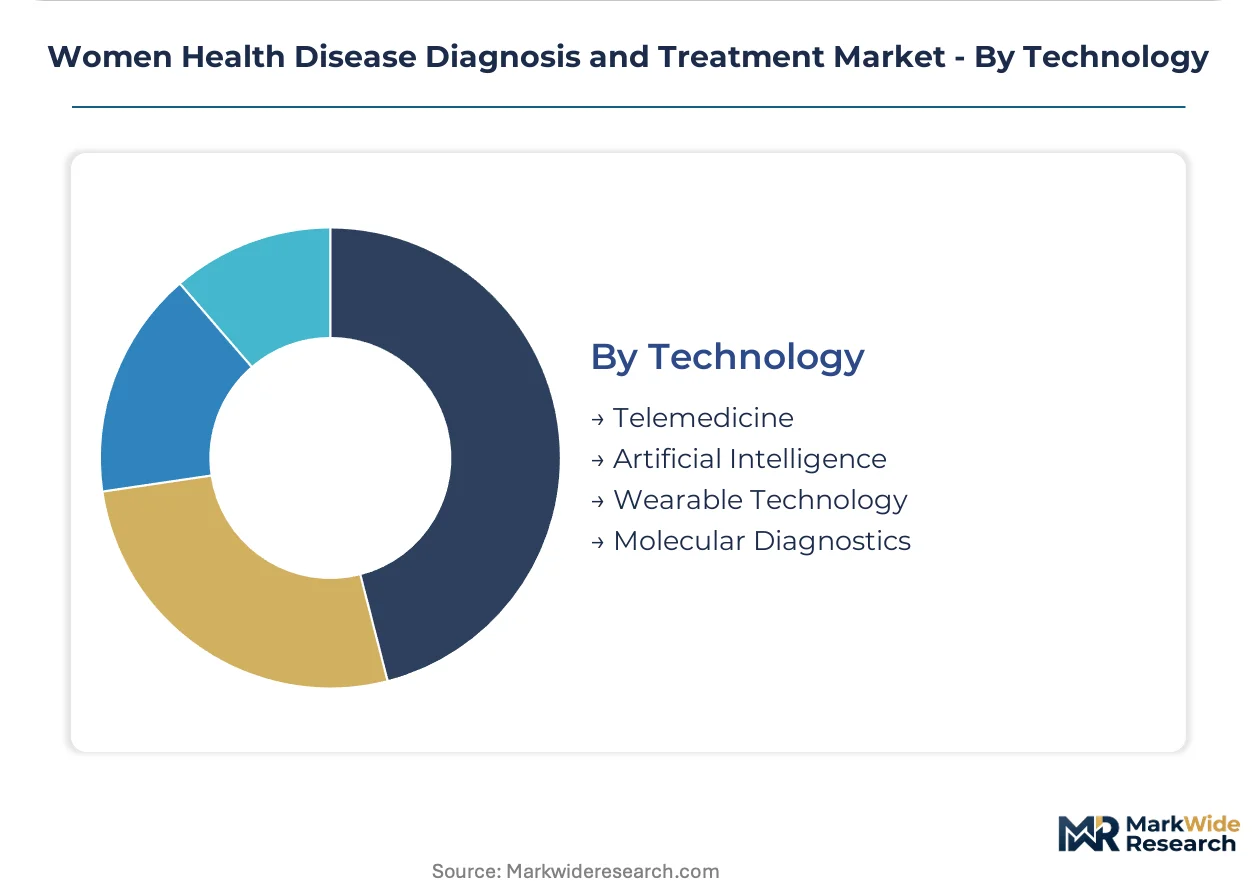
Technology:
Intellectual property intensity and regulatory classification complexity separate modular software layers from hardware-dependent platforms.
- Molecular Diagnostics:PCR-based platforms and liquid biopsy assays for circulating tumor DNA detection command premium pricing through analytical specificity claims. Reproductive and gynecological oncology applications remain underpenetrated relative to breast cancer, creating expansion headroom.
- Artificial Intelligence:FDA 510(k) and De Novo pathway clearances for mammography triage, cervical cytology screening, and ultrasound lesion detection compress interpretation time. Continuous learning algorithms face evolving EMA MDR and EU AI Act conformity assessment requirements.
- Telemedicine:Synchronous consultation and asynchronous image transmission platforms for remote specialist access.
- Wearable Technology:Consumer-grade fertility trackers and clinical-grade cardiac monitors for longitudinal data collection.
Investment intensity clusters in Molecular Diagnostics; regulatory velocity is accelerating most sharply for Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors concentrated demand for integrated women's health diagnostic platforms. Specialized centers of excellence in this corridor drive procurement of multimodal imaging systems and molecular diagnostics infrastructure. Hospital networks across three continents are replicating this clustering model.
United States
Specialized women's health centers in Massachusetts and California concentrate demand for high-throughput molecular diagnostics and AI-enabled mammography systems. FDA 510(k) pathway modernization accelerates commercialization timelines for algorithm-driven screening tools. The Texas Medical Center in Houston deploys integrated diagnostic platforms bundling imaging hardware with analytics software subscriptions.
Germany
Hospital procurement cooperatives in North Rhine-Westphalia and Bavaria negotiate enterprise-wide imaging contracts with modular pricing architectures. EMA Medical Device Regulation enforces stricter post-market surveillance and clinical performance documentation across member states. The Munich biomedical cluster advances AI-assisted diagnostic workflow integration for gynecological oncology applications.
Japan
Academic medical centers in Tokyo and Osaka deploy deep learning algorithms for mammography triage and ultrasound lesion detection at sensitivity thresholds matching experienced radiologists. PMDA regulatory frameworks shape validation requirements for continuously learning algorithms. The Kobe biomedical innovation cluster specializes in multimodal imaging integration for reproductive health pathways.
United Kingdom
NHS England's specialized women's health hubs in London and Manchester drive standardization of liquid biopsy protocols for ovarian and endometrial cancer monitoring. MHRA convergence with EMA MDR requirements elevates software validation to core purchasing criteria. The Cambridge life sciences corridor advances PCR-based platform development for prenatal screening applications.
India
Private hospital chains in Maharashtra and Karnataka expand molecular diagnostics capacity for reproductive health and gynecological oncology. CDSCO regulatory pathways for in-vitro diagnostics shape product registration timelines and clinical evidence requirements. The Hyderabad medical technology cluster develops cost-optimized imaging systems for ambulatory diagnostic settings.
Women Health Disease Diagnosis and Treatment Market Competitive Landscape
Capital-heavy imaging system manufacturers compete with asset-light molecular diagnostics specialists for procurement committee attention. The market structure concentrates around integrated platform vendors with substantial installed bases and recurring service revenue streams. Three archetypes dominate: diversified conglomerates with deep imaging portfolios, pure-play molecular diagnostics specialists, and emerging AI-native software vendors. Competitive moves center on strategic partnerships between hardware OEMs and algorithm developers, plus subscription revenue architecture transformation.
Within the diversified conglomerate tier, Siemens Healthineers AG and GE Healthcare exemplify capital-intensive platform integration strategies. Hologic, Inc. and Thermo Fisher Scientific Inc. occupy positions emphasizing molecular diagnostics specialization and reproductive health applications. These four entities collectively represent the competitive tension between imaging hardware scale and molecular assay precision that procurement committees must navigate.
| Leading Market Players |
|---|
| Hologic, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Quest Diagnostics Incorporated |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Abbott |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| BD |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-cleared AI diagnostics and uncertified imaging software creates a bifurcated pricing architecture that simultaneously concentrates supply chain leverage among validated semiconductor foundries and fragments procurement authority across hospital procurement committees and ambulatory clinic buyers. This tiered performance gap manifests in subscription pricing premiums for algorithm-validated platforms and input scarcity for specialized ultrasound transducer arrays.
Pricing Analysis
Margin tightening in mid-tier diagnostic devices reflects compressed replacement cycles as German hospital cooperatives negotiate bundled imaging contracts. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled mammography systems with FDA 510(k) clearance from basic ultrasound hardware and refurbished equipment channels. Price differentiation hinges on software validation tier and after-sales service bundling. Ambulatory clinics exhibit highest price sensitivity; specialized women's health centers in Japan absorb premium positioning for multimodal integration.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and Germany limit production scaling for specialized imaging detector arrays. Supply chains draw from Japanese precision optics manufacturers, Taiwanese semiconductor foundries, and German sensor fabrication facilities. Raw material dependencies include rare earth elements for MRI magnets, silicon wafers for digital radiography sensors, and specialized polymers for ultrasound transducer housing. Single-source vulnerability concentrates in AI chip fabrication. Distribution runs through hospital procurement cooperatives and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving De Novo pathway for AI-enabled medical devices erects a cost-of-compliance barrier that entrenches incumbents with existing clinical evidence portfolios while filtering out undercapitalized software entrants. EMA MDR post-market surveillance requirements compound this moat across European member states.
For Market Incumbents: Hedge against algorithm commoditization by deepening in-house production of ultrasound transducer arrays and securing captive supply of specialized imaging detectors from Taiwanese foundries. Reinforce installed base lock-in through modular subscription architectures that decouple hardware warranties from AI analytics access fees. Prioritize certification investment for continuous learning algorithms under EU AI Act conformity assessment frameworks. For New Entrants and Emerging Players: The price-point gap between premium molecular diagnostics and economy-grade fertility tracking hardware opens white-space targets in liquid biopsy applications for ovarian and endometrial cancer monitoring. Underpenetrated reproductive health pathways in Indian private hospital chains offer the most penetrable geography. A software-as-a-medical-device go-to-market angle bypasses capital-intensive imaging hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with AI-native diagnostics specialists given FDA 510(k) pathway modernization accelerating commercialization timelines. Long-term viability over a 5-10 year window favors vendors with recurring service revenue architectures transforming capital equipment positions into subscription economics. The signal to watch is hospital procurement committee unbundling behavior separating equipment acquisition from analytics subscriptions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for algorithm-driven mammography screening tools. |
| CE Marking Pathway | Unlocks European hospital procurement cooperatives under EMA MDR compliance requirements. |
| Hospital System Partnership | Secures enterprise-wide imaging contracts bundling hardware with AI analytics subscriptions. |
| Software Companion Development | Transforms capital equipment vendors into recurring service providers through modular pricing. |
| Reimbursement Strategy | Aligns molecular diagnostics penetration with CMS and national health ministry coverage policies. |
Research Methodology
SEC filings, FDA 510(k) clearance databases, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at molecular diagnostics vendors combined with secondary validation across the study window. Bottom-up and top-down triangulation reconciled equipment shipment data with service revenue disclosures from installed base vendors.
Bottom-up modeling segmented volume and value across imaging systems, diagnostic devices, and molecular diagnostics platforms, with additional granularity by end-user site-of-care economics and technology regulatory classification. CAGRs were derived from installed base replacement cycle analysis and software attach rate trajectories throughout the forecast period. Forecast inputs incorporated FDA AI-validation requirement timelines and EMA MDR post-market surveillance cost assumptions.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in private fertility clinic pricing data introduce uncertainty bands in ambulatory segment projections. Forecasts reflect documented assumptions regarding regulatory convergence timelines and software-as-a-medical-device classification harmonization. Material deviation in FDA De Novo review velocity or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Menopause Market
Women's Health
Women Health Care Market
Women's Health
Women's Digital Health Market
Women's Health
Women Health Software Market
Women's Health
Women Health Devices Market
Women's Health
Women's Health App Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Women's Health Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Maternal Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
North America Womens Health Diagnostics Market