
 Women Health Care Market | 2026-2036
Women Health Care Market Size, Share, and Industry Trends Forecast 2026-2036
Women Health Care Market Insights
Specialty-grade clinical protocols is bifurcating the competitive landscape between premium service networks and standardized care pathways. Bayer AG leverages its endocrinology heritage to sustain leadership in hormonal therapy supply chains. Pfizer competes through geographic dominance in North American hospital formularies, while Merck & Co. differentiates via R&D intensity in fertility treatment biologics.
Women health care encompasses diagnostic, therapeutic, and preventive medical services addressing gynecological, reproductive, endocrine, and maternal-fetal conditions, typically delivered through specialized clinical protocols with defined quality benchmarks such as CAP-certified laboratory testing and FDA-cleared diagnostic thresholds. Its primary commercial purpose centers on reducing morbidity across life-stage transitions including menstruation, pregnancy, and menopause while enabling workforce participation through symptom management. Hormonal Therapies anchors the largest margin pool due to chronic administration cycles and patent-protected formulations, while Telehealth delivery is expanding fastest as reimbursement parity laws mature. Nutritional Supplements occupies a fragmented tier where brand strength determines pharmacy shelf access.
The FDA governs device clearance and drug approval pathways, while HIPAA mandates data security standards for reproductive health records; state-level abortion restrictions in the United States are fragmenting service availability and redirecting patient flows across borders. The EMA's Medical Device Regulation tightens clinical evidence requirements for intrauterine devices and diagnostic implants entering European markets. Stakeholders must monitor how payer consolidation affects specialty reimbursement rates for PCOS and menopause management services.
Market Dynamics
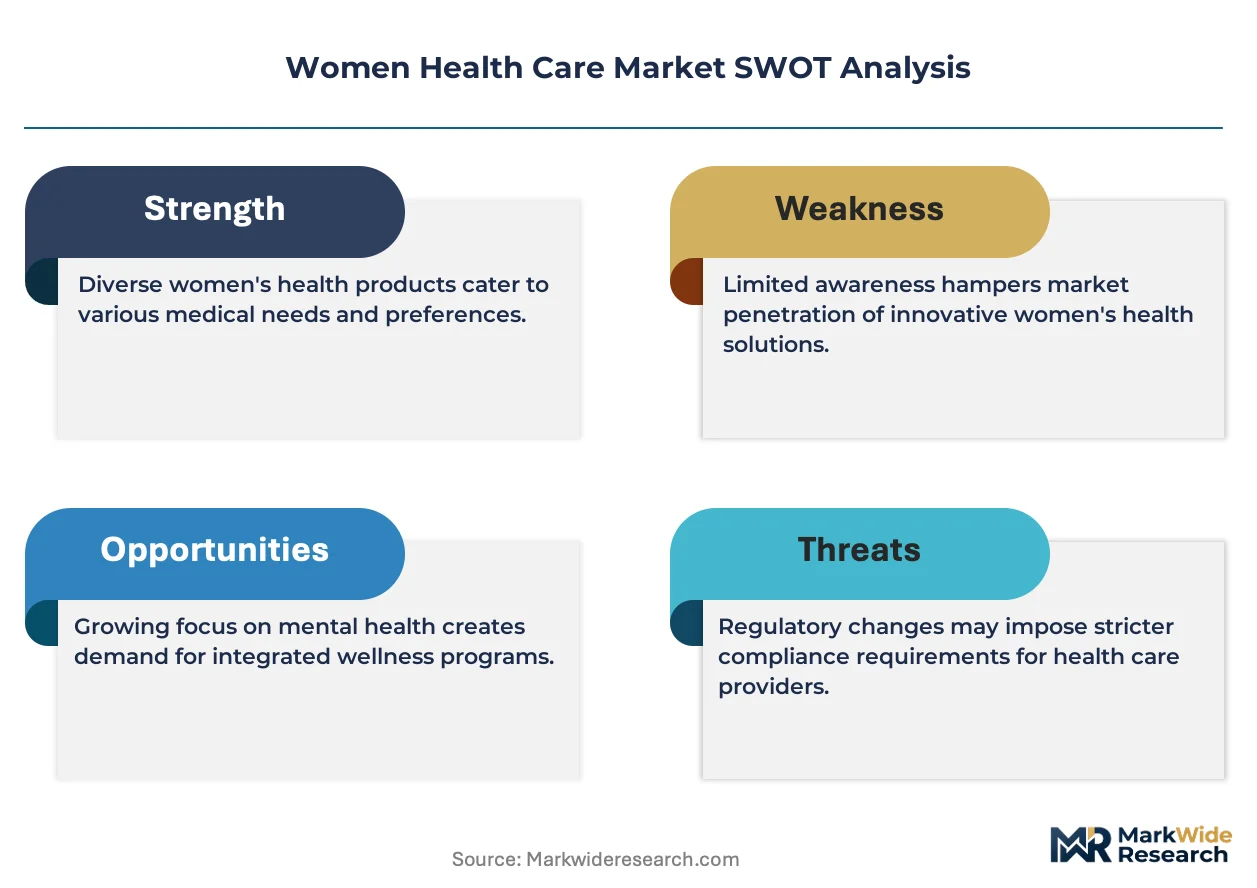
Specialty-grade clinical protocols are bifurcating competitive positioning between premium service networks and standardized care pathways, with reimbursement parity laws accelerating telehealth adoption against traditional clinic-based delivery.
Growth Catalysts
- FDA Menopausal Hormone Therapy Labeling Updates:Revised guidance on cardiovascular risk profiles is expanding prescriber confidence and extending therapy duration for symptomatic patients.
- Telehealth Reimbursement Parity:State-level mandates in the United States are normalizing virtual menopause consultations and remote fertility monitoring.
- Hospital System Service Line Expansion:Dedicated women's health centers in Germany and Japan are deepening specialty infrastructure and capturing complex case referrals.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Hormonal therapy supply chains depend on concentrated manufacturing in China and India, creating vulnerability to export restrictions.
- EMA Medical Device Regulation Compliance Burden:Intrauterine device manufacturers face extended clinical evidence timelines and notified body capacity constraints.
- Bioidentical Hormone Substitution:Compounded formulations from specialty pharmacies are fragmenting adherence to evidence-based prescribing protocols.
Strategic Opportunities
- PCOS Management Underservice:Diagnostic gaps in the United States present white space for integrated metabolic-endocrine care models.
- Remote Patient Monitoring Convergence:Wearable hormone tracking combined with AI-powered cycle prediction is enabling personalized fertility windows.
- Japan's Aging Demographic Tailwind:METI-supported longevity initiatives are expanding menopause symptom management reimbursement categories.
Industry Challenges
- Reproductive Endocrinology Fellowship Scarcity:Limited training pipeline capacity in the United States is constraining specialty clinic expansion.
- HIPAA-Compliant Data Architecture:Cross-border telehealth platforms face fragmented state-level privacy enforcement and record portability friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Health Care Market |
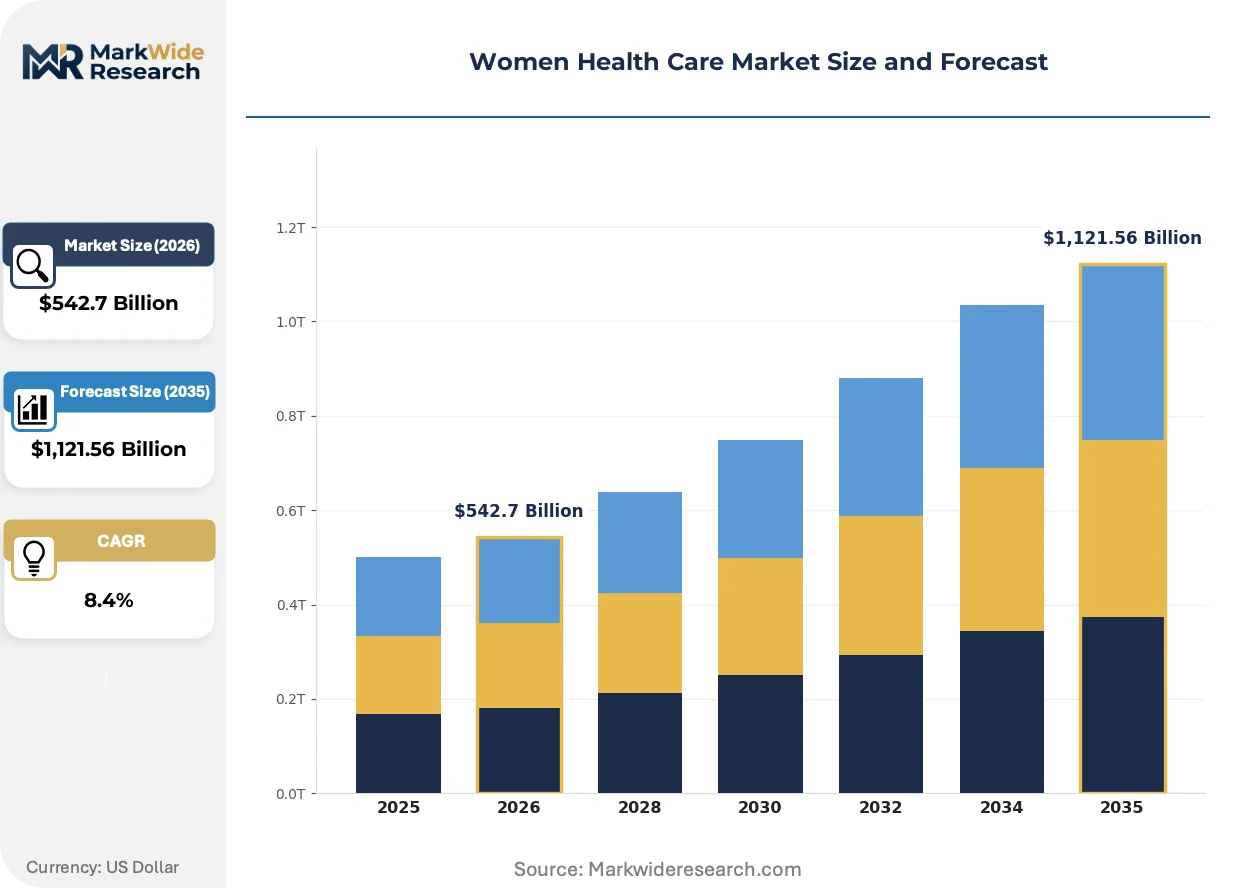
| Market Size in 2026 | $542.7 Billion |
| Market Size in 2035 | $1,121.56 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reproductive Health Devices, Diagnostic Kits, Hormonal Therapies, Nutritional Supplements End User: Clinics, Hospitals, Home Care, Pharmacies Application: Fertility Treatment, Pregnancy Care, Menopause Management, PCOS Treatment Delivery Mode: Online, Retail Pharmacy, Direct Sales, Telehealth |
| Companies Covered | AbbVie, Bayer AG, Pfizer, Amgen, Merck & Co., Teva Pharmaceutical Industries Ltd., Agile Therapeutics, Ferring, Apothecus Pharmaceutical Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Health Care Market Trends and Innovations
Digital diagnostic platforms and decentralized care models are compressing traditional clinic visit cycles while regulatory frameworks race to catch up with remote monitoring capabilities.
Continuous glucose monitoring adapted for polycystic ovary syndrome metabolic tracking is supplanting intermittent fasting insulin tests in fertility clinic protocols. Reproductive endocrinology practices in Germany and the United States are integrating these sensors into standard workups. The technology is supplanting labor-intensive blood draw schedules and enabling real-time lifestyle intervention timing.
EMA's Medical Device Regulation tightened clinical evidence requirements for intrauterine devices and diagnostic implants entering European markets. Manufacturers must now submit extended follow-up data on device migration and perforation rates. Smaller device developers are retreating from the EU market or partnering with larger firms to absorb compliance costs.
Subscription-based hormone therapy delivery is replacing traditional pharmacy pickup for chronic menopause management. Direct-to-consumer platforms in the United States are bundling telehealth consultations with automated refill logistics. This model concentrates patient data with platform operators and threatens traditional OB-GYN practice revenue streams.
Women Health Care Market Segmentation
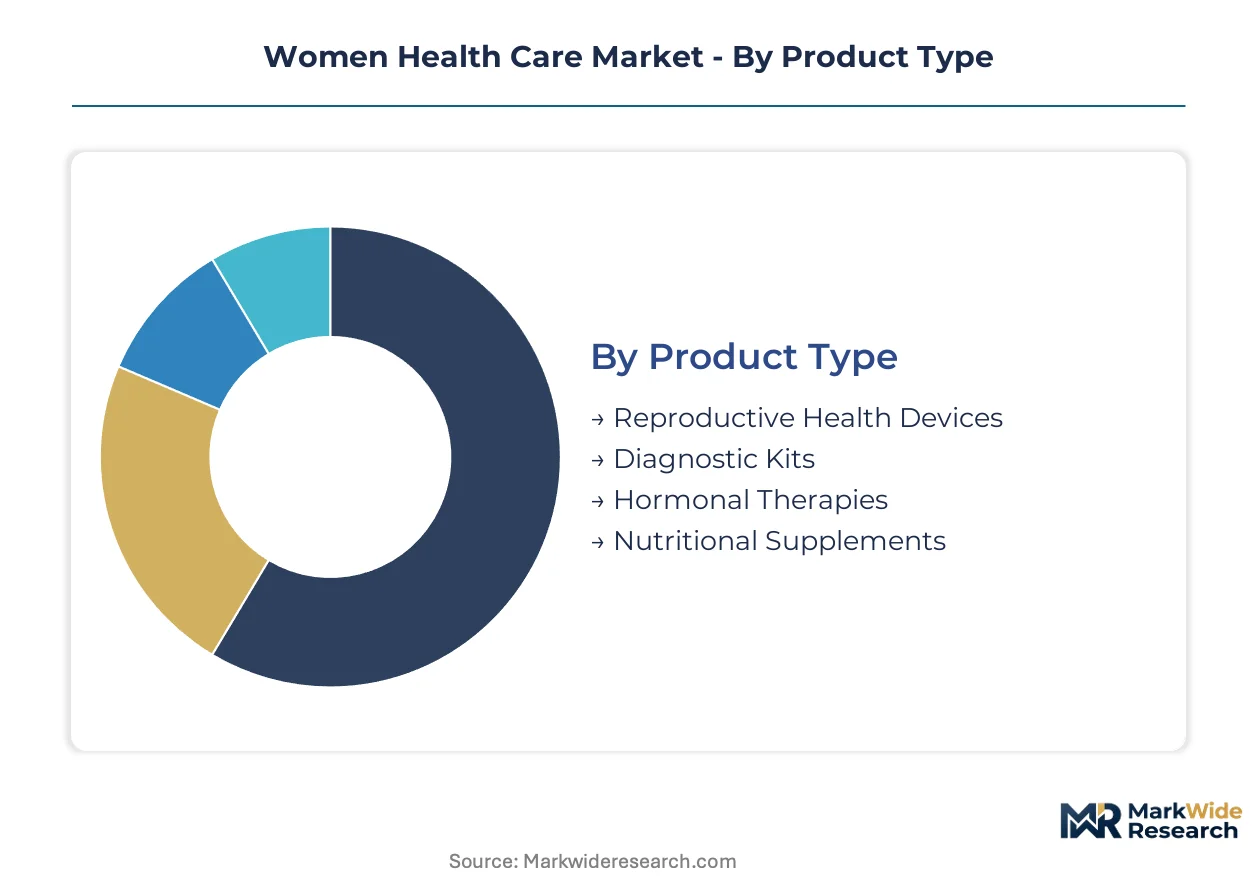
Segmentation in women's health care reveals where substitution pressures and reimbursement dynamics reshape competitive boundaries. Product-level distinctions between device-based and pharmaceutical interventions determine margin durability, while delivery mode fragmentation exposes legacy providers to platform disruption.
Product Type:
Bioidentical hormone substitution and compounded pharmacy formulations exert acute substitution pressure on Hormonal Therapies, while Nutritional Supplements face commoditization from private-label entrants.
- Hormonal Therapies:Patent-protected synthetic and bioidentical estrogen-progestin combinations administered via oral, transdermal, and intrauterine routes. Demand concentrates in United States hospital formularies where FDA labeling updates on cardiovascular risk profiles are extending prescriber confidence and therapy duration for symptomatic menopause patients.
- Reproductive Health Devices:Intrauterine devices, fertility monitors, and cryopreservation equipment with defined quality benchmarks including CAP-certified laboratory testing. Germany and Japan are deepening specialty infrastructure through dedicated women's health centers, capturing complex case referrals for fertility preservation and assisted reproduction.
- Diagnostic Kits:Ovulation predictors, pregnancy tests, and hormone level assays cleared through FDA or EMA pathways. Home-use adoption is climbing fastest in markets with telehealth reimbursement parity.
- Nutritional Supplements:Prenatal vitamins, menopause support formulations, and PCOS-targeted micronutrient blends. Brand strength determines pharmacy shelf access in this fragmented tier where direct-to-consumer platforms are gaining share.
Hormonal Therapies retains volume leadership; Reproductive Health Devices holds the steepest expansion curve.
End User:
Cost tier stratification separates high-acuity hospital-based care from margin-compressed retail channels, with reimbursement differentials determining patient routing.
- Hospitals:Acute maternal-fetal medicine, surgical gynecology, and reproductive endocrinology with embedded CAP-certified laboratory infrastructure. North American health systems are expanding dedicated women's health service lines to capture complex referrals and tertiary care revenue.
- Clinics:Outpatient fertility treatment, menopause management, and PCOS metabolic care delivered through reproductive endocrinology practices. Germany and United States practices are integrating continuous glucose monitoring sensors into standard polycystic ovary syndrome workups.
- Home Care:Self-administered hormone therapy, fertility tracking, and remote patient monitoring through wearable devices. Subscription-based delivery models are replacing traditional pharmacy pickup for chronic menopause management.
- Pharmacies:Dispensing point for hormonal prescriptions, over-the-counter diagnostic kits, and nutritional supplements. Shelf access negotiations favor brands with clinical validation and payer formulary placement.
Hospitals command the highest reimbursement per episode; Home Care is climbing fastest as remote monitoring capabilities mature.
Application:
Volume concentration in pregnancy-related services contrasts with underservice gaps in chronic condition management, creating divergent investment incentives.
- Fertility Treatment:Ovulation induction, in-vitro fertilization, and cryopreservation protocols requiring reproductive endocrinology fellowship-trained specialists. Limited training pipeline capacity in the United States is constraining specialty clinic expansion and creating waitlist bottlenecks.
- Menopause Management:Symptom control through hormonal and non-hormonal interventions across the menopausal transition. Japan's METI-supported longevity initiatives are expanding reimbursement categories for symptom management in aging demographics.
- Pregnancy Care:Prenatal screening, maternal-fetal monitoring, and delivery services with defined quality benchmarks. Hospital system service line expansion in Germany and Japan is deepening infrastructure for high-risk obstetrics.
- PCOS Treatment:Metabolic-endocrine care addressing insulin resistance, androgen excess, and fertility preservation. Diagnostic gaps in the United States present white space for integrated care models combining endocrinology and gynecology protocols.
Pregnancy Care retains volume leadership; PCOS Treatment holds the steepest expansion curve.
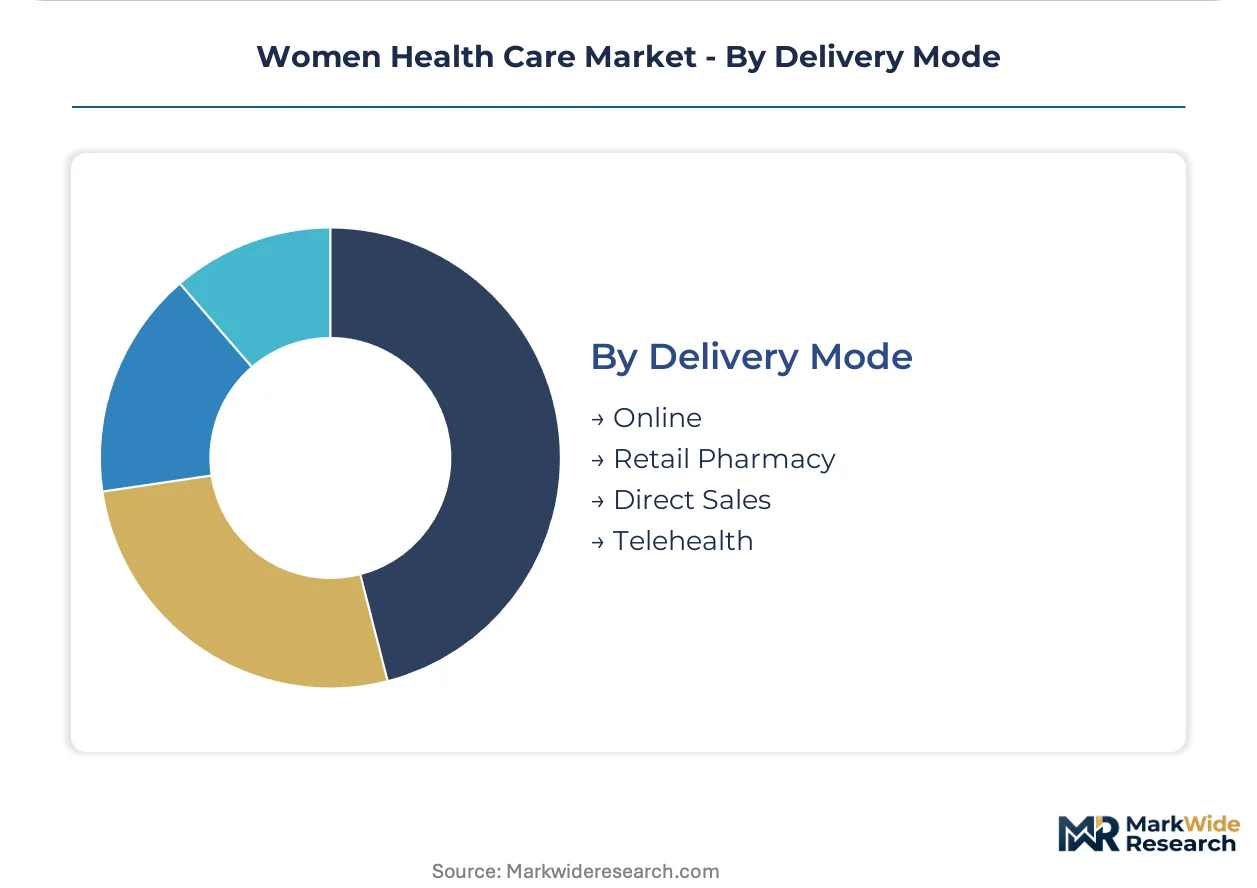
Delivery Mode:
Customer type fragmentation between platform-native consumers and legacy channel loyalists is forcing parallel distribution investments.
- Telehealth:Virtual consultations for menopause management, fertility counseling, and remote monitoring with HIPAA-compliant data architecture. State-level mandates in the United States are normalizing virtual consultations and remote fertility monitoring through reimbursement parity laws.
- Online:Direct-to-consumer platforms bundling telehealth consultations with automated refill logistics for hormone therapy and supplements. This model concentrates patient data with platform operators and threatens traditional OB-GYN practice revenue streams.
- Retail Pharmacy:Brick-and-mortar dispensing with pharmacist counseling and insurance adjudication. Formulary placement negotiations determine access for branded hormonal therapies.
- Direct Sales:Manufacturer-controlled distribution for specialty devices and premium supplement lines. EMA Medical Device Regulation compliance burdens are pushing smaller device developers toward partnership structures with larger firms.
Retail Pharmacy retains volume leadership; Telehealth is climbing fastest as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for hormonal active pharmaceutical ingredients sits heavily in China and India, creating geographic vulnerability that Western markets are addressing through supply chain diversification and regulatory reshoring incentives.
United States
Hospital systems are expanding dedicated women's health service lines to capture complex maternal-fetal medicine referrals, while state-level telehealth reimbursement parity laws normalize virtual menopause consultations. FDA labeling updates on cardiovascular risk profiles for menopausal hormone therapy are extending prescriber confidence and therapy duration. The Boston-Cambridge corridor anchors reproductive endocrinology research clusters where fertility preservation protocols are advancing rapidly.
Germany
Dedicated women's health centers are deepening specialty infrastructure to capture complex case referrals in fertility treatment and high-risk obstetrics. EMA Medical Device Regulation compliance burdens are pushing smaller intrauterine device developers toward partnership structures with larger firms. The Rhine-Ruhr metropolitan region concentrates reproductive medicine clinics integrating continuous glucose monitoring for polycystic ovary syndrome metabolic tracking.
Japan
METI-supported longevity initiatives are expanding reimbursement categories for menopause symptom management in aging demographics. PMDA regulatory frameworks govern device clearance pathways for fertility monitors and diagnostic implants. The Kanto region around Tokyo hosts the densest concentration of reproductive endocrinology practices adopting remote patient monitoring technologies.
India
Active pharmaceutical ingredient manufacturing for hormonal therapies concentrates in Gujarat and Maharashtra, supplying global generic formulations. CDSCO regulatory pathways are tightening clinical evidence requirements for imported reproductive health devices entering domestic markets. Hyderabad's pharmaceutical cluster is diversifying into contract manufacturing for Western hormonal therapy brands seeking supply chain redundancy.
United Kingdom
NHS long-term plan commitments are expanding access to fertility treatment and menopause services through primary care networks. MHRA post-Brexit regulatory autonomy is accelerating divergence from EMA device approval timelines. London's Harley Street medical district retains premium positioning for private reproductive endocrinology and fertility preservation services.
Women Health Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with patent-protected hormonal formulation developers commanding premium margins while generic API manufacturers compete on scale. The market structure bifurcates between consolidated pharmaceutical conglomerates with endocrinology heritage and fragmented device specialists facing regulatory compliance burdens. Three archetypes dominate: integrated pharma-hormone developers, reproductive device specialists, and direct-to-consumer platform operators. Competitive moves center on M&A for pipeline acquisition and strategic partnerships for EMA MDR compliance cost-sharing.
Among integrated pharmaceutical developers, Bayer AG and Pfizer exemplify the scale-driven archetype with established hospital formulary presence, while Merck & Co. occupies a position emphasizing R&D intensity in fertility treatment biologics. These entities anchor the premium tier through patent-protected portfolios and geographic reach, with their market representation reflecting the concentration of hormonal therapy revenue in chronic administration cycles.
| Leading Market Players |
|---|
| AbbVie |
| Bayer AG |
| Pfizer |
| Amgen |
| Merck & Co. |
| Teva Pharmaceutical Industries Ltd. |
| Agile Therapeutics |
| Ferring |
| Apothecus Pharmaceutical Corp. |
| Others |
Pricing and Supply Chain Analysis
FDA clearance tiers gate both supply qualification and price differentiation simultaneously, with 510(k) pathways separating premium bioidentical formulations from economy-grade generics while CAP-certified laboratory infrastructure commands formulary premiums. This regulatory scaffolding concentrates pricing power among incumbents with established hospital relationships, forcing new entrants to absorb compliance costs or accept margin compression in retail channels.
Pricing Analysis
FDA menopausal hormone therapy labeling dictates the pricing tier structure across oral, transdermal, and intrauterine delivery routes, with cardiovascular risk profile certifications enabling premium positioning. Price differentiation rests on CAP laboratory accreditation and EMA Medical Device Regulation compliance status alongside brand heritage in endocrinology. Cost compression in compounded pharmacy alternatives is intensifying because bioidentical substitution fragments adherence to evidence-based protocols. Retail pharmacy channels exhibit highest price sensitivity, while hospital formularies prioritize clinical validation over unit economics.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing concentrates in Gujarat and Maharashtra, India, and coastal provinces across China, creating chokepoint vulnerability for Western hormonal therapy brands. Raw material dependencies span synthetic estrogen precursors, progestin intermediates, and specialized polymer substrates for transdermal patches. Single-source vulnerability runs through concentrated fermentation capacity for biologic fertility treatments. Distribution feeds from contract manufacturing organizations through wholesaler networks to hospital systems and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reproductive endocrinology fellowship scarcity constrains specialty clinic expansion, creating a capability bottleneck that favors incumbents with trained specialist networks while blocking mid-tier entrants from scaling complex case volumes.
For Market Incumbents: Compound defensive moats through backward integration into CAP-certified laboratory infrastructure and captive supply of bioidentical hormone precursors. Acquire remote patient monitoring platforms before telehealth reimbursement parity fully matures, as direct-to-consumer entrants threaten traditional OB-GYN practice revenue streams through subscription-based delivery models. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for continuous glucose monitoring adaptations present the most penetrable entry point, targeting PCOS metabolic tracking where diagnostic gaps persist in United States clinics. Pursue white-space positioning in Japan's METI-supported longevity initiatives, where menopause reimbursement categories are expanding fastest among aging demographics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed reproductive device specialists struggling under EMA Medical Device Regulation compliance burdens. Long-term viability favors platforms with integrated telehealth-hormone therapy logistics and AI-powered cycle prediction capabilities. Watch FDA labeling updates on cardiovascular risk profiles as the inflection signal for therapy duration expansion and prescriber confidence recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CAP Laboratory Certification Investment | CAP-certified infrastructure secures hospital formulary placement and complex case referrals from reproductive endocrinology practices. |
| Telehealth Platform Integration | HIPAA-compliant virtual consultation bundling captures menopause management volume as state reimbursement parity laws mature. |
| EMA MDR Compliance Partnership | Cost-sharing structures with larger device manufacturers absorb extended clinical evidence timelines for intrauterine device entrants. |
| Continuous Glucose Monitoring Adaptation | PCOS metabolic tracking sensors displace intermittent blood draws in fertility clinic protocols across Germany and United States. |
| Direct-to-Consumer Subscription Launch | Automated hormone refill logistics concentrate patient data and threaten traditional pharmacy dispensing margins. |
Research Methodology
Cross-validation between reproductive endocrinology practice administrators and hospital formulary directors anchors the qualitative findings, with drug development executives and payer access specialists providing pipeline visibility. Secondary sources span FDA 510(k) filings, EMA Medical Device Regulation submissions, ClinicalTrials.gov fertility protocol registrations, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation calibrate segment-level estimates.
Sensitivity analysis across therapeutic area, delivery mode, and regional regulatory cluster dimensions shapes the analytical framework throughout the projection horizon. CAGRs derive from patent expiry schedules, biosimilar entry timelines, and telehealth adoption curves. Modeled inputs include reproductive endocrinology fellowship graduation rates, state-level reimbursement parity legislation trajectories, and METI longevity initiative funding allocations.
Decision-makers should treat outputs as directional under stable FDA labeling and EMA MDR enforcement assumptions; material deviation in active pharmaceutical ingredient export restrictions or HIPAA compliance adjudication would warrant model refresh. Practitioners should keep alternative scenarios live as bioidentical substitution rates and telehealth platform consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Women's Health Market
Women's Health
Maternal Health Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women's Digital Health Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Software Market
Women's Health
US Womens Health Market
Women's Health
Women Health Devices Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Menstrual Health Apps Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Dysfunctional Uterine Bleeding Market