
 Mother and Child Healthcare Market | 2026-2036
Mother and Child Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Mother and Child Healthcare Market Intelligence
Neonatal intensive care specifications is redrawing competitive boundaries in maternal and pediatric services. Boston Children's Hospital leverages its cardiac and neurosurgical subspecialties to anchor premium referral networks across North America. Cincinnati Children's competes through one of the largest pediatric research portfolios, translating clinical trial density into family travel demand. St. Jude Children's Research Hospital dominates pediatric oncology access by sustaining zero-billing policies that remove financial barriers to complex care.
Mother and child healthcare encompasses preventive, curative, and rehabilitative services spanning preconception through adolescence, typically delivered through multidisciplinary teams operating at gestational thresholds below 37 weeks and birth weights under 2,500 grams for high-acuity neonatal interventions. The primary purpose centers on reducing maternal mortality ratios and under-five mortality through antenatal screening, skilled birth attendance, and postnatal surveillance systems. Immunization programs within product type segments command stable procurement volumes through Gavi alliance funding and national cold chain commitments, while telehealth delivery modes expand fastest where physician density falls below WHO benchmarks of one provider per 1,000 population. Diagnostic tools concentrate margin pools in prenatal genetic screening and point-of-care hemoglobin testing for anemia detection in antenatal clinics.
FDA pregnancy labeling rules and WHO essential medicines lists jointly shape pharmaceutical formularies accessible to obstetric and pediatric populations, restricting teratogenic compounds while accelerating biosimilar approvals for maternal conditions. India's CDSCO and the EMA's pediatric investigation plans create divergent compliance pathways that fragment clinical trial enrollment strategies for multinational vaccine developers. Stakeholders must monitor how national health insurance expansion in emerging economies reconfigures reimbursement tiers between public procurement and private out-of-pocket spending for cesarean deliveries and neonatal ventilation.
Market Dynamics
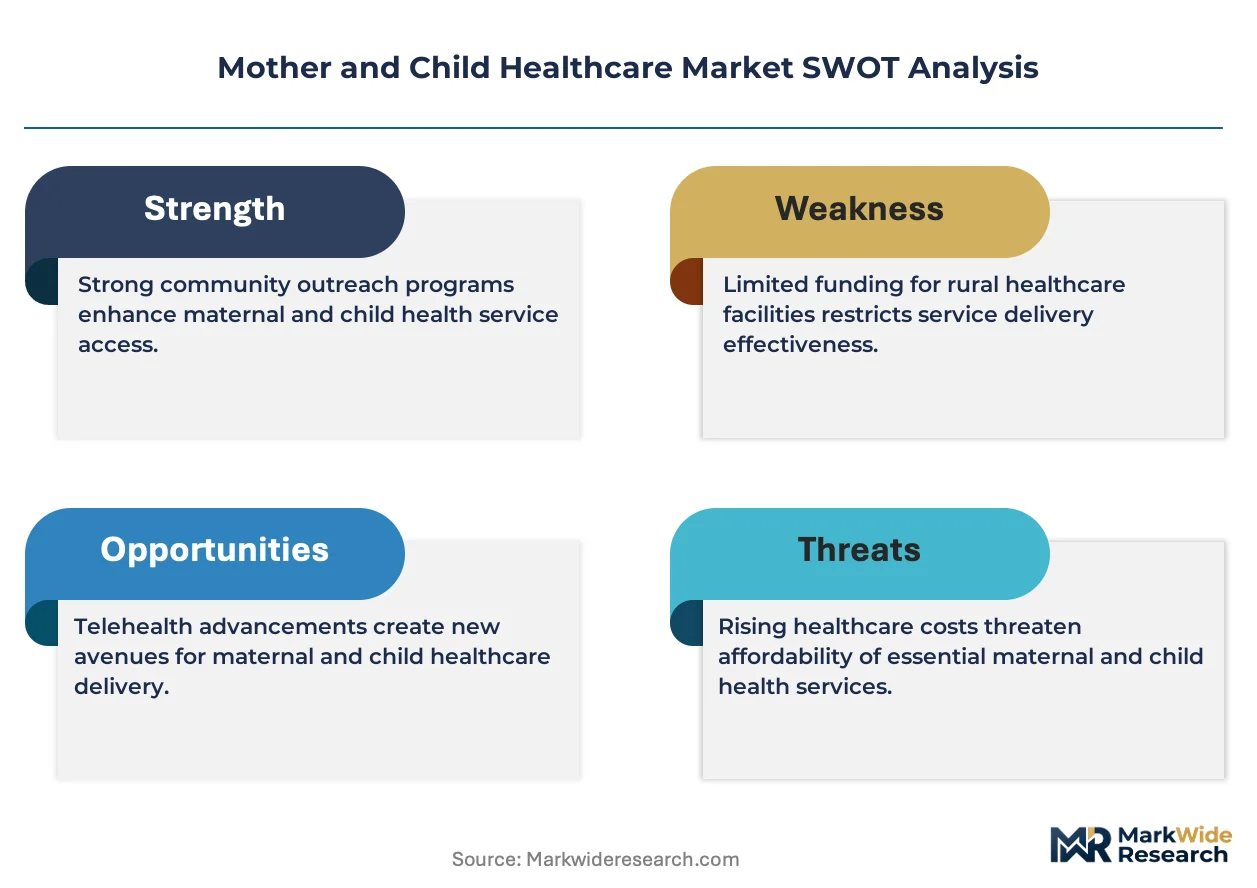
Neonatal intensive care unit specifications are compressing service delivery timelines while expanding acuity thresholds, forcing facility investments in extracorporeal membrane oxygenation capabilities and subspecialist staffing ratios that reshape capital allocation across hospital systems.
Growth Catalysts
- India's Pradhan Mantri Matru Vandana Yojana:Government maternity benefit schemes expand facility-based deliveries in tier-two cities, pulling demand from home births into institutional settings with skilled attendance.
- WHO Prequalification Standards:Tightening manufacturing compliance requirements for maternal vaccines across exporting nations accelerates quality upgrades in active pharmaceutical ingredient sourcing.
- Telehealth Infrastructure:Physician density gaps below WHO benchmarks of one provider per 1,000 population in rural sub-Saharan Africa and South Asia drive rapid adoption of remote antenatal consultation platforms.
Market Restraints
- Cold Chain Input Volatility:Vaccine distribution networks face refrigerant cost fluctuations and energy infrastructure gaps that constrain immunization program reach in tropical climates.
- Specialist Supply Concentration:Pediatric cardiac surgeons and neonatologists cluster in metropolitan academic medical centers, creating access deserts in secondary cities and rural catchment areas.
- FDA Pregnancy Labeling Friction:Restrictive teratogenic compound classifications limit pharmaceutical formularies accessible to obstetric populations, delaying therapeutic options for maternal conditions.
Strategic Opportunities
- Point-of-Care Hemoglobin Testing:Portable diagnostic devices for anemia detection in antenatal clinics address underpenetrated rural segments where laboratory infrastructure remains sparse.
- Biosimilar Acceleration Pathways:EMA pediatric investigation plans and streamlined approval frameworks create regulatory tailwinds for maternal condition therapeutics in European markets.
- Retail Pharmacy Convergence:Chain pharmacies in Brazil and Mexico integrate basic prenatal screening and nutrition counseling, capturing demand that bypasses traditional clinic channels.
Industry Challenges
- Neonatal Ventilation Technician Scarcity:Specialized respiratory therapy training programs fail to match NICU bed expansion rates, creating operational bottlenecks in high-acuity care delivery.
- EMA-FDA Trial Enrollment Divergence:Conflicting pediatric investigation plan requirements fragment multinational vaccine developer strategies, prolonging clinical timeline synchronization.
- Legacy Electronic Health Record Integration:Maternal-fetal medicine platforms struggle with interoperability against entrenched hospital information systems, complicating data continuity across prenatal-to-postnatal care episodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mother and Child Healthcare Market |
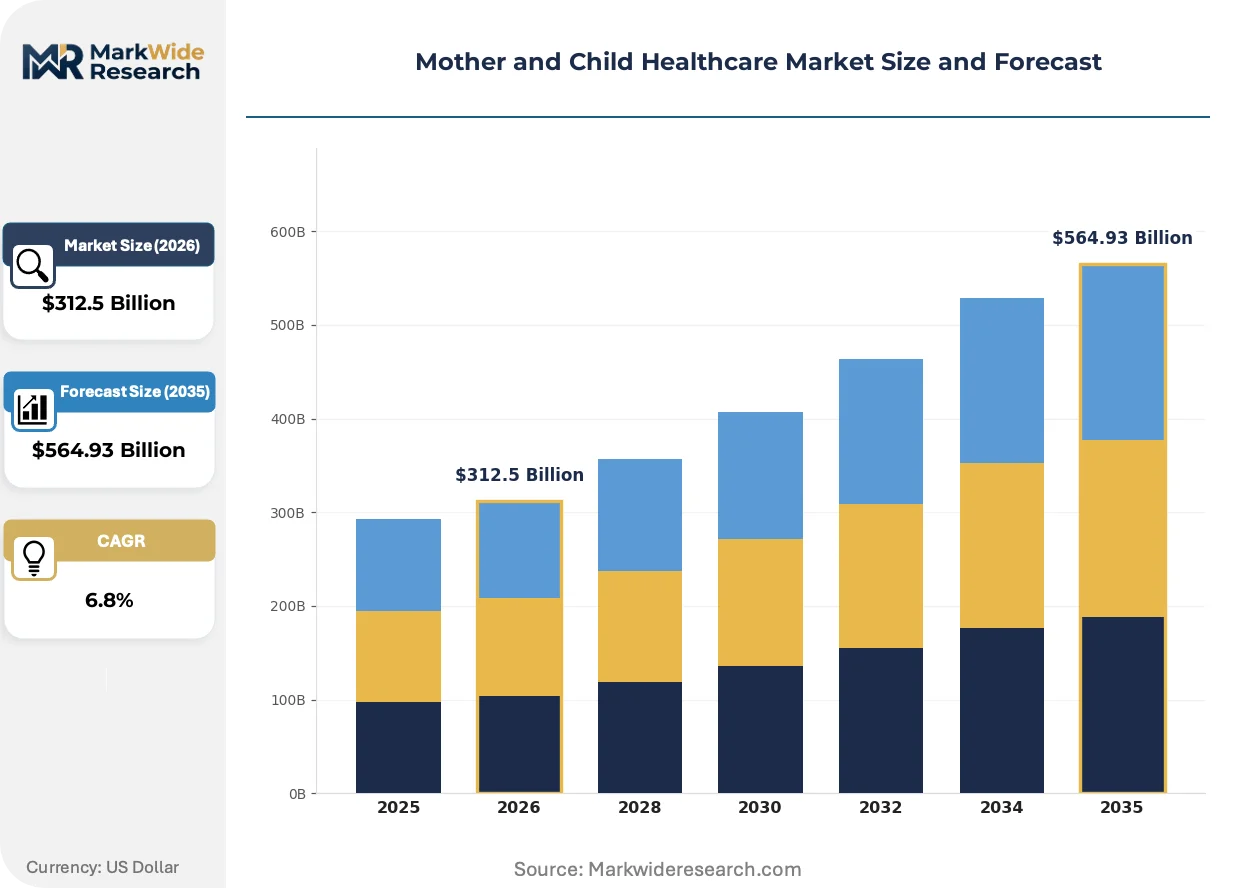
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $564.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunization, Nutritional Supplements, Diagnostic Tools, Medical Devices End User: Hospitals, Clinics, Home Care, Childcare Centers Application: Maternity Care, Pediatric Care, Neonatal Care, Family Planning Delivery Mode: Telehealth, In-person Consultation, Mobile Health, Community Outreach |
| Companies Covered | Children's Healthcare of Atlanta, Boston Children's Hospital, St. Jude Children's Research Hospital, Children's Hospital Los Angeles, Seattle Children's, Nationwide Children's Hospital, Cincinnati Children's, Nemours Children's Health, The Children's Hospital of Philadelphia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mother and Child Healthcare Market Strategic Shifts & Innovations
Diagnostic and therapeutic modalities are compressing physical footprints while expanding functional capabilities, redrawing where care delivery occurs and which provider types control patient relationships across the maternal and pediatric continuum.
Portable ultrasound devices for fetal biometry and cardiac assessment is miniaturizing from cart-based systems to handheld probes, enabling midwife-led models in Indonesian village clinics and Nigerian primary health centers to triage high-risk pregnancies without specialist proximity, compressing referral decision timelines from days to hours.
EMA's Medical Device Regulation (MDR) intensifies clinical evidence requirements for prenatal diagnostic tools and neonatal monitoring equipment, forcing manufacturers to generate post-market surveillance data that smaller device firms struggle to resource, advantaging established players with regulatory affairs infrastructure across European notified body networks.
Subscription-based prenatal care bundles in Brazilian urban markets disaggregate traditional fee-for-service obstetrics, with maternity hospitals packaging antenatal visits, delivery, and postnatal surveillance into fixed-price contracts that employers and health insurers purchase directly, shifting financial risk from patients to providers and compressing price transparency.
Mother and Child Healthcare Market Segmentation
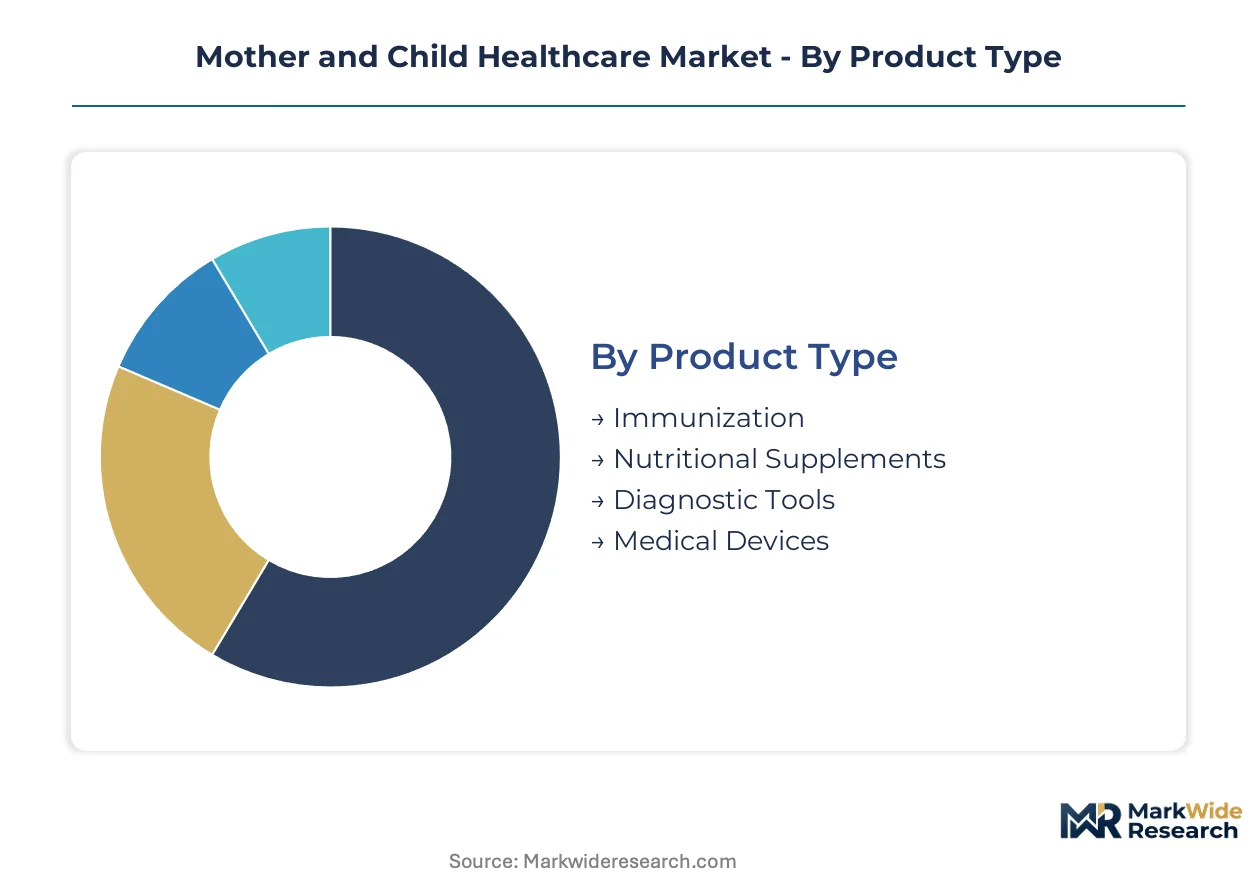
Mother and child healthcare segmentation reveals distinct margin architectures across product, service, and delivery dimensions. Understanding where value concentrates within each category enables targeted resource allocation for manufacturers and providers navigating heterogeneous demand patterns.
Product Type:
Margin pools concentrate in diagnostic tools and medical devices where technology differentiation commands premium pricing, while immunization and nutritional supplements operate on volume-driven procurement economics.
- Immunization:Vaccine portfolios span maternal tetanus-diphtheria, pediatric combination vaccines, and emerging RSV prophylaxis for infants. Gavi alliance funding stabilizes procurement volumes across sub-Saharan Africa and South Asia, though cold chain infrastructure gaps constrain last-mile distribution in tropical climates.
- Diagnostic Tools:Prenatal genetic screening platforms and point-of-care hemoglobin analyzers capture outsized margins through laboratory-substitution models. Demand clusters in Indian tier-two cities where government maternity benefit schemes expand facility-based antenatal screening.
- Nutritional Supplements:Iron-folic acid tablets, vitamin D formulations, and ready-to-use therapeutic foods address micronutrient deficiency burdens.
- Medical Devices:Neonatal incubators, phototherapy units, and portable ultrasound systems serve high-acuity interventions.
Diagnostic tools command the dominant value share, while medical devices are climbing fastest through NICU specification upgrades.
End User:
Volume throughput and acuity thresholds create divergent operational models across institutional and community settings.
- Hospitals:Tertiary referral centers concentrate pediatric cardiac surgery, neonatal ECMO capabilities, and maternal-fetal medicine subspecialties. Boston Children's Hospital and Cincinnati Children's anchor premium networks through research translation and complex intervention density.
- Clinics:Outpatient antenatal and well-child services handle routine screening, immunization administration, and low-risk delivery management.
- Home Care:Postnatal surveillance, lactation support, and chronic pediatric condition management shift care episodes beyond facility walls.
- Childcare Centers:Preventive health screenings and developmental monitoring integrate early childhood education with basic health surveillance.
Hospitals retain the largest revenue footprint, though home care is expanding most quickly through remote monitoring platform adoption.
Application:
Clinical complexity and reimbursement intensity vary sharply across the reproductive and developmental continuum.
- Maternity Care:Antenatal screening, skilled birth attendance, and postnatal surveillance target maternal mortality reduction. India's Pradhan Mantri Matru Vandana Yojana pulls demand from home births into institutional settings across tier-two cities.
- Pediatric Care:Curative and preventive services from infancy through adolescence span immunization, growth monitoring, and chronic disease management.
- Neonatal Care:Interventions for gestational thresholds below 37 weeks and birth weights under 2,500 grams require specialized ventilation, thermal regulation, and nutritional support capabilities.
- Family Planning:Contraceptive provision and reproductive health counseling complement maternal health outcomes.
Neonatal care generates the highest per-episode margins, while maternity care commands the broadest population reach.
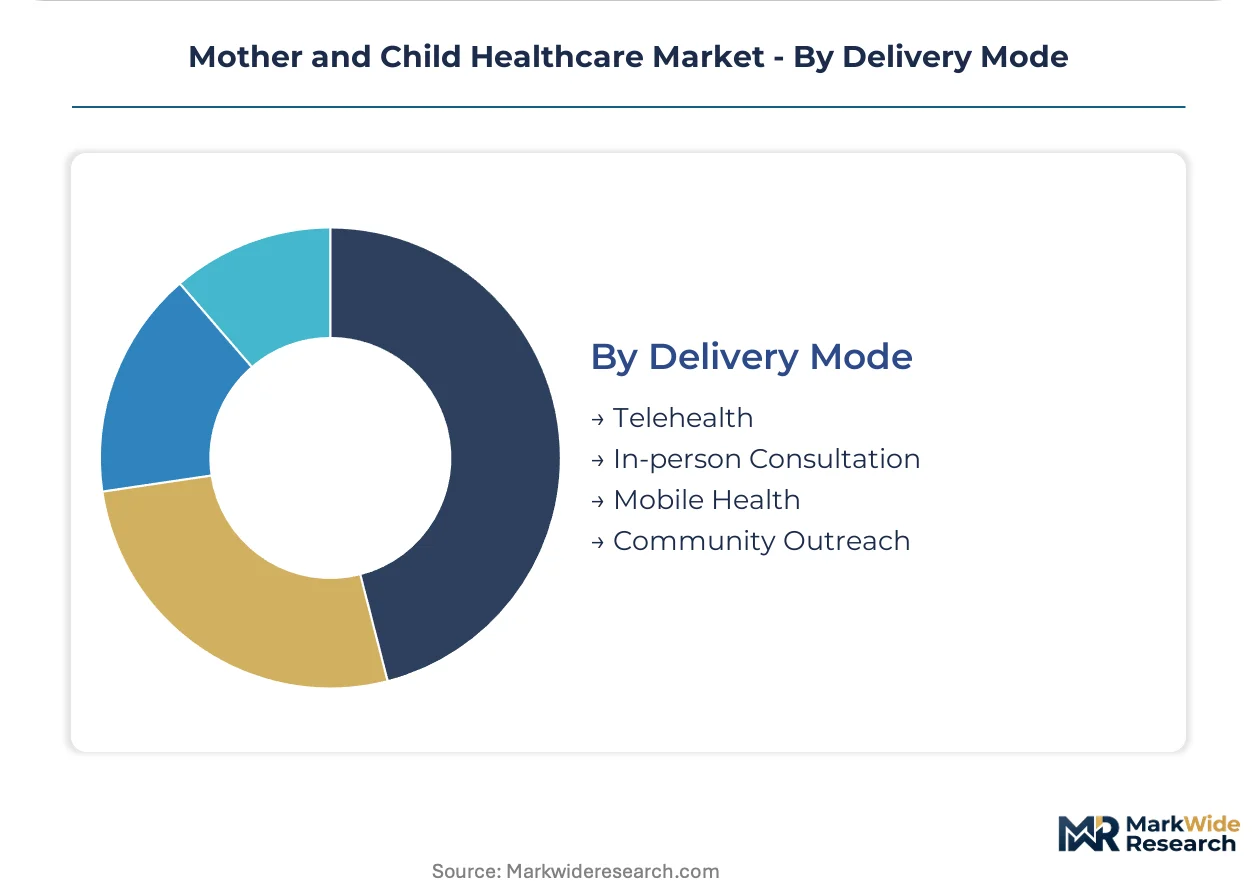
Delivery Mode:
Physical proximity requirements and technology enablement reshape where patient-provider interactions occur.
- Telehealth:Remote antenatal consultations and pediatric follow-ups address physician density gaps below WHO benchmarks of one provider per 1,000 population in rural sub-Saharan Africa and South Asia. Platform adoption accelerates where infrastructure constraints previously limited access.
- In-person Consultation:Facility-based encounters remain essential for physical examinations, procedural interventions, and high-acuity decision-making.
- Mobile Health:SMS-based appointment reminders, medication adherence prompts, and symptom triage extend reach into underserved catchments.
- Community Outreach:Health worker-led home visits and village-level screening programs bridge last-mile gaps for immunization and antenatal enrollment.
In-person consultation maintains the dominant encounter volume, though telehealth is gaining share fastest through pandemic-accelerated infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for neonatal ventilation equipment and prenatal diagnostic platforms concentrates procurement leverage in manufacturing exporters, while government maternity benefit schemes redirect domestic demand flows toward institutional delivery channels across emerging economies.
United States
Pediatric cardiac surgery and neonatal ECMO capabilities cluster in metropolitan academic medical centers, creating referral gravity for complex interventions. FDA pregnancy labeling rules restrict pharmaceutical formularies accessible to obstetric populations. Boston anchors premium networks through research translation density at specialty hospitals.
India
Facility-based deliveries surge in tier-two cities as government maternity benefit schemes expand coverage beyond metropolitan corridors. CDSCO manufacturing compliance requirements tighten for maternal vaccine exporters seeking quality upgrades. Diagnostic tool demand concentrates in Maharashtra and Gujarat where antenatal screening infrastructure scales rapidly.
Germany
EMA pediatric investigation plans and Medical Device Regulation intensify clinical evidence requirements for prenatal diagnostic manufacturers. Neonatal monitoring equipment faces post-market surveillance obligations that advantage established regulatory affairs infrastructure. Bavaria and Baden-Württemberg host precision device engineering clusters serving European procurement networks.
Brazil
Subscription-based prenatal care bundles disaggregate fee-for-service obstetrics in urban markets, shifting financial risk to providers. ANVISA regulatory pathways shape pharmaceutical formularies for maternal populations. São Paulo and Rio de Janeiro concentrate retail pharmacy convergence models integrating basic screening and nutrition counseling.
China
Domestic manufacturing scales for portable ultrasound devices and neonatal incubators serving price-sensitive procurement channels. NMPA streamlined approval frameworks accelerate biosimilar access for maternal condition therapeutics. Yangtze River Delta and Pearl River Delta clusters dominate medical device export capacity for Southeast Asian and African markets.
Mother and Child Healthcare Market Key Industry Players
Listed leaders compete with private specialists across research translation and complex intervention capabilities, creating tiered access structures where academic medical centers anchor premium referral networks while regional systems handle volume throughput. The market exhibits concentration at the ultra-specialized apex alongside fragmentation in community-based maternity services. Three archetypes dominate: research-intensive pediatric institutes, vertically integrated hospital systems, and niche subspecialty centers. Competitive moves center on ECMO capability expansion and telehealth platform licensing to extend geographic catchment without physical bed additions.
Within the research-intensive tier, Boston Children's Hospital and Cincinnati Children's exemplify institutions translating clinical trial density into family travel demand and premium network positioning. St. Jude Children's Research Hospital occupies a distinct archetype as a pediatric oncology specialist sustaining zero-billing policies that remove financial barriers to complex care access.
| Leading Market Players |
|---|
| Children's Healthcare of Atlanta |
| Boston Children's Hospital |
| St. Jude Children's Research Hospital |
| Children's Hospital Los Angeles |
| Seattle Children's |
| Nationwide Children's Hospital |
| Cincinnati Children's |
| Nemours Children's Health |
| The Children's Hospital of Philadelphia |
| Others |
Cost & Logistics Intelligence
Subscription-based prenatal care bundles in Brazilian urban markets lock in both supply access and price visibility by shifting financial risk from patients to providers through fixed-price contracts covering antenatal visits, delivery, and postnatal surveillance. This contracting pattern compresses price transparency while creating predictable demand streams for maternity hospitals and integrated health systems.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in neonatal ventilation equipment and prenatal diagnostic platforms. Price differentiation rests on FDA clearance tier and ISO 13485 certification grade, with metropolitan academic medical centers showing least price sensitivity while tier-two city hospitals in India face acute cost compression. Pricing pressure stems from government procurement mandates under India's Pradhan Mantri Matru Vandana Yojana expanding coverage into secondary cities.
Supply Chain Analysis
Strategic stockpiling of cold chain refrigerants and backup power systems dominates inventory strategy given tropical climate distribution challenges and energy infrastructure gaps. Manufacturing concentrates in China for portable ultrasound devices, Germany for precision neonatal monitoring equipment, and India for active pharmaceutical ingredients in maternal vaccines. Supply chains draw from specialized electronic components, medical-grade polymers, and temperature-controlled logistics networks. Single-source vulnerability runs through concentrated neonatologist training program capacity. Distribution feeds from manufacturer-direct hospital contracts and GPO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mother and child healthcare is approaching a platform-economics inflection where telehealth infrastructure and electronic health record interoperability determine which provider networks capture longitudinal patient relationships across prenatal-to-postnatal care episodes.
For Market Incumbents: Secure ECMO capability expansion in metropolitan academic medical centers to defend referral network gravity against pediatric specialty hospital competitors. Lock in exclusive equipment servicing contracts with tier-two city hospitals in India where government maternity benefit schemes are pulling demand from home births into institutional settings.
For New Entrants and Emerging Players: Lead with point-of-care hemoglobin testing devices targeting underpenetrated rural antenatal clinics in sub-Saharan Africa where laboratory infrastructure remains sparse. Capture demand through midwife-led distribution partnerships bypassing traditional hospital procurement channels.
For Investors and Strategic Acquirers: Capital is best deployed toward telehealth platform operators with demonstrated hospital system integration capabilities and regulatory compliance across multiple jurisdictions. Watch FDA pregnancy labeling rule revisions as inflection indicators for pharmaceutical formulary expansion opportunities in maternal therapeutics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive referral agreements with Cincinnati Children's and Boston Children's anchor premium network positioning. |
| FDA Submission | Pregnancy labeling pathway expansions unlock therapeutic options previously restricted by teratogenic compound classifications. |
| CE Marking Pathway | EMA Medical Device Regulation compliance creates European market access for prenatal diagnostic manufacturers. |
| Software Companion Development | Maternal-fetal medicine platform interoperability resolves data continuity gaps across prenatal-to-postnatal episodes. |
| Reimbursement Strategy | Gavi alliance funding stabilization secures procurement volumes for maternal vaccines across sub-Saharan Africa. |
Research Approach
Operator-level perspectives from neonatologists, hospital purchasing committee members, GPO contracts managers, and maternal-fetal medicine subspecialists anchored the qualitative base. Secondary validation drew from FDA pregnancy labeling filings, EMA pediatric investigation plans, CDSCO manufacturing compliance records, and hospital procurement databases. Bottom-up demand modeling across product type, end user, application, and delivery mode segments triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across regulatory approval timeline variations, cold chain infrastructure investment scenarios, and physician density improvement trajectories throughout the projection horizon. Segmentation dimensions modeled included product type tier, institutional versus community delivery setting, gestational acuity threshold, and regional regulatory cluster. CAGRs were derived from historical volume trajectories and elasticity-adjusted demand projections, incorporating WHO prequalification standard adoption curves and national health insurance expansion patterns as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained Gavi alliance funding commitments and stable cold chain refrigerant supply would require recalibration. Forecasts reflect documented assumptions regarding government maternity benefit scheme penetration rates and telehealth infrastructure deployment velocities. Revision becomes warranted when WHO prequalification compliance costs or FDA pregnancy labeling friction thresholds cross material impact levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Menopause Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Devices Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Menstrual Health Apps Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women Health Software Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Women's Health Market
Women's Health
Maternal Health Market
Women's Health
Women Health Care Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women's Digital Health Market
Women's Health
Dysfunctional Uterine Bleeding Market