
 Maternal Health Market | 2026-2036
Maternal Health Market Size, Share, and Industry Trends Forecast 2026-2036
Maternal Health Market Intelligence
India's generic pharmaceutical producers is pivoting toward prenatal vitamin formulations for emerging markets. Pfizer Inc. leverages its biologics pipeline to sustain maternal vaccine development across African distribution networks. Johnson & Johnson anchors consumer-facing prenatal supplement brands in Latin American retail pharmacies. Merck & Co., Inc. competes in oxytocin analog supply for institutional birthing centers.
Maternal health encompasses clinical services, diagnostic tools, nutritional interventions, and therapeutic products designed to reduce mortality and morbidity during pregnancy, childbirth, and the postpartum period, with prenatal supplements typically containing folic acid, iron, calcium, and DHA at standardized dosages. The field serves healthcare systems, government procurement programs, and direct-to-consumer channels seeking to improve birth outcomes and reduce complications. Prenatal supplements occupy the largest revenue pool due to recurring purchase patterns and over-the-counter accessibility, while fetal monitors command premium pricing in tertiary hospital settings. Telehealth services represent the fastest-expanding delivery mode as broadband infrastructure penetrates rural catchment areas.
FDA pregnancy labeling rules and WHO essential medicines lists shape product registration requirements and procurement eligibility for maternal therapeutics in regulated markets. India's CDSCO and the EU's EMA enforce varying bioequivalence standards that fragment approval timelines for prenatal generics across jurisdictions. Stakeholders must monitor reimbursement policy shifts in Brazil and Nigeria where national health insurance schemes are expanding maternity coverage parameters.
Market Dynamics
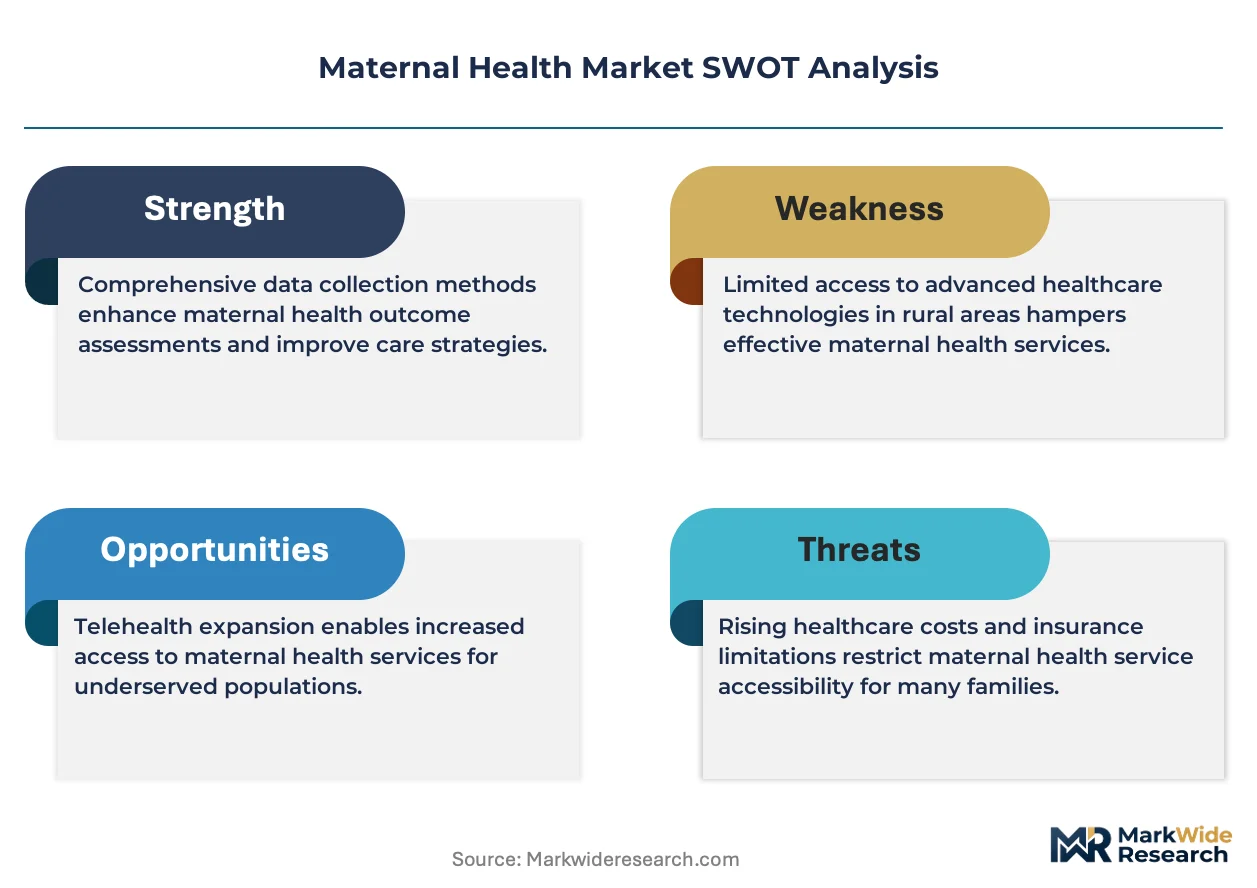
Telehealth infrastructure deployment is compressing geographic barriers to antenatal care access, forcing traditional clinic-based service models to restructure around hybrid delivery architectures that integrate remote monitoring with intermittent in-person verification.
Growth Catalysts
- WHO Antenatal Care Guidelines:Tightened quality benchmarks for visit frequency and service content are mandating expanded diagnostic capacity in public health systems across Southeast Asia and sub-Saharan Africa.
- India's Tier-2 Urbanization:Public-private maternity partnerships in cities such as Indore, Lucknow, and Coimbatore are scaling institutional birth coverage beyond metropolitan cores.
- Point-of-Care Diagnostics:Portable hemoglobin and glucose testing devices are enabling frontline health workers to triage high-risk pregnancies without laboratory infrastructure.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for oxytocin and magnesium sulfate concentrates in Chinese and Indian chemical parks, creating single-source vulnerability.
- Bioequivalence Fragmentation:India's CDSCO and the EU's EMA enforce divergent dissolution standards for prenatal generics, forcing duplicate clinical programs and extended registration timelines.
- Iron Formulation Costs:Ferrous bisglycinate and carbonyl iron variants command 3-4x raw material premiums over ferrous sulfate, compressing margin structures in mass-market supplement segments.
Strategic Opportunities
- Brazil's National Health Insurance Expansion:ANVISA reimbursement protocols for home-based fetal monitoring are creating demand for subscription-based device leasing models.
- DHA-Algae Sourcing Convergence:Fermentation-derived omega-3 is displacing fish oil in prenatal formulations, enabling vegetarian certification and supply chain traceability claims.
- Nigeria's Maternity Coverage Parameters:Federal health insurance scheme expansion into informal sector enrollment is opening prepaid care bundles for low-income urban districts.
Industry Challenges
- Ultrasound Technician Scarcity:Training pipeline gaps for certified sonographers are extending appointment wait times in rural catchment areas despite equipment availability.
- Legacy EHR Integration:Maternal health data standards (FHIR R4, ICD-10 obstetric codes) require expensive middleware development to connect proprietary telehealth platforms with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternal Health Market |
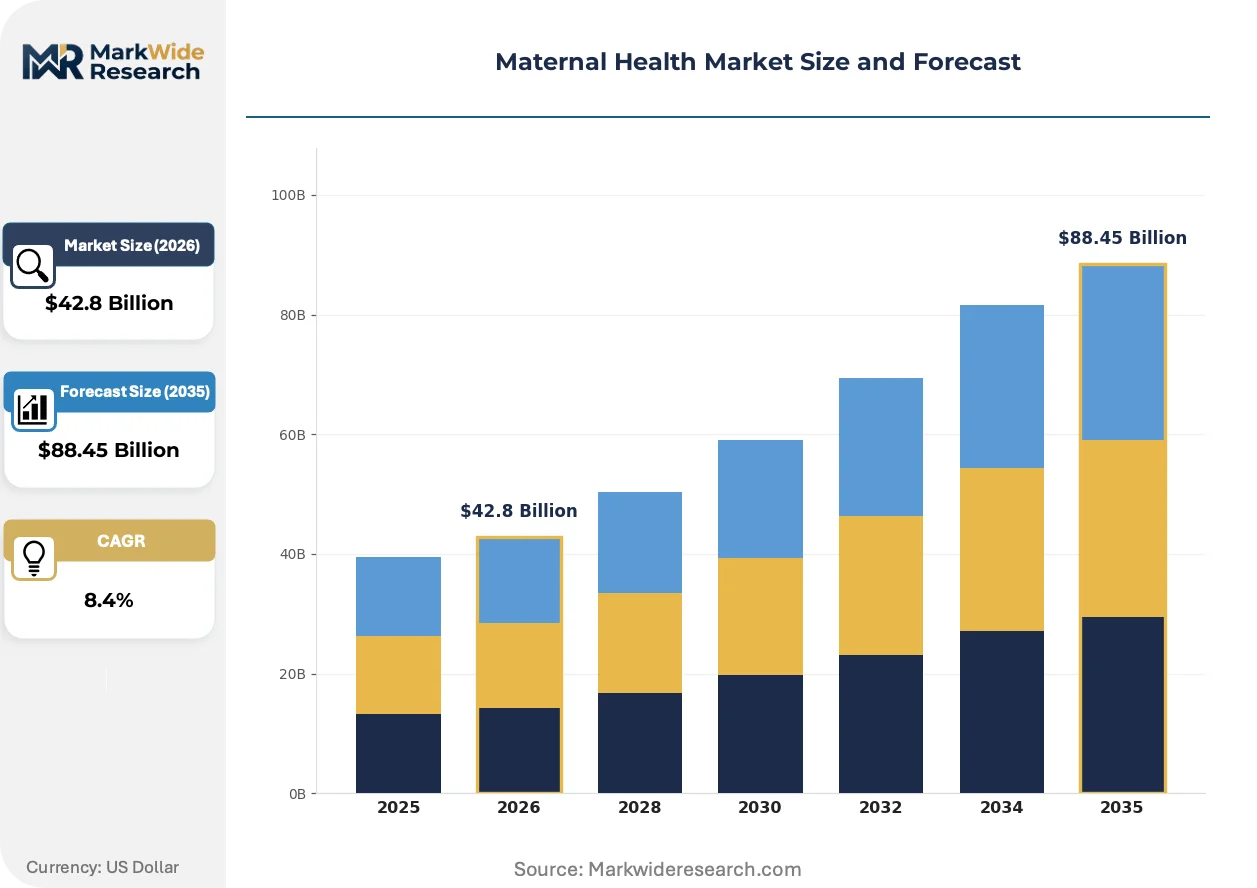
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pregnancy Tests, Prenatal Supplements, Labor Monitors, Fetal Monitors Delivery Mode: Home Birth, Hospital Birth, Birthing Centers, Telehealth Services End User: Expectant Mothers, Healthcare Providers, Midwives, Obstetricians Application: Routine Checkups, Complications Monitoring, Nutritional Support, Postpartum Care |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline, Bayer AG, GE Healthcare, Philips Healthcare, Abbott Laboratories, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternal Health Market Strategic Shifts & Innovations
Digital biomarker collection and algorithmic risk stratification are displacing scheduled visit protocols with continuous surveillance models that trigger intervention based on real-time physiologic deviation rather than calendar-based screening.
Continuous glucose monitoring patches adapted for gestational diabetes management are consolidating metabolic surveillance into wearable form factors that transmit data directly to obstetric care teams. Tertiary hospital systems in South Korea and Australia are deploying these devices for high-risk pregnancy cohorts, reducing in-clinic monitoring visits by half while maintaining glycemic control targets. The technology is consolidating fragmented point-of-care testing into unified data streams that enable predictive rather than reactive insulin management.
The EU's Medical Device Regulation (MDR) is reclassifying fetal heart rate monitors and contraction tocodynamometers from Class IIa to Class IIb, triggering notified body involvement and clinical evidence requirements that smaller manufacturers cannot satisfy. European distributors are dropping non-compliant product lines, concentrating shelf space among legacy manufacturers with established technical documentation. Home-use Doppler devices face particular scrutiny as MDR Annex XVI extends coverage to products with aesthetic or wellness claims that imply medical purpose.
Subscription-based prenatal vitamin delivery is displacing pharmacy-centric purchasing in direct-to-consumer channels, with algorithmic replenishment tied to gestational age rather than household inventory depletion. Urban millennial cohorts in the United States and United Kingdom are driving this shift, prioritizing convenience and dosage personalization over immediate retail availability. The model is compressing brand loyalty windows as switching costs diminish and trial-size sampling integrates with telehealth onboarding flows.
Maternal Health Market Segmentation
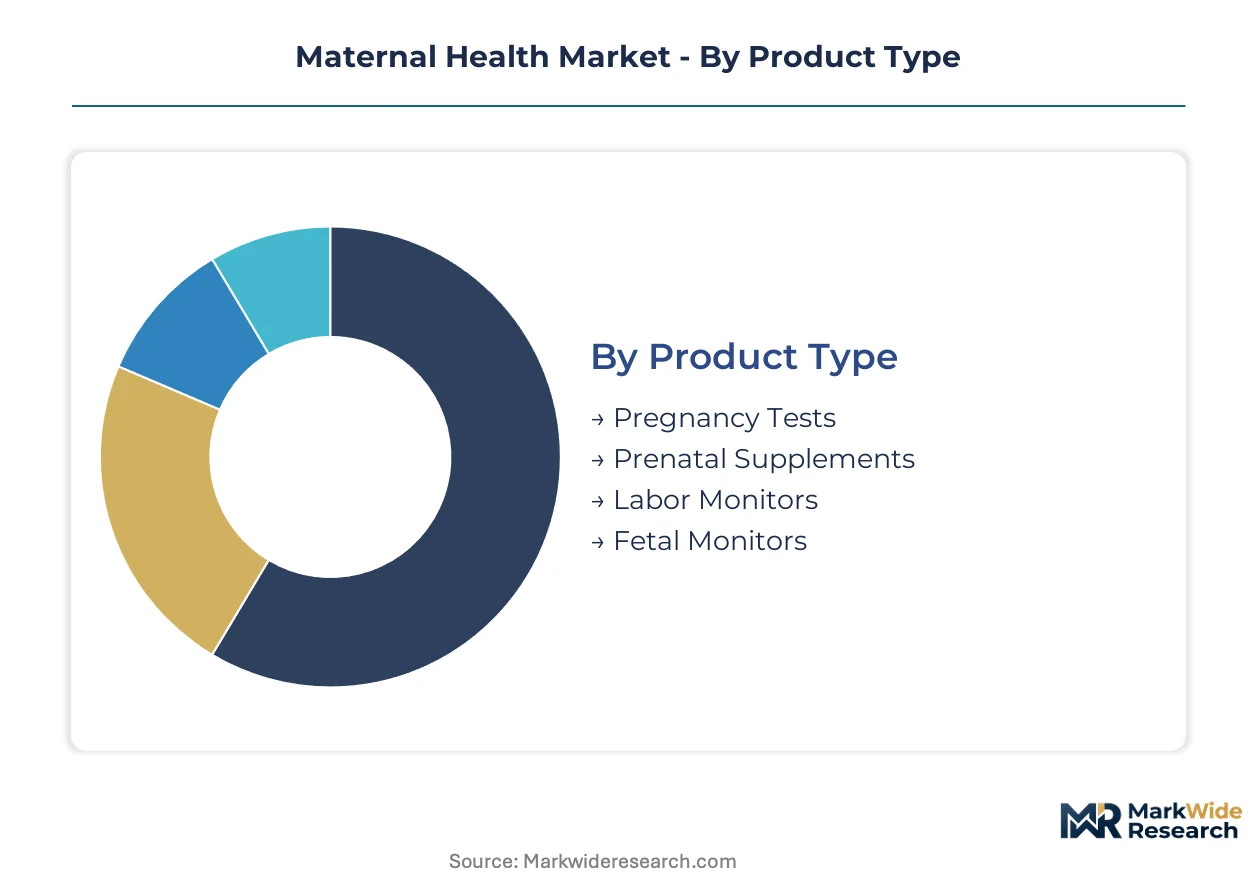
Segmentation in maternal health reveals how supply chains, reimbursement pathways, and clinical workflows diverge across product categories and care settings. Understanding these divisions exposes where margin pools concentrate and where new entrants can bypass entrenched distribution.
Product Type:
Supply concentration in active pharmaceutical ingredients and diagnostic sensor manufacturing creates divergent margin structures across product categories.
- Prenatal Supplements:Formulations containing folic acid, iron, calcium, and DHA dominate recurring revenue streams due to over-the-counter accessibility and gestational-age dosing protocols. India's generic pharmaceutical producers are pivoting capacity toward these formulations as hospital procurement in tier-2 cities scales.
- Fetal Monitors:Cardiotocography and Doppler systems command premium pricing in tertiary hospital settings, with the EU's MDR reclassification from Class IIa to Class IIb triggering notified body involvement that smaller manufacturers cannot satisfy. South Korean and Australian hospital systems are deploying these for high-risk pregnancy cohorts.
- Pregnancy Tests:Lateral flow immunoassay devices saturate retail pharmacy channels with thin margins, though digital result interpretation apps are creating subscription attach opportunities.
- Labor Monitors:Uterine contraction tocodynamometers and cervical dilation sensors concentrate in institutional birthing centers, with ANVISA reimbursement protocols in Brazil enabling home-based device leasing models.
Today's leader: Prenatal Supplements. Tomorrow's challenger: Fetal Monitors.
Delivery Mode:
Cost tier differentiation separates capital-intensive institutional infrastructure from lean, technology-enabled distributed models.
- Telehealth Services:Broadband penetration into rural catchment areas is compressing geographic barriers, forcing hybrid architectures that integrate remote monitoring with intermittent in-person verification. Continuous glucose monitoring patches for gestational diabetes management are consolidating metabolic surveillance into wearable form factors.
- Hospital Birth:Institutional capacity expansion across Southeast Asia concentrates diagnostic equipment procurement and specialist labor pools, with WHO antenatal care guidelines mandating expanded visit frequency.
- Birthing Centers:Midwife-led facilities in Latin American retail pharmacy corridors emphasize low-intervention delivery, though oxytocin analog supply constraints from API concentration in Chinese chemical parks create vulnerability.
- Home Birth:Direct-to-consumer prenatal vitamin subscription models and portable Doppler devices serve urban millennial cohorts in the United States and United Kingdom, with algorithmic replenishment tied to gestational age.
Telehealth Services are gaining share fastest as infrastructure deployment outpaces physical facility construction.
End User:
Customer type determines purchasing authority, with procurement patterns diverging between institutional reimbursement and direct out-of-pocket expenditure.
- Healthcare Providers:Hospital systems and clinic networks drive volume procurement of fetal monitors and labor equipment, with India's public-private maternity partnerships scaling institutional birth coverage.
- Expectant Mothers:Direct purchasing concentrates in prenatal supplements and home-use diagnostic devices, with Nigeria's federal health insurance scheme expansion into informal sector enrollment opening prepaid care bundles.
- Obstetricians:Specialist-led practices in tertiary settings command premium pricing for complications monitoring and high-risk pregnancy management.
- Midwives:Frontline health workers in sub-Saharan Africa utilize portable hemoglobin and glucose testing devices to triage high-risk pregnancies without laboratory infrastructure.
Healthcare Providers anchor current procurement volume. Expectant Mothers represent the steepest expansion trajectory as direct-to-consumer channels mature.
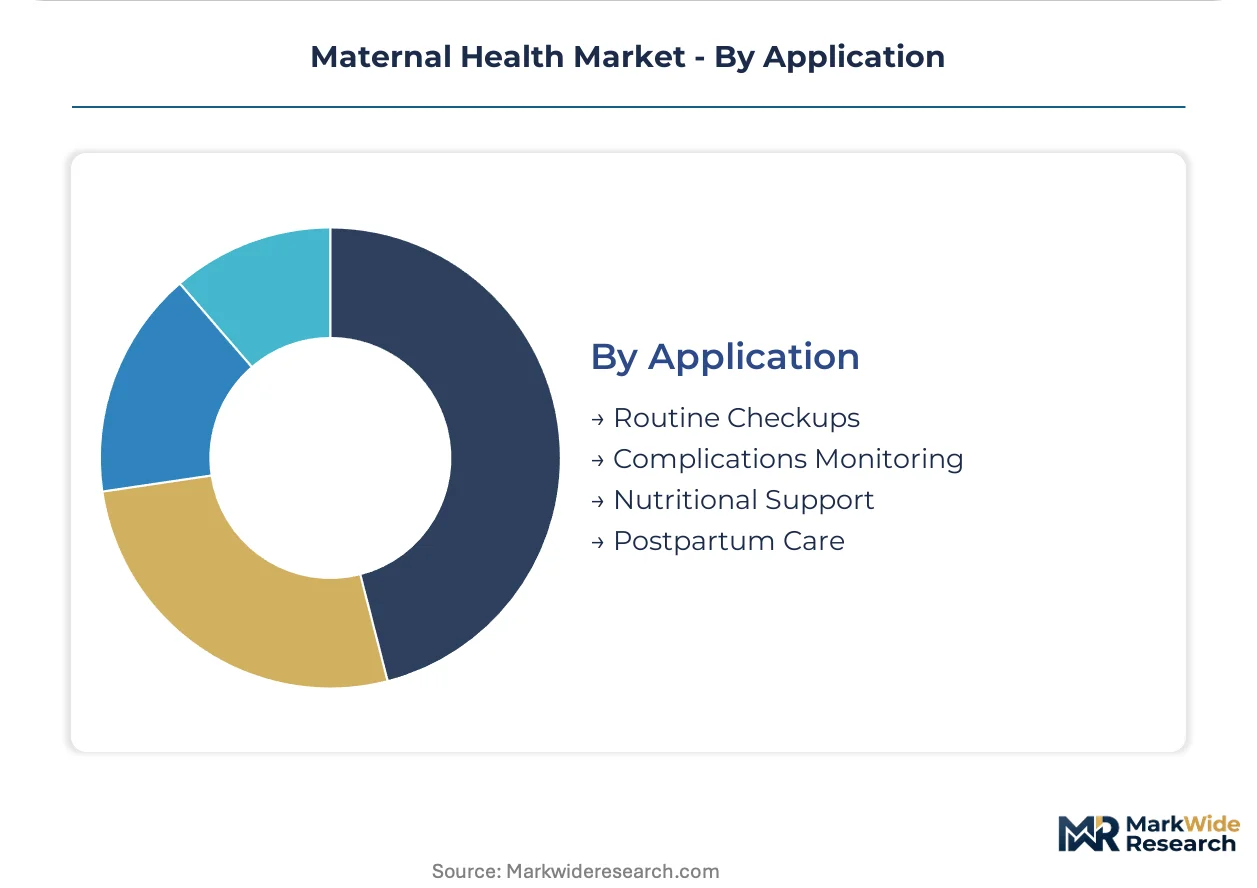
Application:
Maturity gradients separate established routine care protocols from emerging technology-enabled surveillance models.
- Routine Checkups:Scheduled visit protocols face displacement as digital biomarker collection and algorithmic risk stratification enable continuous surveillance models triggering intervention based on real-time physiologic deviation.
- Complications Monitoring:Gestational diabetes and preeclampsia surveillance is consolidating into unified data streams that enable predictive rather than reactive management, with tertiary systems in South Korea and Australia reducing in-clinic visits by half.
- Nutritional Support:Iron, folate, and DHA supplementation programs concentrate in government procurement channels, though DHA-algae fermentation is displacing fish oil to enable vegetarian certification claims.
- Postpartum Care:Depression screening and lactation support services remain underdeveloped relative to antenatal investment, creating whitespace for integrated care bundles.
Routine Checkups retain institutional anchoring. Complications Monitoring is climbing the fastest as wearable form factors mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing maternal health manufacturing capacity toward jurisdictions with streamlined bioequivalence pathways, while demand clusters concentrate where national insurance schemes are expanding maternity coverage parameters.
United States
FDA pregnancy labeling rules and HIPAA-compliant telehealth platforms are accelerating hybrid care model adoption. The FDA's tightened REMS protocols for oxytocin products are reshaping institutional procurement standards. Hospital systems in Texas and Florida are deploying continuous glucose monitoring patches for gestational diabetes management at scale.
India
CDSCO's divergent dissolution standards for prenatal generics are forcing duplicate clinical programs that extend registration timelines. The country's PLI scheme for pharmaceutical manufacturing is incentivizing domestic API production for iron and folate formulations. Tier-2 cities including Indore, Lucknow, and Coimbatore are scaling public-private maternity partnerships beyond metropolitan cores.
Brazil
ANVISA reimbursement protocols for home-based fetal monitoring are creating demand for subscription-based device leasing models. The national health insurance expansion is widening maternity coverage parameters for informal sector enrollment. São Paulo's hospital networks are consolidating diagnostic equipment procurement under centralized purchasing agreements.
Germany
The EU's Medical Device Regulation reclassification of fetal monitors from Class IIa to Class IIb is triggering notified body involvement that smaller manufacturers cannot satisfy. EMA bioequivalence standards for prenatal generics are fragmenting approval timelines across member states. Bavaria's tertiary hospital systems are deploying algorithmic risk stratification for high-risk pregnancy cohorts.
Nigeria
Federal health insurance scheme expansion into informal sector enrollment is opening prepaid care bundles for low-income urban districts. The country's national pharmaceutical regulator is tightening import quality benchmarks for magnesium sulfate and oxytocin analogs. Lagos and Abuja are concentrating point-of-care diagnostic deployment for frontline health worker triage capabilities.
Maternal Health Market Key Industry Players
Indian generic producers anchor the volume tier for prenatal supplement formulations; European and American specialists hold premium positions in fetal monitoring and biologics development. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with biologics pipelines, regional generic manufacturers with API backward integration, and emerging telehealth platform operators with algorithmic care coordination. Consolidation pressure is intensifying through strategic partnerships between device manufacturers and digital health platforms, alongside capacity expansion in Indian chemical parks for iron and DHA-algae fermentation inputs.
Within the multinational pharmaceutical tier, Johnson & Johnson and Pfizer Inc. occupy positions exemplifying divergent strategic archetypes—consumer-facing prenatal supplement brands versus biologics-driven maternal vaccine development. Merck & Co., Inc. represents the institutional therapeutics specialist archetype, with its positioning in oxytocin analog supply chains for birthing centers. These three anchors illustrate how competitive positioning fragments across consumer retail, institutional procurement, and vaccine development vectors without unified market dominance.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline |
| Bayer AG |
| GE Healthcare |
| Philips Healthcare |
| Abbott Laboratories |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Premium-commodity bifurcation between biologics-driven maternal vaccines and mass-market prenatal generics manifests in divergent margin structures and sourcing configurations. WHO essential medicines list eligibility anchors institutional procurement pricing for oxytocin analogs and magnesium sulfate, while direct-to-consumer supplement channels absorb 3-4x raw material premiums for ferrous bisglycinate formulations.
Pricing Analysis
Distributor margin layers compress as public procurement programs in Nigeria and Brazil consolidate volume purchasing under national health insurance schemes. Three-tier pricing structure across premium biologics, standard institutional therapeutics, and economy generic supplements separates reimbursement-eligible formulations from out-of-pocket retail purchases. Pricing pressure stems from iron formulation cost inflation and DHA-algae fermentation scale-up investments. Government procurement officers exhibit highest price sensitivity, while direct-to-consumer urban millennials prioritize convenience premiums over unit economics.
Supply Chain Analysis
Returns and refurbishment flows remain minimal for single-use prenatal supplements, though fetal monitor leasing models in Brazil's home-based care programs create reverse logistics infrastructure for device redeployment. Active pharmaceutical ingredient production concentrates in Indian and Chinese chemical parks, with oxytocin and magnesium sulfate synthesis drawing from concentrated fermentation and chemical processing inputs. Single-source vulnerability in Chinese heparin precursor supply creates structural risk for anticoagulant-dependent maternal interventions. Distribution runs through hospital procurement consortia in Southeast Asia, direct-to-consumer subscription platforms in North America, and retail pharmacy chains in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's tier-2 city expansion, where CDSCO regulatory timelines lag EMA standards by 18-24 months but manufacturing cost structures undercut European production by 40-60%.
For Market Incumbents: Lock in API backward integration for iron and DHA-algae fermentation inputs before PLI scheme subsidies expire. Secure WHO prequalification status for oxytocin analogs to defend institutional procurement eligibility against emerging Indian generic challengers. Prioritize certification investment for EU MDR Class IIb fetal monitor compliance to exploit smaller manufacturer exit from European distribution channels. For New Entrants and Emerging Players: Rural midwife networks in sub-Saharan Africa represent the most penetrable buyer archetype for portable hemoglobin and glucose testing devices. Nigeria's informal sector enrollment expansion creates whitespace for prepaid maternity care bundles in Lagos and Abuja urban districts. Partner with telehealth platform operators to bypass entrenched hospital procurement gatekeepers and establish direct-to-patient onboarding flows. For Investors and Strategic Acquirers: Asymmetric upside sits with telehealth platform operators possessing algorithmic risk stratification capabilities and existing broadband infrastructure partnerships. Five-to-ten year viability hinges on reimbursement policy convergence across Brazil, Nigeria, and India national health insurance schemes. Monitor ANVISA home-based fetal monitoring reimbursement protocol adoption rates as inflection indicator for subscription-based device leasing model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks institutional procurement eligibility across Southeast Asian and sub-Saharan African public health systems. |
| EU MDR Class IIb Certification | Concentrates fetal monitor shelf space among legacy manufacturers with established technical documentation. |
| DHA-Algae Fermentation Scale-Up | Enables vegetarian certification claims and supply chain traceability for premium prenatal formulations. |
| Telehealth Platform Integration | Compresses geographic barriers to antenatal care access through hybrid delivery architectures. |
| India Tier-2 City Partnership | Scales institutional birth coverage beyond metropolitan cores through public-private maternity collaborations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with obstetric care clinicians, hospital procurement committee members, pharmaceutical regulatory affairs leads, and telehealth platform engineers with secondary validation against FDA pregnancy labeling filings, CDSCO approval databases, WHO essential medicines list revisions, and national health insurance scheme expansion announcements. Bottom-up patient population modeling and top-down healthcare expenditure triangulation anchored volume and value estimates.
Segment-weighting approaches distributed analytical emphasis across product type, delivery mode, and end user dimensions, with additional calibration for gestational-age-specific dosing protocols and regional regulatory cluster heterogeneity. CAGRs derived from longitudinal procurement data series and infrastructure deployment trajectories across the projection horizon. Fetal monitor reclassification timelines and broadband penetration curves served as maternal health-specific forecast inputs.
Underlying measurement precision varies by segment; telehealth services and direct-to-consumer supplement channels carry tighter precision than institutional birthing center equipment procurement due to data transparency differentials. Forecasts reflect assumptions regarding WHO guideline adoption rates, national insurance scheme enrollment trajectories, and API supply chain stability that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Women Health Software Market
Women's Health
Women's Digital Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women's Health App Market
Women's Health
Menopause Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Care Market
Women's Health
Women Health Devices Market
Women's Health
Women's Health Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Disease Diagnosis and Treatment Market