
 North America Womens Health Diagnostics Market | 2026-2036
North America Womens Health Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Womens Health Diagnostics Market Analytics
Consolidation among hospital purchasing networks is restructuring vendor relationships across the North America Womens Health Diagnostics Market. Large integrated delivery networks now command centralized contracting for imaging and laboratory services, pressuring standalone diagnostic manufacturers. Quest Diagnostics Incorporated leverages its national laboratory footprint to sustain high-throughput processing contracts with these consolidated buyers. Hologic, Inc. anchors its position through dedicated breast health and cervical cancer screening platforms that dominate hospital capital equipment budgets. Abbott competes in point-of-care fertility and hormonal testing through compact instrument systems designed for clinic deployment.
Women's health diagnostics encompasses clinical assays, imaging modalities, and biomarker platforms engineered to detect, monitor, and predict conditions specific to female physiology, including reproductive system cancers, endocrine disorders, and pregnancy-related complications. These technologies typically operate with analytical sensitivity thresholds measured in picograms per milliliter for immunoassays and spatial resolution below one millimeter for advanced ultrasound applications, serving primarily to enable earlier therapeutic intervention and reduce mortality from gynecological malignancies. In-vitro diagnostics and molecular testing together capture the dominant share of revenue growth, driven by expanded reimbursement for liquid biopsy and next-generation sequencing panels in ovarian and breast cancer surveillance. Cancer screening applications command premium pricing relative to hormonal assessments, while diagnostic laboratories represent the most concentrated end-user channel for high-complexity molecular workflows.
FDA premarket notification and premarket approval pathways govern commercial entry for novel diagnostics in the United States, while Health Canada issues medical device licenses under the Medical Devices Regulations for northern market access. CLIA certification requirements for high-complexity testing create structural barriers that favor established laboratory operators with existing quality management infrastructure. Stakeholders must monitor evolving CMS coverage determination processes for multi-cancer early detection assays, as national reimbursement decisions will reshape investment priorities across the development pipeline.
Market Dynamics
Hospital purchasing network consolidation across the United States and Canada is compressing vendor margins and forcing diagnostic manufacturers to restructure commercial strategies around centralized procurement contracts rather than individual facility relationships.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for multi-cancer early detection assays are pulling liquid biopsy technologies into routine ovarian and breast cancer surveillance protocols.
- Integrated delivery networks:Large hospital systems in Texas and California are consolidating laboratory procurement, creating volume concentration that rewards high-throughput diagnostic processors.
- Next-generation sequencing:NGS panel adoption for hereditary cancer screening is accelerating as CLIA-certified laboratories scale automated molecular workflows.
Market Restraints
- CLIA certification barriers:High-complexity testing requirements favor established laboratory operators with existing quality infrastructure, blocking new entrants.
- FDA premarket timelines:Novel biomarker assays face extended review cycles under premarket approval pathways, delaying commercialization revenue.
- Reagent supply concentration:Critical assay components for molecular diagnostics originate from limited North American suppliers, exposing production to single-source risk.
Strategic Opportunities
- Point-of-care fertility testing:Compact hormonal assay systems for clinic deployment remain underpenetrated in Canadian provincial healthcare networks.
- AI-augmented imaging:Machine learning integration with ultrasound and mammography platforms is creating new reimbursement categories for radiology practices.
- Value-based care contracts:Ontario and British Columbia health authorities are piloting outcome-linked diagnostic procurement that rewards early detection performance.
Industry Challenges
- Molecular pathology workforce scarcity:Certified laboratory directors with NGS interpretation expertise command premium compensation, constraining test volume expansion.
- Legacy LIS integration:Hospital information systems require costly middleware development to connect new diagnostic instruments with existing electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Womens Health Diagnostics Market |
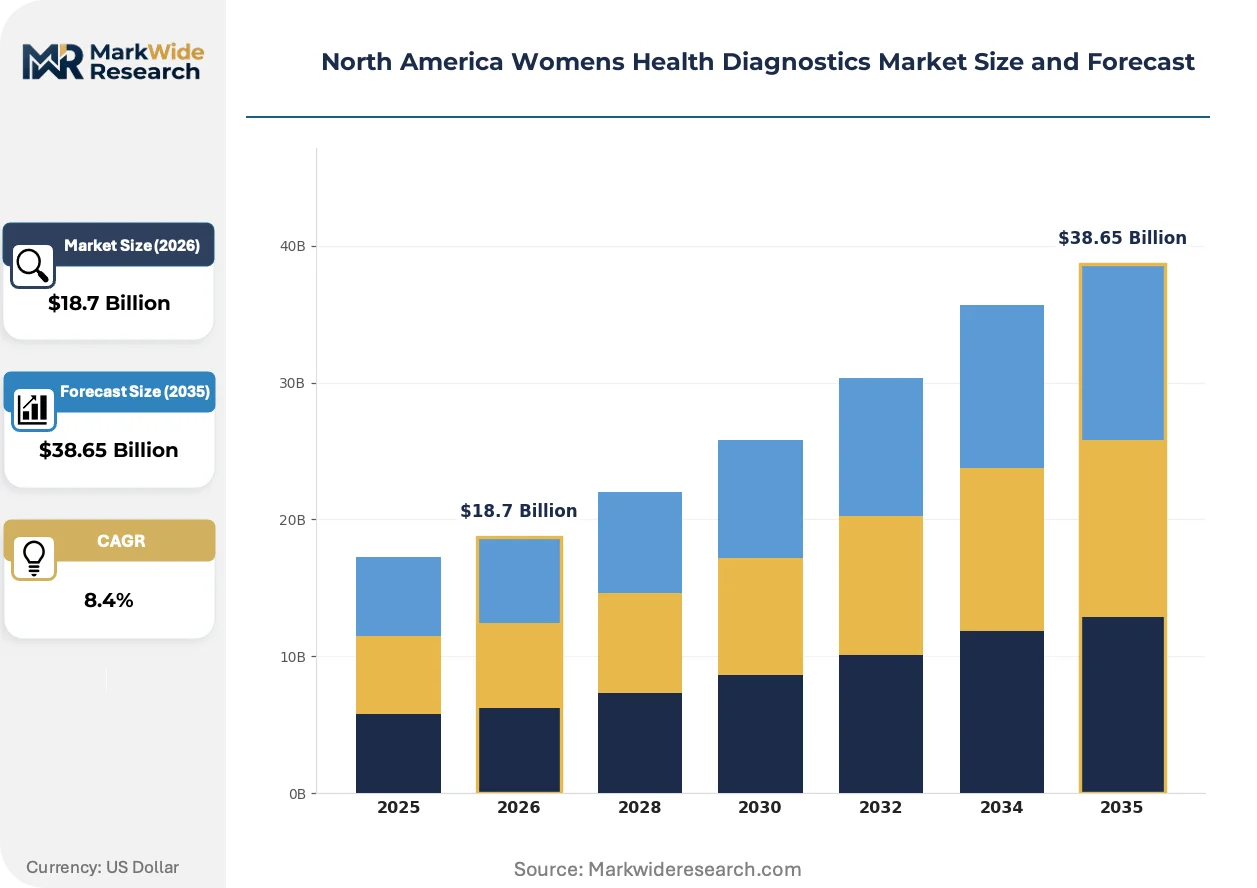
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Vitro Diagnostics, Imaging Systems, Point-of-Care Devices, Biomarkers Application: Gynecological Disorders, Fertility Testing, Hormonal Assessments, Cancer Screening End User: Clinics, Hospitals, Homecare Settings, Diagnostic Laboratories Technology: Molecular Testing, Immunoassays, Ultrasound, Genetic Testing |
| Companies Covered | Quest Diagnostics Incorporated, Hologic, Inc., Abbott, BD, GE Healthcare, Thermo Fisher Scientific Inc., Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Womens Health Diagnostics Market Evolving Landscape
Digital pathology and artificial intelligence are converging to reshape how cervical and breast cancer screening workflows operate, compressing turnaround times while raising analytical throughput requirements for clinical laboratories.
Liquid biopsy platforms are automating circulating tumor DNA isolation and analysis, enabling continuous monitoring without tissue biopsy. Community oncology practices in Florida and Arizona are adopting these systems to retain patients who would otherwise transfer to academic medical centers. The technology is automating sample-to-answer workflows that previously required manual molecular biology expertise.
Health Canada's Medical Devices Regulations are tightening software-as-a-medical-device classification for AI-enabled diagnostic algorithms, requiring clinical validation studies for algorithms that influence treatment decisions. Manufacturers must submit algorithm change control protocols that document performance drift monitoring. Breast imaging AI tools face heightened scrutiny under this framework, with several products delayed pending supplementary clinical evidence.
Direct-to-consumer genetic testing is fragmenting traditional referral pathways for hereditary cancer screening, with patients arriving at oncology consultations already possessing BRCA panel results. This pattern concentrates in metropolitan California and New York markets where consumer genomics penetration is highest. Physician groups are responding by integrating pre-test counseling into telehealth workflows to manage inappropriate testing demand.
North America Womens Health Diagnostics Market Segmentation
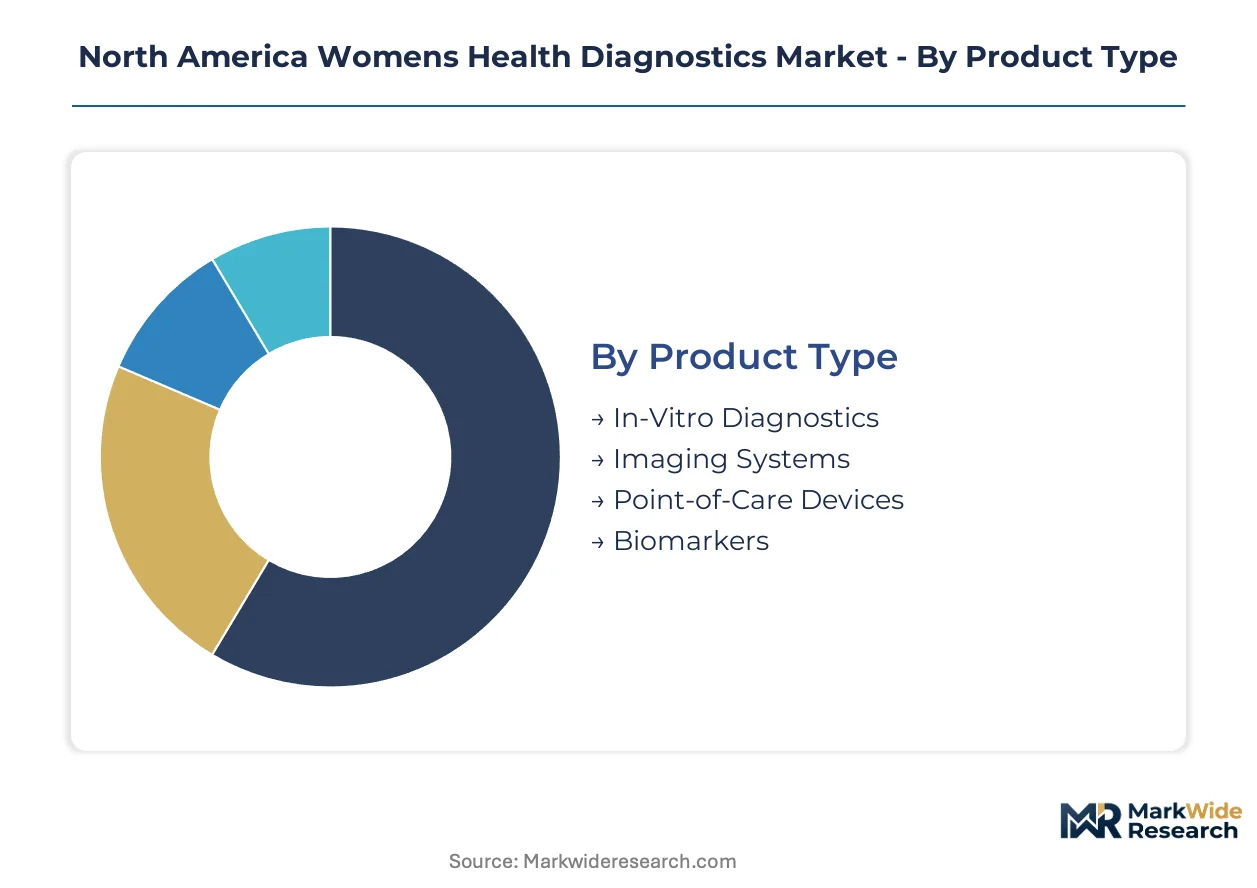
Diagnostic manufacturers allocate capital differently across product architectures, with molecular platforms demanding substantial upfront laboratory infrastructure while point-of-care devices prioritize miniaturization engineering. Understanding these investment profiles clarifies why certain segments consolidate under hospital networks while others fragment across independent clinics.
Product Type:
Capital intensity varies sharply across diagnostic modalities, with imaging systems requiring the heaviest manufacturing and service infrastructure while biomarker reagents scale through chemistry optimization.
- In-Vitro Diagnostics:Encompasses automated analyzers and reagent kits processing blood, urine, and tissue specimens in centralized laboratories. Demand concentrates in Texas and California diagnostic laboratory hubs where high-throughput processing contracts with consolidated hospital networks drive volume. CLIA certification requirements favor established operators with existing quality management infrastructure.
- Imaging Systems:Mammography, ultrasound, and MRI platforms engineered for breast and pelvic anatomical visualization. Hospital systems in Ontario and British Columbia anchor procurement through centralized capital equipment budgets, though AI-augmented software modules are creating new reimbursement categories that alter total cost of ownership calculations.
- Point-of-Care Devices:Compact hormonal and fertility assay systems designed for clinic deployment without laboratory infrastructure.
- Biomarkers:Circulating protein, nucleic acid, and metabolite indicators measured through immunoassay or mass spectrometry methods.
In-Vitro Diagnostics absorbs the bulk of installed capacity; Point-of-Care Devices is expanding most quickly.
Application:
Clinical utility and reimbursement depth determine which applications command premium pricing versus commodity positioning across United States and Canadian healthcare systems.
- Cancer Screening:Ovarian, breast, and cervical malignancy detection through imaging, molecular, and cytological methods. Medicare coverage determinations for multi-cancer early detection assays are pulling liquid biopsy technologies into routine surveillance protocols, with Florida and Arizona community oncology practices adopting automated sample-to-answer workflows.
- Fertility Testing:Ovarian reserve assessment, ovulation prediction, and semen analysis supporting assisted reproduction decisions. Canadian provincial healthcare networks remain underpenetrated for clinic-based hormonal testing, creating structural whitespace for compact instrument systems.
- Hormonal Assessments:Thyroid, reproductive, and metabolic endocrine profiling through serum or saliva specimens.
- Gynecological Disorders:Infection, endometriosis, and pelvic inflammatory disease diagnostics.
Cancer Screening commands the steepest pricing tier; Fertility Testing is climbing the fastest as delayed family planning expands addressable demand.
End User:
Procurement authority and testing complexity requirements segment the customer base into concentrated buyers versus distributed decision-makers.
- Diagnostic Laboratories:CLIA-certified facilities processing high-complexity molecular and cytogenetic workflows. Quest Diagnostics Incorporated sustains national contracts through automated NGS panel scaling, with molecular pathology workforce scarcity constraining test volume expansion across the sector.
- Hospitals:Integrated delivery networks consolidating imaging and laboratory procurement through centralized contracting. Large systems in Texas and California command volume concentration that rewards high-throughput processors and pressures standalone manufacturers.
- Clinics:Physician offices and ambulatory surgical centers requiring moderate-complexity testing capabilities.
- Homecare Settings:Direct-to-consumer and remote patient monitoring applications.
Diagnostic Laboratories capture the highest test complexity; Clinics are gaining share fastest as point-of-care capabilities expand.
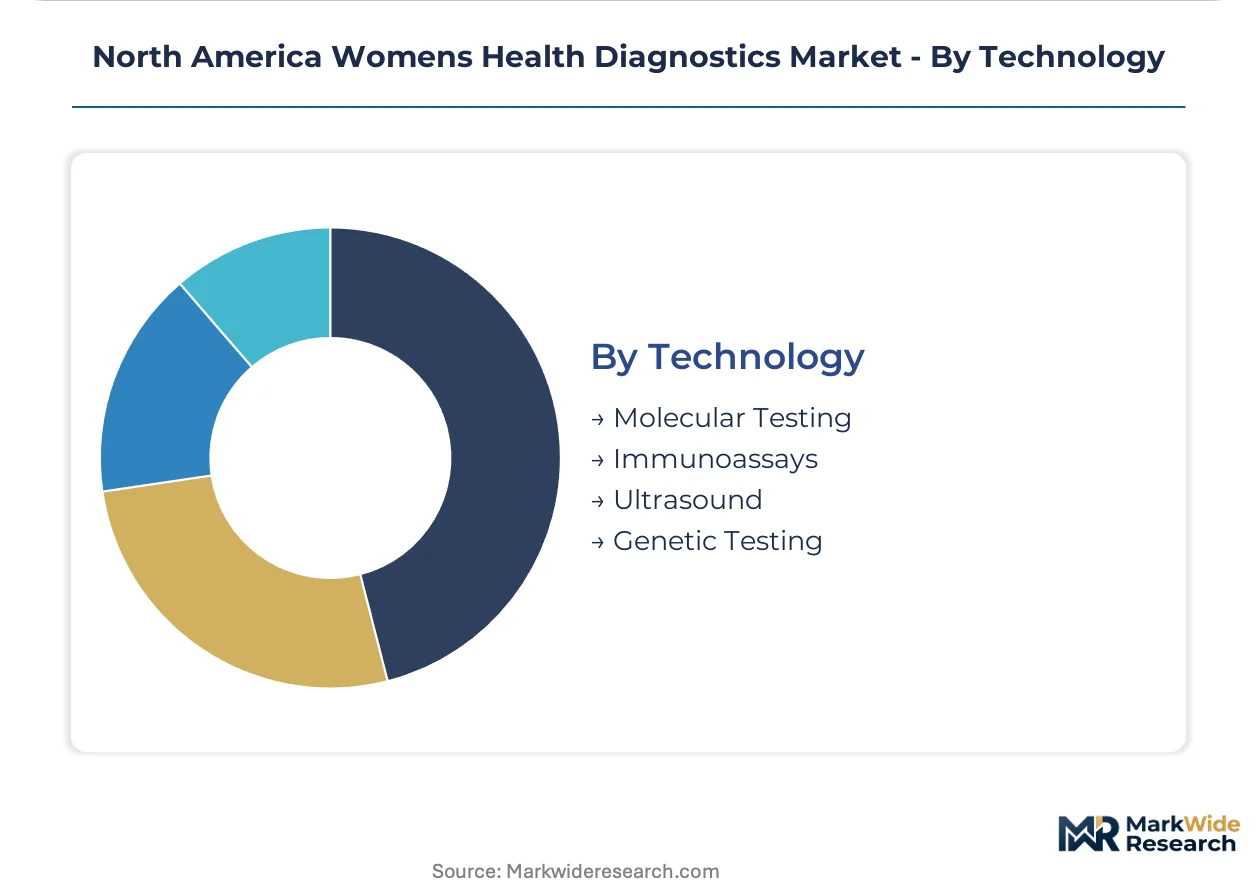
Technology:
Regulatory validation burden and automation maturity differentiate technologies by time-to-market and operational scalability.
- Molecular Testing:PCR, NGS, and nucleic acid hybridization methods for genetic and oncologic profiling. FDA premarket approval pathways govern novel biomarker assay commercialization, with extended review cycles delaying revenue for developers lacking established quality systems.
- Ultrasound:Transabdominal and transvaginal imaging with machine learning integration for automated lesion detection. Health Canada's Medical Devices Regulations are tightening software-as-a-medical-device classification for AI-enabled algorithms, requiring clinical validation studies and algorithm change control protocols.
- Immunoassays:Antibody-based detection of hormones, tumor markers, and infectious agents.
- Genetic Testing:Hereditary cancer panels and pharmacogenomic profiling.
Molecular Testing carries the heaviest regulatory load; Ultrasound is scaling fastest through AI-augmented reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomarker reagent manufacturing concentrates in Massachusetts and California, anchoring supply chains for molecular diagnostic platforms across the continent.
United States
Texas and California hospital systems drive centralized laboratory procurement for high-throughput cancer screening workflows. FDA premarket approval pathways govern novel biomarker assay commercialization, with extended review cycles affecting product launch timelines. Florida community oncology practices adopt liquid biopsy systems to retain patients locally.
Canada
Ontario and British Columbia health authorities pilot outcome-linked diagnostic procurement models. Health Canada's Medical Devices Regulations tighten software-as-a-medical-device classification for AI-enabled imaging algorithms. Toronto and Vancouver anchor clinical laboratory concentration for provincial healthcare networks.
Mexico
Mexico City Metro concentrates demand for imported point-of-care fertility testing devices through private hospital chains. COFEPRIS medical device registration requirements create regulatory alignment with FDA standards for northern market access. Guadalajara emerges as a distribution hub for Central American diagnostic reagent supply.
North America Womens Health Diagnostics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented imaging and decentralized point-of-care deployment. The vendor base stratifies between consolidated laboratory networks with national processing contracts and specialized manufacturers of capital-intensive imaging platforms. Three archetypes dominate: high-throughput laboratory processors, dedicated women's health platform developers, and compact point-of-care instrument suppliers. Competitive positioning hinges on securing centralized procurement contracts with integrated delivery networks and obtaining favorable CMS coverage determinations for novel assay categories.
Among United States-based operators, Quest Diagnostics Incorporated and Hologic, Inc. exemplify contrasting scale strategies within the sector. Quest Diagnostics Incorporated occupies a position as a national laboratory processor sustaining volume concentration through automated molecular workflow scaling. Hologic, Inc. anchors the dedicated platform tier through capital equipment relationships with hospital breast health and cervical cancer screening programs. Abbott represents the point-of-care archetype with compact instrument systems designed for clinic deployment without centralized laboratory infrastructure.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| Hologic, Inc. |
| Abbott |
| BD |
| GE Healthcare |
| Thermo Fisher Scientific Inc. |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
CLIA-certification tier divergence separates premium molecular diagnostics from commodity immunoassays, with this bifurcation manifesting in both pricing power and supply chain configurations across the United States and Canada. High-complexity testing platforms command bundled service contracts that absorb instrument maintenance and reagent replenishment, while point-of-care devices compete on unbundled hardware acquisition with per-test consumable economics.
Pricing Analysis
Extended warranty and field-service bundling distinguishes capital-intensive imaging systems from reagent-dependent molecular platforms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA pathway completion status and CLIA laboratory certification tier. Pricing pressure stems from integrated delivery network consolidation in Texas and California, where centralized procurement compresses margins for standalone diagnostic manufacturers. Hospital systems exhibit lowest price sensitivity for AI-augmented imaging modules with established CPT reimbursement codes, while independent clinics drive hardest bargains on point-of-care fertility instruments.
Supply Chain Analysis
Reverse-logistics infrastructure for refurbished imaging systems and remanufactured assay analyzers channels secondary equipment through certified pre-owned programs in Ontario and British Columbia. Biomarker reagent manufacturing concentrates in Massachusetts and California, with critical nucleic acid isolation chemistries drawing from limited North American suppliers. Raw material dependencies include fluorophore conjugates, polymerase enzymes, and magnetic bead substrates. Single-source vulnerability for NGS library preparation kits exposes production to supplier concentration risk. Distribution runs through national laboratory networks and regional medical device distributors serving hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
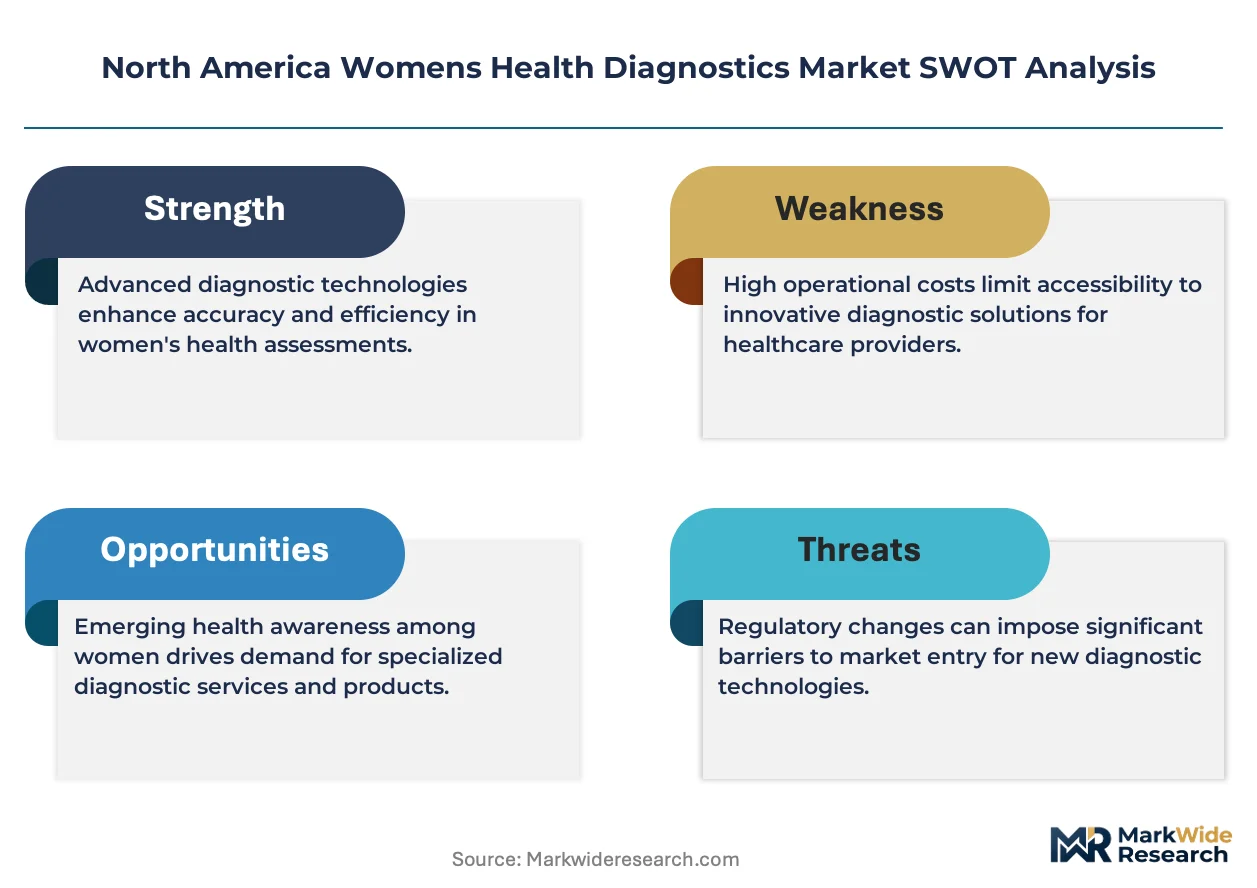
The North America Womens Health Diagnostics Market functions as a vertical-integration race, with players pursuing backward control over reagent chemistries to defend margin structures against consolidated buyer power.
For Market Incumbents: Hedge against molecular pathology workforce scarcity by acquiring CLIA-certified laboratories with established quality infrastructure in Texas and California. Secure captive supply of fluorophore and enzyme reagents through in-house production partnerships or long-term offtake agreements with Massachusetts-based specialty chemical manufacturers.
For New Entrants and Emerging Players: Community oncology practices in Florida and Arizona represent an underserved buyer archetype seeking liquid biopsy platforms that retain patients locally. Penetrate this whitespace through automated sample-to-answer workflows with minimal molecular biology expertise requirements. Pursue direct-to-consumer genetic testing integration with telehealth pre-test counseling as a go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-augmented imaging specialists given Health Canada's tightening software-as-a-medical-device classification and the resulting clinical validation barrier for unproven algorithms. Long-term viability over the next decade hinges on securing favorable CMS coverage determinations for multi-cancer early detection assays. Monitor Ontario and British Columbia outcome-linked procurement pilots for early signals of value-based care adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Acquisition | Consolidated hospital networks in Texas and California demand high-complexity testing partners with existing quality infrastructure. |
| FDA Premarket Approval Pathway | Novel biomarker assays require extended review cycles that favor developers with established regulatory affairs capabilities. |
| Hospital System Partnership | Integrated delivery networks anchor procurement through centralized contracting for imaging and laboratory services. |
| Software Companion Development | AI-augmented ultrasound and mammography modules create new reimbursement categories under evolving CPT codes. |
| Reimbursement Strategy | CMS coverage determinations for liquid biopsy technologies reshape investment priorities across the oncology surveillance pipeline. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, CLIA laboratory director consultations, and biomedical engineer assessments underwrites the qualitative findings in this study. Primary fieldwork captured perspectives from GPO contracts managers, molecular pathology workforce recruiters, and point-of-care clinic operators across the United States and Canada. Secondary validation drew from FDA 510(k) and PMA filing databases, Health Canada medical device license records, CMS national coverage determination documents, and hospital procurement database aggregators. Bottom-up test volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Comparable-period anchoring aligned the projection horizon against historical CLIA laboratory certification trends and FDA review cycle duration patterns. The analytical framework modeled segmentation across product architecture, clinical application, end-user procurement authority, and technology regulatory burden. CAGRs derived from installed base expansion rates and reimbursement pathway adoption curves. Forecast inputs incorporated molecular pathology workforce supply constraints and integrated delivery network consolidation velocity in Texas and California.
Revisions become necessary when FDA premarket approval timelines extend materially, Health Canada software-as-a-medical-device enforcement intensifies, or CMS multi-cancer early detection coverage determinations deviate from anticipated pathways. Practitioners should monitor integrated delivery network contract awards, CLIA laboratory director compensation inflation, and AI imaging algorithm clinical validation study completions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Menopause Market
Women's Health
Maternal Health Market
Women's Health
Women's Health Market
Women's Health
Women Health Software Market
Women's Health
Women's Health App Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women's Digital Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
US Womens Health Market
Women's Health
Women Health Care Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women Health Devices Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market