
 Workplace Menstrual Health Benefits Platform Market | 2026-2036
Workplace Menstrual Health Benefits Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Workplace Menstrual Health Benefits Platform Market Insights
The gap between premium employer-sponsored platforms and basic wellness app integrations is shifting as large corporations demand clinical-grade telemedicine support while smaller employers settle for symptom tracking add-ons. Peppy leverages its specialized coaching model to anchor the premium tier for Fortune 500 clients. Maven Clinic sustains broad geographic coverage across North America and Europe through its hybrid care network. Fertifa differentiates by concentrating on fertility and menstrual health convergence within occupational health frameworks.
Workplace menstrual health benefits platforms are digital infrastructure systems that combine HIPAA-compliant health data architecture with employer-administered access controls, typically integrating with existing HRIS and payroll systems to deliver confidential clinical support. Their primary commercial purpose is reducing absenteeism and improving retention by addressing a historically underserved area of employee health. Cloud-based and SaaS deployment models dominate current procurement because they minimize IT overhead and accelerate onboarding for HR teams. Telemedicine support within solution types captures the strongest margin pools due to clinician licensing requirements and recurring consultation fees. Small and medium enterprises represent the fastest-growing end user category as platform vendors release stripped-down, price-accessible tiers.
HIPAA governs data handling for US employers, while the EU AI Act and GDPR impose algorithmic transparency and consent requirements on symptom prediction features offered to European workforces. The UK's Equality and Human Rights Commission guidance further shapes platform design by mandating reasonable accommodation documentation linked to menstrual health conditions. Employers must evaluate whether their chosen vendor's regulatory mapping covers all jurisdictions where remote employees reside.
Market Dynamics
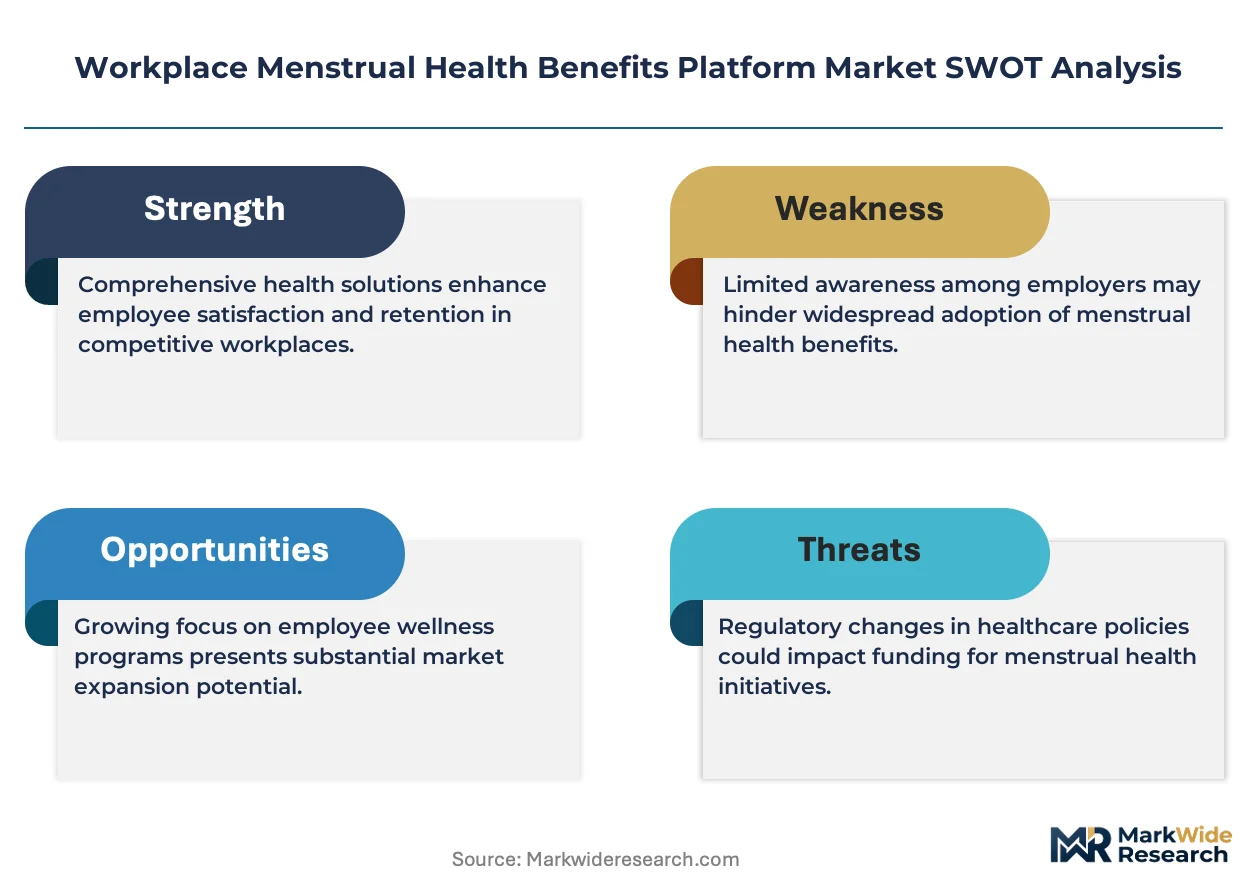
Employer procurement teams are consolidating vendor relationships around platforms that embed certified clinical workflows rather than standalone wellness tools, compressing the addressable supplier base for point solutions.
Growth Catalysts
- OSHA emerging guidelines:Anticipated federal employer safety standards in the United States are prompting HR departments to formalize menstrual health accommodations ahead of compliance deadlines.
- Technology sector HR expansion:Large technology employers are mandating comprehensive reproductive health benefits as standard compensation components, creating reference customers for enterprise platform adoption.
- United Kingdom market concentration:Dense clustering of multinational corporate headquarters in London and Manchester generates concentrated demand for English-language platform deployments with NHS integration capabilities.
Market Restraints
- Clinician licensing costs:Multi-jurisdictional telemedicine credentialing creates fixed cost burdens that scale poorly for vendors serving distributed workforces across state and national boundaries.
- EU AI Act algorithmic transparency:Symptom prediction features require explainable AI documentation that extends development timelines and limits proprietary model architectures.
- Legacy HRIS integration friction:Custom API development for aging payroll systems consumes implementation resources and delays recurring revenue recognition.
Strategic Opportunities
- Small and medium enterprise tier expansion:Stripped-down platform versions with reduced clinical intensity can capture price-sensitive employers below five hundred employees.
- Fertility-menstrual convergence:Occupational health frameworks that combine family planning with cycle management address retention challenges in female-dominated industries.
- GDPR-compliant data architecture export:Privacy-engineered platforms developed for European workforces can enter Middle Eastern and Asia-Pacific markets with stringent data localization requirements.
Industry Challenges
- Specialized health coach recruitment:Certified menstrual health educators remain scarce relative to platform scaling timelines, constraining service quality at volume.
- Multi-jurisdiction compliance documentation:Employers must verify vendor coverage for HIPAA, GDPR, and national health data laws across all remote employee locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workplace Menstrual Health Benefits Platform Market |
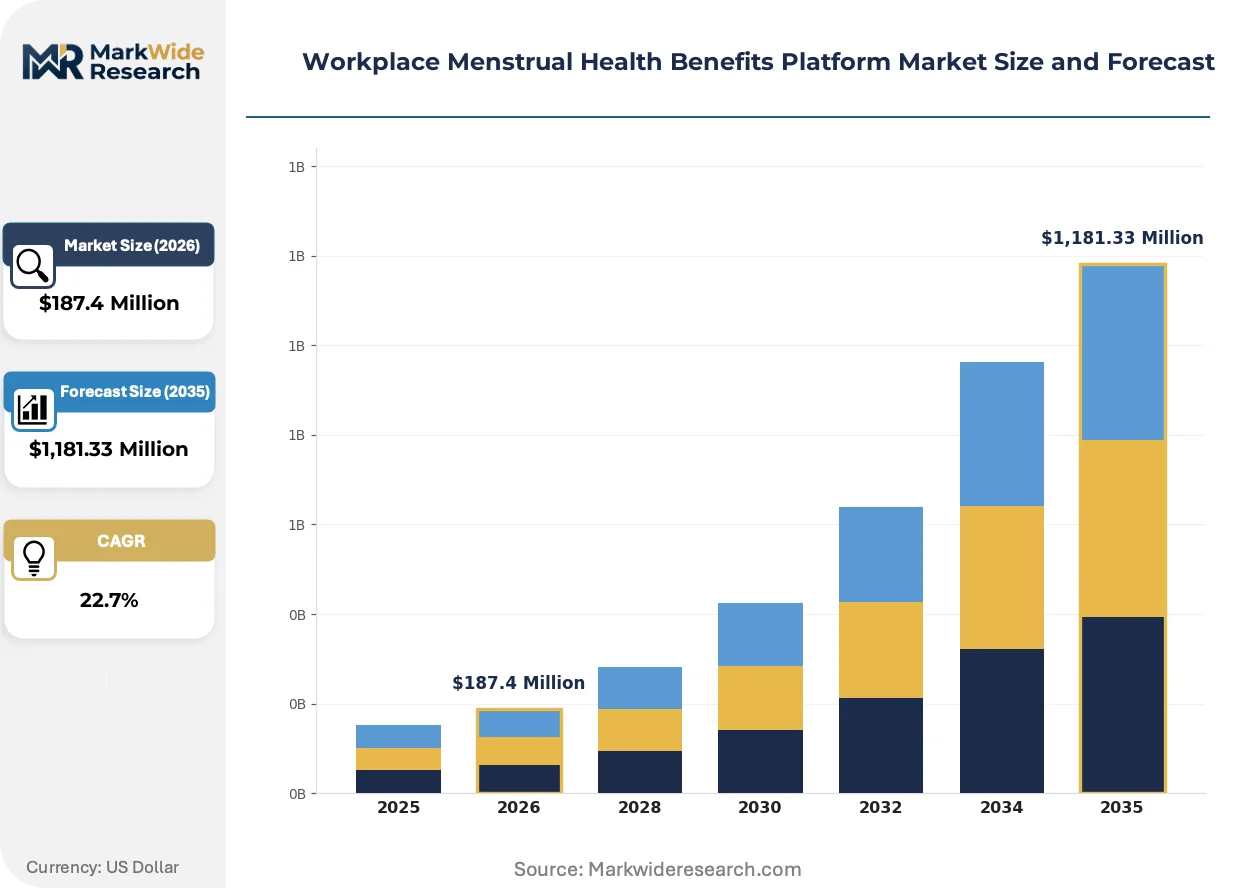
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Digital Health Tracking, Telemedicine Support, Educational Content, Personalized Coaching, Symptom Management Tools Deployment Model: Cloud-Based, SaaS, On-Premises, Hybrid Solutions, Mobile Applications Application: Employee Wellness Programs, HR Benefits Management, Occupational Health Support, Diversity & Inclusion Initiatives, Productivity Enhancement End User: Corporations, Small Medium Enterprises, Non-Profit Organizations, Government Agencies, Educational Institutions |
| Companies Covered | Peppy, Fertifa, Maven Clinic, Progyny, Ovia Health, Vira Health, Carrot Fertility, Flo Health, Clue by BioWink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workplace Menstrual Health Benefits Platform Market Trends and Innovations
Platform architecture is converging on modular clinical service stacks that employers configure based on workforce demographics and risk tolerance rather than purchasing predetermined bundles.
AI-powered symptom triage engines are absorbing routine clinical intake workflows previously handled by human coaches. Mid-market employers with limited occupational health staff are adopting these tools fastest. The technology is absorbing margin from traditional telemedicine consultations by deflecting low-acuity cases to automated pathways.
The EU AI Act's risk classification system for health prediction algorithms is forcing vendors to reengineer cycle tracking features with mandatory human oversight loops. This regulatory architecture elevates compliance costs for European deployments. Vendors serving German and French workforces are responding by segregating EU-specific product builds from global codebases.
Benefits administrators are unbundling menstrual health platforms from broader wellness contracts and evaluating them as standalone procurement categories with distinct ROI metrics. This purchasing pattern is displacing bundled EAP vendors that previously captured this spend. The shift is most visible in United States technology and professional services firms with dedicated diversity and inclusion procurement functions.
Workplace Menstrual Health Benefits Platform Market Segmentation
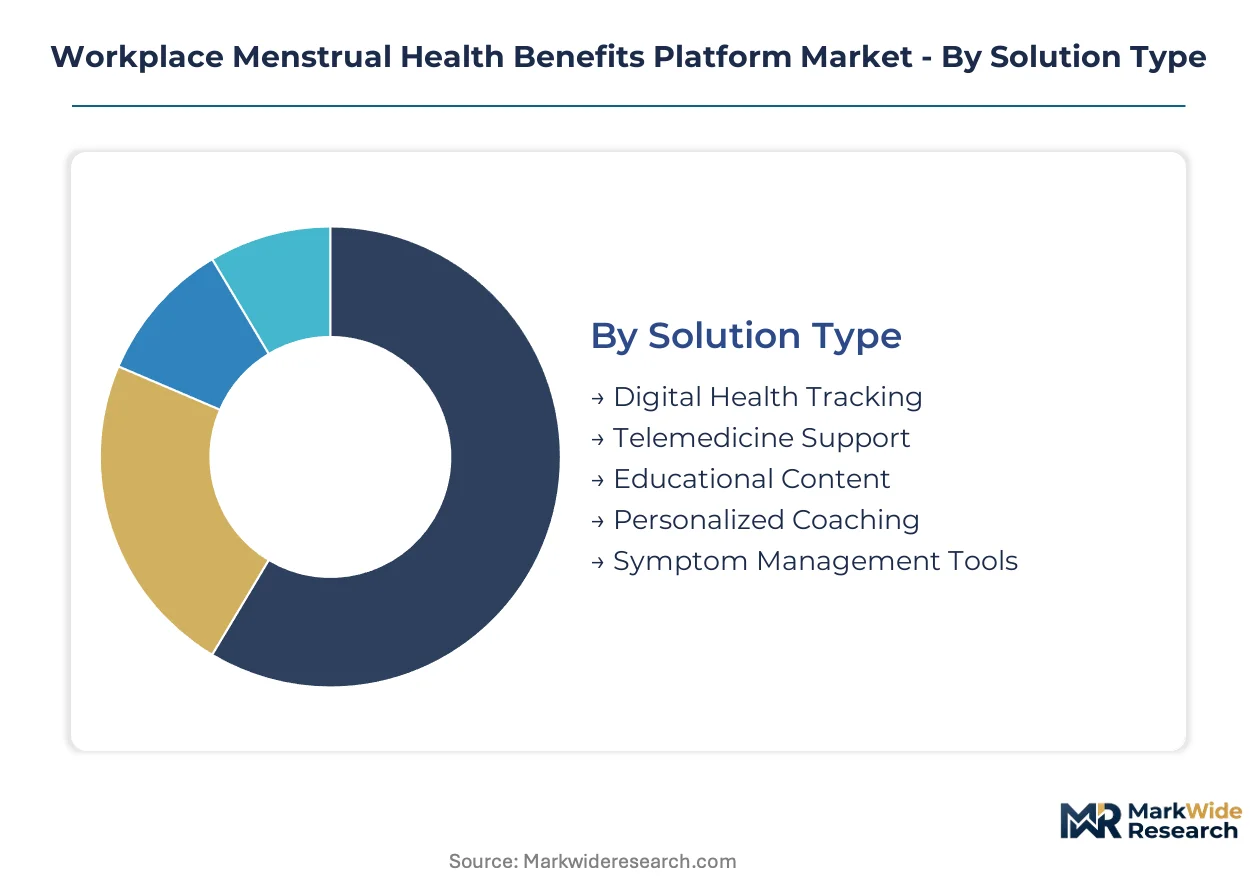
Platform vendors structure offerings across four intersecting dimensions that determine pricing architecture and implementation complexity. Procurement teams evaluate solution types against deployment constraints, while end-user scale dictates service intensity and regulatory exposure.
Solution Type:
Clinical sophistication separates premium platforms from wellness add-ons, with telemedicine credentialing requirements creating tiered margin structures.
- Digital Health Tracking:HIPAA-compliant cycle logging and symptom pattern recognition form the baseline infrastructure. Demand concentrates in US technology employers seeking OSHA-aligned documentation capabilities ahead of anticipated federal guidelines.
- Telemedicine Support:Licensed clinician networks deliver synchronous consultations for acute menstrual health concerns. United Kingdom multinational headquarters in London and Manchester generate concentrated procurement for English-language deployments with NHS pathway integration.
- Educational Content:Curated learning modules covering endometriosis, PCOS, and perimenopause awareness.
- Personalized Coaching:One-to-one certified menstrual health educator sessions addressing workplace accommodation navigation.
- Symptom Management Tools:AI-powered triage engines routing cases to appropriate care tiers per EU AI Act risk classifications.
Telemedicine Support leads on scale; Personalized Coaching leads on momentum.
Deployment Model:
IT overhead tolerance and data sovereignty requirements shape employer selection between cloud-native and controlled-environment architectures.
- Cloud-Based:Multi-tenant infrastructure minimizing client-side server maintenance. German and French workforces drive EU-specific product builds segregated from global codebases to satisfy GDPR algorithmic transparency mandates.
- SaaS:Subscription licensing with automated updates and API-first HRIS integration. Small and medium enterprises below five hundred employees represent the steepest expansion trajectory as vendors release price-accessible tiers.
- On-Premises:Self-hosted instances for organizations with stringent data localization requirements.
- Hybrid Solutions:Mixed architectures separating sensitive health records from administrative dashboards.
- Mobile Applications:Native iOS and Android experiences with offline symptom logging capabilities.
SaaS dominates procurement volume; Cloud-Based gains share fastest in regulated European markets.
Application:
Functional deployment context determines integration depth with existing employer systems and measurement frameworks.
- Employee Wellness Programs:Comprehensive benefit embedding within broader health and wellbeing portfolios. US professional services firms with dedicated diversity and inclusion procurement functions unbundle menstrual health from bundled EAP contracts most aggressively.
- HR Benefits Management:Direct integration with payroll and enrollment systems for streamlined administration. United Kingdom market concentration around multinational corporate headquarters accelerates English-language platform adoption with centralized benefits coordination.
- Occupational Health Support:Clinical-grade interventions addressing absenteeism and presenteeism metrics.
- Diversity & Inclusion Initiatives:Retention-focused programming targeting female-dominated industry verticals.
- Productivity Enhancement:Outcome-based contracts tying platform fees to measured workforce performance improvements.
HR Benefits Management leads on scale; Diversity & Inclusion Initiatives leads on momentum.
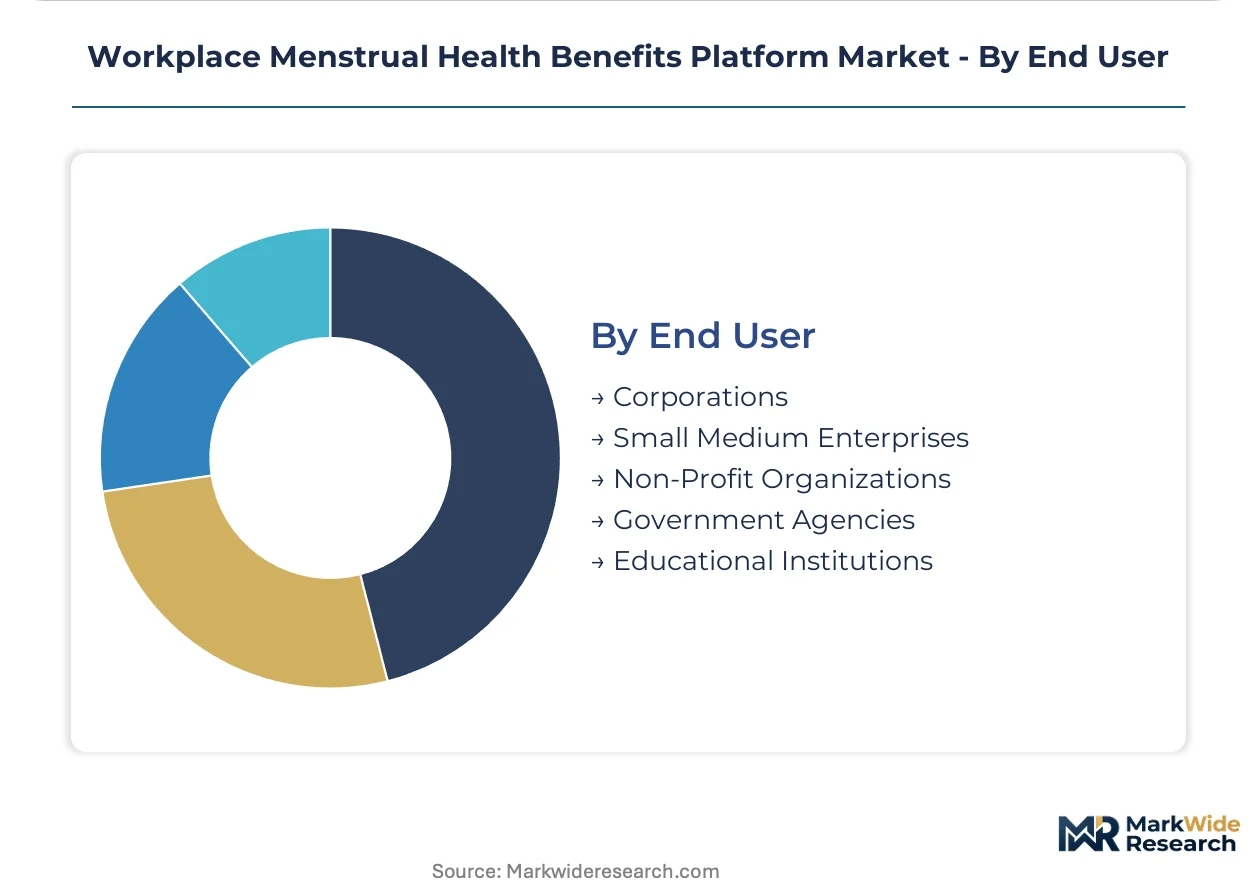
End User:
Organizational scale dictates service configuration complexity and price sensitivity thresholds.
- Corporations:Enterprise-grade deployments with dedicated account management and custom API development. Technology sector HR departments mandate comprehensive reproductive health benefits as standard compensation components, establishing reference architectures.
- Small Medium Enterprises:Stripped-down platform versions with reduced clinical intensity and self-service onboarding. This segment climbs the fastest as vendor product teams prioritize accessible pricing tiers.
- Non-Profit Organizations:Mission-aligned deployments often subsidized by foundation grant funding.
- Government Agencies:Public sector procurement with enhanced audit trails and civil service integration requirements.
- Educational Institutions:Campus-wide implementations serving faculty, staff, and in some configurations student populations.
Corporations anchor current revenue; Small Medium Enterprises delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector talent clusters in London, San Francisco, and Berlin drive disproportionate platform procurement as employers compete for female workforce retention. Multinational corporate headquarters concentrate demand in English-language markets with integrated healthcare systems. Regulatory divergence between HIPAA-governed US deployments and GDPR-constrained European builds shapes vendor product architecture decisions.
United States
OSHA emerging guidelines are prompting HR departments at Fortune 500 technology employers to formalize menstrual health accommodations ahead of federal compliance deadlines. HIPAA governs all health data architecture for US-based deployments, requiring Business Associate Agreements with clinical service vendors. San Francisco Bay Area technology campuses anchor enterprise procurement volume, with reference architectures spreading to Seattle and Austin corporate headquarters.
United Kingdom
Dense clustering of multinational corporate headquarters in London and Manchester generates concentrated demand for English-language platform deployments with NHS pathway integration capabilities. The Equality and Human Rights Commission guidance mandates reasonable accommodation documentation linked to menstrual health conditions, shaping platform feature requirements. Peppy and Maven Clinic have established strong enterprise footholds serving banking and professional services employers in the City of London and Canary Wharf.
Germany
EU AI Act algorithmic transparency requirements impose explainable AI documentation on symptom prediction features, extending development timelines for vendors serving German workforces. GDPR consent requirements and the country's federal data protection authority enforce strict health data localization standards. Berlin and Munich technology employers drive SaaS procurement, with vendors responding by segregating EU-specific product builds from global codebases.
France
ANSM and CNIL oversight creates dual regulatory exposure for health prediction algorithms and personal data processing in menstrual health platforms. The country's labor code provisions for workplace health accommodations intersect with emerging platform-based documentation tools. Paris-based multinational headquarters and Lyon pharmaceutical clusters generate demand for French-language clinical support with occupational health integration.
Canada
Health Canada and provincial privacy commissioners govern health data handling for employers with distributed remote workforces spanning Ontario, British Columbia, and Quebec. The country's technology sector expansion in Toronto and Vancouver creates demand for English and French bilingual platform deployments. Provincial occupational health regulations vary, requiring vendors to map compliance coverage across multiple jurisdictions for national employer contracts.
Workplace Menstrual Health Benefits Platform Market Competitive Landscape
Capital-heavy clinical infrastructure providers compete with asset-light wellness app developers for employer procurement budgets. The vendor base separates into three tiers: enterprise-grade platforms with licensed telemedicine networks, mid-market SaaS solutions with coaching-based support, and basic symptom tracking add-ons bundled within broader wellness contracts. Dominant competitive moves include strategic partnerships with occupational health providers and geographic expansion through regulatory-compliant product builds.
Within the specialized coaching tier, Peppy anchors premium positioning for Fortune 500 clients through its certified educator network. Maven Clinic exemplifies broad geographic coverage across North America and Europe through hybrid care network architecture. Fertifa occupies a distinct position at the fertility-menstrual convergence point, embedding within occupational health frameworks rather than standalone wellness procurement.
| Leading Market Players |
|---|
| Peppy |
| Fertifa |
| Maven Clinic |
| Progyny |
| Ovia Health |
| Vira Health |
| Carrot Fertility |
| Flo Health |
| Clue by BioWink |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 procurement mandates for certified clinical workflows are compressing vendor margins and forcing platform developers to absorb multi-jurisdictional telemedicine licensing costs. This demand-side pressure stratifies pricing tiers around service intensity rather than feature breadth.
Pricing Analysis
The bundled-vs-unbundled service split defines current pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates telemedicine-enabled platforms from coaching-based mid-market solutions and basic symptom tracking add-ons. Price differentiation rests on clinician certification grade and geographic coverage scope. Pricing pressure stems from SME procurement teams demanding stripped-down tiers without clinical overhead. Small and medium enterprises exhibit highest price sensitivity; enterprise technology employers show lowest.
Supply Chain Analysis
Freight costs for cross-border data infrastructure are negligible, yet regulatory compliance logistics dominate vendor cost structures. Platform development concentrates in the United States, United Kingdom, and Germany, with clinical service networks anchored in these jurisdictions. Raw material dependencies include HIPAA-compliant cloud hosting, GDPR-certified data architecture, and licensed clinician labor pools. Single-source vulnerability sits with certified menstrual health educator recruitment. Distribution runs through direct enterprise sales teams and benefits broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand, with OSHA emerging guidelines and EU AI Act risk classifications creating compliance-driven procurement cycles.
For Market Incumbents: Deploy modular clinical service stacks to defend against wellness app developers encroaching from below. Deepen API integration capabilities for legacy HRIS environments to lock in enterprise accounts. Counter clinician licensing cost inflation through automated triage engines that deflect low-acuity cases. For New Entrants and Emerging Players: Capture price-accessible SME tiers below five hundred employees where incumbent clinical infrastructure becomes cost-prohibitive. White-space concentration sits in French and German mid-market employers needing GDPR-compliant builds without Fortune 500 implementation complexity. Go-to-market through occupational health provider partnerships accelerates trust acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with platforms possessing NHS pathway integration and EU AI Act pre-certified algorithmic architectures. Long-term viability favors vendors whose regulatory mapping spans HIPAA, GDPR, and emerging OSHA frameworks without custom rebuilds per jurisdiction. Watch for clinician licensing cost spikes as inflection indicator for automated triage adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Algorithmic transparency documentation unlocks German and French enterprise procurement. |
| NHS Pathway Integration | English-language clinical routing secures London multinational headquarters contracts. |
| Legacy HRIS API Development | Custom payroll system connectors reduce implementation friction for mid-market employers. |
| Certified Educator Network Expansion | Scarce menstrual health coaching labor constrains service quality at volume. |
| SME Tier Product Launch | Stripped-down clinical intensity captures price-sensitive employers below five hundred employees. |
Research Methodology
Direct dialogue with HR benefits directors, occupational health officers, platform product managers, and clinical service vendors grounded qualitative findings. Secondary validation drew from OSHA regulatory filings, EU AI Act implementation guidance, NHS digital health procurement databases, and enterprise HRIS integration documentation. Bottom-up and top-down triangulation cross-checked vendor-reported deployment metrics against employer benefits expenditure patterns.
Bottom-up modeling segmented addressable demand by solution type, deployment model, application context, and organizational scale across the analysis window. Top-down validation triangulated against technology sector benefits expenditure disclosures and professional services firm procurement patterns. CAGRs derived from regression analysis of adoption velocity correlated with regulatory milestone timing. Forecast inputs included clinician licensing cost trajectories and HRIS integration completion rates.
Regulatory implementation delays, clinician supply constraints, and HRIS integration backlogs are the dominant revision risks to modeled adoption curves. Forecasts embed assumptions about OSHA guideline finalization and EU AI Act enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Menstrual Health Apps Market
Women's Health
Menopause Market
Women's Health
Women Health Devices Market
Women's Health
Women Health Software Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Maternal Health Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women's Health App Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Women Health Care Market
Women's Health
Women's Digital Health Market
Women's Health
Women's Health Market
Women's Health
Mother and Child Healthcare Market