
 Menopause Market | 2026-2036
Menopause Market Size, Share, and Industry Trends Forecast 2026-2036
Menopause Market Intelligence
Specialty pharmacy distribution is narrowing as direct-to-patient channels capture greater prescription volume for menopause therapies. Pfizer Inc. leverages its established hormone therapy infrastructure to sustain wholesale relationships with large health systems. Bayer AG anchors its position through urology and women's health crossover portfolios that compete across symptom management categories. Theramex specializes in hormone replacement therapy formulations that differentiate through localized regulatory approvals.
Menopause encompasses the permanent cessation of ovarian function marked by twelve consecutive months without menstruation, typically occurring between ages 45 and 55 with declining estrogen and progesterone production. The condition drives commercial activity across pharmaceutical intervention, diagnostic monitoring, and supportive care services aimed at managing vasomotor symptoms, genitourinary syndrome, and long-term metabolic changes. Hormone Replacement Therapy dominates current prescription value due to established clinical guidelines and reimbursement familiarity, while Non-hormonal Therapies represent the fastest-expanding segment as patients with contraindications seek alternatives. Dietary Supplements occupy a mature, fragmented margin pool where brand trust and third-party certification determine purchasing decisions.
FDA oversight of menopause drug approvals shapes clinical trial endpoints and labeling requirements for vasomotor symptom claims, while EMA's centralized marketing authorization process determines commercial access across European member states. REACH compliance affects excipient sourcing and formulation chemistry for topical estrogen products manufactured in or imported into the European Union. Stakeholders must monitor regulatory divergence between FDA and EMA on non-hormonal therapy approval standards as this will determine portfolio prioritization and geographic launch sequencing.
Market Dynamics
Hospital outpatient clinics in the United States are aggressively expanding dedicated menopause service lines as patient volume rises, creating a structural pull on pharmaceutical distribution networks and care delivery infrastructure.
Growth Catalysts
- FDA Guidance on Non-hormonal Therapies:The agency's clarified pathway for vasomotor symptom treatments is accelerating clinical trial enrollment and shortening development timelines for novel drug candidates.
- Integrated Women's Health Networks:Consolidated care delivery models in the United States are capturing patient volume through coordinated diagnostic, therapeutic, and monitoring services under single organizational umbrellas.
- Direct-to-Patient Channels:Telehealth platforms and specialty mail-order pharmacies are capturing prescription volume previously routed through traditional wholesale distribution, compressing margin capture for intermediaries.
Market Restraints
- REACH Compliance Costs:European excipient sourcing requirements for topical estrogen formulations impose formulation chemistry constraints and supplier qualification burdens that inflate manufacturing overhead.
- Regulatory Divergence:Misaligned FDA and EMA approval standards for non-hormonal therapies force portfolio prioritization trade-offs and geographic launch sequencing delays.
- Specialty Pharmacy Concentration:Narrowing distribution channels create single-point-of-failure risk for manufacturers dependent on limited wholesale relationships with large health systems.
Strategic Opportunities
- Underpenetrated Genitourinary Syndrome Segment:Diagnostic awareness gaps for GSM symptoms in outpatient settings represent unaddressed prescription potential for localized hormone and non-hormonal interventions.
- EU Green Deal Alignment:Sustainable manufacturing incentives and bio-based excipient development programs create competitive differentiation pathways for European market entry.
- Digital Therapeutic Convergence:Integration of symptom-tracking applications with prescription workflows is enabling adherence monitoring and real-world evidence generation for payor negotiations.
Industry Challenges
- Clinical Trial Endpoint Standardization:Variable vasomotor symptom measurement protocols across investigator sites complicate regulatory submission packages and extend study timelines.
- Legacy EHR Integration:Menopause-specific diagnostic codes and care pathway modules require costly health information system upgrades for hospital outpatient networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menopause Market |
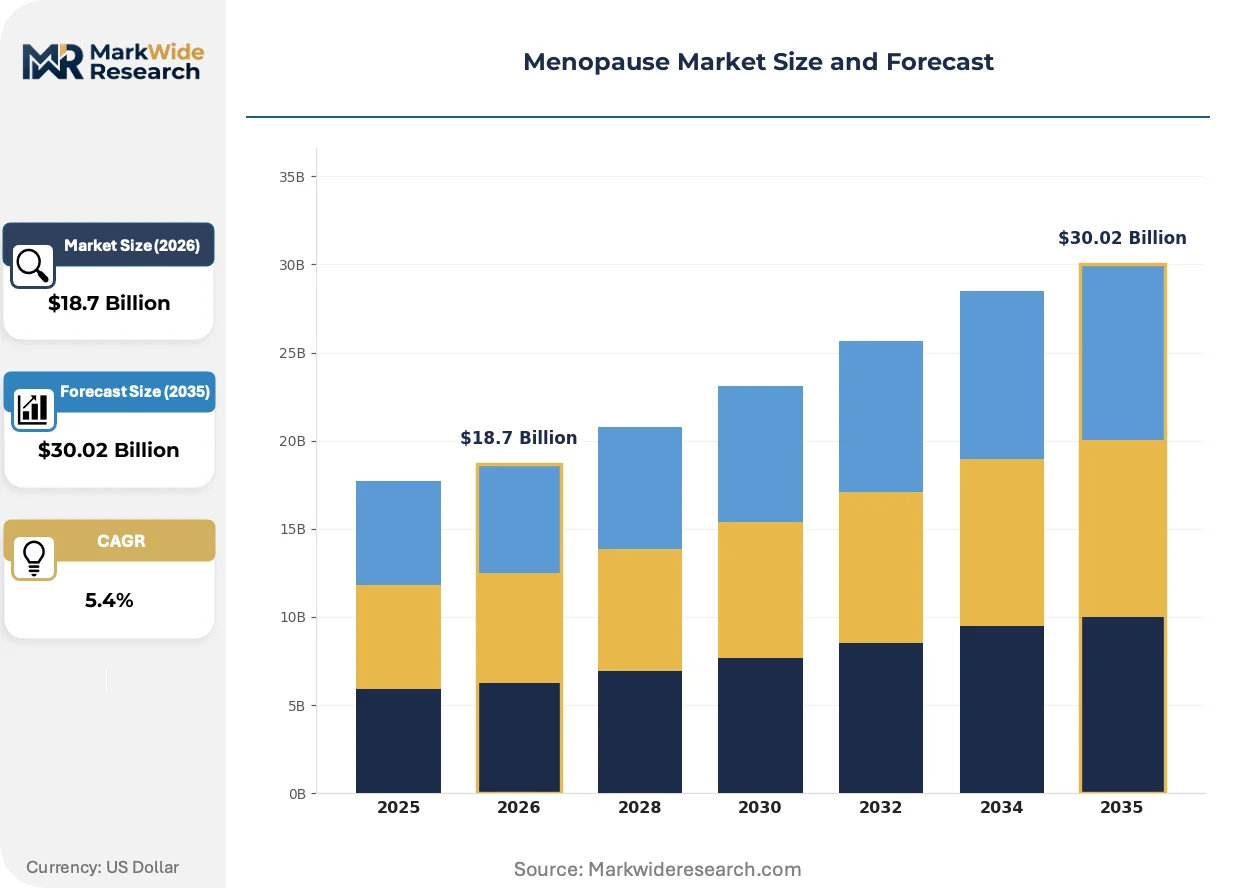
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Non-hormonal Therapies, Dietary Supplements, Herbal Remedies Application: Symptom Relief, Bone Health, Mood Support, Sexual Health End User: Homecare, Hospitals, Clinics, Pharmacies Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Pfizer Inc., Dr. Reddy's Laboratories Ltd., Bayer AG, GlaxoSmithKline PLC, Astellas Pharma Inc., AbbVie Inc., Pure Encapsulations LLC, Organon & Co, Theramex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menopause Market Strategic Shifts & Innovations
Digital health infrastructure is digitizing patient engagement and clinical decision support across menopause care delivery. Three interconnected developments are compressing traditional care models and redistributing value capture across the therapeutic ecosystem.
Remote patient monitoring technology is digitizing symptom tracking and treatment response measurement for vasomotor and genitourinary symptoms. Integrated women's health networks in the United States are deploying connected devices and mobile applications to capture real-world adherence data. This infrastructure is digitizing the traditional in-clinic follow-up model and enabling outcome-based contract negotiations with commercial payors.
EMA's centralized marketing authorization process is harmonizing clinical evidence requirements across European member states for hormone replacement therapies. The regulatory consolidation is reducing redundant national submission burdens but intensifying competition for centralized assessment capacity. Non-hormonal therapy developers are responding by front-loading European trial sites to secure priority review slots.
Patients are initiating care journeys through direct-to-consumer diagnostic platforms before presenting to traditional outpatient settings. This channel shift is compressing the traditional referral pathway and displacing primary care gatekeeper functions. The United States exhibits the most pronounced behavior change, where employer-sponsored digital health benefits accelerate platform adoption among commercially insured populations.
Menopause Market Segmentation
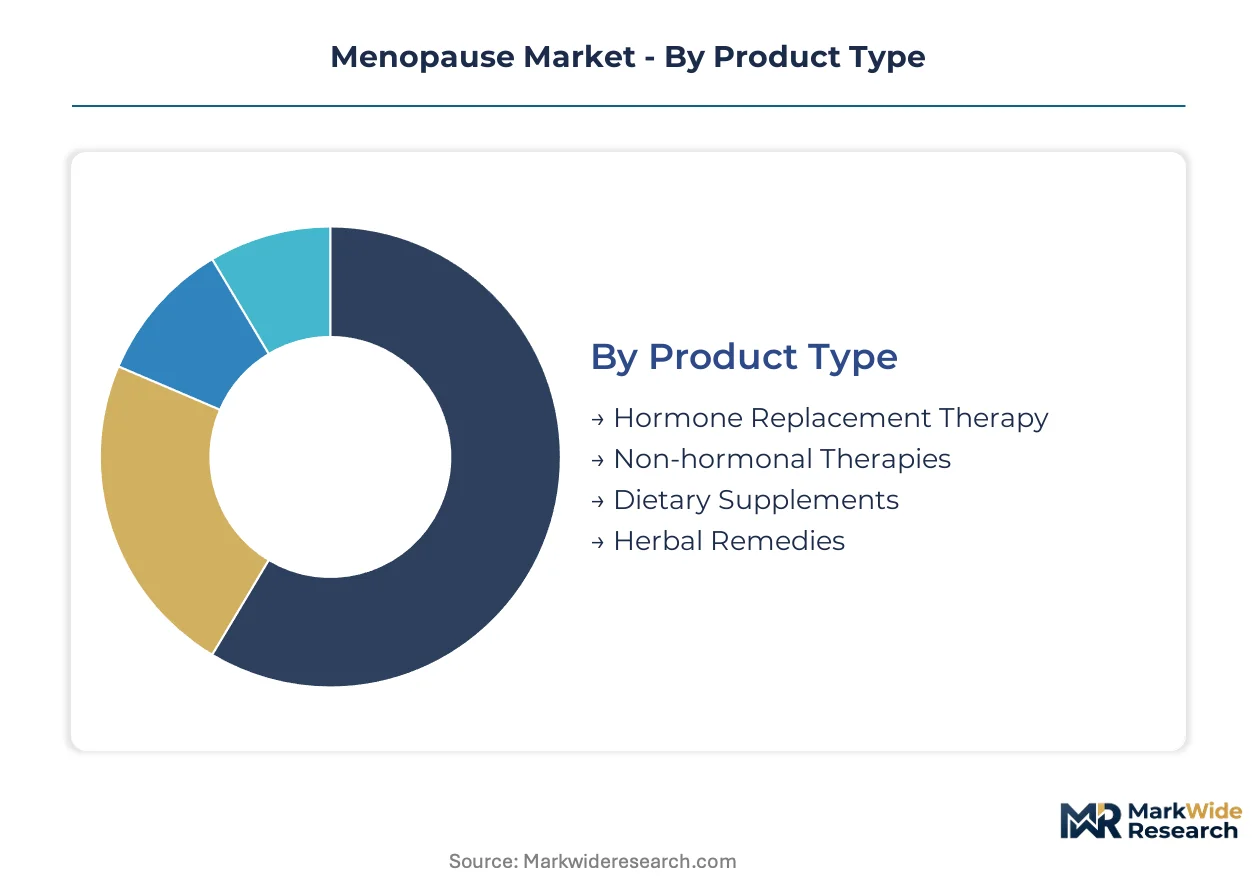
Segmentation in the menopause market reveals distinct purchasing rhythms across therapeutic categories. Prescription therapies turn over on clinical trial cycles and regulatory approvals, while consumer-facing segments respond to wellness trends and retail seasonality.
Product Type:
Hormone Replacement Therapy commands the longest development cycles due to FDA and EMA safety surveillance requirements, while Dietary Supplements refresh formulations quarterly based on ingredient trend cycles.
- Hormone Replacement Therapy:Synthetic and bioidentical estrogen-progesterone formulations administered via oral, transdermal, or vaginal routes. Demand concentrates in United States hospital outpatient networks where integrated women's health systems manage long-term metabolic risk. FDA post-market surveillance requirements and EMA centralized marketing authorization processes sustain high barriers to generic substitution.
- Non-hormonal Therapies:FDA-approved neurokinin receptor antagonists and selective serotonin reuptake inhibitors targeting vasomotor symptoms without hormonal exposure. Expansion concentrates among patients with contraindications to estrogen therapy, particularly breast cancer survivors and thrombosis-risk populations in United States specialty pharmacy channels. FDA's clarified development pathway is accelerating clinical trial enrollment for novel candidates.
- Dietary Supplements:Over-the-counter phytoestrogen, vitamin D, and omega-3 formulations positioned for symptom management. Third-party certification programs like NSF International and USP Verified drive brand switching in United States direct-to-consumer channels.
- Herbal Remedies:Black cohosh, red clover, and evening primrose oil preparations rooted in traditional medicine practice. Regulatory divergence between FDA dietary supplement oversight and EMA herbal monograph requirements fragments geographic commercialization strategies.
Hormone Replacement Therapy dominates installed base. Non-hormonal Therapies are where expansion concentrates.
Application:
Cost tier stratification separates reimbursed prescription indications from out-of-pocket wellness positioning, with symptom severity determining payer coverage thresholds.
- Symptom Relief:Vasomotor symptom management—hot flashes and night sweats—represents the primary reimbursed indication driving prescription volume. United States integrated women's health networks capture patient volume through coordinated diagnostic and therapeutic protocols, with telehealth platforms now initiating care journeys before traditional outpatient presentation.
- Bone Health:Osteoporosis prevention and fracture risk reduction through calcium, vitamin D, and bisphosphonate co-therapy. Long-term adherence challenges in United States Medicare populations sustain market expansion for sustained-release formulations and combination products.
- Mood Support:Anxiety and depression symptom management overlapping with perimenopausal transition. Prescription overlap with general psychiatric indications creates formulary positioning competition in United States commercial payor networks.
- Sexual Health:Genitourinary syndrome of menopause addressing vaginal atrophy, dyspareunia, and urinary symptoms. Diagnostic awareness gaps in United States outpatient settings represent unaddressed prescription potential for localized hormone and non-hormonal interventions.
Symptom Relief commands reimbursement priority. Sexual Health is where diagnostic expansion concentrates.
End User:
Patient acuity and care setting regulation determine distribution infrastructure requirements, with institutional procurement favoring formulary consolidation.
- Homecare:Self-administered therapies purchased through retail pharmacy and direct-to-patient channels. United States telehealth platforms and specialty mail-order pharmacies are capturing prescription volume previously routed through traditional wholesale distribution.
- Hospitals:Inpatient menopause service lines manage acute presentations and surgical menopause cases. United States hospital outpatient clinics are aggressively expanding dedicated menopause service lines as patient volume rises.
- Clinics:Specialized menopause and women's health practices delivering diagnostic and therapeutic coordination. EMA centralized marketing authorization harmonization is reducing redundant national submission burdens across European member state clinic networks.
- Pharmacies:Community and specialty pharmacy dispensing with adherence monitoring and patient counseling. United States specialty pharmacy concentration creates single-point-of-failure risk for manufacturers dependent on limited wholesale relationships.
Homecare captures volume scale. Hospitals are where service line investment concentrates.
Distribution Channel:
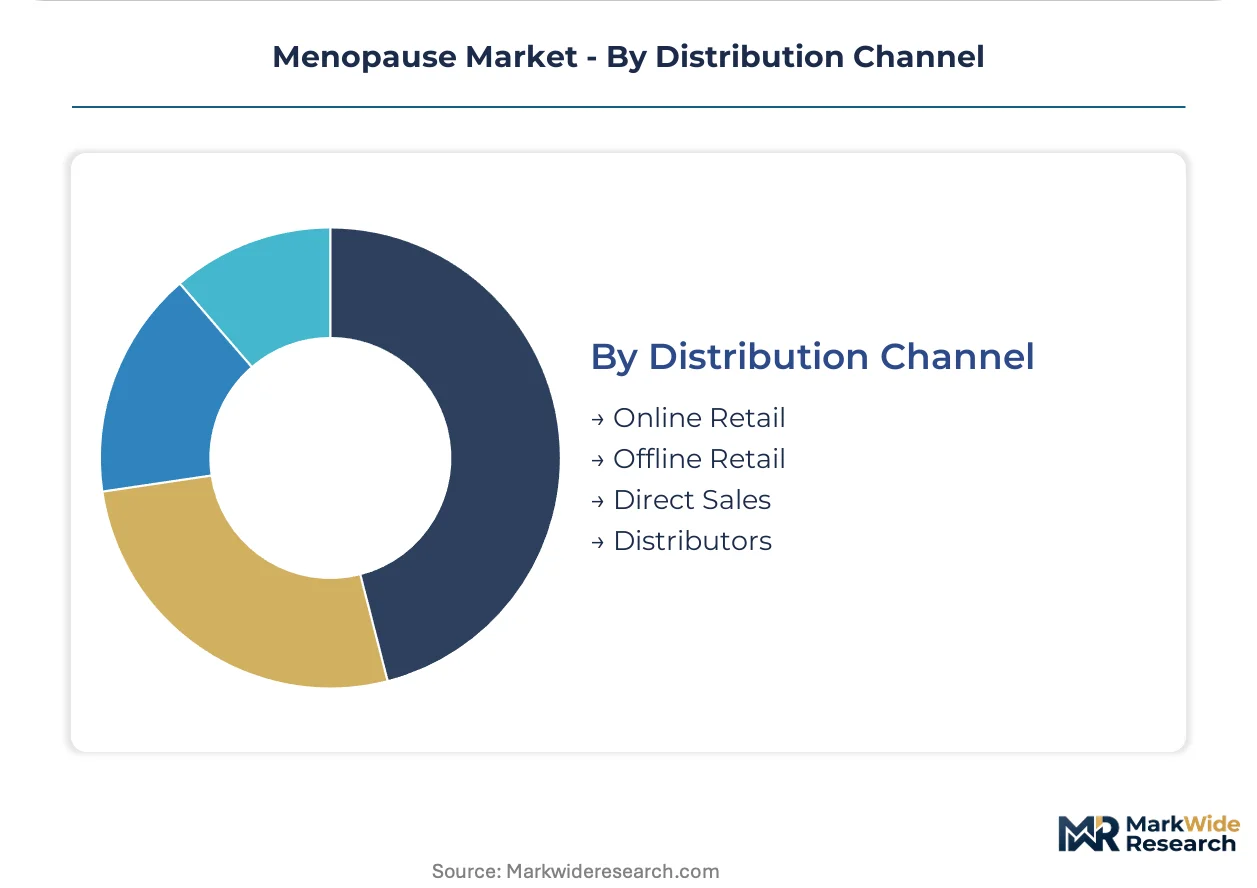
Margin capture shifts with channel control, as direct relationships displace intermediary markups and reshape manufacturer pricing power.
- Online Retail:E-commerce platforms and telehealth-integrated pharmacies capturing prescription and supplement volume. United States employer-sponsored digital health benefits accelerate platform adoption among commercially insured populations.
- Offline Retail:Brick-and-mortar pharmacy chains and mass merchandisers with in-store clinic partnerships. Shelf space competition intensifies for Dietary Supplements where brand trust and third-party certification determine purchasing decisions.
- Direct Sales:Manufacturer-owned channels and subscription models bypassing wholesale intermediaries. REACH compliance costs for European excipient sourcing constrain direct distribution of topical estrogen formulations.
- Distributors:Pharmaceutical wholesalers and specialty pharmacy service providers managing cold-chain and controlled-substance logistics. Narrowing specialty pharmacy channels compress margin capture for intermediaries serving large United States health systems.
Offline Retail dominates transaction frequency. Online Retail is where patient initiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European pharmaceutical distribution for hormone replacement therapies, with cold-chain logistics infrastructure underwriting continental supply security. Integrated rail links connect Dutch distribution hubs to German manufacturing clusters and French hospital networks. This infrastructure configuration positions the Netherlands as the logistical spine of European menopause therapeutics trade.
United States
Hospital outpatient clinics in Texas, Florida, and California are expanding dedicated menopause service lines as patient volume rises. FDA guidance on non-hormonal therapies for vasomotor symptoms is reshaping product development pathways and accelerating clinical trial enrollment. The Greater Boston corridor hosts concentrated biotech R&D activity targeting neurokinin receptor antagonists.
Germany
EMA's centralized marketing authorization process determines commercial access across German hospital networks and clinic systems. REACH compliance requirements for topical estrogen excipients impose formulation chemistry constraints on manufacturers operating in or importing into the European Union. The Rhine-Ruhr industrial region concentrates pharmaceutical manufacturing capacity serving Central European distribution.
United Kingdom
Integrated women's health networks in London and the Southeast are consolidating menopause care delivery under single organizational umbrellas. MHRA post-Brexit regulatory divergence from EMA standards creates parallel submission requirements for hormone therapy approvals. The Cambridge-Oxford-London triangle anchors digital health platform development for remote patient monitoring.
Japan
PMDA oversight of menopause drug approvals shapes clinical trial endpoints for vasomotor symptom claims in the Japanese market. METI incentives for pharmaceutical manufacturing modernization support domestic production of hormone replacement formulations. The Kanto region around Tokyo concentrates specialist gynecology clinics and hospital outpatient services.
Australia
TGA approval standards for non-hormonal therapies influence portfolio prioritization for companies seeking Asia-Pacific market entry beyond Japan. Public hospital outpatient networks in New South Wales and Victoria are expanding menopause service capacity. The Sydney-Melbourne corridor anchors telehealth platform adoption for direct-to-patient prescription channels.
Menopause Market Key Industry Players
On the supply side, the industry is consolidating around established pharmaceutical conglomerates with legacy hormone therapy infrastructure and emerging specialists with targeted regulatory expertise. The competitive terrain separates into three strategic archetypes: diversified multinationals with wholesale health system relationships, mid-cap hormone therapy specialists with localized regulatory approvals, and consumer-facing supplement platforms with direct-to-patient distribution. Dominant competitive moves include portfolio diversification into non-hormonal alternatives and geographic expansion through centralized marketing authorization strategies.
Within the diversified multinational tier, Pfizer Inc. and Bayer AG exemplify archetypes built on established wholesale infrastructure and crossover therapeutic portfolios. Theramex occupies a position among the specialized hormone therapy developers, anchoring the mid-cap segment with formulation-focused regulatory strategies. Dr. Reddy's Laboratories Ltd. represents the generic and biosimilar manufacturing archetype, situating within cost-competitive supply chains serving volume markets. These three entities collectively illustrate the competitive spectrum without exhausting the participant base.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Bayer AG |
| GlaxoSmithKline PLC |
| Astellas Pharma Inc. |
| AbbVie Inc. |
| Pure Encapsulations LLC |
| Organon & Co |
| Theramex |
| Others |
Cost & Logistics Intelligence
Dutch cold-chain logistics infrastructure for hormone replacement therapies concentrates upstream pharmaceutical distribution capacity, anchoring margin capture in European wholesale networks and specialty pharmacy intermediaries serving hospital outpatient systems.
Pricing Analysis
Volume-discount tiering structures separate large health system procurement from retail pharmacy transactions across hormone replacement and non-hormonal therapeutic categories. Three-tier pricing stratifies across branded originators, authorized generics, and commodity alternatives, with FDA safety surveillance requirements and EMA centralized authorization sustaining premium tiers through regulatory differentiation. Cost compression in generic hormone formulations intensifies as Indian and Chinese API manufacturers expand capacity, while integrated women's health networks in the United States exhibit lowest price sensitivity due to formulary consolidation and bundled reimbursement mechanisms.
Supply Chain Analysis
Contract-manufacturing concentration for topical estrogen formulations sits with German and Swiss chemical processing specialists holding REACH-compliant excipient qualification. Active pharmaceutical ingredient production draws from Indian and Chinese manufacturing clusters, with synthetic estrogen precursors resting on petrochemical feedstock supply from the Rhine-Ruhr industrial region. Single-source vulnerability characterizes specialty excipient supply for transdermal patches, where ECHA registration requirements constrain supplier switching. Distribution runs through Dutch pharmaceutical wholesalers with cold-chain capability serving European hospital networks, while United States direct-to-patient channels bypass traditional wholesale markups through telehealth-integrated specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The menopause market functions as a service-attach opportunity where adherence monitoring and digital therapeutic companion applications expand recurring revenue faster than prescription product margins alone.
For Market Incumbents: Harden formulary positioning through backward integration into diagnostic service lines within United States hospital outpatient networks. Threats from direct-to-consumer telehealth platforms displacing traditional gatekeeper functions demand channel control investments in remote patient monitoring infrastructure. Certification investment in FDA Quality System Regulation compliance for software-as-medical-device companions represents a critical defensive lever. For New Entrants and Emerging Players: Australia's public hospital outpatient networks present underpenetrated capacity for non-hormonal therapy expansion, with TGA approval pathways offering faster commercialization timelines than FDA or EMA processes. White-space targets concentrate in genitourinary syndrome diagnostics where awareness gaps persist across outpatient settings. A go-to-market angle pairing symptom-tracking applications with localized hormone delivery systems captures patient initiation before traditional clinical presentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital therapeutic development as software validation costs displace clinical trial expenditure for hardware-centric interventions. Long-term viability across the analysis window favors platform plays integrating prescription workflows with real-world evidence generation capabilities. Acquisition target archetypes include telehealth infrastructure providers with existing women's health user bases. The signal to watch is FDA guidance evolution on software-as-medical-device classification for symptom management applications.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA's clarified non-hormonal pathway accelerates neurokinin receptor antagonist enrollment timelines. |
| Regulatory Approval Pathway | EMA centralized marketing authorization reduces redundant national submissions across European member states. |
| Manufacturing Scale-Up | REACH-compliant excipient sourcing expansion supports topical estrogen capacity for EU market entry. |
| Pipeline Diversification | Genitourinary syndrome therapeutic development addresses diagnostic awareness gaps in outpatient settings. |
| Strategic Partnership | Telehealth platform alliances with integrated women's health networks compress traditional referral pathways. |
Research Approach
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling triangulates against top-down pharmaceutical expenditure estimates across therapeutic categories and regional regulatory clusters.
Calibration approaches anchor volume and value outputs to historical prescription audit data and reimbursement rate benchmarks across the projection horizon. Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population risk stratification, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to approved therapy penetration rates and emerging candidate probability-weighted launch timelines, with clinical trial enrollment velocity and regulatory review duration serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer diagnostic platforms or non-hormonal therapy specialists would shift outcomes beyond modeled ranges. Regulatory divergence between FDA and EMA on software-as-medical-device classification and REACH compliance cost inflation represent specific revision risks. Quarterly review of clinical trial enrollment data and formulary exclusion list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Women's Health App Market
Women's Health
Women Health Software Market
Women's Health
Women Health Care Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
US Womens Health Market
Women's Health
Women's Digital Health Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Menstrual Health Apps Market
Women's Health
Women's Health Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women Health Devices Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Maternal Health Market