
 US Womens Health Market | 2026-2036
US Womens Health Market Size, Share, and Industry Trends Forecast 2026-2036
US Womens Health Market Insights
Specialty pharmacy distribution is reshaping how hormonal therapies and fertility biologics reach patients across the United States. Pfizer leverages its manufacturing scale to supply long-acting contraceptive formulations through closed-door pharmacy networks. Hologic anchors the diagnostic layer with imaging and molecular testing platforms deployed in outpatient settings. AbbVie competes through its therapeutic portfolio focused on endometriosis and uterine health conditions.
Women's health encompasses medical products, diagnostic systems, and digital services engineered to address reproductive biology, hormonal regulation, and sex-specific disease pathways, with formulations typically requiring bioequivalence studies and sterility assurance for parenteral delivery. Its primary commercial purpose centers on reducing morbidity from gynecologic cancers, managing fertility windows, and moderating menopausal symptom burden. Hormonal Therapies represent the most mature revenue pool, though margin compression from generic alternatives is redirecting investment toward AI-driven Diagnostics, where algorithm-enabled cervical cytology and breast imaging interpretation command premium reimbursement. Healthcare Apps targeting menopause symptom tracking and telehealth-guided fertility counseling are expanding fastest among technology segments, reflecting payer willingness to cover remote monitoring for chronic gynecologic conditions.
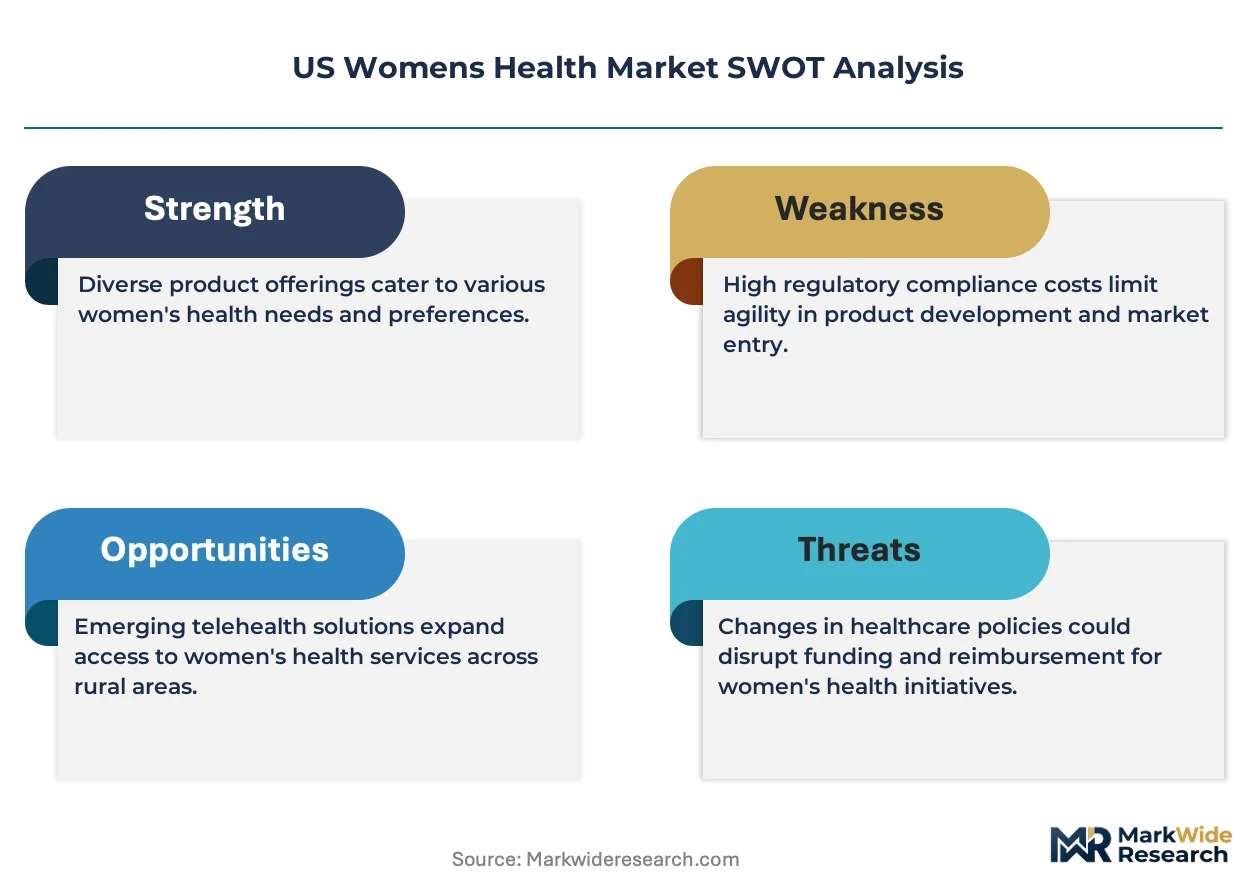
FDA oversees pharmaceutical and device approvals through its Center for Devices and Radiological Health and Office of Women's Health, while HIPAA governs data exchange across Telehealth Solutions and Mobile Health Platforms collecting reproductive health information. State-level Medicaid expansion decisions in states including California, New York, and Illinois directly determine access coverage for preventive screenings and contraceptive services. Stakeholders must monitor evolving FDA guidance on software as a medical device classification, as reclassification would reshape commercialization timelines and capital requirements for digital women's health entrants.
Market Dynamics
Hospital systems in Texas and California are consolidating women's health service lines into vertically integrated networks, capturing patient volume through dedicated ambulatory surgery centers and closed-loop referral pathways that lock in hormonal therapy and diagnostic testing revenue.
Growth Catalysts
- Medicaid Expansion:California, New York, and Illinois extended coverage for preventive screenings and contraceptive services, expanding addressable patient pools for ambulatory providers.
- FDA Software Pathways:Accelerated 510(k) clearances for digital therapeutics targeting menopause symptom management and fertility tracking are compressing commercialization timelines for software entrants.
- Telehealth Infrastructure:HIPAA-compliant platforms enabling remote monitoring of chronic gynecologic conditions now qualify for reimbursement in 42 states, shifting care delivery from inpatient to outpatient settings.
Market Restraints
- Generic Substitution:Long-acting contraceptive formulations face margin compression as bioequivalent alternatives enter through specialty pharmacy distribution channels.
- Reimbursement Variability:State-level Medicaid fragmentation creates coverage gaps for molecular diagnostic testing, limiting Hologic's platform deployment in non-expansion states.
- Clinical Validation Burden:AI-enabled cervical cytology algorithms require extensive training datasets across diverse populations, slowing algorithmic deployment in community health settings.
Strategic Opportunities
- Rural Network Gaps:Federally Qualified Health Centers in Texas and Florida lack dedicated women's health specialists, creating white space for telehealth-guided fertility counseling platforms.
- Menopause Digital Therapeutics:FDA's evolving guidance on software as a medical device classification may reclassify symptom-tracking apps as reimburable medical devices.
- Hybrid Care Models:Integration of at-home hormone monitoring with specialist consultation is penetrating employer-sponsored insurance plans in the Midwest.
Industry Challenges
- Interoperability Friction:Reproductive health data exchange between HIPAA-governed telehealth platforms and hospital EHR systems requires costly API development.
- Talent Scarcity:Maternal-fetal medicine specialists concentrate in academic medical centers, constraining expansion of high-risk pregnancy services into community settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Womens Health Market |
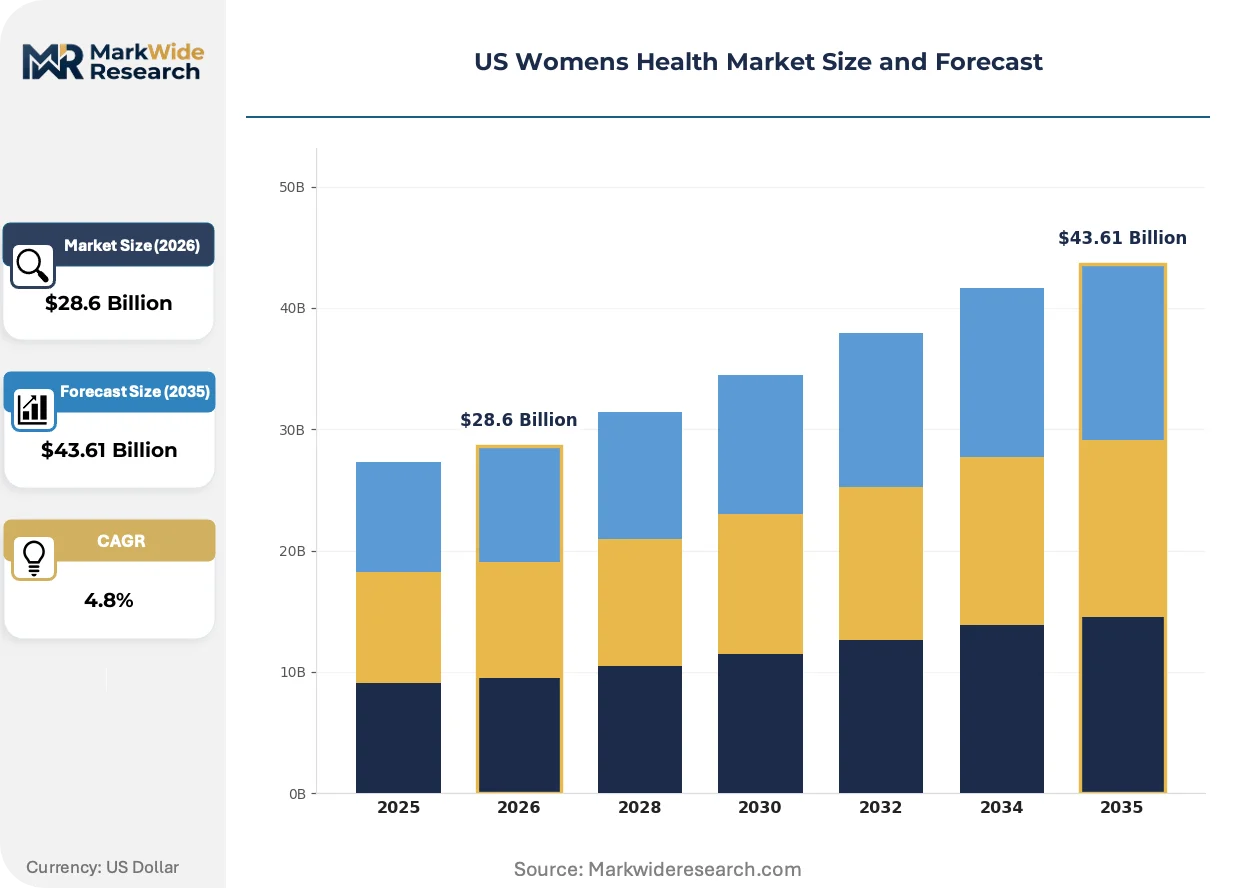
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Nutritional Supplements, Diagnostic Devices, Healthcare Apps Application: Menopause Management, Reproductive Health, Fertility Treatment, Preventive Care End User: Clinics, Hospitals, Homecare, Wellness Centers Technology: Wearable Devices, Telehealth Solutions, Mobile Health Platforms, AI-driven Diagnostics |
| Companies Covered | Bayer AG, Pfizer, AbbVie, Merck & Co., Amgen, Hologic, Roche, Boston Scientific Corporation, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Womens Health Market Trends and Innovations
Algorithmic interpretation of diagnostic imaging and biomarker data is compressing specialist labor requirements while expanding screening accessibility across underserved geographies and payer segments.
AI-enabled breast imaging analysis is migrating from academic medical centers to community radiology practices as cloud deployment models reduce infrastructure requirements. Regional hospital systems in Texas and Arizona are adopting these tools to address radiologist staffing shortages. The technology is compressing interpretation turnaround times from days to hours, enabling same-day diagnostic pathways that lock in patient retention.
FDA's Office of Women's Health issued draft guidance clarifying software as a medical device boundaries for fertility-tracking applications, creating regulatory certainty for digital therapeutic developers. The framework distinguishes wellness applications from diagnostic devices based on intended use claims and risk profiles. Menopause symptom management platforms with algorithmic treatment recommendations face reclassification scrutiny, prompting firms to adjust commercialization strategies.
Employer-sponsored health plans are unbundling fertility benefits from traditional medical coverage, creating dedicated spending categories for egg freezing and in-vitro fertilization. Large self-insured employers in technology and financial services sectors are contracting directly with specialty pharmacy networks for hormonal therapy distribution. This procurement evolution is most visible in California and Massachusetts, where talent competition drives comprehensive reproductive health benefit expansion.
US Womens Health Market Segmentation
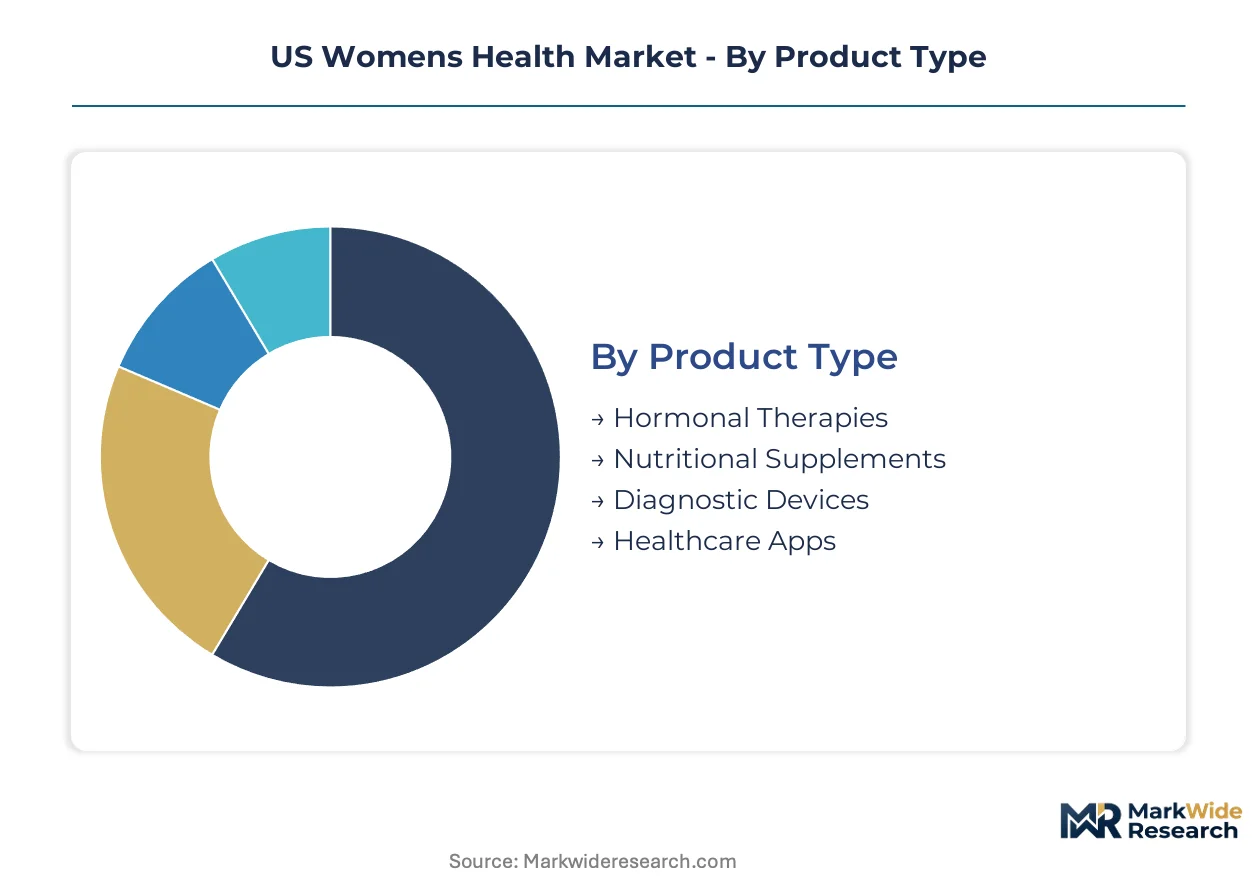
Segmentation in the US women's health market reveals distinct procurement rhythms and reimbursement profiles across product categories. Hospital systems, specialty pharmacies, and direct-to-consumer channels each favor different segment combinations based on formulary control, regulatory pathway, and patient acquisition economics.
Product Type:
Hormonal Therapies turn inventory fastest through closed-door specialty pharmacy networks, while Healthcare Apps exhibit the longest commercialization cycles pending FDA software classification decisions.
- Hormonal Therapies:Long-acting contraceptive formulations and menopausal hormone replacement products manufactured under sterility assurance protocols. Texas and California health systems anchor procurement volume through closed-loop specialty pharmacy contracts, though generic bioequivalent entry compresses margins.
- Healthcare Apps:Software-based platforms for symptom tracking, fertility monitoring, and telehealth-guided counseling requiring HIPAA-compliant architecture. FDA's evolving guidance on software as a medical device classification determines reimbursement eligibility, with 42 states now covering remote monitoring for chronic gynecologic conditions.
- Nutritional Supplements:Over-the-counter prenatal vitamins and menopause-support formulations distributed through retail pharmacy and direct-to-consumer channels.
- Diagnostic Devices:Imaging systems and molecular testing platforms deployed in outpatient settings, with Hologic anchoring supply through regional hospital networks.
Hormonal Therapies anchors the volume base while Healthcare Apps gains share at the steepest rate.
Application:
Cost tier stratification separates institutional reimbursement pathways from out-of-pocket spending categories across the four application areas.
- Menopause Management:Symptom mitigation through hormonal and non-hormonal interventions, with employer-sponsored plans in California and Massachusetts unbundling dedicated spending categories. Digital therapeutic entrants target this segment for FDA 510(k) clearance acceleration.
- Preventive Care:Cervical cytology, breast imaging, and routine screening services reimbursed through Medicaid expansion states including California, New York, and Illinois.
- Reproductive Health:Contraceptive services and gynecologic condition management delivered through Federally Qualified Health Centers and ambulatory surgery centers.
- Fertility Treatment:Egg freezing, in-vitro fertilization, and hormonal stimulation protocols concentrated in self-insured employer plans within technology and financial services sectors.
Preventive Care absorbs the highest institutional reimbursement volume while Menopause Management climbs fastest as digital therapeutic coverage expands.
End User:
Patient acuity and care setting determine procurement authority, with Hospitals controlling high-complexity diagnostics and Homecare channels capturing chronic condition monitoring.
- Hospitals:Academic medical centers and regional systems in Texas and California consolidate women's health service lines, capturing diagnostic testing and surgical volume through vertically integrated networks.
- Homecare:At-home hormone monitoring and telehealth-guided consultation penetrating employer-sponsored insurance plans in the Midwest, with HIPAA-compliant platforms enabling remote chronic gynecologic management.
- Clinics:Community-based providers and ambulatory surgery centers handling routine procedures and preventive screenings.
- Wellness Centers:Direct-to-consumer service providers offering fertility counseling and menopause support outside traditional medical reimbursement.
Hospitals command the highest per-patient revenue while Homecare extends reach most rapidly into previously underserved geographies.
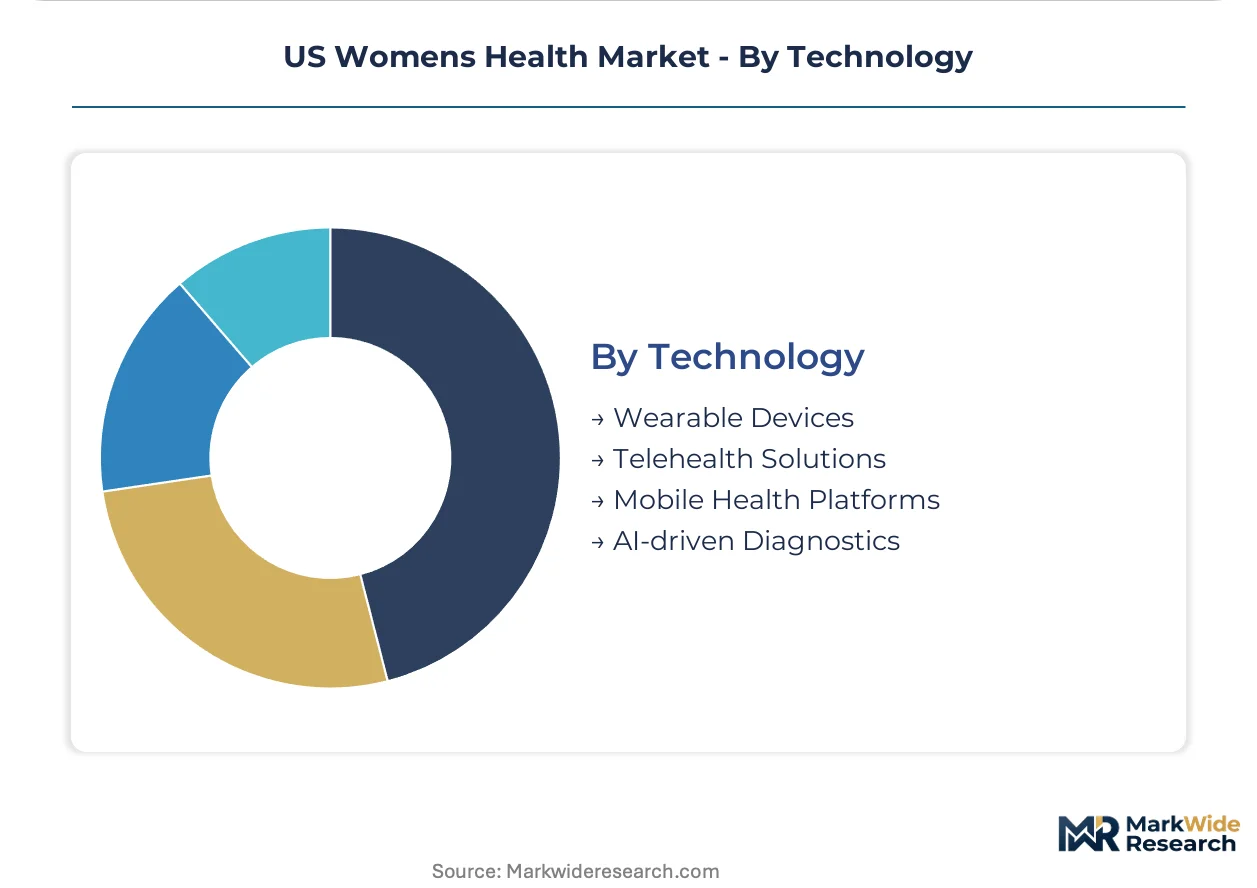
Technology:
Development maturity separates deployed platforms from emerging categories awaiting clinical validation and regulatory clarity.
- AI-driven Diagnostics:Algorithm-enabled cervical cytology and breast imaging interpretation migrating from academic centers to community radiology practices. Cloud deployment models reduce infrastructure requirements, with Texas and Arizona hospital systems adopting these tools to address radiologist staffing shortages.
- Telehealth Solutions:HIPAA-governed platforms for remote specialist consultation and chronic condition monitoring, with reimbursement now available across 42 states.
- Mobile Health Platforms:Smartphone-based applications for fertility tracking and symptom logging, with FDA's Office of Women's Health distinguishing wellness from diagnostic device classification.
- Wearable Devices:Continuous hormone monitoring and physiological tracking hardware integrated with specialist consultation workflows.
Telehealth Solutions carries the broadest reimbursement coverage while AI-driven Diagnostics scales most quickly from academic to community settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Office of Women's Health anchors regulatory oversight for the dominant US market, with state-level Medicaid expansion decisions fragmenting access coverage across sub-regional health systems and ambulatory networks.
California
Medi-Cal expansion drives preventive screening volume through Federally Qualified Health Centers in Los Angeles and San Francisco Bay Area corridors. State mandates require contraceptive coverage without cost-sharing, expanding addressable pools for hormonal therapy distribution. Kaiser Permanente and Sutter Health anchor vertically integrated women's health networks capturing diagnostic and surgical volume.
Texas
Large health systems including HCA Houston Healthcare and Baylor Scott & White consolidate dedicated women's health service lines across Dallas-Fort Worth and Houston metros. State Medicaid restrictions limit contraceptive access coverage, redirecting demand toward employer-sponsored plans and cash-pay fertility services. Ambulatory surgery centers cluster along the I-35 corridor specializing in gynecologic procedures.
New York
Medicaid expansion under the Essential Plan extends reproductive health coverage through NYC Health + Hospitals and Northwell Health networks. State regulations mandate coverage for fertility preservation services, attracting employer plan unbundling in Manhattan and Brooklyn. Academic medical centers including Mount Sinai and NYU Langone anchor high-risk pregnancy referral pathways.
Illinois
Medicaid expansion drives preventive care volume through Cook County Health and Advocate Aurora systems in Chicago metro. State policy mandates coverage for contraceptive and menopause management services, expanding telehealth reimbursement for remote gynecologic monitoring. Northwestern Medicine anchors molecular diagnostic testing deployment across the Great Lakes region.
Massachusetts
Employer-sponsored benefit unbundling concentrates fertility services procurement among technology and financial services firms in Boston and Cambridge. State regulations mandate coverage for in-vitro fertilization and egg freezing, driving direct contracting with specialty pharmacy networks. Mass General Brigham and Beth Israel Lahey Health anchor academic referral pathways for complex gynecologic conditions.
US Womens Health Market Competitive Landscape
Pharmaceutical incumbents and diagnostic platform specialists split the market across therapeutic and technology layers. Consolidation concentrates around manufacturers with sterility-assured parenteral capacity and algorithm-enabled imaging interpretability. Three archetypes dominate: large-cap diversified pharmas with hormonal therapy portfolios, diagnostic platform vendors with molecular testing scale, and digital therapeutic entrants pursuing FDA software classification. Competitive moves center on specialty pharmacy network capture and AI-enabled diagnostic deployment into community settings.
Among large-cap pharmaceutical anchors, Bayer AG and Pfizer occupy positions spanning contraceptive and menopausal hormone formulations. AbbVie sits within the therapeutic specialist tier focused on endometriosis and uterine health conditions. Hologic anchors the diagnostic platform archetype through imaging and molecular testing systems deployed across regional hospital networks. These named entities exemplify the strategic segmentation between therapeutic manufacturing scale and diagnostic technology integration.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer |
| AbbVie |
| Merck & Co. |
| Amgen |
| Hologic |
| Roche |
| Boston Scientific Corporation |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in sterility-assured parenteral manufacturing across the US Midwest and Northeast drives both supplier consolidation behavior and premium pricing posture for hormonal therapy formulations, with FDA-registered contract manufacturers commanding extended lead times and selective customer allocation.
Pricing Analysis
Geographic price spreads between Texas and Massachusetts fertility service markets exceed those between branded and generic hormonal therapies in the same corridor. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales clinical support intensity. Pricing pressure stems from generic bioequivalent entry into long-acting contraceptive categories. Employer-sponsored plans in technology sectors show lowest price sensitivity, while Federally Qualified Health Centers operate under strict formulary budget constraints.
Supply Chain Analysis
Extended payment terms from specialty pharmacy distributors to hormonal therapy manufacturers now stretch beyond 90 days, reflecting working capital pressure downstream. Active pharmaceutical ingredient production draws from India, China, and Ireland, with finished formulation capacity concentrated in Puerto Rico and the continental US. Supply chain risk centers on single-source vulnerability for high-potency estrogen analogs. Distribution runs through closed-door specialty pharmacy networks anchored by regional health system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with FDA software classification clarity for menopause digital therapeutics accelerating reimbursement tailwinds and compressing commercialization timelines for algorithm-enabled entrants.
For Market Incumbents: Harden formulary control through captive specialty pharmacy contracting in Texas and California health systems, where vertical integration locks in hormonal therapy volume. Deepen backward integration into sterility-assured parenteral manufacturing capacity to offset API cost volatility. Defend diagnostic platform share by embedding AI-enabled cytology algorithms into hospital EHR workflows, creating switching costs against emerging imaging entrants.
For New Entrants and Emerging Players: Establish a beachhead in employer-sponsored menopause management benefits, where unbundled fertility spending categories create procurement openness absent in traditional medical coverage. Target Federally Qualified Health Centers in Florida and Texas for telehealth-guided fertility counseling platforms, exploiting specialist scarcity in rural networks. Lead with HIPAA-compliant remote monitoring architectures that qualify for reimbursement across 42 states.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital therapeutic developers with FDA 510(k) clearances for chronic gynecologic condition management, where subscription models displace episodic fee-for-service capture. Long-term viability favors platforms integrating at-home diagnostics with specialist consultation workflows. Monitor FDA Office of Women's Health guidance publication as inflection signal for software reclassification and reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for menopause symptom management platforms seeking device classification. |
| Hospital System Partnership | Locks in diagnostic testing volume through vertically integrated referral pathways in Texas and California networks. |
| Specialty Pharmacy Network Capture | Secures distribution control for hormonal therapies through closed-door contracts with regional health systems. |
| Software Companion Development | Enables AI-enabled interpretation of cervical cytology and breast imaging to migrate from academic to community settings. |
| Reimbursement Strategy | Expands addressable patient pools by qualifying telehealth platforms for Medicaid and employer plan coverage across 42 states. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement databases, hospital GPO contracts, and state Medicaid expansion policy documents. Interviews with formulary directors at specialty pharmacy networks, regulatory affairs leads at digital therapeutic developers, biomedical engineers at diagnostic platform vendors, and clinicians at academic medical centers informed demand-side validation. Bottom-up patient volume modeling and top-down health system expenditure analysis were triangulated against manufacturer shipment data.
Forecast inputs include treatment line progression curves, dosage form substitution elasticities, patient population segmentation by payer type, and regional regulatory cluster adoption patterns across the analysis window. Segmentation dimensions encompass product type, application, end user, and technology deployment maturity. CAGRs were derived from slope-intercept modeling of historical revenue trajectories adjusted for pipeline conversion probabilities and reimbursement expansion scenarios.
Stress conditions across generic entry timing, FDA software reclassification decisions, and state Medicaid fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway clarity and payer behavior stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Mother and Child Healthcare Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Maternal Health Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Menstrual Health Apps Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women's Digital Health Market
Women's Health
Women Health Software Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Care Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women Health Devices Market
Women's Health
Women's Health App Market