
 Global 3D Ics Market | 2026-2036
Global 3D Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Ics Market Foresight
ISO 26262 automotive functional safety qualification is collapsing the supplier pool for automotive-grade 3D ICs. Taiwan Semiconductor Manufacturing Company dominates advanced TSV foundry output for high-performance computing. Samsung Electronics anchors memory-centric die stacking through its vertical NAND and HBM portfolios. Intel Corporation differentiates via Foveros direct bonding technology for client and server processor tiles.
3D ICs integrate multiple semiconductor dies into vertically stacked architectures using through-silicon vias, microbumps, or hybrid bonding to achieve higher interconnect density and reduced signal latency than planar integration. Through-Silicon Via technology leads in high-bandwidth memory applications where pitch scaling below ten micrometers enables processor-memory coherence. Fan-Out Packaging captures expanding margin pools in mobile and automotive RF modules where substrate cost reduction and form-factor miniaturization drive substitution from traditional flip-chip. Wafer-Level Packaging sustains volume leadership in image sensor and power management integration for consumer electronics.
FDA oversight of diagnostic imaging equipment and NHTSA crashworthiness standards for autonomous systems shape reliability requirements for aerospace avionics and automotive systems applications. ECHA REACH restrictions on lead-based solders and EU RoHS substance limits accelerate copper-pillar and sintered-silver interconnect transitions across European-bound supply chains. METI's semiconductor resilience policies in Japan reinforce domestic advanced packaging capacity for telecommunications equipment. Stakeholders must monitor how export control harmonization across US Bureau of Industry and Security, EU dual-use regulations, and Japan's METI end-user screening affects equipment access for China-bound expansion plans.
Market Dynamics
Memory-intensive data center operators are compressing procurement timelines for vertically stacked logic as China's dual carbon goals and stricter semiconductor efficiency mandates accelerate the obsolescence of legacy planar processes.
Growth Catalysts
- Dual carbon goals:China's binding carbon neutrality targets are forcing foundries to retire power-hungry planar fabrication lines ahead of schedule, redirecting capex toward 3D stacking capacity.
- HBM penetration:High-bandwidth memory modules using through-silicon via interconnects are capturing share in AI training clusters where processor-memory bandwidth bottlenecks throttle model scaling.
- Automotive functional safety:ISO 26262 qualification requirements are collapsing the supplier pool for automotive-grade 3D ICs, concentrating orders among certified foundries and packaging houses.
Market Restraints
- TSV yield volatility:Through-silicon via formation and filling processes exhibit defect rates that compound exponentially with stack height, elevating effective wafer costs above planar equivalents.
- Equipment concentration:Advanced hybrid bonding and TSV etch tools concentrate among a narrow base of Japanese and European equipment suppliers, creating procurement bottlenecks for capacity expansions.
- Thermal dissipation limits:Vertically stacked architectures face heat extraction constraints that throttle clock speeds in high-performance computing applications, capping performance gains.
Strategic Opportunities
- India packaging corridors:The country's semiconductor PLI scheme and Gujarat Dholera semiconductor ecosystem are attracting advanced packaging joint ventures targeting domestic telecommunications and defense demand.
- Hybrid bonding convergence:The intersection of die-to-wafer hybrid bonding with chiplets-based processor disaggregation is opening sub-micron pitch interconnect applications previously reserved for monolithic integration.
- EU Green Deal alignment:REACH restrictions on lead-based solders and RoHS substance limits are accelerating copper-pillar and sintered-silver transitions, favoring European-bound supply chain reconfigurations.
Industry Challenges
- Multi-physics simulation talent:The scarcity of engineers capable of modeling thermo-mechanical stress across heterogeneous die stacks is extending product qualification timelines.
- CoWoS capacity allocation:Foundry-level chip-on-wafer-on-substrate bottlenecks are forcing fabless designers into binding capacity reservation contracts that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Ics Market |
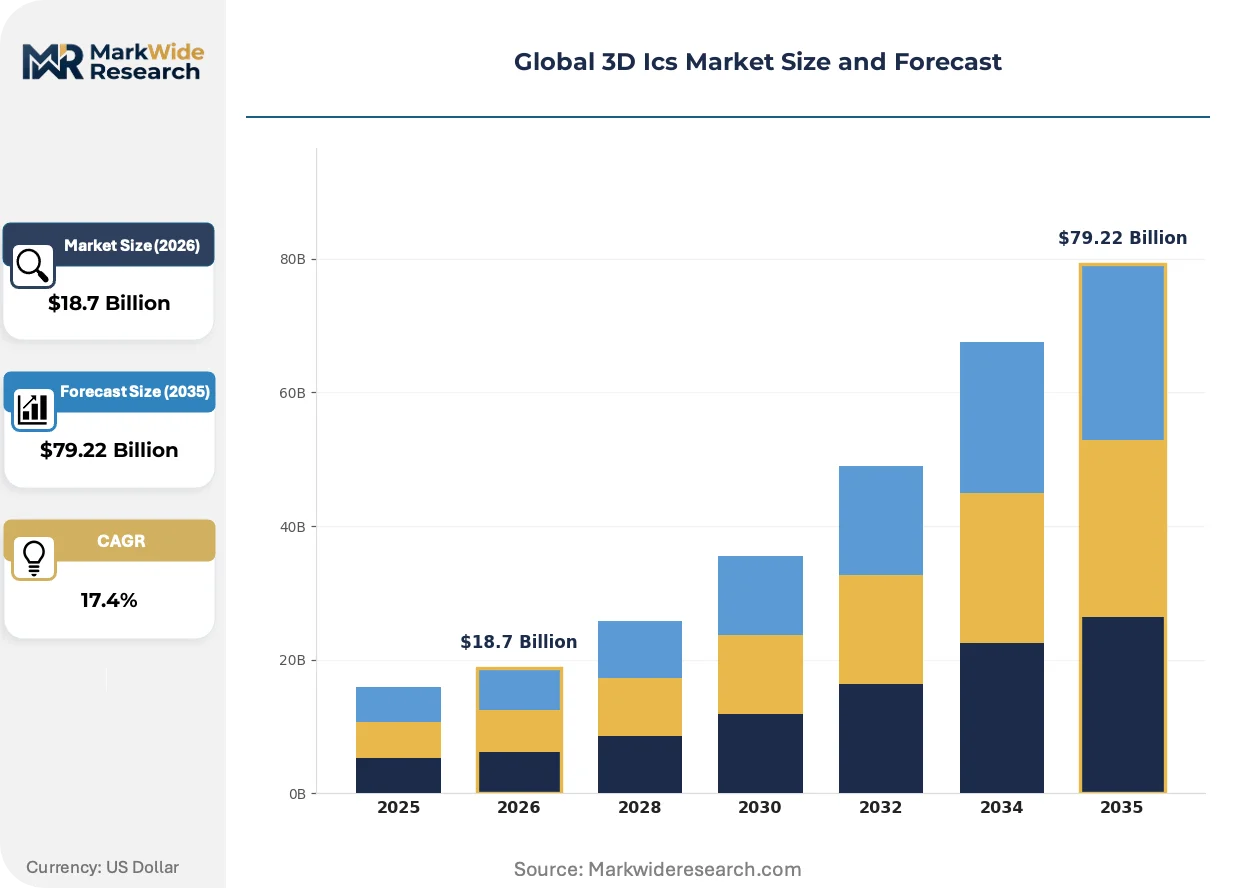
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: System-in-Package, Chip-on-Wafer, Through-Silicon Via, Wafer-Level Packaging Technology: Wafer Bonding, TSV Integration, Die Stacking, Microbump Interconnect, Fan-Out Packaging Application: Consumer Electronics, Telecommunications Equipment, Automotive Systems, Aerospace Avionics, Industrial Automation End User: OEMs, Foundries, Test & Assembly Services, Semiconductor Design Houses |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics, Intel Corporation, Advanced Semiconductor Engineering, Micron Technology, SK Hynix, GlobalFoundries, STMicroelectronics, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Ics Market Shifts & Advancements
Hybrid bonding technology is compressing interconnect pitch below ten micrometers, enabling processor-memory coherence architectures that planar integration cannot replicate. Three developments are restructuring competitive positioning.
Hybrid bonding is displacing microbump-based stacking in high-performance computing die-to-wafer applications where pitch scaling demands exceed thermocompression limits. NVIDIA and AMD accelerator roadmaps now specify hybrid bonding for next-generation HBM stacks, forcing packaging subcontractors to retrofit cleanroom infrastructure for sub-micron alignment accuracy. This displacement is concentrating advanced packaging margin capture among equipment suppliers capable of delivering angstrom-level placement precision.
ECHA REACH restrictions on lead-based solders and EU RoHS substance limits are accelerating copper-pillar and sintered-silver interconnect transitions across European-bound supply chains. Automotive and industrial equipment manufacturers serving EU markets must requalify assembly processes ahead of 2026 substance threshold deadlines, compressing supplier transition timelines. German automotive tier-1 suppliers are prioritizing sintered-silver die-attach for power module applications to preempt compliance exposure.
Data center operators are consolidating procurement authority for vertically stacked logic into centralized silicon engineering teams that bypass traditional component distribution channels. Hyperscale cloud providers in the United States and China are issuing binding multi-year foundry commitments directly, disintermediating legacy semiconductor distributors. This concentration is visible most acutely in Taiwan's Hsinchu Science Park corridor where foundry and packaging ecosystems co-locate to serve direct procurement relationships.
Global 3D Ics Market Segmentation
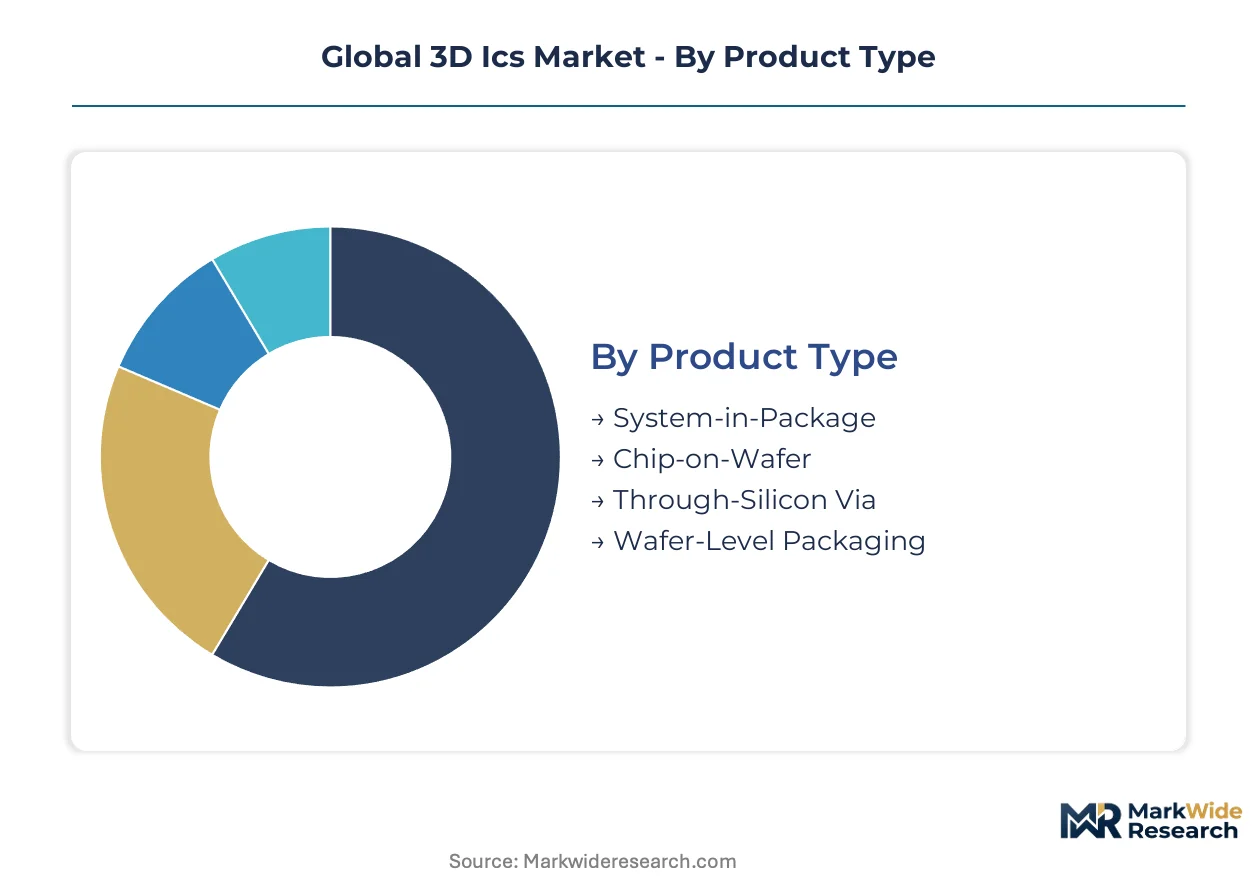
Vertical integration complexity in 3D ICs fragments procurement channels across product architectures, bonding technologies, application verticals, and end-user categories. Channel configuration directly shapes margin capture, with foundry-direct relationships displacing traditional distribution in high-performance computing while assembly services retain intermediary roles in cost-sensitive consumer segments.
Product Type:
Channel mix varies sharply: foundries and OSATs dominate Through-Silicon Via and Chip-on-Wafer procurement, while System-in-Package flows through broader component distribution serving mid-tier OEMs.
- Through-Silicon Via:Vertical interconnects penetrating full wafer thickness enable high-bandwidth memory-to-processor stacking. Procurement concentrates in Taiwan's Hsinchu corridor where foundry and packaging ecosystems co-locate to serve direct hyperscale commitments.
- System-in-Package:Multi-die integration in molded substrates serves mobile RF and sensor fusion applications where form-factor constraints override bandwidth requirements. Demand flows through semiconductor distributors serving mid-volume OEMs in South Korea and Japan.
- Chip-on-Wafer:Die-to-wafer bonding for HBM and logic-on-logic stacks. Procurement runs through foundry-level capacity reservation contracts.
- Wafer-Level Packaging:Redistribution layers and bumping for image sensors and power management ICs. Volume channels through OSATs serving consumer electronics OEMs.
By volume, Wafer-Level Packaging leads. By growth pace, Through-Silicon Via is climbing the fastest.
Technology:
Cost tier stratification separates premium hybrid bonding from mainstream microbump interconnect, with capital intensity determining foundry versus OSAT channel alignment.
- Wafer Bonding:Direct oxide or metal fusion at sub-micron pitch enables highest interconnect density for AI accelerators. Premium tier procurement locks into TSMC and Samsung captive capacity with multi-year binding commitments.
- Fan-Out Packaging:RDL-first embedding of dies in molded reconstituted wafers reduces substrate cost for mobile and automotive RF modules. Standard tier volume flows through ASE and Amkor serving price-sensitive OEMs.
- TSV Integration:Via formation, isolation, and filling processes for vertical interconnects. Foundry-direct channel for HBM, OSAT channel for CIS.
- Die Stacking:Sequential or simultaneous bonding of thinned wafers or dies. Procurement splits by pitch requirement.
- Microbump Interconnect:Solder or copper-pillar bumps at 20-40 micrometer pitch. Economy tier for legacy consumer and industrial applications.
WTSV Integration commands the steepest expansion trajectory as HBM penetration accelerates. Microbump Interconnect retains volume leadership in unit terms.
Application:
Customer type dictates channel structure: hyperscale direct procurement for telecommunications, tiered distribution for consumer electronics, and qualified supplier lists for automotive and aerospace.
- Telecommunications Equipment:Baseband processors and optical transceivers for 5G infrastructure demand 3D stacking for bandwidth density. Procurement centralizes in direct foundry relationships serving Huawei, Ericsson, and Nokia engineering teams.
- Automotive Systems:ADAS sensor fusion and domain controllers require ISO 26262-qualified 3D ICs. Supply concentrates among certified packaging houses with tier-1 supplier gatekeeping.
- Consumer Electronics:Smartphones, wearables, and tablets drive System-in-Package and Fan-Out volume. Channels through broadline distributors serving ODMs.
- Aerospace Avionics:Radiation-hardened and high-reliability 3D stacks for satellite and defense applications. Procurement via qualified supplier lists with long qualification cycles.
- Industrial Automation:Motor drives and PLCs adopting power module 3D integration. Channels through industrial component specialists.
Consumer Electronics maintains volume dominance. Telecommunications Equipment is gaining share fastest on 5G and AI training cluster buildouts.
End User:
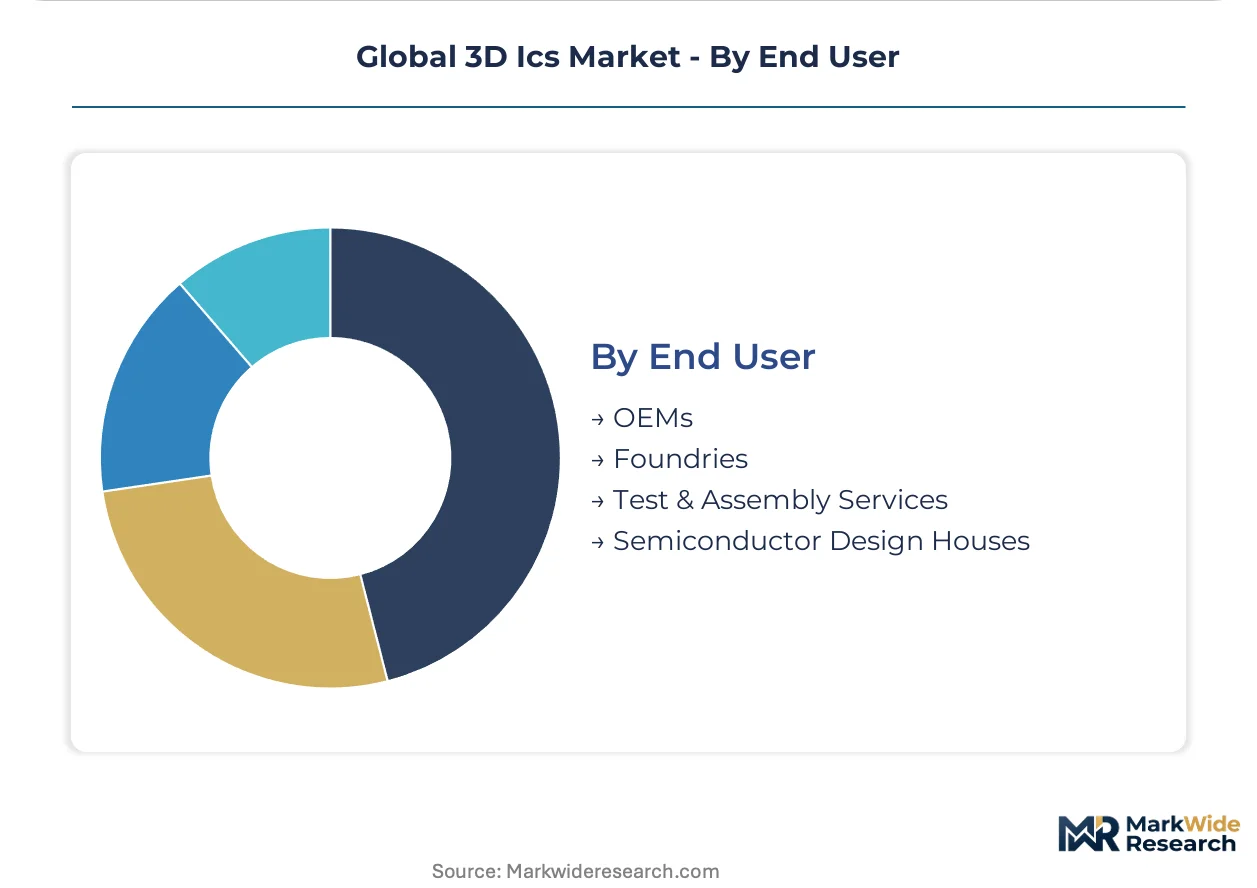
Margin concentration aligns with supply chain position: foundries capture value in advanced bonding, design houses extract rents in chiplet architectures, while test and assembly services compete on scale economies.
- Foundries:TSMC, Samsung, and Intel internalize advanced packaging for process-node differentiation. Captive 3D IC output serves direct hyperscale and fabless semiconductor relationships.
- Semiconductor Design Houses:AMD, NVIDIA, and Broadcom specify 3D architectures and procure foundry capacity. Value capture shifts upstream to chiplet and HBM interface IP.
- OEMs:Apple, Tesla, and cloud operators issue binding silicon engineering requirements. Direct procurement teams bypass traditional component distribution.
- Test & Assembly Services:ASE, Amkor, and JCET provide outsourced packaging for mid-tier fabless designers. Scale-driven competition compresses margins.
By revenue contribution, Foundries lead. By expansion rate, Semiconductor Design Houses are pulling ahead on chiplet disaggregation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals are forcing foundries to retire power-hungry planar fabrication lines ahead of schedule, redirecting capital expenditure toward 3D stacking capacity across multiple jurisdictions.
China
Memory-intensive data center operators in Beijing and Shanghai are compressing procurement timelines for vertically stacked logic. MIIT semiconductor efficiency mandates are accelerating the obsolescence of legacy planar processes. Yangtze River Delta clusters around Hsinchu Science Park corridor serve direct hyperscale procurement relationships.
United States
Hyperscale cloud providers are issuing binding multi-year foundry commitments directly, disintermediating legacy semiconductor distributors. NHTSA crashworthiness standards for autonomous systems shape reliability requirements for automotive-grade 3D ICs. Greater Boston and Pacific Northwest engineering teams specify chiplet architectures for AI training clusters.
Taiwan
Foundry and packaging ecosystems co-locate to serve direct procurement relationships from fabless semiconductor design houses. The country's semiconductor resilience policies reinforce domestic advanced packaging capacity for telecommunications equipment. Hsinchu Science Park anchors vertically stacked logic output for high-performance computing applications.
South Korea
Memory-centric die stacking anchors vertical NAND and HBM portfolios serving AI accelerator roadmaps. MFDS regulatory frameworks influence component qualification timelines for domestic telecommunications OEMs. Seoul Capital Area packaging houses retrofit cleanroom infrastructure for sub-micron alignment accuracy.
Japan
METI semiconductor resilience policies reinforce domestic advanced packaging capacity for telecommunications equipment. JIS standards govern interconnect reliability requirements for industrial automation applications. Kyushu and Kanto clusters concentrate equipment suppliers capable of delivering angstrom-level placement precision.
Global 3D Ics Market Competitive Landscape
Player mix skews toward integrated foundries with captive advanced packaging capabilities. Taiwan Semiconductor Manufacturing Company, Samsung Electronics, and Intel Corporation internalize 3D IC output for process-node differentiation. Three strategic archetypes dominate: foundry-integrated packaging houses, memory-centric vertical integrators, and fabless semiconductor design houses specifying architectures. Competitive moves concentrate on multi-year binding capacity reservation contracts and cleanroom infrastructure retrofitting for hybrid bonding convergence.
Among integrated foundries, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify the premium-tier vector where captive 3D IC output serves direct hyperscale relationships. Intel Corporation occupies a position within the hybrid bonding specialization tier, representing technology differentiation through direct bonding architectures for processor tiles. These three anchors illustrate how foundry-level consolidation around advanced packaging capabilities is compressing margin structures for mid-tier assembly services while concentrating value capture upstream.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics |
| Intel Corporation |
| Advanced Semiconductor Engineering |
| Micron Technology |
| SK Hynix |
| GlobalFoundries |
| STMicroelectronics |
| NVIDIA Corporation |
| Others |
Supply & Pricing Matrix
TSMC's Hsinchu Science Park wafer fab utilization rates above ninety percent create asymmetric pricing power for advanced packaging slots, compressing margin structures for mid-tier OSATs while elevating cost floors for fabless designers locked into multi-year capacity reservation contracts.
Pricing Analysis
Certification level (ISO 26262 automotive-grade versus industrial-grade) creates the primary spread, with automotive-qualified 3D ICs commanding substantial premiums over consumer-tier equivalents. Contract-based long-term offtake agreements dominate high-performance computing procurement, while spot-market flexibility persists in consumer electronics segments. Cost compression in mid-tier microbump interconnect is intensifying because ASE and Amkor compete on scale economies for mobile RF module business. Consumer electronics OEMs exhibit highest price sensitivity, whereas hyperscale cloud operators demonstrate lowest sensitivity due to performance-per-watt optimization priorities.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and advanced packaging output, with Japan supplying critical TSV etch and hybrid bonding equipment. Silicon wafers, high-purity specialty gases, and sub-micron alignment systems constitute essential inputs that draw from concentrated supplier bases. Single-source vulnerability in angstrom-level placement equipment creates procurement bottlenecks for capacity expansions. Distribution runs through foundry-direct channels for high-performance computing, while broadline semiconductor distributors retain intermediary roles in cost-sensitive consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid bonding convergence with chiplet architectures is disrupting monolithic integration economics, creating asymmetric value capture opportunities for equipment suppliers and foundries with captive advanced packaging capabilities.
For Market Incumbents: Compound defensive moats through backward integration into sintered-silver interconnect materials and captive supply of sub-micron alignment equipment. Expand Hsinchu Science Park adjacent capacity to preempt CoWoS allocation bottlenecks threatening margin structures. ISO 26262 certification depth serves as the priority lever for automotive-grade supplier pool consolidation.
For New Entrants and Emerging Players: Differentiate on India packaging corridor joint ventures targeting domestic telecommunications and defense demand under PLI scheme incentives. Penetrate Gujarat Dholera ecosystem white-space before incumbent foundries establish captive operations. Lead with sintered-silver die-attach specialization for EU-bound automotive power modules facing REACH RoHS transition deadlines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment suppliers capable of delivering angstrom-level placement precision for hybrid bonding retrofit cycles. Five-to-ten year viability hinges on exposure to AI training cluster capex rather than consumer electronics cyclicality. Monitor NVIDIA and AMD accelerator roadmap specifications as inflection indicators for packaging subcontractor cleanroom investment triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Cleanroom Retrofit | Sub-micron alignment accuracy enables TSMC and Samsung to capture HBM stack margins from OSATs. |
| Sintered-Silver Interconnect Transition | German automotive tier-1 suppliers preempt ECHA REACH compliance exposure in power module assembly. |
| India PLI Joint Venture Formation | Gujarat Dholera ecosystem attracts advanced packaging capacity for domestic telecommunications OEMs. |
| CoWoS Capacity Reservation Contract | Hyperscale cloud providers lock in Taiwan foundry output, disintermediating legacy semiconductor distributors. |
| ISO 26262 Certification Investment | Automotive-grade 3D IC supplier pool collapse concentrates orders among qualified packaging houses. |
Research Methodology
Operator-level perspectives from foundry packaging engineers, OSAT procurement directors, fabless semiconductor design leads, and automotive tier-1 supplier quality managers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings, hyperscaler capex disclosures, SEMI equipment shipment data, and MIIT semiconductor efficiency mandate documentation. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates across the analysis window.
Sensitivity analysis tested forecast robustness against TSV yield volatility scenarios and equipment procurement bottleneck assumptions. Modeled dimensions span product architecture, bonding technology tier, application vertical, and end-user category throughout the projection horizon. CAGRs derived from segment-level growth rate synthesis and input-output modeling of semiconductor capital expenditure cycles. HBM penetration curves and dual carbon policy implementation timelines served as industry-specific forecast inputs.
Material uncertainties — export control harmonization shifts, thermal dissipation limit breakthroughs, and multi-physics simulation talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding foundry capacity allocation patterns and automotive qualification timeline compression. Recalibration cycles align with material shifts in MIIT efficiency mandates and hybrid bonding equipment delivery schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market