
 China Analog IC Market | 2026-2036
China Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
China Analog IC Market Insights
Foundry-backed project financing is tilting competitive dynamics toward capital-intensive domestic players. Silan Microelectronics leverages captive wafer capacity to sustain cost advantages across voltage regulator lines. Hua Hong Semiconductor anchors its position through 12-inch analog-dedicated foundry services for fabless designers. 3PEAK Incorporated specializes in precision signal conditioning for industrial automation clients.
China Analog IC denotes semiconductor devices processing continuous electrical signals with parameters such as bandwidth, slew rate, and noise figure defining performance boundaries. These components enable power management, sensor interfacing, and signal conversion across electronic systems where digital processing remains impractical. Voltage regulators and power management applications command the deepest margin pools as automotive electronics and telecommunications infrastructure scale procurement. CMOS technology dominates unit volumes while BiCMOS variants capture premium positioning in high-frequency signal conditioning segments. Operational amplifiers retain mature, stable demand patterns compared with faster-growing data acquisition applications serving smart factory deployments.
SAMR enforces quality certification for automotive-grade analog ICs while MIIT channels subsidies toward domestic 28nm and above process nodes under industrial policy directives. GB standards for electromagnetic compatibility constrain import eligibility and shape local design rule requirements. China's dual carbon goals under MEE tighten energy efficiency benchmarks that power management ICs must satisfy for grid and EV charger applications. Stakeholders must monitor foundry utilization rates and policy subsidy renewal cycles to calibrate capacity commitments against demand volatility.
Market Dynamics
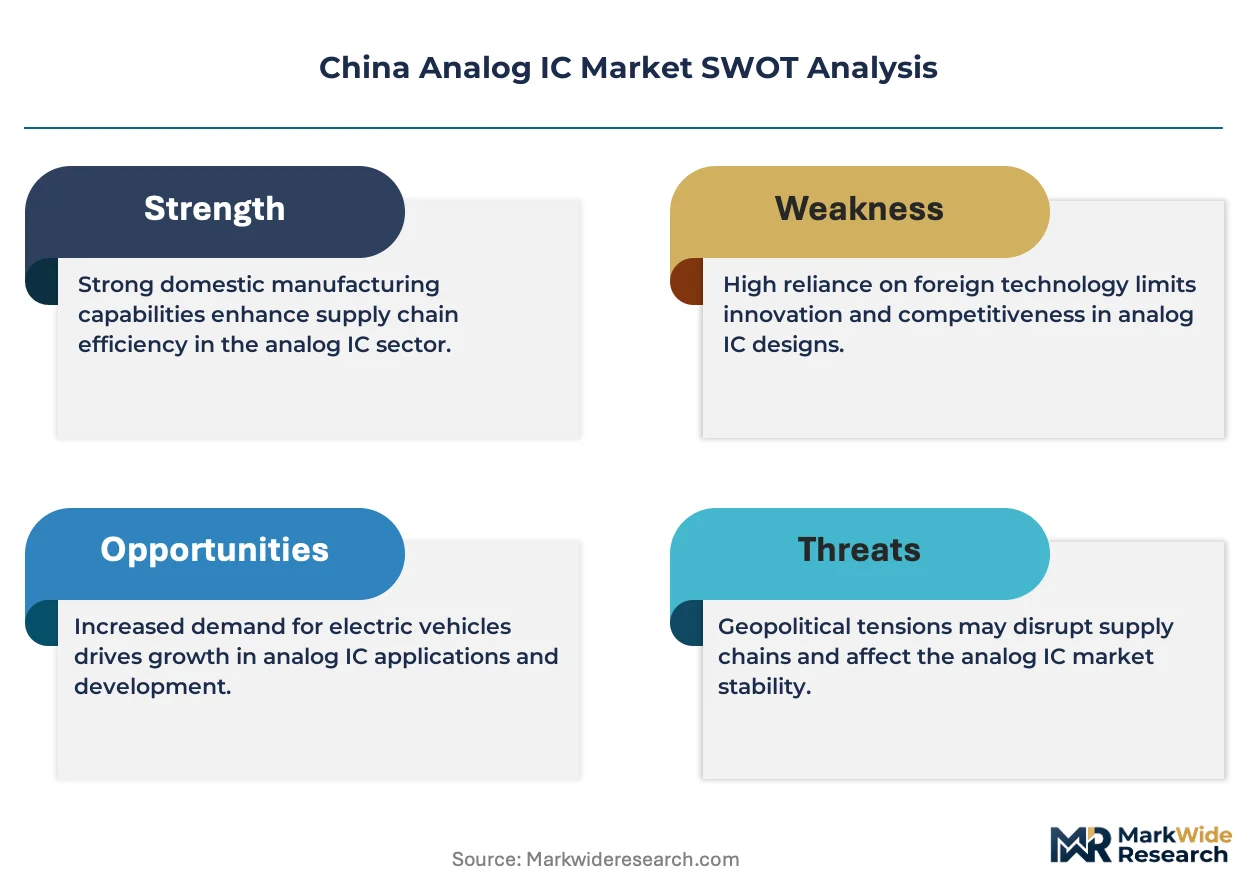
Foundry-backed project financing is tilting competitive dynamics toward capital-intensive domestic players, while China's dual carbon goals under MEE are tightening energy efficiency benchmarks that power management ICs must satisfy for grid and EV charger applications.
Growth Catalysts
- New energy vehicle procurement:Domestic automakers are expanding analog IC procurement budgets for battery management and motor control systems. This demand concentrates in the Yangtze River Delta semiconductor cluster around Shanghai.
- MIIT industrial policy:Subsidies channel toward domestic 28nm and above process nodes, accelerating capacity buildout for analog-dedicated foundry services. Fabless designers benefit from localized supply security.
- BiCMOS process advancement:High-frequency signal conditioning segments are capturing premium positioning as telecommunications infrastructure scales procurement of precision amplifiers and data converters.
Market Restraints
- 12-inch wafer supply concentration:Analog-dedicated foundry capacity remains concentrated among Hua Hong Semiconductor and select state-backed facilities, creating bottleneck risk during demand spikes.
- GB electromagnetic compatibility standards:Import eligibility constraints and local design rule requirements create friction for foreign suppliers seeking automotive-grade certification under SAMR protocols.
- Silicon carbide substitution:Wide-bandgap semiconductors are displacing traditional analog power management in high-voltage EV charging and grid infrastructure above 650V operating thresholds.
Strategic Opportunities
- Smart factory data acquisition:Industrial automation deployments are driving demand for precision signal conditioning and sensor interfacing solutions in underpenetrated inland manufacturing hubs.
- Dual carbon regulatory tailwind:MEE energy efficiency mandates for grid infrastructure are creating certified product premiums for power management ICs meeting stringent standby power benchmarks.
- Direct foundry-fabless partnerships:Bypassing traditional distribution channels, designers are securing dedicated capacity allocations through project financing structures backed by municipal semiconductor funds.
Industry Challenges
- Analog design expertise scarcity:Experienced circuit designers capable of optimizing noise figure and slew rate parameters remain concentrated among senior engineers at established IDMs, constraining fabless startup scaling.
- Automotive qualification timelines:AEC-Q100 certification cycles extending 18-24 months delay revenue recognition for power management suppliers targeting new energy vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Analog IC Market |
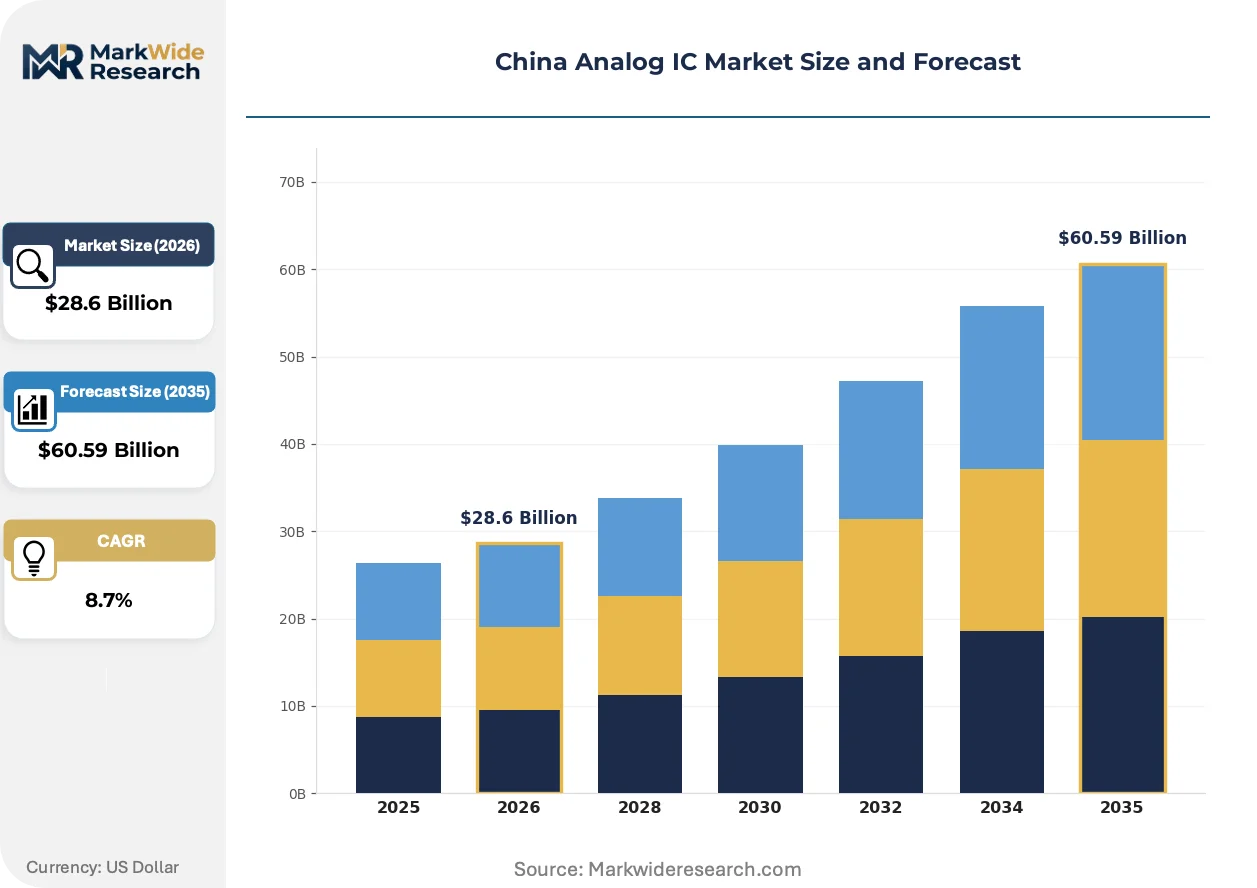
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Analog Multiplexers Technology: CMOS, BiCMOS, BJT, GaAs End User: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications Application: Signal Conditioning, Signal Conversion, Power Management, Data Acquisition |
| Companies Covered | Wuhan Juxin Microelectronics, Silan Microelectronics, SG Micro Corp, Hua Hong Semiconductor, Skywork Solutions Inc, 3PEAK Incorporated, Shanghai Chipanalog Microelectronics, HiSilicon, Jiangsu Diao Microelectronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Analog IC Market Trends and Innovations
Process technology migration and procurement model evolution are compressing design cycles while regulatory pressure on energy efficiency is redefining performance benchmarks across voltage regulator and signal conditioning portfolios.
BiCMOS technology is migrating from niche RF applications into mainstream industrial signal conditioning, where foundry process improvements have narrowed cost gaps with CMOS alternatives. Precision amplifier suppliers serving smart factory deployments are adopting these processes to achieve sub-microvolt offset specifications. The shift is compressing margins for pure-play CMOS competitors while enabling integrated sensor interface solutions previously requiring discrete component assemblies.
China's dual carbon goals under MEE are tightening energy efficiency benchmarks that power management ICs must satisfy for grid infrastructure and EV charger certifications. GB standards for standby power and conversion efficiency are constraining import eligibility while creating certified product premiums for domestic suppliers meeting Grade 1 efficiency tiers. Automotive-grade voltage regulator lines face parallel pressure from SAMR quality certification protocols that mandate enhanced thermal cycling reliability.
Direct procurement relationships between fabless designers and captive foundries are displacing traditional distribution channels for high-volume power management contracts. Municipal semiconductor investment funds are facilitating these arrangements through project financing structures that secure capacity allocations against demand volatility. The Yangtze River Delta cluster exhibits the most advanced development of this model, with Shanghai-based designers leveraging proximity to Hua Hong Semiconductor's 12-inch analog-dedicated facilities.
China Analog IC Market Segmentation
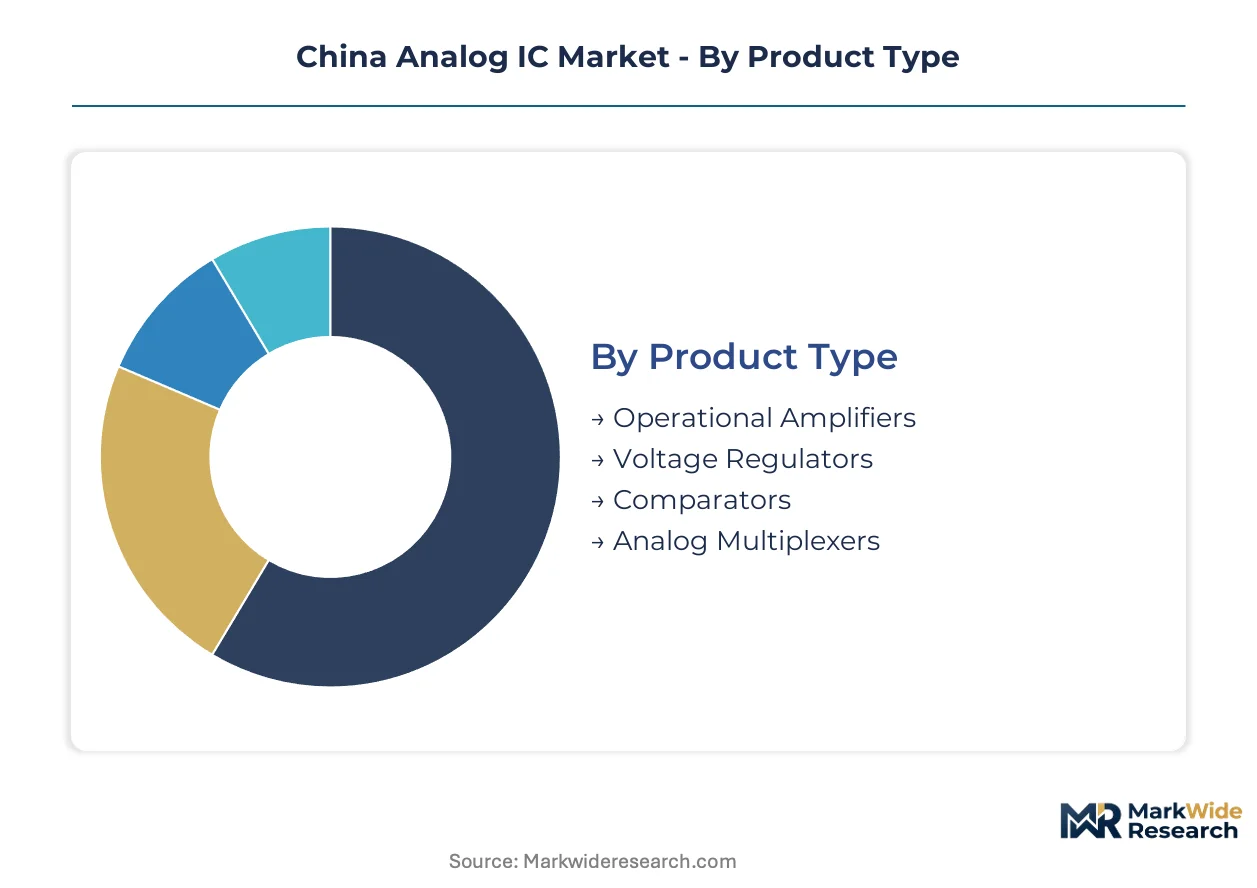
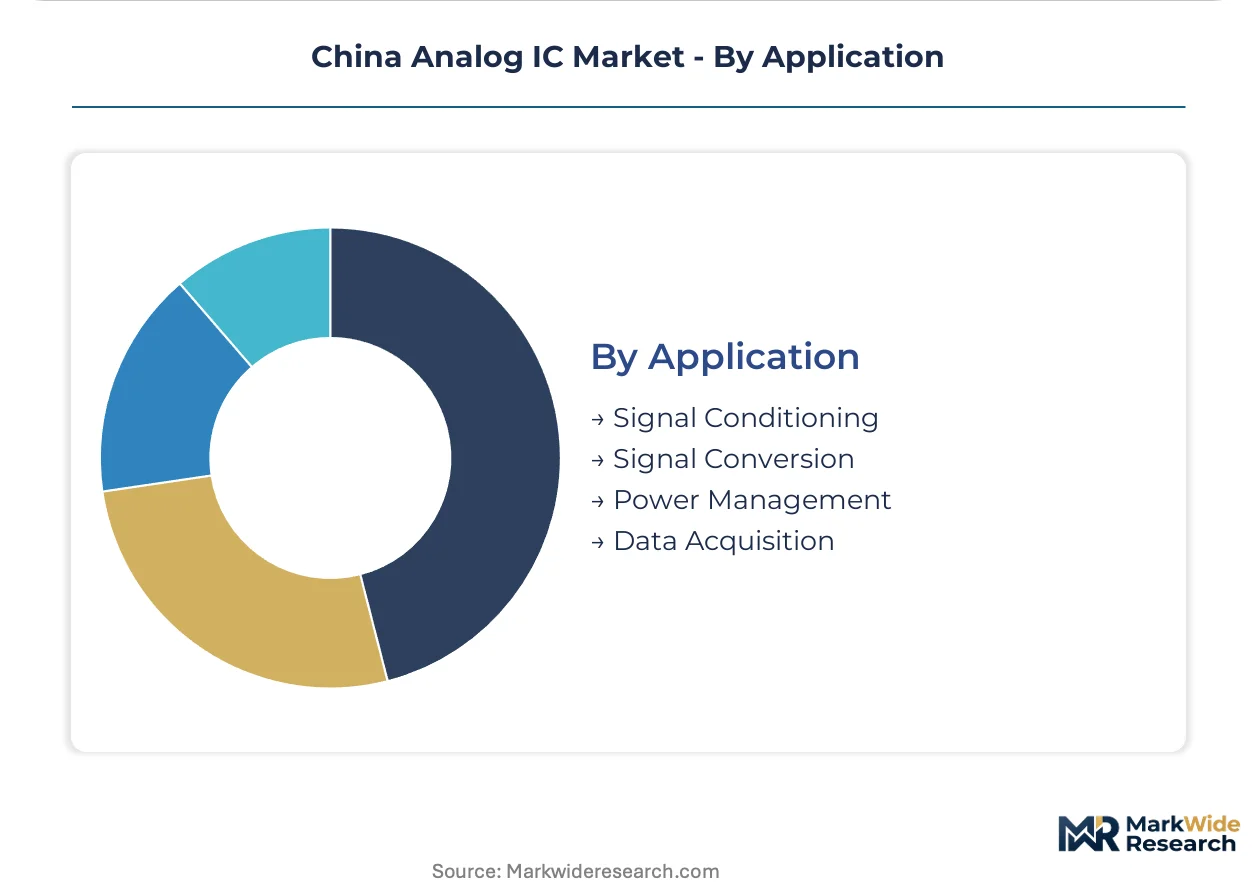
Analog IC segmentation in China reflects divergent procurement cycles across automotive qualification timelines and consumer electronics refresh rates. Voltage regulators and power management ICs face 18-24 month AEC-Q100 certification delays, while signal conditioning components for industrial automation track smart factory deployment waves. Understanding these temporal patterns enables capacity planning against subsidy renewal cycles and foundry utilization volatility.
Product Type:
Voltage regulators turn inventory fastest in consumer electronics, while automotive-grade operational amplifiers lock working capital through extended qualification protocols.
- Voltage Regulators:These devices maintain stable output voltage despite input fluctuations and load variations. Demand concentrates in Yangtze River Delta EV charging infrastructure where MEE dual carbon mandates enforce Grade 1 efficiency tiers. Silan Microelectronics leverages captive 12-inch wafer capacity to defend cost positions against fabless competitors.
- Operational Amplifiers:High-gain differential voltage amplifiers with mature, stable demand patterns across industrial sensing applications. Procurement from Shanghai-based designers accelerates for precision motor control in new energy vehicle platforms, though AEC-Q100 thermal cycling requirements extend revenue recognition timelines.
- Comparators:High-speed threshold detection circuits enabling zero-crossing detection and voltage monitoring functions. Domestic fabless designers target underpenetrated inland manufacturing hubs for industrial automation retrofit programs.
- Analog Multiplexers:Signal routing switches selecting among multiple analog inputs. BiCMOS process migration narrows cost gaps with CMOS alternatives in sensor interface applications.
Voltage regulators dominate installed base volumes. Operational amplifiers are where margin expansion concentrates through automotive certification premiums.
Technology:
Process selection stratifies by frequency requirements and noise specifications, with cost tiers separating commodity CMOS from premium BiCMOS positioning.
- CMOS:Dominant unit volume technology leveraging low static power consumption and high integration density. MIIT subsidies for 28nm and above nodes accelerate domestic foundry capacity buildout at Hua Hong Semiconductor facilities.
- BiCMOS:Bipolar-CMOS integration combining high-frequency bipolar transistors with CMOS logic density. Sub-microvolt offset specifications capture premium positioning in telecommunications infrastructure and precision data acquisition systems.
- BJT:Bipolar junction transistor technology retaining niche applications in high-current drive circuits and linear regulator pass elements. Legacy automotive designs sustain residual demand despite CMOS displacement trends.
- GaAs:Gallium arsenide compound semiconductors for microwave and millimeter-wave frequency applications. RF front-end modules in 5G base station deployments drive selective procurement above 6GHz operating thresholds.
CMOS holds the deepest production volume. BiCMOS is climbing the fastest as foundry process improvements compress cost premiums.
End User:
Customer type determines certification burden and pricing power, with automotive electronics commanding structural premiums against consumer electronics margin compression.
- Automotive Electronics:Battery management systems and motor control platforms for new energy vehicle manufacturers. SAMR quality certification protocols and AEC-Q100 reliability mandates create import eligibility barriers favoring domestic suppliers with established automotive qualification track records.
- Industrial Automation:Smart factory deployments driving precision signal conditioning and sensor interfacing demand. Inland manufacturing hubs beyond the Yangtze River Delta cluster present underpenetrated expansion opportunities for data acquisition system suppliers.
- Consumer Electronics:High-volume, short-lifecycle applications including smartphones, tablets, and wearable devices. Price-sensitive procurement concentrates among established IDMs with scale economies.
- Telecommunications:Base station infrastructure and optical networking equipment requiring high-linearity amplifiers and precision data converters. BiCMOS process adoption accelerates for sub-microvolt offset specifications in 5G deployment waves.
Consumer electronics anchors unit shipment volumes. Automotive electronics is gaining share fastest through procurement budget expansion at domestic EV manufacturers.
Application:
Functional use case determines integration complexity and discrete component substitution vulnerability, with power management facing silicon carbide displacement above 650V thresholds.
- Power Management:Voltage regulation, battery charging, and power distribution functions across electronic systems. MEE energy efficiency benchmarks for grid infrastructure and EV chargers constrain import eligibility while creating certified product premiums for Grade 1 efficiency tier compliance.
- Signal Conditioning:Amplification, filtering, and linearization of sensor outputs for downstream processing. Smart factory deployments in inland manufacturing hubs drive demand for integrated sensor interface solutions previously requiring discrete component assemblies.
- Signal Conversion:Analog-to-digital and digital-to-analog translation bridging continuous and discrete signal domains. Telecommunications infrastructure scaling accelerates procurement of precision data converters with high dynamic range specifications.
- Data Acquisition:Multi-channel sensor sampling and digitization for industrial monitoring and control systems. Direct foundry-fabless partnerships through municipal semiconductor funds secure capacity allocations against demand volatility in this expanding segment.
Power management commands the deepest margin pools. Data acquisition is where design activity concentrates through smart factory deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics buyers cluster in the Yangtze River Delta, while industrial automation demand disperses toward inland manufacturing corridors under central government industrial upgrading mandates.
Yangtze River Delta
New energy vehicle manufacturers in Shanghai and Suzhou are expanding analog IC procurement budgets for battery management systems. MIIT channels subsidies toward domestic 28nm and above process nodes, accelerating foundry capacity buildout. The Shanghai cluster anchors Hua Hong Semiconductor's 12-inch analog-dedicated facilities serving fabless designers.
Pearl River Delta
Consumer electronics OEMs in Shenzhen and Dongguan drive high-volume demand for voltage regulators and power management ICs. GB standards for electromagnetic compatibility constrain import eligibility while shaping local design rule requirements. Municipal semiconductor funds in Guangzhou facilitate direct foundry-fabless partnerships bypassing traditional distribution channels.
Beijing-Tianjin-Hebei
Telecommunications infrastructure deployments around Beijing accelerate procurement of precision amplifiers and data converters. SAMR enforces quality certification protocols for automotive-grade components that create eligibility barriers for uncertified suppliers. The region's design houses concentrate on high-frequency signal conditioning for 5G base station applications.
Sichuan-Chongqing
Smart factory retrofits in Chengdu and Chongqing manufacturing hubs drive demand for sensor interfacing and data acquisition systems. MEE dual carbon goals tighten energy efficiency benchmarks that power management ICs must satisfy for industrial certification. Inland expansion reduces logistics costs for western China automation deployments.
Shandong Peninsula
Grid infrastructure modernization in Jinan and Qingdao creates certified product premiums for power management ICs meeting Grade 1 efficiency tiers. Provincial industrial policies align with national dual carbon targets under MEE directives. Local system integrators prioritize domestic suppliers with established qualification track records for EV charging infrastructure.
China Analog IC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tilting toward capital-intensive domestic foundry-backed groups. Silan Microelectronics leverages captive wafer capacity to sustain cost advantages, while Hua Hong Semiconductor anchors its position through 12-inch analog-dedicated foundry services. Three strategic archetypes dominate: integrated device manufacturers with captive fabrication, fabless designers securing dedicated capacity through municipal funds, and precision specialists targeting industrial automation niches. Competitive moves concentrate on foundry utilization rate optimization and direct procurement relationship formation.
Among foundry-integrated domestic players, Silan Microelectronics and Hua Hong Semiconductor occupy positions as scale anchors with captive or dedicated fabrication capacity. Within the precision signal conditioning tier, 3PEAK Incorporated exemplifies specialists targeting industrial automation with sub-microvolt offset specifications. These three represent the competitive spectrum from volume-driven power management to high-performance analog design, with each archetype responding differently to MIIT subsidy cycles and SAMR automotive qualification timelines.
| Leading Market Players |
|---|
| Wuhan Juxin Microelectronics |
| Silan Microelectronics |
| SG Micro Corp |
| Hua Hong Semiconductor |
| Skywork Solutions Inc |
| 3PEAK Incorporated |
| Shanghai Chipanalog Microelectronics |
| HiSilicon |
| Jiangsu Diao Microelectronics |
| Others |
Pricing and Supply Chain Analysis
Hua Hong Semiconductor's 12-inch analog-dedicated foundry utilization rates above 85% are compressing margin buffers for fabless designers while amplifying pricing power for captive-capacity players like Silan Microelectronics. This supply tightness propagates through procurement contracts as municipal semiconductor funds secure preferential allocations.
Pricing Analysis
Certification level under SAMR automotive-grade protocols creates the primary spread between premium and standard tiers. Three-tier pricing structure separates AEC-Q100 qualified lines from industrial-grade and consumer-tier alternatives. Pricing pressure stems from silicon carbide substitution above 650V thresholds in EV charging infrastructure. Consumer electronics buyers exhibit highest price sensitivity while automotive electronics procurement accepts structural premiums for qualification track records.
Supply Chain Analysis
Polysilicon feedstock and 12-inch silicon wafers draw primarily from Taiwan, South Korea, and domestic Chinese suppliers. Specialty gases including high-purity nitrogen and argon rest on imports from Japan and the USA. Single-source vulnerability concentrates around analog-dedicated foundry capacity at Hua Hong Semiconductor facilities. Distribution runs through direct foundry-fabless partnerships backed by municipal semiconductor investment funds, displacing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analog circuit design expertise scarcity constrains fabless scaling as experienced engineers optimizing noise figure and slew rate parameters remain concentrated at established IDMs. This talent gap amplifies acquisition premiums for teams with proven automotive qualification experience.
For Market Incumbents: Build captive wafer capacity moats through backward integration into 12-inch fabrication or exclusive foundry partnerships. Secure dedicated allocation agreements with Hua Hong Semiconductor before municipal fund competition intensifies. Accelerate AEC-Q100 certification pipelines to defend automotive revenue streams against silicon carbide displacement in high-voltage segments.
For New Entrants and Emerging Players: Inland manufacturing hubs beyond the Yangtze River Delta cluster represent the most penetrable entry point for industrial automation signal conditioning. Precision data acquisition for smart factory retrofits in Sichuan-Chongqing corridors faces less entrenched incumbent presence. Partner with municipal semiconductor funds for project-financed capacity allocations rather than competing for spot foundry availability.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision signal conditioning specialists with established industrial automation customer relationships. Five-to-ten year viability favors fabless designers securing dedicated foundry capacity through municipal fund structures. Monitor MIIT subsidy renewal cycles as inflection indicators for domestic 28nm and above process node expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Securement | Municipal fund-backed project financing locks dedicated 12-inch analog wafer allocations against demand volatility. |
| AEC-Q100 Certification Acceleration | SAMR automotive-grade protocols create 18-24 month revenue recognition delays that qualified suppliers bypass. |
| BiCMOS Process Migration | Sub-microvolt offset specifications capture premium positioning in telecommunications and precision industrial applications. |
| Inland Manufacturing Hub Expansion | Sichuan-Chongqing smart factory deployments reduce logistics costs for western China automation system integrators. |
| Silicon Carbide Portfolio Diversification | Wide-bandgap semiconductor capabilities above 650V defend against substitution in EV charging and grid infrastructure. |
Research Methodology
Operator-level perspectives from fabless design house executives, foundry operations managers, automotive Tier 1 procurement leads, and municipal semiconductor fund directors anchored the qualitative base. Primary interviews combined with secondary validation against MIIT policy filings, SAMR certification databases, customs trade records, and SEC disclosures from listed analog IC suppliers. Bottom-up segment sizing triangulated with top-down macroeconomic drivers across the analysis window.
Scenario-bracketing around MIIT subsidy renewal cycles and foundry utilization volatility shaped the analytical framework. Segmentation dimensions modeled include product type, process technology, end-user vertical, and regional cluster concentration. CAGRs derived from installed base growth rates and content-per-vehicle expansion in new energy vehicle platforms. Forecast inputs incorporated MEE dual carbon efficiency tier adoption curves and AEC-Q100 certification pipeline durations.
Practitioners should monitor silicon carbide cost parity milestones and municipal fund allocation competition for early signals of analog IC substitution pressure. Forecasts reflect assumptions on domestic 28nm process node yield maturation and automotive platform qualification timelines. Cross-checking against foundry utilization rate disclosures and MIIT subsidy disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market