
 APAC Analog IC Market | 2026-2036
APAC Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Analog IC Market Insights
Automotive-grade AEC-Q100 qualification is unwinding legacy consumer-tier supply arrangements across the APAC Analog IC Market. Texas Instruments Incorporated anchors its position through captive 300mm analog fab capacity in Japan. STMicroelectronics NV specializes in silicon carbide gate drivers for EV traction inverters. Renesas Electronics Corporation leverages its microcontroller-analog integration to dominate automotive body electronics.
APAC Analog ICs are continuous-signal integrated circuits fabricated on bipolar, CMOS, or BiCMOS processes with operating voltages typically spanning 1.8V to 40V, designed to interface between physical sensors and digital processors. Automotive Electronics commands the deepest margin pools as OEMs mandate functional safety under ISO 26262. Consumer Electronics remains the highest-volume outlet though price compression intensifies in standard voltage regulators. BiCMOS technology captures design wins where high-speed precision amplifiers must coexist with dense digital logic.
Japan's METI enforces semiconductor supply chain resilience mandates that redirect analog IC inventory thresholds upward. South Korea's MFDS and KOSHA frameworks intersect where medical and industrial analog applications require concurrent certification. China's GB standards and MIIT dual carbon targets force power management IC efficiency benchmarks higher. Stakeholders must decide whether to pursue in-house BCD process development or license from established foundry partners before qualification timelines harden.
Market Dynamics
Automotive electrification is compressing qualification timelines across the APAC Analog IC Market as OEMs demand ISO 26262 functional safety certification alongside AEC-Q100 reliability standards.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's efficiency benchmarks for power management ICs are accelerating BCD process investments across domestic foundries.
- Silicon Carbide Traction Inverters:EV manufacturers in South Korea and Japan are sourcing specialized gate drivers that operate at higher temperatures than silicon alternatives.
- Medical-Industrial Convergence:South Korea's MFDS and KOSHA frameworks are creating dual-certified analog IC demand for patient monitoring equipment deployed in industrial settings.
Market Restraints
- 300mm Wafer Supply Concentration:Captive analog fab capacity concentrates in Japan and Texas, limiting foundry access for fabless APAC designers.
- Legacy Node Equipment Scarcity:Deposition and etch tools for 130nm-180nm BCD processes face extended lead times from Japanese equipment suppliers.
- BiCMOS Process Complexity:The integration of high-speed bipolar with dense CMOS logic requires specialized design kits that few foundries qualify for automotive grades.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Contract assemblers are relocating from southern China, creating localized analog IC demand for power regulation in consumer devices.
- India PLI Scheme:Production-linked incentives for semiconductor packaging are attracting analog IC test and assembly investments from established APAC suppliers.
- BiCMOS-Digital Convergence:Precision amplifiers with integrated ADCs are capturing design wins in Japan's industrial sensor networks.
Industry Challenges
- Automotive Functional Safety Talent:ISO 26262 systems engineers with analog IC expertise command premium compensation in South Korea's foundry clusters.
- Multi-Site Qualification Burden:METI supply chain resilience mandates require Japanese suppliers to maintain redundant inventory thresholds across dispersed warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Analog IC Market |
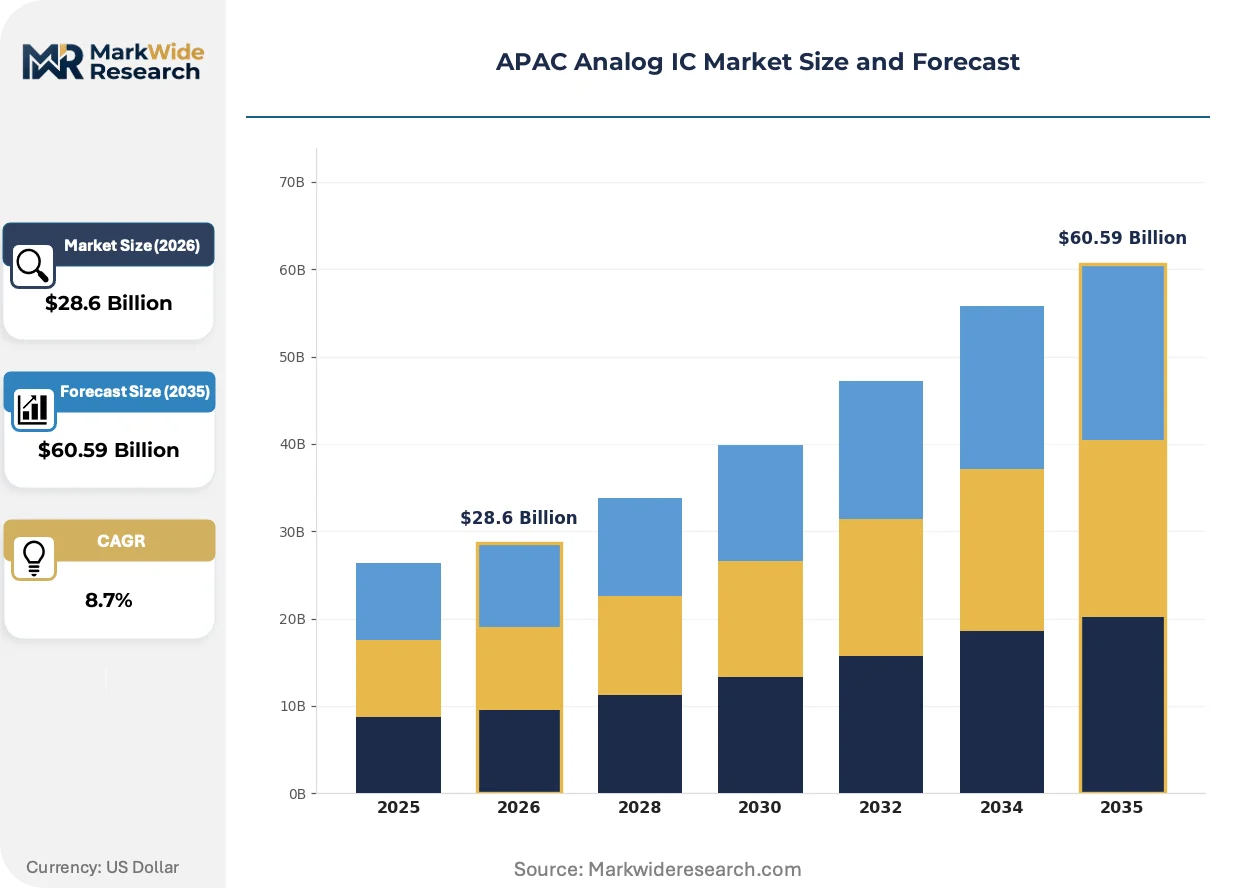
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Audio Amplifiers Technology: Bipolar, CMOS, BiCMOS, SiGe Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications End User: OEMs, Aftermarket Providers, System Integrators, Distributors |
| Companies Covered | NXP Semiconductors NV, STMicroelectronics NV, Texas Instruments Incorporated, Microchip Technology Inc, ON Semiconductor, Analog Devices Inc, Renesas Electronics Corporation, MediaTek Inc, Infineon Technologies AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Analog IC Market Trends and Innovations
Process-node specialization is fragmenting competitive positioning across the APAC Analog IC Market as mature nodes gain strategic importance over leading-edge digital scaling.
Gallium nitride power stages are decomposing the traditional silicon MOSFET-plus-driver architecture in EV onboard chargers. Chinese tier-one suppliers are qualifying GaN-based solutions at 650V ratings for 2026 platform launches. This technology is compressing the addressable market for conventional silicon gate drivers while expanding margins for integrated GaN controller suppliers.
METI's semiconductor supply chain resilience directives are mandating six-month inventory buffers for automotive-grade analog ICs held within Japanese territory. Tier-1 suppliers are renegotiating contract terms to distribute carrying costs across the value chain. The body electronics segment faces the steepest compliance burden due to its high SKU count and lower individual shipment volumes.
Consolidated procurement desks at Korean chaebol electronics divisions are unbundling analog IC sourcing from microcontroller bundles. Direct negotiations with Renesas and STMicroelectronics are replacing distributor-mediated transactions for high-volume voltage regulator families. This concentration is most visible in Seoul's consumer appliance manufacturing corridors where annual analog IC spends exceed internal sourcing thresholds.
APAC Analog IC Market Segmentation
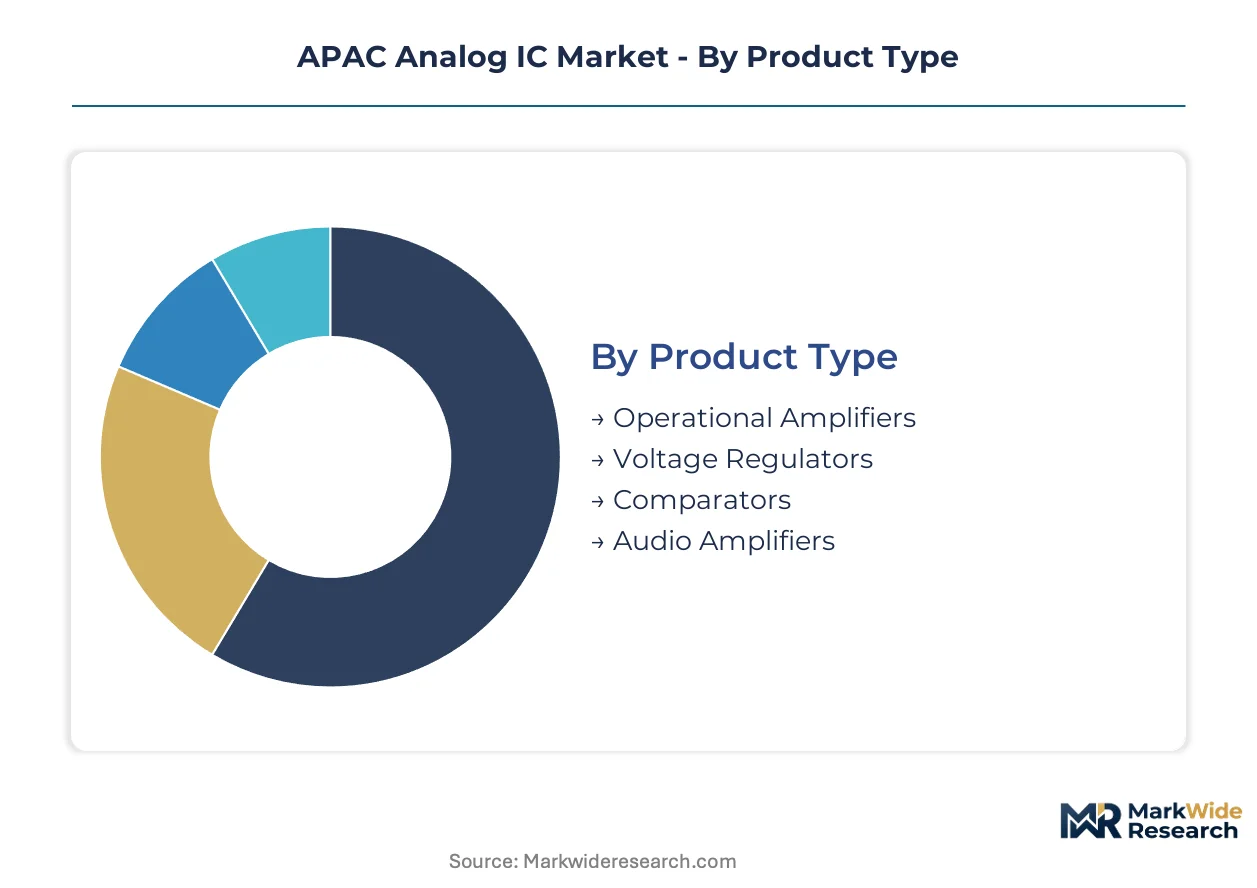
Analog IC segmentation across APAC reflects divergent margin structures between high-volume consumer applications and safety-critical automotive systems. Process technology choices and qualification tiers fragment competitive positioning more sharply than end-use volume distribution alone would suggest.
Product Type:
Voltage regulators face the most acute substitution pressure from integrated power management units in smartphone SoCs, while discrete operational amplifiers defend their sockets through precision requirements that resist integration.
- Voltage Regulators:Linear and switching architectures span 1.8V to 40V input ranges with load transient response specifications tightening under MIIT efficiency mandates. China's domestic foundries are capturing design wins in mid-range consumer applications as efficiency benchmarks force process node refreshes.
- Operational Amplifiers:Precision bipolar and CMOS designs achieve microvolt offset voltages for sensor interface applications. South Korea's semiconductor foundry clusters concentrate demand for high-speed variants in industrial automation equipment where signal chain integrity commands premium pricing.
- Comparators:High-speed voltage comparison circuits with nanosecond propagation delays serve overvoltage detection in power management subsystems.
- Audio Amplifiers:Class-D and Class-AB architectures deliver watt-scale output for smartphone and portable device speaker drivers.
Voltage regulators anchor the volume base while operational amplifiers gain share at the steepest rate.
Technology:
Process maturity curves separate segments by automotive qualification burden, with newer compound semiconductors climbing the reliability learning curve fastest in EV power applications.
- BiCMOS:Merged bipolar-CMOS processes combine high transconductance with dense logic integration for precision mixed-signal subsystems. Japan's industrial sensor networks concentrate demand where analog front-ends must coexist with digital calibration engines.
- Bipolar:Junction-isolated processes deliver superior matching and low noise for precision voltage references and current mirrors. Legacy 180nm bipolar capacity concentrates in Japanese captive fabs serving automotive body electronics with decade-long production commitments.
- CMOS:Scalable processes dominate high-volume consumer applications where cost-per-function minimization outweighs precision specifications.
- SiGe:Silicon-germanium heterojunction processes extend bipolar performance into microwave frequencies for RF transceiver front-ends.
Bipolar technology anchors the volume base while BiCMOS gains share at the steepest rate.
Application:
End-use qualification tiers stratify segments by functional safety requirements, with ISO 26262 certification creating impermeable boundaries between automotive and consumer-grade supply chains.
- Automotive Electronics:AEC-Q100 qualified devices with ISO 26262 functional safety ratings serve powertrain, body, and infotainment subsystems. South Korean and Japanese EV manufacturers source specialized gate drivers and battery management ICs under compressed platform development timelines.
- Consumer Electronics:High-volume, short-lifecycle applications in smartphones, tablets, and wearables drive cost-optimized CMOS implementations. Vietnam's electronics manufacturing relocation from southern China is creating localized demand for power regulation ICs in final assembly operations.
- Industrial Automation:Extended temperature range and long-term availability requirements distinguish this segment from consumer tiers.
- Telecommunications:Base station and optical communication infrastructure demand high-linearity RF and precision timing components.
Consumer electronics anchors the volume base while automotive electronics gains share at the steepest rate.
End User:
Procurement consolidation patterns separate segments by technical engagement depth, with direct manufacturer relationships replacing distribution for high-volume qualified families.
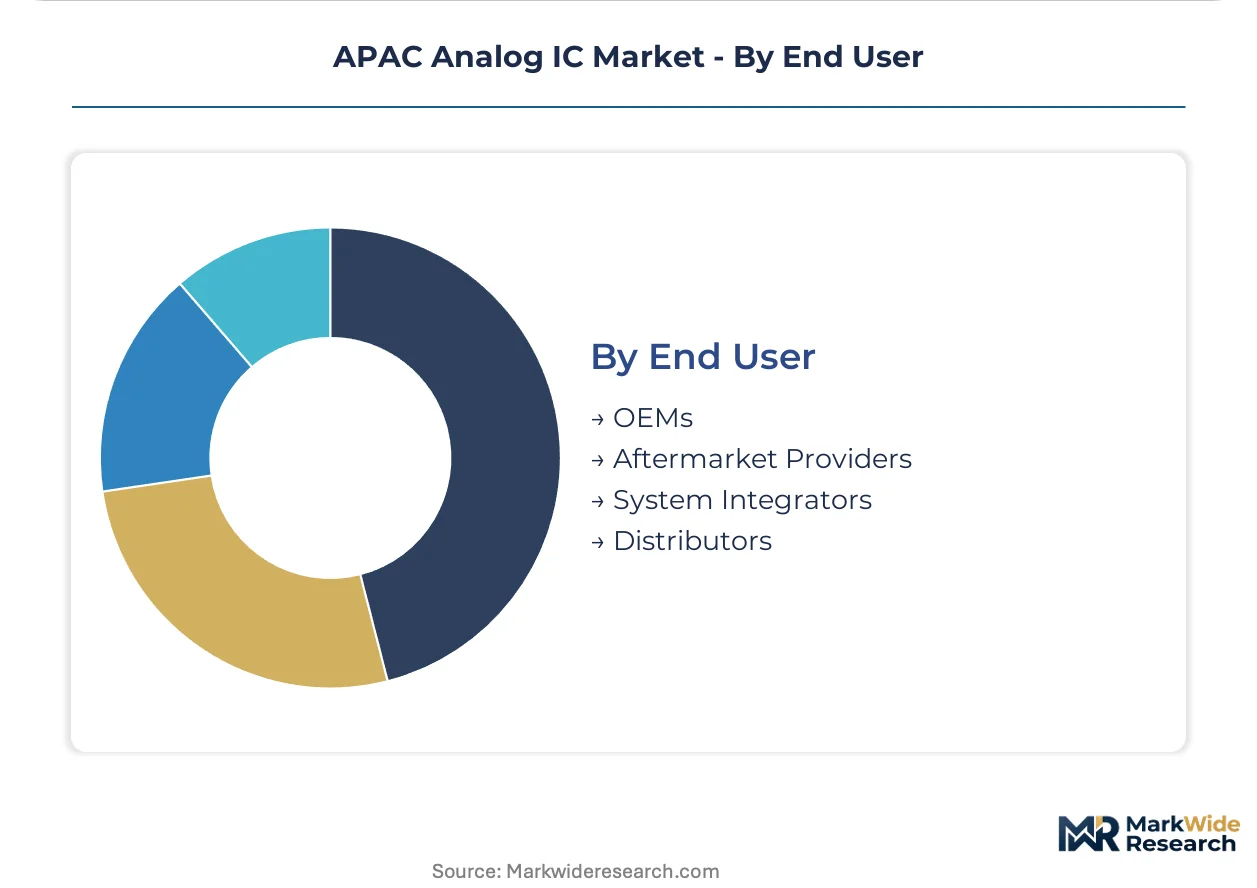
- OEMs:Original equipment manufacturers in automotive and consumer electronics conduct direct qualification and volume procurement of analog IC families. Korean chaebol electronics divisions are unbundling analog sourcing from microcontroller bundles to negotiate directly with established suppliers.
- Distributors:Arrow, Avnet, and regional specialists maintain inventory buffers and technical support for mid-volume industrial and commercial accounts. METI supply chain resilience mandates in Japan are forcing distributor inventory threshold increases that renegotiate carrying cost allocations.
- System Integrators:Subsystem assemblers source analog components for specialized industrial and medical equipment configurations.
- Aftermarket Providers:Replacement and repair channels serve extended vehicle and industrial equipment lifecycles with cross-reference compatible alternatives.
Distributors anchor the volume base while OEMs gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
APAC Analog IC trade flows reveal a structural import dependency for high-reliability automotive grades, while mature-node consumer devices export from Chinese and Vietnamese assembly hubs. The region's semiconductor clusters concentrate in four national manufacturing corridors with divergent specialization profiles.
China
Domestic foundries are expanding BCD process capacity to serve EV power management demand under MIIT dual carbon efficiency mandates. GB standards now enforce minimum conversion efficiency thresholds for DC-DC regulators used in industrial equipment. Yangtze River Delta fabs in Shanghai and Wuxi are qualifying 130nm automotive-grade lines for local tier-one suppliers.
Japan
METI supply chain resilience directives mandate six-month inventory buffers for automotive-grade devices held within domestic territory. Captive 300mm analog fab capacity concentrates in Tokyo and Nagoya corridors serving decade-long automotive body electronics commitments. Renesas anchors microcontroller-analog integration supply from Kanto region facilities.
South Korea
Seoul Capital Area foundry clusters face acute ISO 26262 functional safety engineering shortages as Hyundai-Kia accelerates EV platform timelines. MFDS and KOSHA dual certification requirements are reshaping procurement for medical-industrial convergence applications. Busan-Ulsan corridor suppliers are unbundling analog sourcing from microcontroller bundles to negotiate directly with European specialists.
Vietnam
Electronics manufacturing relocation from southern China is creating localized demand for power regulation ICs in final assembly operations. Contract assemblers in Bac Ninh and Hai Phong industrial zones require voltage regulators for smartphone and tablet production lines. Domestic consumption remains minimal; nearly all analog IC demand derives from export-oriented manufacturing.
India
PLI scheme incentives for semiconductor packaging are attracting analog IC test and assembly investments from established APAC suppliers. Karnataka and Tamil Nadu electronics manufacturing clusters are qualifying power management devices for smartphone and appliance production. Domestic design activity concentrates in Bengaluru fabless centers targeting industrial automation applications.
APAC Analog IC Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and qualification depth. The vendor base organizes into three tiers: integrated device manufacturers with captive fab capacity, fabless designers licensing from foundry partners, and diversified conglomerates with analog IC divisions. Consolidation pressures intensify as automotive qualification timelines compress and BCD process development costs escalate. Dominant competitive moves include foundry partnership negotiations for BCD technology access and strategic inventory positioning under Japanese METI resilience mandates.
Within the integrated device manufacturer tier, Texas Instruments Incorporated, STMicroelectronics NV, and Renesas Electronics Corporation exemplify divergent geographic anchoring strategies. Texas Instruments represents North American-owned capacity concentration in Japan. STMicroelectronics NV occupies a European-headquartered position with SiC gate driver specialization for EV traction applications. Renesas Electronics Corporation anchors Japanese microcontroller-analog integration supply for automotive body electronics. These three entities illustrate how captive fab ownership, regional government alignment, and end-market focus combine to determine competitive positioning in automotive-grade analog IC supply.
| Leading Market Players |
|---|
| NXP Semiconductors NV |
| STMicroelectronics NV |
| Texas Instruments Incorporated |
| Microchip Technology Inc |
| ON Semiconductor |
| Analog Devices Inc |
| Renesas Electronics Corporation |
| MediaTek Inc |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Japanese foundries lock in wafer supply for automotive-grade analog ICs while fixing die costs across multi-year platform commitments. These arrangements tether price visibility to METI-mandated inventory thresholds that redistribute carrying costs across tier-1 suppliers and OEM procurement desks.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through direct negotiations that bypass distributor markups for high-volume voltage regulator families. Three-tier pricing structure across AEC-Q100 automotive, industrial-grade, and consumer-tier qualification levels separates segments by certification burden and functional safety requirements. Cost compression in consumer-grade CMOS implementations intensifies as Chinese domestic foundries expand BCD capacity under MIIT efficiency mandates. Smartphone SoC integrators exhibit the highest price sensitivity as integrated power management units displace discrete regulators, while automotive OEMs accept premium pricing for ISO 26262-certified devices with decade-long supply guarantees.
Supply Chain Analysis
Six-month inventory buffers mandated by METI directives have extended lead-time expectations for automotive-grade devices held within Japanese territory. Captive fab capacity concentrates in Japan and Texas, drawing from 300mm wafer supply and legacy deposition equipment for 130nm-180nm BCD processes. Silicon carbide substrate availability and specialized bipolar-CMOS design kit qualification create single-source vulnerability for high-reliability gate drivers. Distribution runs through Arrow and Avnet for mid-volume industrial accounts, while Korean chaebol electronics divisions consolidate procurement through direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride power stages threaten conventional silicon gate driver architectures, forcing incumbents to defend their socket positions through integrated controller solutions rather than discrete component supply.
For Market Incumbents: Compound microcontroller-analog integration advantages to deepen automotive body electronics penetration before qualification timelines harden further. Accelerate BCD process partnerships with Yangtze River Delta foundries to offset captive capacity constraints in Japan. Prioritize ISO 26262 systems engineering retention in Seoul Capital Area clusters where talent scarcity commands premium compensation. For New Entrants and Emerging Players: Differentiate on medical-industrial convergence applications requiring concurrent MFDS and KOSHA certification, a white-space where dual-qualified analog IC demand outpaces established supply. Target Vietnam's Bac Ninh and Hai Phong electronics manufacturing zones with localized power regulation IC support for contract assemblers relocating from southern China. Pursue fabless design house partnerships with domestic Chinese foundries qualifying 130nm automotive-grade lines. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive bipolar capacity and decade-long automotive production commitments. The long-term viability window favors entities with METI-aligned inventory positioning and direct OEM procurement relationships. Watch for GaN controller qualification announcements at 650V ratings as the inflection signal for silicon gate driver displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| BCD Process Partnership | Secures foundry access for power management IC qualification under MIIT dual carbon mandates. |
| ISO 26262 Certification Investment | Unlocks automotive functional safety sockets with compressed OEM platform development timelines. |
| GaN Controller Integration | Captures margin expansion in EV onboard chargers displacing conventional silicon architectures. |
| Inventory Buffer Positioning | Aligns with METI resilience directives redistributing carrying costs across Japanese supply chains. |
| Direct OEM Procurement Channel | Bypasses distributor concentration as Korean chaebol electronics divisions unbundle analog sourcing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the APAC Analog IC value chain, including automotive platform engineers at Hyundai-Kia, tier-1 supplier procurement leads in Seoul, foundry operations directors in Shanghai and Tokyo, and industrial automation equipment designers in Japan's sensor network corridors. Secondary validation drew from MIIT policy filings, METI supply chain resilience directives, MFDS medical device regulations, SEC 10-K disclosures from listed semiconductor manufacturers, and customs trade data for analog IC shipments. Bottom-up demand modeling triangulated against top-down capacity assessments from identified foundry investments.
Across the analysis window, the forecast framework segmented volume and value outputs by product type, process technology, application tier, and end-user procurement pattern, with additional modeling of qualification-grade stratification between automotive and consumer tiers. CAGRs were derived from production capacity expansion schedules, platform launch timelines from EV manufacturers, and efficiency mandate implementation trajectories under Chinese GB standards. Key inputs included BCD process node migration curves, silicon carbide adoption rates in traction inverters, and inventory threshold adjustments under Japanese resilience mandates.
Forecasts assume regulatory continuity in MIIT dual carbon enforcement, METI inventory directives, and MFDS-KOSHA dual certification requirements; material policy shifts would require re-modeling of foundry investment returns and qualification timeline assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Japan Analog IC Market