
 Memory IC Market | 2026-2036
Memory IC Market Size, Share, and Industry Trends Forecast 2026-2036
Memory IC Market Foresight
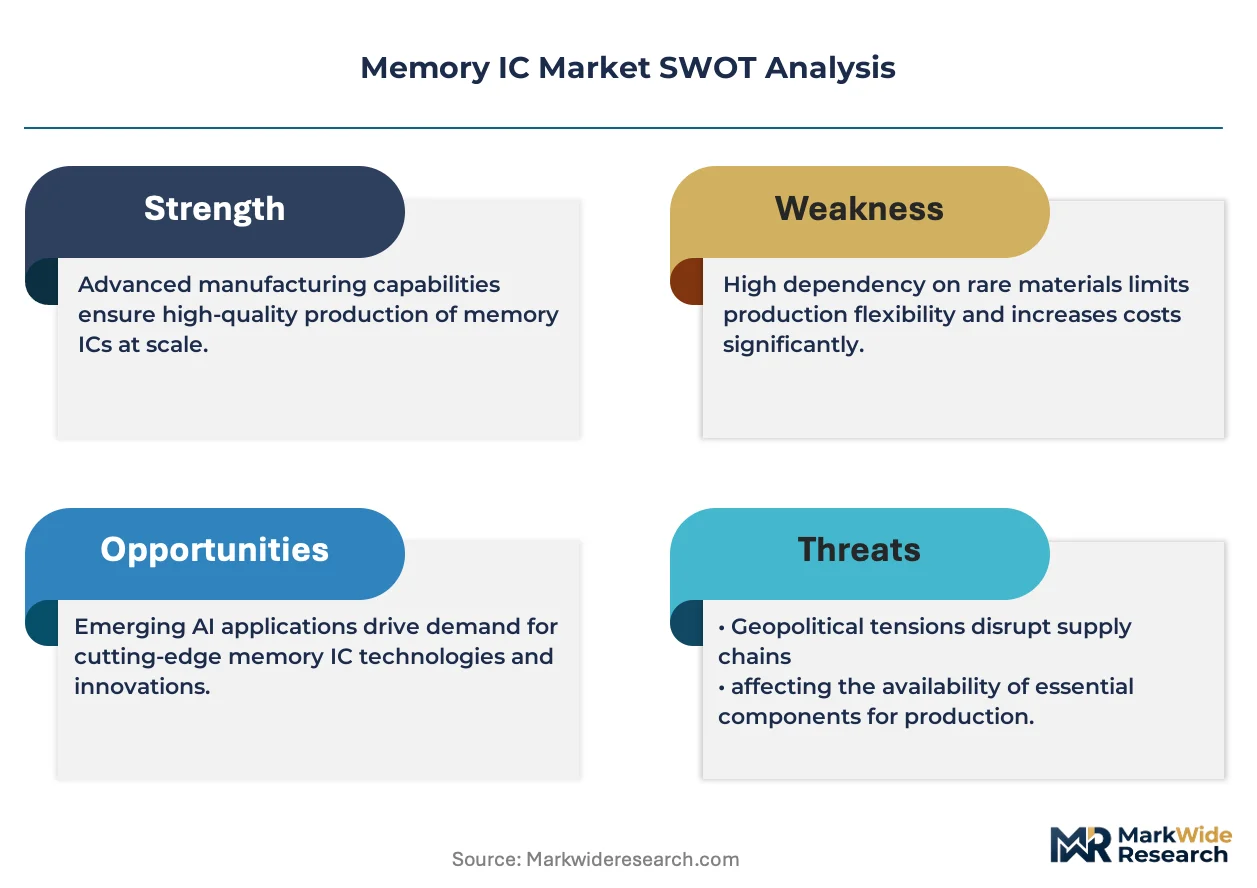
Compute-intensive AI workloads is tilting server architectures toward high-bandwidth memory configurations. Samsung Electronics leverages its vertical fabrication complex in Pyeongtaek to sustain cost leadership in advanced DRAM nodes. SK hynix anchors the HBM segment through proprietary stacking technology and tight coupling with GPU vendors. Micron Technology navigates geopolitical fragmentation by operating distinct supply chains for its US, Singapore, and Taiwan fabs.
Memory ICs are integrated circuits designed for temporary or permanent data storage, fabricated through photolithographic processes on silicon wafers with feature sizes now reaching sub-10 nanometer classes; they serve as the primary data repositories in electronic systems from mobile handsets to enterprise servers. DRAM occupies the largest revenue pool given its ubiquity in computing devices, while 3D NAND Flash leads bit-growth trajectories through layer-count expansion in solid-state storage. DDR5 commands premium positioning in server and PC refresh cycles, whereas LPDDR specializes in power-constrained smartphone and IoT endpoints.
The US CHIPS and Science Act directs subsidy eligibility toward domestic memory fabrication, while South Korea's Ministry of Trade, Industry and Energy coordinates K-Semiconductor Belt investments to preserve national competitiveness. China's MIIT imposes localization requirements on government procurement of memory components, altering vendor access patterns. Stakeholders must weigh geopolitical alignment against cost efficiency when siting new wafer capacity or qualifying second-source suppliers.
Market Dynamics
High-bandwidth memory integration for AI training clusters is compressing refresh cycles and concentrating procurement power among hyperscale data center operators. This demand concentration is reshaping capacity planning across the entire fabrication base.
Growth Catalysts
- AI Server Deployment:Hyperscale data center operators are expanding DRAM and NAND allocations to support large language model training and inference workloads.
- K-Semiconductor Belt:South Korea's Ministry of Trade, Industry and Energy coordinates domestic investment incentives to preserve national competitiveness in advanced memory nodes.
- EU Chips Act:The subsidy framework is reshaping European semiconductor fabrication capacity allocation toward memory-adjacent logic and specialty DRAM.
Market Restraints
- Extreme Ultraviolet Lithography Dependency:Sub-10 nanometer patterning requires ASML EUV equipment with multi-year order backlogs, constraining capacity expansion timelines.
- Geographic Supply Concentration:Advanced DRAM and NAND bit production concentrates in the Pyeongtaek cluster and select Taiwan fabs, creating single-point vulnerability.
- Silicon Wafer Input Volatility:300mm prime-grade silicon supply tightens during semiconductor upcycles, transmitting cost pressure downstream.
Strategic Opportunities
- Automotive Edge Computing:ADAS and autonomous vehicle architectures require LPDDR5 and GDDR6 for real-time sensor fusion, opening a new demand vertical outside traditional computing.
- US CHIPS Act Subsidies:Domestic memory fabrication eligibility directs capital toward greenfield DRAM and NAND facilities in Idaho and New York.
- Compute Express Link Convergence:CXL memory pooling technology enables disaggregated server architectures, expanding attach rates for high-capacity DRAM modules.
Industry Challenges
- EUV Photoresist Chemist Shortage:Advanced lithography process engineering talent concentrates at a handful of institutions, constraining node migration timelines.
- Legacy DDR4 Inventory Absorption:Server OEMs face working capital pressure from overlapping DDR4 and DDR5 qualification cycles during platform transitions.
- Cross-Border IP Licensing Complexity:Stacking and packaging patents span multiple jurisdictions, complicating HBM technology transfer agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory IC Market |
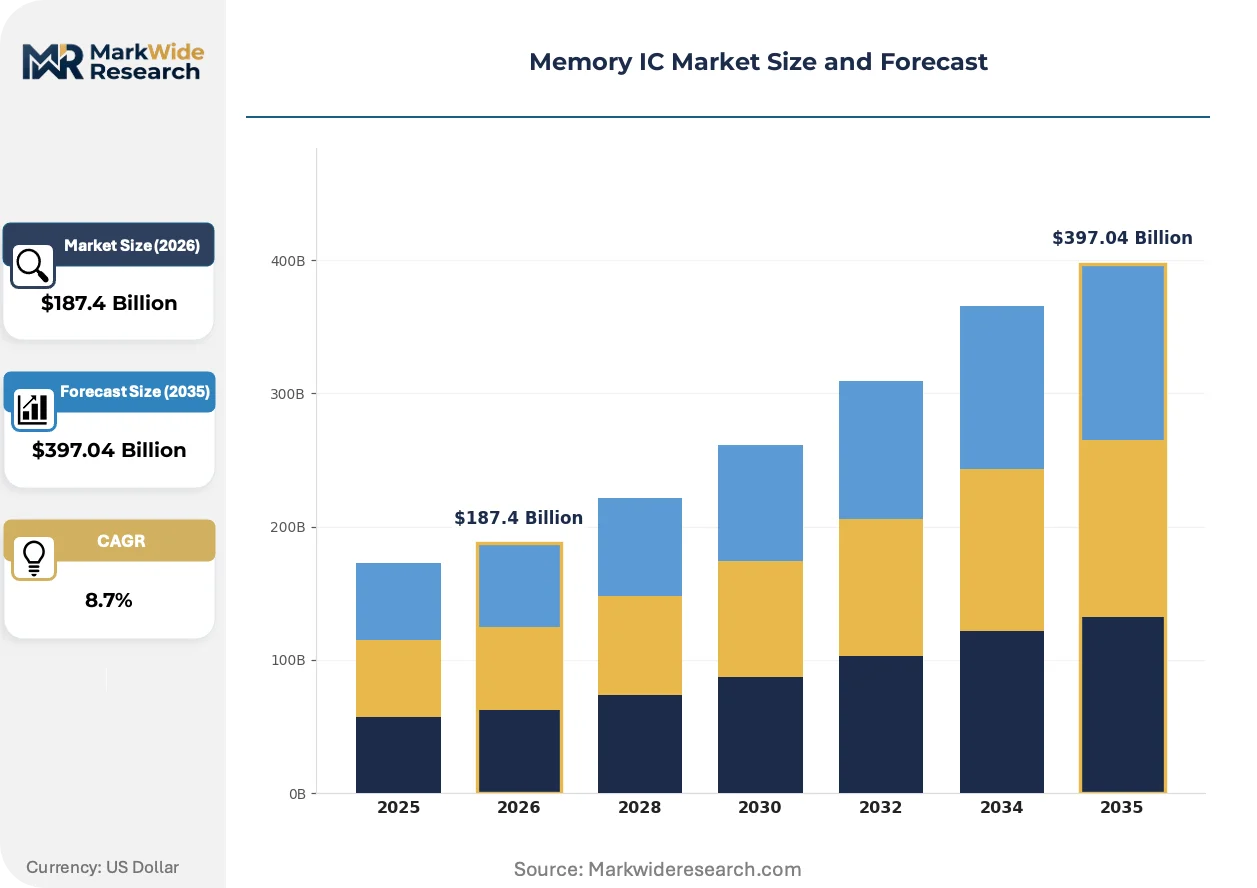
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash, ROM End User: Consumer Electronics, Automotive, Industrial, Telecommunications Technology: 3D NAND, DDR4, DDR5, LPDDR Application: Smartphones, Laptops, Servers, IoT Devices |
| Companies Covered | Samsung Electronics Co., Ltd., SK hynix Inc., Micron Technology, Inc., Kioxia Holdings Corporation, Western Digital Corporation, Nanya Technology Corporation, Winbond Electronics Corporation, Macronix International Co., Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory IC Market Shifts & Advancements
Memory subsystem architectures are fragmenting along workload-specific optimization paths. Specialized configurations for AI inference, training, and edge deployment are displacing general-purpose DIMM standardization.
Hybrid bonding die-stacking technology is virtualizing the physical separation between logic and memory domains. GPU vendors adopt this for HBM3E integration, compressing interconnect pitch below 10 micrometers. The structural consequence is collapsing the historical distinction between processor and memory suppliers, forcing new partnership models.
REACH substance restrictions on PFAS and fluorinated gases are tightening process chemistry requirements for EU-based fabrication. Memory manufacturers must reformulate etching and cleaning chemistries or relocate certain process steps. Advanced packaging operations in Ireland and Germany face the most immediate compliance timeline pressure.
Hyperscale buyers are consolidating memory procurement through direct wafer-level agreements rather than module vendor channels. This disintermediation compresses margin pools for traditional DRAM and NAND distributors. The pattern is most visible in North American cloud operator supply chains, where qualification programs now span die, package, and module tiers simultaneously.
Memory IC Market Segmentation
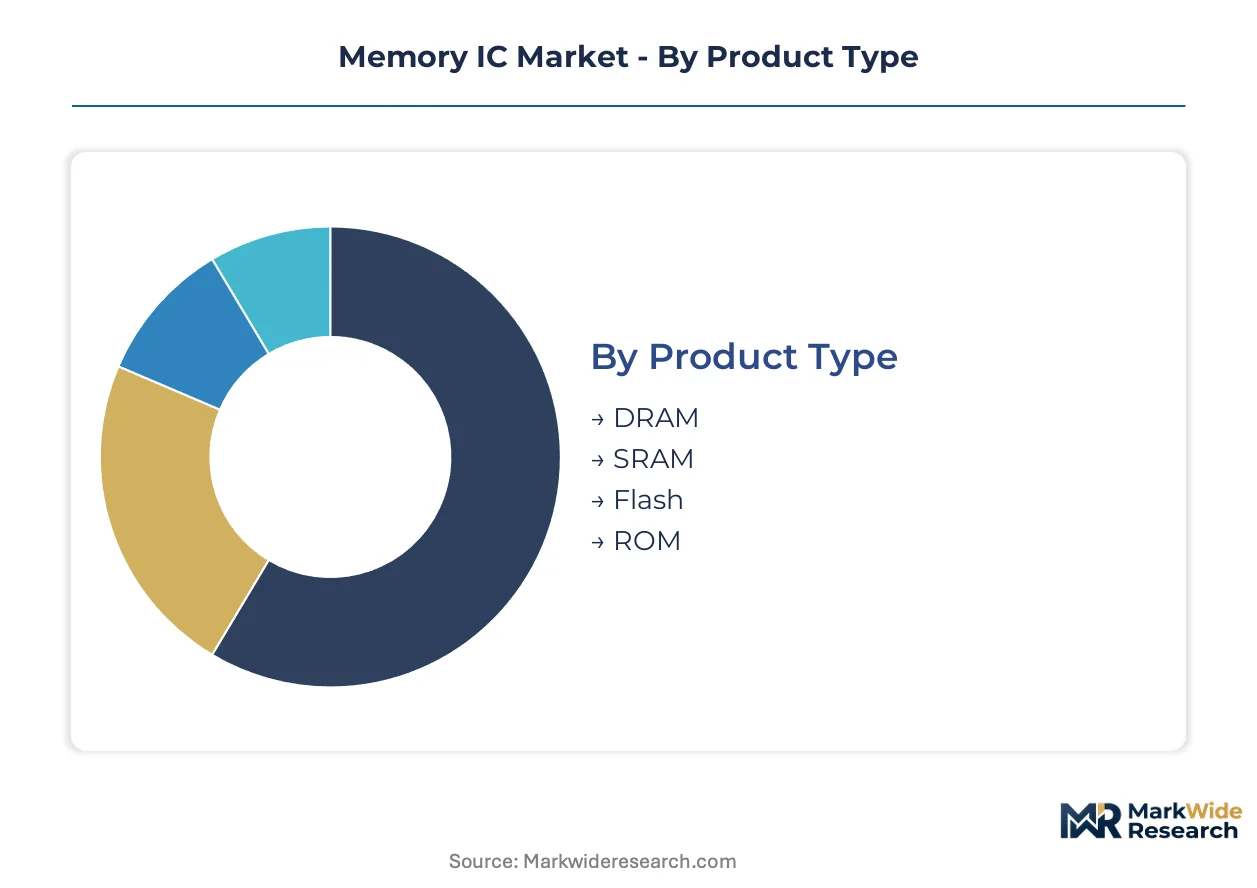
Memory IC segmentation reveals how fabrication economics, interface protocols, and thermal constraints fragment demand across computing tiers. Each dimension—product architecture, end-use environment, process node, and device form—creates distinct procurement specifications and margin structures.
Product Type:
Use-case spectrum spans volatile working memory to persistent storage, with each category optimizing for speed, density, or retention characteristics.
- DRAM:Capacitor-based volatile memory fabricated on sub-10nm nodes refreshes charge thousands of times per second to retain data. Hyperscale data center operators in the US and South Korea concentrate procurement for AI training clusters, driving DDR5 and HBM migrations despite EUV equipment constraints.
- Flash:Floating-gate non-volatile storage retains data without power, with 3D NAND stacking 200+ vertical layers to achieve terabit-scale densities. Enterprise SSD deployments in cloud facilities anchor bit demand, though QLC endurance limitations restrict write-intensive workloads.
- SRAM:Six-transistor cell structures deliver fastest access times for CPU cache hierarchies, trading density for speed. Automotive ECUs and network processors in Japan and Germany embed SRAM for deterministic real-time response.
- ROM:Mask-programmed or one-time programmable non-volatile storage holds firmware and boot code in cost-optimized devices. IoT endpoints in India and Brazil utilize ROM for immutable security certificates and factory calibration data.
Established volume favors Flash; emerging adoption favors DRAM variants optimized for AI inference.
End User:
Customer archetypes impose divergent qualification regimes—consumer cycles prioritize cost, while automotive mandates functional safety certification.
- Consumer Electronics:Smartphone OEMs in South Korea and China specify LPDDR5X for flagship handsets, balancing bandwidth against thermal envelopes. Refresh cycles compress to 12-18 months, forcing memory vendors to pre-qualify die stacks ahead of platform launches.
- Automotive:ADAS architectures require AEC-Q100 Grade 1 DRAM and NAND with -40°C to 125°C operating ranges. German and Japanese Tier-1 suppliers source GDDR6 for sensor fusion and LPDDR5 for cockpit domain controllers under ISO 26262 functional safety mandates.
- Industrial:Factory automation and energy infrastructure demand extended-temperature EEPROM and FRAM with 10-year data retention. European industrial OEMs specify memory modules with conformal coating and underfill for vibration resistance.
- Telecommunications:5G baseband processors and edge routers buffer traffic through RLDRAM and QDR SRAM. US and Nordic network equipment vendors prioritize deterministic latency over density for packet processing pipelines.
Automotive qualification timelines stretch 24-36 months, compressing margin for vendors accustomed to consumer velocity.
Technology:
Process and interface generations stratify along performance-per-watt curves, with migration economics determining adoption cadence.
- 3D NAND:Charge-trap cell architectures stack 232+ layers in vertical strings, achieving cost-per-bit leadership through string-stacking and split-gate innovations. YMTC's Xtacking and Samsung's COP structures represent divergent scaling paths.
- DDR5:On-die ECC and doubled burst length support 4800-6400 MT/s transfer rates for server and PC refresh cycles. Intel and AMD platform transitions in North American and Taiwanese supply chains drive module qualification.
- DDR4:Mature 3200 MT/s interfaces dominate legacy server installed bases and cost-optimized PC segments. Inventory absorption pressure overlaps with DDR5 ramps, straining working capital across distribution channels.
- LPDDR:Low-voltage swing interfaces optimize for milliwatt-range active power in smartphone and wearable SoCs. Samsung and SK hynix anchor supply through mobile-first process nodes at Pyeongtaek.
3D NAND layer-count expansion climbs the fastest; DDR5 attach rates accelerate most quickly in enterprise servers.
Application:
Device form factors dictate package constraints, thermal dissipation, and supply chain proximity to final assembly.
- Servers:DIMM and CXL-attached memory pools scale to terabyte capacities per socket for database and AI workloads. US hyperscale operators qualify die, package, and module tiers simultaneously, disintermediating traditional distributors.
- Smartphones:Multi-chip packages stack LPDDR and NAND atop application processors through hybrid bonding. Chinese and Vietnamese final assembly plants source within 72-hour logistics radii from memory packaging facilities.
- Laptops:SODIMM and on-board LPDDR configurations split between upgradeable and soldered architectures. Taiwanese ODMs coordinate memory procurement with CPU platform ramps for enterprise and education segments.
- IoT Devices:Serial NOR and low-density SRAM satisfy kilobyte-scale code storage in sensors and actuators. European industrial IoT deployments favor secured elements with immutable boot ROM.
Server memory pools expand most rapidly in bit volume; IoT endpoints proliferate fastest in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports advanced DRAM and HBM die to US hyperscale data center operators and Taiwanese packaging facilities, forming the dominant trade corridor in high-bandwidth memory. This bilateral flow shapes capacity allocation and pricing benchmarks across the fabrication base.
United States
Hyperscale cloud operators in Virginia and Oregon drive DDR5 and HBM procurement for AI training clusters. The CHIPS and Science Act directs subsidy eligibility toward domestic memory fabrication in Idaho and New York. Intel operates advanced packaging facilities in New Mexico and Arizona to support disaggregated server architectures.
South Korea
Samsung Electronics and SK hynix anchor Pyeongtaek as the world's densest memory manufacturing cluster, supplying HBM3E to GPU vendors. The Ministry of Trade, Industry and Energy coordinates K-Semiconductor Belt investments to preserve national competitiveness. Busan-Ulsan houses specialized packaging operations for mobile multi-chip modules.
China
YMTC expands 3D NAND layer counts for domestic server and smartphone OEMs in Shenzhen and Beijing. MIIT imposes localization requirements on government procurement of memory components. The Yangtze River Delta concentration in Hefei and Wuhan develops captive supply chains for industrial and automotive segments.
Japan
Kioxia and Western Digital operate joint-venture NAND fabs in Yokkaichi and Kitakami for enterprise SSD markets. METI coordinates supply chain resilience investments under the Economic Security Promotion Act. Kyoto-Osaka hosts specialized materials and equipment suppliers for EUV photoresist chemistry.
Taiwan
Nanya Technology and Winbond serve specialty DRAM and niche memory segments for networking and industrial applications. The Hsinchu Science Park concentrates packaging and testing operations within 72-hour logistics radii of Chinese final assembly plants. TSMC's advanced packaging ecosystem supports HBM-logic integration for AI accelerators.
Memory IC Market Competitive Landscape
On the supply side, the industry is consolidated around three vertically integrated fabricators controlling advanced DRAM and NAND bit production, with tiered competition in specialty and legacy segments. Strategic archetypes include scale-driven commodity producers, HBM-integrated logic-memory partnerships, and niche specialists in automotive and industrial grades. Dominant competitive moves encompass hybrid bonding capacity expansion for die-stacking technology and strategic partnerships between memory vendors and GPU designers.
Among South Korea-based fabricators, Samsung Electronics Co., Ltd. and SK hynix Inc. exemplify the scale-driven archetype through captive control over Pyeongtaek fabrication complexes. Micron Technology, Inc. represents geographic diversification strategy, operating distinct supply chains across US, Singapore, and Taiwan facilities to navigate trade policy fragmentation. These three entities anchor competitive positioning in advanced nodes while specialty players occupy positions in automotive-qualified and low-power segments.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| SK hynix Inc. |
| Micron Technology, Inc. |
| Kioxia Holdings Corporation |
| Western Digital Corporation |
| Nanya Technology Corporation |
| Winbond Electronics Corporation |
| Macronix International Co., Ltd. |
| Infineon Technologies AG |
| Others |
Supply & Pricing Matrix
ASML's EUV equipment order backlogs in the Netherlands concentrate upstream bargaining power, compressing margin pools for DRAM and NAND fabricators while hyperscale data center operators capture downstream pricing leverage through direct wafer-level procurement agreements.
Pricing Analysis
DDR5-to-DDR4 pricing spreads widen during server platform transitions, while HBM3E commands substantial premiums over standard DRAM through GPU vendor qualification gates. Contract-based long-term offtake agreements dominate hyperscale procurement, with price differentiation driven by volume scale and thermal grade certification. Cost compression in commodity NAND runs through QLC endurance limitations and enterprise SSD inventory absorption. Consumer smartphone OEMs exhibit highest price sensitivity; AI training cluster operators demonstrate lowest sensitivity due to performance-per-watt imperatives.
Supply Chain Analysis
Extended payment terms from South Korean fabricators to Japanese photoresist and silicon wafer suppliers illustrate supply-chain finance dependencies at critical input tiers. Advanced bit production concentrates in South Korea, Taiwan, and the United States, drawing from EUV lithography systems, 300mm prime-grade silicon, and specialty process gases. Single-source vulnerability around Pyeongtaek clustering creates tariff exposure and logistics chokepoint risk. Distribution runs through direct die sales to cloud operators alongside traditional module vendor channels for enterprise and consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Memory subsystem standardization around CXL and HBM interfaces is reconfiguring platform economics, with interoperability mandates from GPU vendors and CPU architects forcing new partnership hierarchies across the fabrication base.
For Market Incumbents: Entrench hybrid bonding capacity leadership through Pyeongtaek and Idaho facility expansion, while securing GPU vendor co-development agreements against emerging logic-memory integration threats from foundry competitors. Prioritize AEC-Q100 Grade 1 certification investment to defend automotive segment margins against European and Japanese specialty suppliers. For New Entrants and Emerging Players: Establish a beachhead in automotive edge computing through GDDR6 and LPDDR5 qualification for ADAS sensor fusion, where 24-36 month timelines deter incumbent resource reallocation. Target industrial IoT segments in Europe requiring secured elements with immutable boot ROM, leveraging REACH compliance as a qualification barrier against Asian commodity suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward specialty DRAM fabricators with captive packaging capabilities in Taiwan and Japan, positioned for 5-10 year automotive and networking demand trajectories. Monitor HBM3E yield ramp rates at major suppliers as the signal indicating AI training cluster supply adequacy and pricing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Samsung and SK hynix are scaling die-stacking facilities to meet GPU vendor HBM3E integration requirements. |
| US CHIPS Act Facility Buildout | Micron is qualifying greenfield DRAM and NAND fabs in Idaho and New York for domestic hyperscale supply. |
| Automotive Safety Certification Investment | Infineon and Kioxia are pursuing ISO 26262 and AEC-Q100 Grade 1 for ADAS memory modules. |
| CXL Memory Pooling Partnership | Intel and AMD platform vendors are integrating CXL-attached DRAM for disaggregated server architectures. |
| EUV Photoresist Chemistry Localization | Japanese suppliers are expanding Kyoto-Osaka facilities to reduce ASML equipment dependency risks. |
Research Methodology
The analysis maps DRAM, NAND, SRAM, and specialty memory segments, each validated through semiconductor fabrication executives, hyperscale data center procurement officers, GPU vendor platform architects, and automotive Tier-1 supplier quality directors. Primary interview findings triangulate against SEC 10-K filings, hyperscaler capex disclosures, ASML order backlog reports, and customs trade data. Bottom-up bit-demand modeling and top-down fabrication capacity assessment cross-validate volume and value outputs.
Fixed assumptions across the analysis window include sustained AI training cluster deployment rates, EUV equipment delivery schedules, and K-Semiconductor Belt subsidy continuity. Variable stress parameters encompass DDR5 attach rate acceleration, 3D NAND layer-count migration timelines, and automotive qualification cycle compression. Segmentation dimensions span product architecture, end-use environment, process node, and device form factor. CAGRs derive from bit-growth trajectories and blended average selling price evolution, with inputs from silicon wafer supply tightness and photolithography node migration economics.
Stress conditions across EUV equipment availability, geopolitical trade policy fragmentation, and raw material input volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition cadence and demand concentration patterns. Macroeconomic contraction, regulatory restriction on fluorinated process gases, or breakthrough in alternative memory architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Contactless Memory Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Memory Market
Memory Chips
DRAM Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
DDR RAM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
China Flash Memory Market
Memory Chips
Smartphone RAM Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Memory Chip Market
Memory Chips
LPDDR5 DRAM Market