
 South Korea Integrated Circuits Market | 2026-2036
South Korea Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Integrated Circuits Market Insights
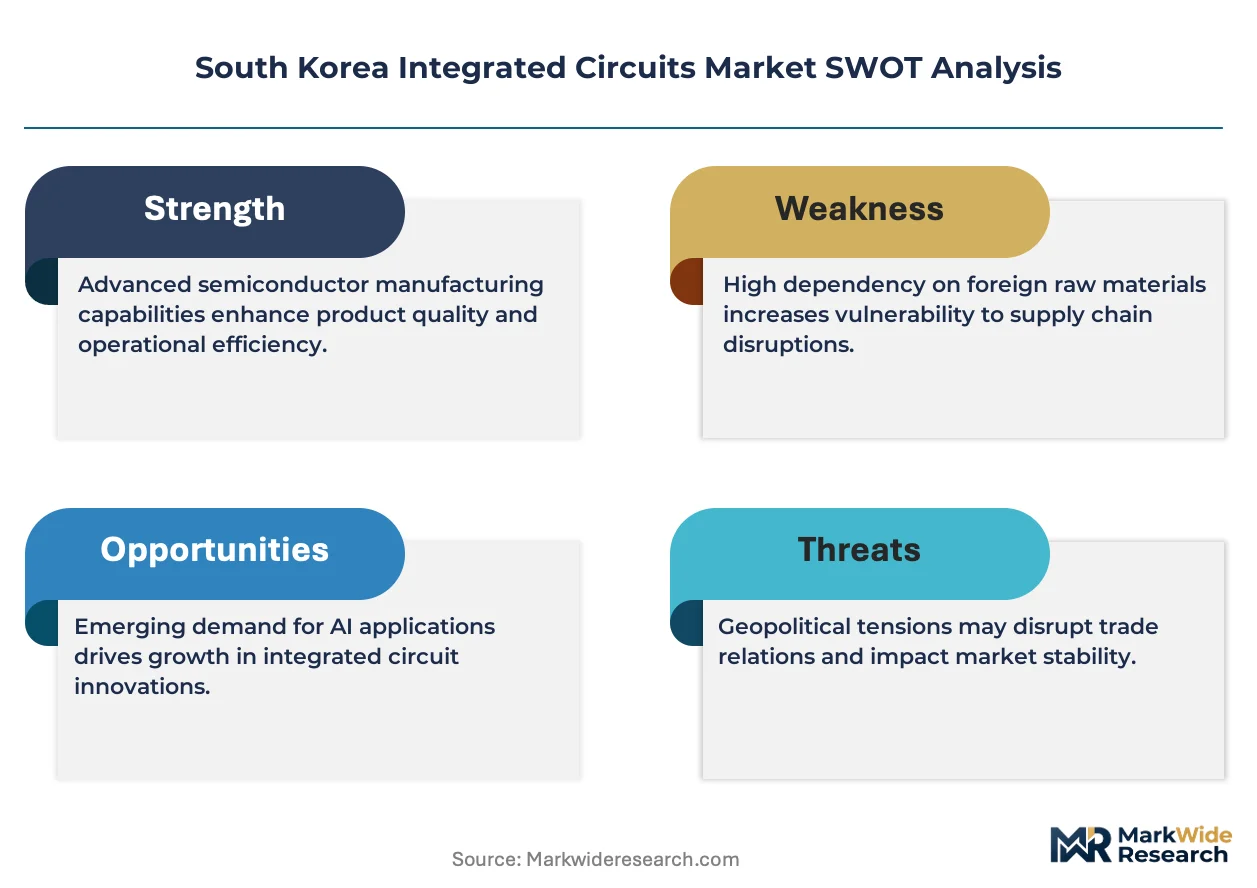
Domestic foundry capacity in South Korea is expanding to secure supply chain autonomy for advanced logic and memory production. Samsung Electronics leverages vertical integration from wafer fabrication to system-level packaging, sustaining technology leadership in DRAM and NAND flash. SK Hynix anchors the high-bandwidth memory segment with specialized HBM manufacturing for AI accelerators. DB HiTek competes in the mature-node analog and power IC space, occupying a distinct position below the leading memory duopoly.
Integrated circuits are miniaturized electronic assemblies of transistors, resistors, and capacitors fabricated on semiconductor substrates, typically silicon wafers processed through photolithography, etching, and deposition steps with feature sizes now reaching sub-3 nanometer nodes in leading-edge production. These devices serve as the computational and control cores of virtually all electronic systems, executing data processing, signal modulation, and power management functions. Memory chips command the largest revenue pool in the South Korean market given the country's established DRAM and NAND flash infrastructure. CMOS technology dominates fabrication economics for logic and consumer applications, while GaAs retains structural importance in telecommunications RF components where high-frequency performance justifies material costs. Automotive end-use applications represent the fastest-growing demand segment as electric vehicles and advanced driver-assistance systems multiply semiconductor content per vehicle.
MFDS oversight of medical device electronics and KOSHA workplace safety standards shape manufacturing facility design and operational compliance for domestic producers. The K-Chips Act and related fiscal incentives from METI channel capital toward advanced process nodes and packaging technologies, directly influencing capacity investment timelines. Stakeholders must monitor how export control alignments with US Department of Commerce regulations affect equipment procurement and technology transfer pathways for South Korean fabricators.
Market Dynamics
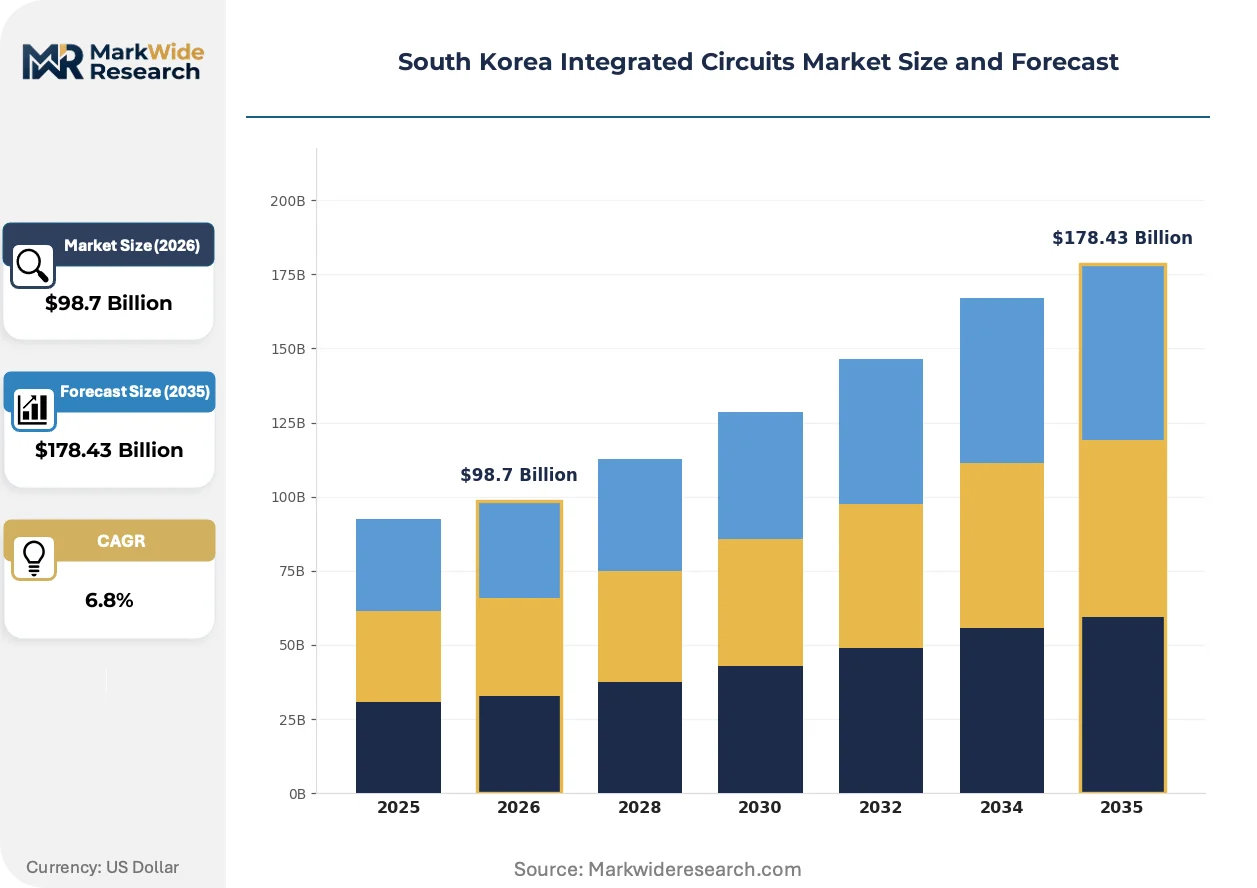
Advanced packaging technologies and heterogeneous integration are compressing traditional supply chain tiers in South Korean semiconductor manufacturing. The K-Chips Act channels public capital toward 2nm-class fabrication facilities while automotive electronics demand reshapes capacity allocation across memory and logic segments.
Growth Catalysts
- Automotive electronics demand:Electric vehicle platforms and advanced driver-assistance systems multiply semiconductor content per vehicle, pulling capacity toward power management and sensor interface chips.
- K-Chips Act fiscal incentives:Tax credits and subsidized infrastructure accelerate domestic investment in sub-3nm process nodes and advanced packaging facilities.
- AI accelerator deployment:High-bandwidth memory architectures serve training and inference workloads, sustaining specialized DRAM process development.
Market Restraints
- Equipment import dependency:Lithography and deposition tool procurement concentrates among Dutch and Japanese suppliers, creating vulnerability to export control alignment shifts.
- Raw material cost volatility:Neon gas and high-purity silicon wafer prices fluctuate with energy market conditions, compressing foundry margin structures.
- Technical limitation at atomic scale:Quantum tunneling effects and power density constraints impede further planar scaling, forcing costly architectural pivots to gate-all-around transistors.
Strategic Opportunities
- Chiplets and disaggregated design:Modular die integration enables cost optimization across process nodes, opening foundry services to fabless system designers.
- Power semiconductor expansion:Silicon carbide and gallium nitride substrates address electric vehicle traction inverter requirements, diversifying beyond silicon CMOS.
- Regulatory tailwind from carbon accounting:EU CSRD disclosure requirements and South Korean green bond frameworks reward low-carbon fabrication processes with preferential capital access.
Industry Challenges
- Process engineer scarcity:Sub-5nm node expertise concentrates among veteran practitioners, constraining fab ramp timelines and yield recovery.
- Legacy system integration friction:200mm and 300mm wafer production lines operate incompatible automation protocols, complicating capacity reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Integrated Circuits Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Memory Chips, Analog ICs, Digital Signal Processors End User: Consumer Electronics, Telecommunications, Automotive, Industrial Technology: CMOS, BiCMOS, GaAs, SOI Application: Data Processing, Signal Processing, Communication, Control Systems |
| Companies Covered | Samsung Electronics, SK Hynix, LG Innotek, Samsung Electro-Mechanics, DB HiTek, Hana Micron, Hanmi Semiconductor, Nepes, Silicon Works, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Integrated Circuits Market Trends and Innovations
Process-node advancement and packaging innovation are converging to redefine competitive advantage in South Korean semiconductor manufacturing. Three developments merit particular attention.
Gate-all-around transistor architecture replaces finFET structures at 2nm-class nodes, delivering superior electrostatic control and power efficiency. Samsung Foundry and memory divisions deploy this technology for logic and high-density storage applications. The format is expanding into mobile application processors and data center accelerators, compressing incumbent planar transistor supply chains.
MFDS medical device regulations and KOSHA workplace safety standards tighten contamination control and chemical handling protocols across fabrication facilities. These requirements elevate capital expenditure for cleanroom infrastructure and exhaust treatment systems. Analog and mixed-signal foundries serving implantable device markets adapt fastest, securing long-term supply agreements with diagnostic equipment manufacturers.
Direct chiplet procurement from multiple foundries displaces single-source wafer purchasing among system integrators. Automotive Tier 1 suppliers now assemble multi-die modules from heterogeneous sources, bypassing traditional packaged component distributors. This pattern concentrates in Seoul metropolitan cluster electronics manufacturing, where proximity enables rapid qualification cycles.
South Korea Integrated Circuits Market Segmentation
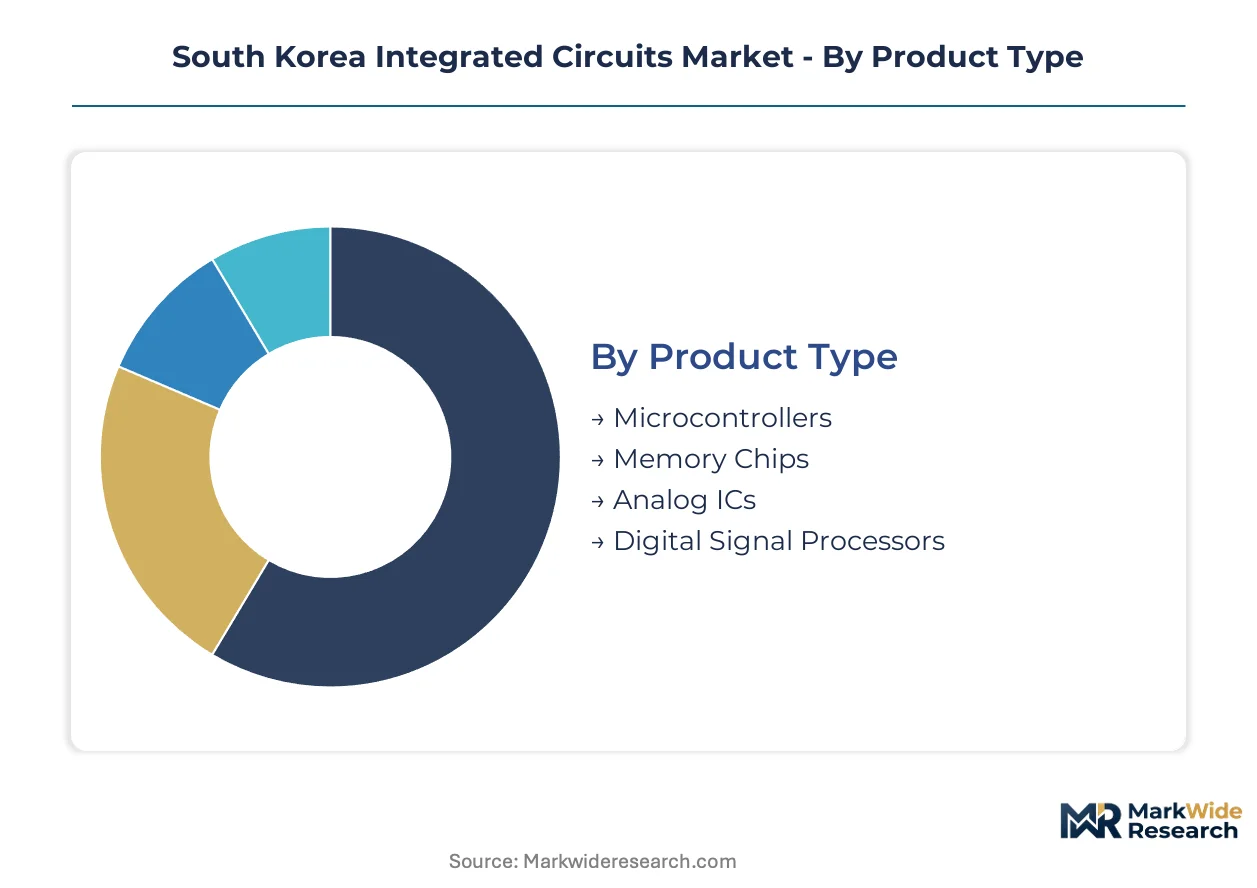
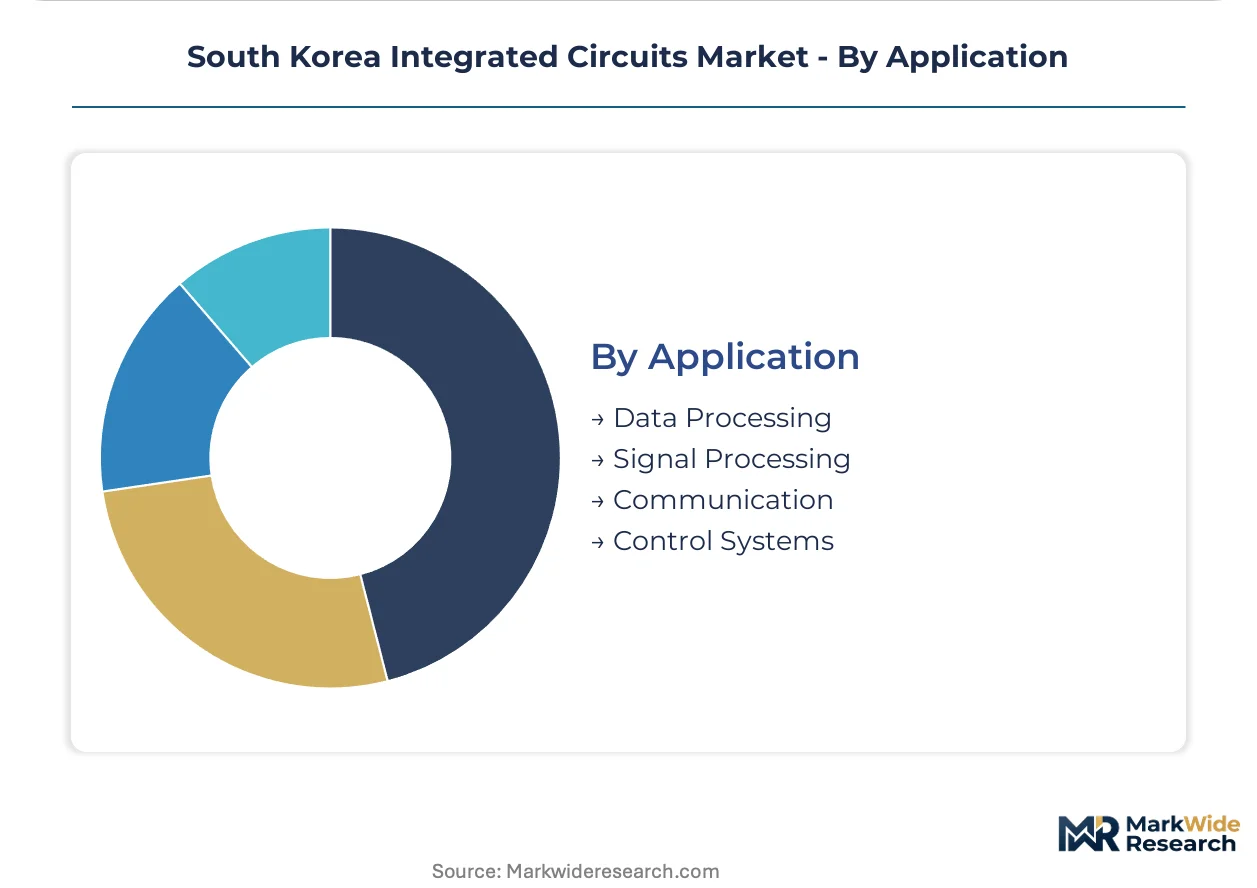
Semiconductor segmentation in South Korea reveals how fabrication capacity aligns with distinct technical requirements and end-use specifications. Each dimension—product architecture, customer industry, process technology, and functional application—shapes investment priorities across Samsung Electronics, SK Hynix, and the domestic foundry ecosystem.
Product Type:
Upgrade cycles in consumer devices and enterprise infrastructure drive replacement demand across distinct IC architectures.
- Memory Chips:DRAM and NAND flash devices store executable code and persistent data in bit-addressable cell arrays. Demand concentrates in Seoul metropolitan cluster data centers and AI training facilities where SK Hynix HBM3E serves NVIDIA accelerator boards. K-Chips Act subsidies accelerate 3D NAND layer-count expansion.
- Microcontrollers:Embedded processing units integrate CPU cores with on-chip memory and peripheral interfaces for deterministic control tasks. Automotive ECU procurement from Hyundai Motor Group and Kia pulls capacity toward 40nm-90nm automotive-qualified nodes.
- Analog ICs:Continuous-signal processing devices manage power conversion, sensor interfacing, and RF modulation. DB HiTek foundry capacity in Bucheon serves industrial motor drive and display driver applications.
- Digital Signal Processors:Specialized arithmetic units execute fast Fourier transforms and filter operations for real-time data streams. Base station infrastructure deployments by Samsung Networks absorb DSP supply for 5G massive MIMO arrays.
Volume placements concentrate in Memory Chips; the faster expansion belongs to Microcontrollers.
End User:
Customer industry margins and qualification timelines differentiate procurement patterns across the South Korean supply base.
- Automotive:Electric vehicle traction inverters, battery management systems, and ADAS sensor fusion modules demand AEC-Q100 qualified components. Hyundai Motor Group's Asan and Ulsan plants multiply semiconductor content per platform.
- Telecommunications:5G baseband processors, RF front-end modules, and optical transceivers serve domestic carrier infrastructure. Samsung Electronics' Suwon campus anchors R&D for millimeter-wave beamforming ICs.
- Consumer Electronics:Smartphone application processors, OLED display drivers, and camera image sensors ship to Samsung Mobile and LG Electronics assembly lines. Flagship device launch cadences synchronize foundry capacity allocation.
- Industrial:Programmable logic controllers, motor drives, and power inverters operate across extended temperature ranges. Factory automation adoption in Gyeonggi-do manufacturing corridors sustains demand for ruggedized packaging.
Revenue concentration sits with Consumer Electronics; Automotive climbs fastest on electrification mandates.
Technology:
Process node economics and material substrate characteristics determine competitive positioning in South Korean wafer fabrication.
- CMOS:Complementary metal-oxide-semiconductor logic dominates digital integration with mature design tools and scalable lithography. Samsung Foundry's Pyeongtaek campus produces 3nm GAA-class mobile processors.
- GaAs:Gallium arsenide substrates deliver superior electron mobility for microwave and millimeter-wave amplification. RF component demand from defense and satellite communications programs sustains specialized epitaxial growth capacity.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog performance with digital logic density. Precision data converters in medical imaging equipment exploit this hybrid process.
- SOI:Silicon-on-insulator structures reduce parasitic capacitance and leakage for low-power RF and high-voltage applications. Automotive radar front-ends adopt SOI substrates for improved signal isolation.
CMOS commands the dominant capacity share; SOI gains traction fastest in automotive radar penetration.
Application:
Functional purpose determines architectural trade-offs between computational throughput, energy efficiency, and real-time determinism.
- Data Processing:General-purpose and AI-accelerated computation for cloud and edge workloads. High-bandwidth memory integration with logic dies serves training cluster deployments.
- Communication:Physical layer modulation, protocol stack execution, and antenna beamforming for wireless and wireline networks. 5G-Advanced standardization drives baseband complexity upward.
- Signal Processing:Analog-to-digital conversion, filtering, and compression for sensor and media streams. Audio codec integration in TWS earbuds exemplifies low-power implementation.
- Control Systems:Closed-loop regulation of mechanical, thermal, and electrical parameters in industrial and automotive contexts. Functional safety certification to ISO 26262 constrains design methodology.
Data Processing absorbs the largest wafer starts; Communication applications expand most quickly on network infrastructure refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon wafer production in Ulsan and neon gas processing near Seoul supply critical feedstocks for South Korean fabrication facilities. Domestic cluster formation concentrates advanced packaging and memory assembly in the Seoul metropolitan corridor.
Seoul Capital Area
AI accelerator deployment and hyperscale data center construction drive HBM3E demand from SK Hynix. The K-Chips Act channels tax credits toward Pyeongtaek fab expansion. Samsung Electronics anchors 3nm gate-all-around logic production in Suwon and Hwaseong.
Busan-Ulsan
Automotive electronics procurement from Hyundai Motor Group multiplies power semiconductor content per electric vehicle platform. KOSHA workplace safety standards govern cleanroom chemical handling protocols. Ulsan semiconductor material plants supply silicon wafers to domestic foundries.
Daegu-Gyeongbuk
Defense and satellite communications programs sustain gallium arsenide epitaxial growth capacity for RF components. National strategic technology designation streamlines export licensing for compound semiconductor equipment. Daegu technology parks host specialized analog foundry operations.
Daejeon-Sejong
Research institute collaboration on advanced packaging architectures supports heterogeneous integration roadmaps. Government R&D procurement under K-Chips Act implementation funds chiplet interconnect development. Sejong administrative city concentration enables rapid regulatory coordination for pilot production lines.
Gwangju-Honam
Display driver IC and image sensor packaging demand from LG Electronics and Samsung Mobile pulls assembly capacity southwest. Regional development incentives under national semiconductor cluster policy attract backend service providers. Gwangju free economic zone infrastructure supports outsourced semiconductor assembly and test operations.
South Korea Integrated Circuits Market Competitive Landscape
Global memory leaders compete with regional packaging specialists and analog foundries across process node tiers and end-use applications. Market structure concentrates in a memory duopoly with fragmented competition in mature-node logic and backend services. Three archetypes dominate: vertically integrated memory conglomerates, specialized analog foundries, and outsourced assembly providers. Capacity expansion and heterogeneous integration partnerships constitute the primary competitive vectors reshaping positioning.
Within the vertically integrated tier, Samsung Electronics exemplifies captive wafer fabrication and system-level packaging control. SK Hynix occupies a position as high-bandwidth memory anchor for AI accelerator supply chains. DB HiTek represents mature-node analog specialization serving industrial and automotive power management segments.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| LG Innotek |
| Samsung Electro-Mechanics |
| DB HiTek |
| Hana Micron |
| Hanmi Semiconductor |
| Nepes |
| Silicon Works |
| Others |
Pricing and Supply Chain Analysis
Captive wafer fabrication at Samsung Electronics and SK Hynix anchors supply security while concentrating pricing power in advanced memory nodes. This vertical control over epitaxial growth through system-level packaging insulates domestic leaders from foundry margin volatility but exposes them to equipment import dependency.
Pricing Analysis
Long-term contract structures bundle volume commitments with technical service packages, while spot procurement for commodity-grade wafers leaves after-sales support unbundled. Three-tier pricing structure across premium, standard, and economy levels differentiates by automotive qualification grade and volume scale. Cost compression in mature-node analog foundry services is intensifying because DB HiTek and regional competitors expand 200mm capacity. Automotive Tier 1 suppliers exhibit highest price sensitivity due to platform cost targets, whereas AI accelerator vendors prioritize supply assurance over unit economics.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers including JSR and Tokyo Ohka Kogyo, while extreme ultraviolet lithography equipment draws exclusively from ASML in the Netherlands. High-purity neon gas processing concentrates in Ukraine and China, with silicon wafer feedstock anchored in Japan and the United States. Single-source vulnerability in EUV tool procurement creates structural risk given export control alignment requirements. Distribution runs through captive vertically integrated channels for memory leaders, while analog foundries serve fabless designers through direct technical sales engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korean integrated circuits market functions as a vertical-integration race where captive control over advanced packaging and substrate development determines margin capture. Players pursue downstream leverage through system-level module supply to automotive and AI infrastructure end-users.
For Market Incumbents: Deepen gate-all-around transistor yield learning curves at Pyeongtaek and Hwaseong facilities to defend against TSMC's 2nm ramp. Secure alternative equipment sourcing pathways from Japanese lithography suppliers to mitigate ASML dependency risk. Expand automotive-qualified capacity at 40nm-90nm nodes before Chinese foundries capture Hyundai Motor Group procurement.
For New Entrants and Emerging Players: Capture heterogeneous integration opportunities in chiplet-based power modules for electric vehicle traction inverters. Target the Daegu-Gyeongbuk defense RF segment where gallium arsenide epitaxial capacity remains constrained. Establish direct qualification relationships with Seoul-based automotive Tier 1 suppliers rather than competing on memory commodity economics.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty analog foundry acquisition by industrial semiconductor conglomerates seeking automotive exposure. Long-term viability over the next decade hinges on successful migration to gate-all-around architectures and advanced packaging revenue mix expansion. Monitor K-Chips Act subsidy disbursement velocity as the inflection indicator for domestic capacity expansion commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Process Ramp | Samsung Foundry's 3nm GAA production at Pyeongtaek secures logic leadership against TSMC. |
| HBM3E Capacity Expansion | SK Hynix high-bandwidth memory output serves NVIDIA accelerator board procurement requirements. |
| Automotive Node Qualification | DB HiTek 40nm-90nm automotive certification captures Hyundai Motor Group ECU demand. |
| Advanced Packaging Joint Venture | Heterogeneous integration partnerships enable chiplet assembly for AI training clusters. |
| Silicon Carbide Substrate Development | Power semiconductor expansion addresses electric vehicle traction inverter specifications. |
Research Methodology
SEC 10-K filings, Korea Semiconductor Industry Association trade statistics, and equipment import customs records formed the secondary backbone for this analysis. Primary interviews with fab operations directors, foundry business development leads, automotive Tier 1 procurement managers, and K-Chips Act policy officials validated capacity and investment assumptions. Bottom-up wafer start projections and top-down memory revenue triangulation converged on segment-level estimates across the analysis window.
Historical trendline analysis of DRAM and NAND flash pricing cycles informed demand elasticity assumptions throughout the projection horizon. The analytical framework modeled segmentation across product architecture, end-use industry, process technology node, and functional application. CAGRs derived from capacity expansion timelines and technology transition roadmaps incorporated equipment lead times and yield ramp curves as semiconductor-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EUV equipment export licensing, raw material neon gas supply disruption, and automotive electrification policy acceleration. Forecasts reflect documented assumptions regarding subsidy disbursement schedules and foundry yield achievement rates. A small set of triggers—K-Chips Act revision, China-Taiwan supply contingency activation, and gate-all-around yield inflection—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
PFC Control IC Market