
 Taiwan Analog Integrated Circuits Market | 2026-2036
Taiwan Analog Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Analog Integrated Circuits Market Insights
A widening capability gap between foundry-dependent and fab-lite strategies is redrawing competitive tiers in Taiwan's analog IC sector. Texas Instruments sustains captive fabrication across 300mm analog fabs, securing die supply continuity for voltage regulator portfolios. Infineon Technologies AG anchors its position through insulated-gate bipolar transistor integration for automotive traction inverters. Richtek Technology Corporation specializes in compact DC-DC converters for notebook and handset OEMs clustered around Taipei.
Taiwan Analog Integrated Circuits are continuous-signal processing devices fabricated through precision lithography on silicon or compound semiconductor substrates, with operating parameters spanning microvolt offset voltages to kilovolt isolation ratings. These components condition, regulate, and convert electrical signals in power management, sensor interfacing, and motor control systems across industrial and consumer equipment. Operational amplifiers and voltage regulators occupy the largest share of product-level revenue, reflecting their ubiquity in every electronic subsystem. Automotive applications are expanding fastest as electric vehicle platforms multiply the per-vehicle analog content for battery management and onboard charging. CMOS and BiCMOS technologies dominate wafer starts, though GaN processes are penetrating high-frequency power conversion segments where efficiency thresholds are tightening.
Taiwan's Ministry of Economic Affairs enforces BIS-aligned semiconductor quality standards through the Bureau of Standards, Metrology and Inspection, while the National Communications Commission certifies electromagnetic compatibility for analog components entering telecommunications infrastructure. These frameworks elevate compliance costs for imported die but simultaneously protect domestic packaging and test houses from uncertified foreign competition. Stakeholders must monitor how NCC spectrum reallocation rules and emerging carbon-footprint disclosure requirements from the Environmental Protection Administration reshape component qualification timelines and foundry selection criteria.
Market Dynamics
Wafer-level packaging density requirements and BIS electromagnetic compliance mandates are compressing qualification timelines for Taiwan's analog IC suppliers serving automotive power management systems.
Growth Catalysts
- Automotive electrification:Battery management systems and onboard charging modules multiply per-vehicle analog component counts as electric vehicle platforms expand production volumes across Taichung precision manufacturing corridors.
- Bureau of Standards, Metrology and Inspection alignment:Taiwan's BIS semiconductor quality frameworks protect domestic packaging houses from uncertified foreign competition while streamlining certification for qualified suppliers.
- GaN process penetration:Gallium nitride fabrication for high-frequency power conversion segments addresses tightening efficiency thresholds in server and telecommunications infrastructure applications.
Market Restraints
- 300mm silicon wafer supply concentration:Foundry-dependent strategies face die allocation pressure when captive fabricators like Texas Instruments prioritize internal voltage regulator portfolios during supply crunches.
- NCC electromagnetic compliance costs:National Communications Commission certification requirements for telecommunications infrastructure components elevate qualification expenses for imported die entering Taiwan's packaging ecosystem.
- Silicon carbide substitution threat:SiC power devices displace analog ICs in high-voltage automotive traction inverter applications above 650V operating thresholds.
Strategic Opportunities
- Hsinchu Science Park fab expansion:Underutilized cleanroom capacity among specialty analog foundries enables fabless designers to secure preferential wafer starts for industrial sensor interface products.
- Environmental Protection Administration carbon disclosure:Emerging carbon-footprint reporting requirements create first-mover advantage for domestic suppliers with verified low-emission packaging processes.
- BiCMOS-CMOS convergence:Process technology blending enables single-die integration of precision analog front-ends with digital signal processing for smart factory sensor nodes.
Industry Challenges
- Compound semiconductor process engineering talent:GaN and SiC fabrication expertise scarcity constrains foundry expansion timelines as universities lag in RF power device curriculum updates.
- Multi-die integration complexity:System-in-package analog modules require thermal co-design capabilities that legacy discrete component houses lack, forcing acquisition of advanced simulation tools.
- NCC spectrum reallocation compliance:Rapid electromagnetic compatibility rule revisions for 5G infrastructure components compress product redesign cycles before market withdrawal deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Analog Integrated Circuits Market |
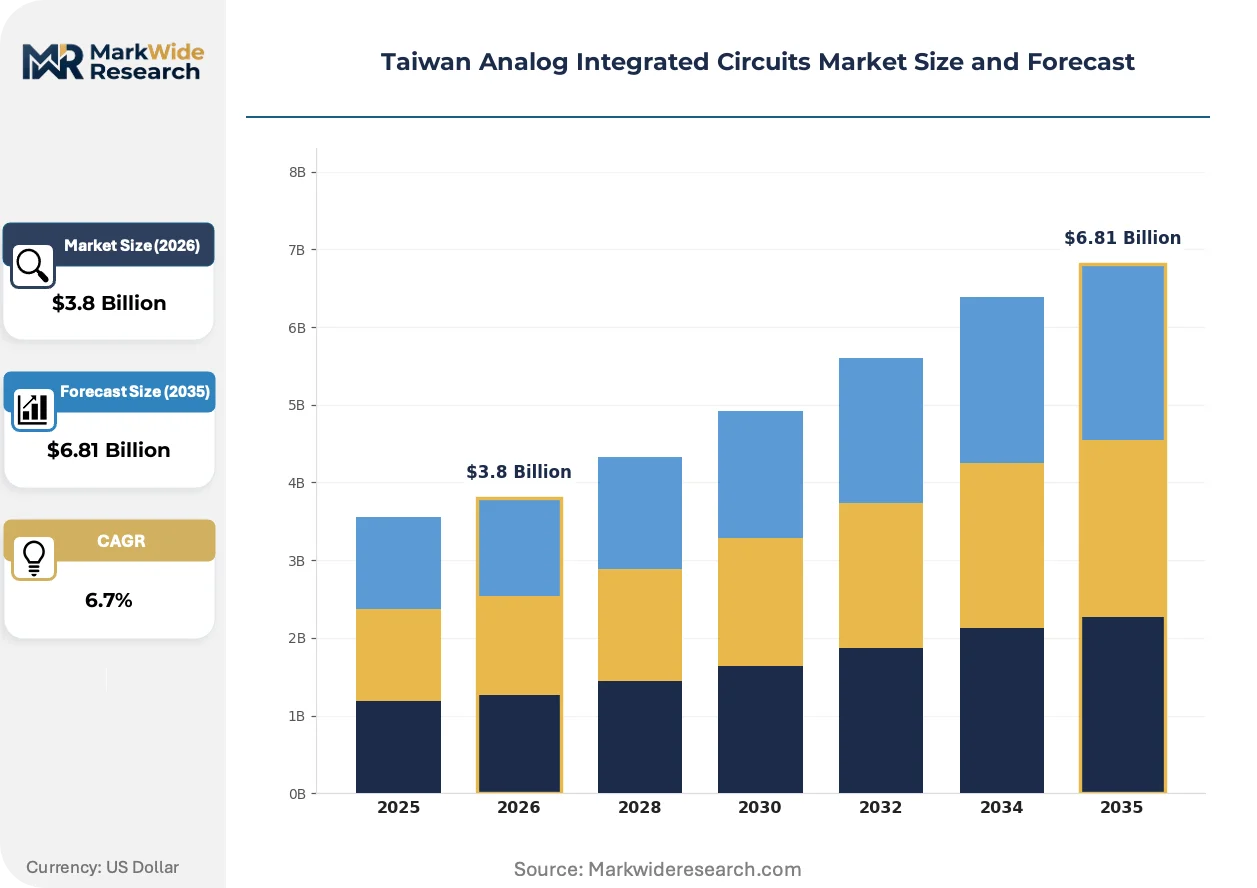
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Resistors Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Cmos, Bipolar, BiCMOS, GaN End User: OEMs, Aftermarket Providers, Contract Manufacturers, System Integrators |
| Companies Covered | Analog Devices Inc., Texas Instruments Inc., Infineon Technologies AG, STMicroelectronics N.V., Renesas Electronics Corporation, Microchip Technology Inc., NXP Semiconductors NV, Richtek Technology Corporation, MediaTek Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Analog Integrated Circuits Market Trends and Innovations
Process geometry compression and heterogeneous integration are redefining performance benchmarks for Taiwan's analog IC suppliers, while regulatory carbon accounting and procurement centralization reshape commercial relationships.
BiCMOS operational amplifiers with sub-microvolt offset voltages now serve precision sensor interfaces in medical and industrial automation equipment. Automotive tier-one suppliers in Taichung corridors are qualifying these devices for battery current sensing at volumes exceeding consumer electronics adoption. The technology is miniaturizing signal conditioning footprints while maintaining isolation ratings previously requiring discrete component assemblies.
Taiwan's Bureau of Standards, Metrology and Inspection is harmonizing semiconductor quality standards with BIS frameworks to accelerate cross-border component recognition. This alignment reduces duplicate testing costs for packaging houses serving both domestic and Indian export markets. Foundries in Hsinchu Science Park are responding by pre-qualifying process flows to dual-jurisdiction specifications before customer tape-out.
Consolidated procurement by notebook and handset OEMs clustered around Taipei is compressing supplier qualification cycles from eighteen months to nine. Volume commitments now precede design wins rather than following them, displacing the traditional sample-trial-production ramp sequence. This concentration is most visible in DC-DC converter sourcing, where Richtek Technology Corporation and comparable specialists face direct annual negotiations with three dominant contract manufacturers.
Taiwan Analog Integrated Circuits Market Segmentation
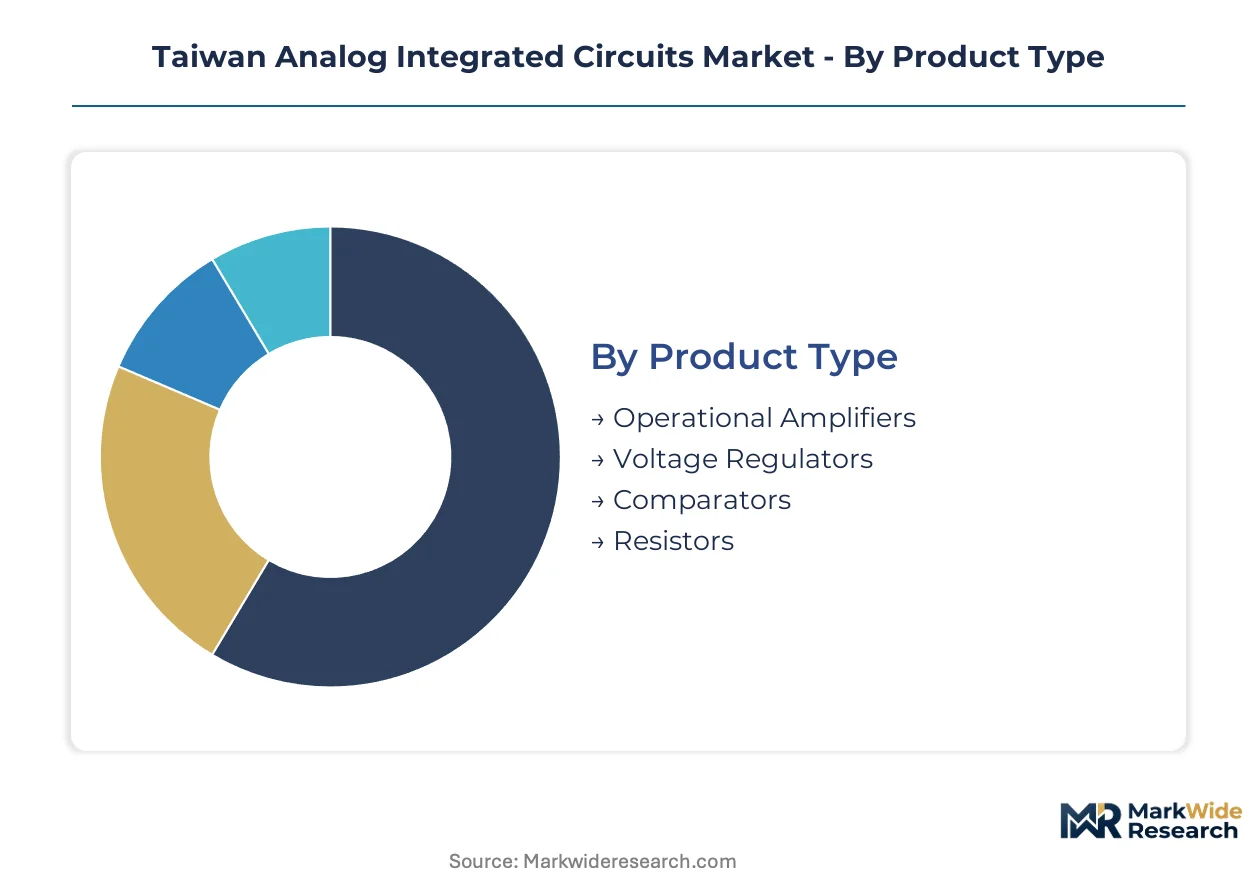
Segmentation reveals how Taiwan's analog IC suppliers allocate wafer capacity across divergent margin profiles and certification requirements. Product mix decisions directly impact foundry loading at Hsinchu Science Park fabs and packaging house utilization in Taichung corridors.
Product Type:
Operational amplifiers and voltage regulators dominate domestic wafer starts, while comparators and resistor arrays serve export-heavy instrumentation markets.
- Operational Amplifiers:Precision signal conditioning devices fabricated through BiCMOS processes achieve sub-microvolt offset voltages for medical and industrial sensor interfaces. Demand concentrates among Taipei-clustered notebook OEMs and Taichung-based battery management system suppliers seeking current sensing accuracy.
- Voltage Regulators:Power management ICs regulate DC output across load variations from microamp standby currents to multi-amp processor cores. Automotive electrification in Taichung precision manufacturing corridors multiplies per-vehicle content for DC-DC conversion in onboard charging modules.
- Comparators:High-speed threshold detection circuits trigger protection responses in motor control and power supply feedback loops.
- Resistors:Precision thin-film and thick-film passive elements establish reference voltages and current limits in discrete analog subsystems.
Voltage regulators hold the largest share; momentum sits with operational amplifiers.
Application:
Automotive and industrial automation applications command premium pricing through BIS-aligned qualification requirements, while consumer electronics and telecommunications serve higher volume, compressed margin segments.
- Consumer Electronics:Notebook and handset power management ICs from Taipei-area OEMs drive high-volume DC-DC converter demand with eighteen-month product lifecycles.
- Automotive:Battery management systems and traction inverter interfaces require AEC-Q100 qualification and BIS semiconductor quality certification through the Bureau of Standards, Metrology and Inspection. Electric vehicle platform expansion across Taichung manufacturing corridors multiplies analog content per vehicle.
- Industrial Automation:Smart factory sensor nodes integrate precision analog front-ends with digital processing for process control and predictive maintenance.
- Telecommunications:Base station power amplifiers and RF signal chains demand NCC electromagnetic compliance certification, elevating qualification costs for packaging houses serving 5G infrastructure.
Consumer electronics holds the largest share; automotive is climbing the fastest.
Technology:
CMOS and BiCMOS processes anchor Hsinchu Science Park wafer production, while GaN fabrication requires compound semiconductor expertise concentrated among specialized foundries.
- CMOS:Complementary metal-oxide-semiconductor dominates analog IC wafer starts through cost-efficient scaling and digital integration compatibility for mixed-signal designs.
- Bipolar:Junction transistor processes deliver superior transconductance and noise performance for precision voltage references and high-speed comparators in instrumentation equipment.
- BiCMOS:Process technology blending enables single-die integration of precision analog front-ends with digital signal processing for smart factory sensor nodes in Taichung industrial corridors.
- GaN:Gallium nitride fabrication addresses tightening efficiency thresholds in server power supplies and telecommunications infrastructure, though RF power device curriculum gaps constrain foundry expansion timelines.
CMOS holds the largest share; GaN shows the steepest expansion trajectory.
End User:
OEMs and contract manufacturers concentrate procurement power around Taipei, while aftermarket providers and system integrators fragment demand across specialized industrial applications.
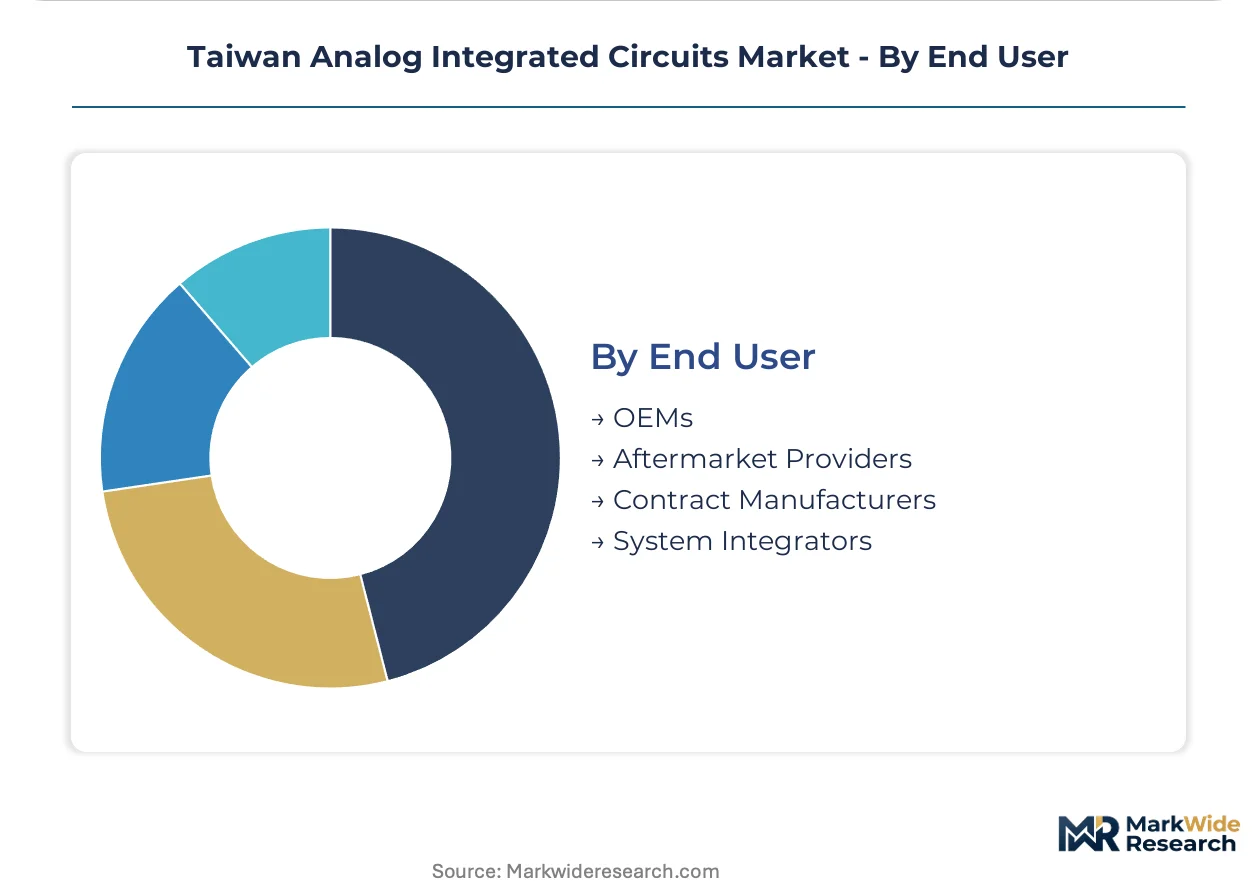
- OEMs:Original equipment manufacturers in consumer electronics and automotive verticals consolidate annual analog IC procurement through direct supplier negotiations, compressing qualification cycles from eighteen months to nine.
- Aftermarket Providers:Replacement component distributors serve repair and upgrade markets for industrial equipment and vehicle electronics with lower volume, higher margin profiles.
- Contract Manufacturers:Electronics manufacturing services providers in Taipei corridors centralize DC-DC converter sourcing through dominant three-firm procurement structures.
- System Integrators:Industrial automation specialists combine analog sensor interfaces with control systems for smart factory deployments across Taiwan's precision manufacturing regions.
OEMs hold the largest share; contract manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Hsinchu Science Park fabs while Taichung precision manufacturing corridors absorb margin pressure from consolidated procurement. Taiwan's analog IC market exhibits sharp regional differentiation between captive fabrication clusters and foundry-dependent packaging ecosystems.
Hsinchu Science Park
Specialty analog foundries command premium wafer starts for industrial sensor interfaces and automotive power management ICs. The Bureau of Standards, Metrology and Inspection enforces BIS-aligned semiconductor quality certification that protects domestic packaging houses from uncertified foreign competition. Cleanroom capacity expansion accelerates as fabless designers secure preferential allocation for BiCMOS operational amplifiers.
Taichung Precision Manufacturing Corridor
Battery management system suppliers multiply per-vehicle analog content as electric vehicle platforms expand production volumes across this central Taiwan industrial belt. National Communications Commission electromagnetic compliance mandates elevate qualification costs for telecommunications infrastructure components entering the packaging ecosystem. Tier-one automotive suppliers cluster here to qualify AEC-Q100 devices for traction inverter interfaces.
Taipei Metropolitan Cluster
Notebook and handset OEMs drive high-volume DC-DC converter demand with compressed eighteen-month product lifecycles. Consolidated procurement by three dominant contract manufacturers has shortened supplier qualification cycles from eighteen months to nine. Richtek Technology Corporation anchors this corridor's compact converter specialization for portable electronics.
Kaohsiung Industrial Zone
Legacy discrete component houses face thermal co-design capability gaps as system-in-package analog modules proliferate. Environmental Protection Administration carbon-footprint disclosure requirements create first-mover advantage for suppliers with verified low-emission packaging processes. Marine logistics infrastructure supports export-oriented resistor and comparator production for instrumentation markets.
Taiwan Analog Integrated Circuits Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across Taiwan's analog IC sector. Captive fabricators with 300mm analog fabs secure die supply continuity while foundry-dependent competitors face allocation pressure during supply crunches. Three archetypes dominate: vertically integrated multinationals with in-house fabrication, fabless specialists targeting narrow application segments, and hybrid players blending outsourced wafer production with proprietary packaging. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure cleanroom access and electromagnetic compliance certification.
Among US-based integrated device manufacturers, Texas Instruments Inc. and Analog Devices Inc. occupy positions exemplifying captive fabrication strategies. Infineon Technologies AG represents European vertically integrated competition with automotive power management specialization. Within the fabless tier, Richtek Technology Corporation anchors Taiwan-native DC-DC converter expertise for notebook and handset OEMs clustered around Taipei.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Texas Instruments Inc. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| NXP Semiconductors NV |
| Richtek Technology Corporation |
| MediaTek Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts lock in wafer starts at Hsinchu Science Park foundries while fixing die costs for voltage regulator and operational amplifier portfolios. These arrangements give fabless designers price visibility across multi-year automotive qualification cycles, even as spot-market silicon wafers fluctuate with raw material availability.
Pricing Analysis
Configured-to-order pricing for AEC-Q100 qualified automotive devices commands spreads exceeding standard consumer-grade operational amplifiers by factors tied to BIS certification through the Bureau of Standards, Metrology and Inspection. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive from industrial-grade and unqualified consumer variants. Cost compression in notebook DC-DC converters is intensifying because Taipei-area OEMs consolidated procurement through three dominant contract manufacturers. Consumer electronics buyers exhibit highest price sensitivity, while automotive tier-one suppliers accept premium positioning for guaranteed die supply.
Supply Chain Analysis
Strategic stockpile preferences dominate automotive analog IC procurement as battery management system suppliers buffer against 300mm silicon wafer allocation crunches. Taiwan, South Korea, and Japan concentrate specialty analog foundry capacity, while high-purity silicon wafers and specialized photoresists feed from Japanese and German chemical suppliers. Single-source vulnerability concentrates in 300mm wafer supply when captive fabricators like Texas Instruments prioritize internal portfolios. Distribution runs through direct OEM negotiations for high-volume consumer segments and authorized distributors for industrial aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as electric vehicle platform diversification multiplies battery management system variants beyond standardized consumer electronics volumes. This demand-side shift creates niche openings for specialized DC-DC converter and sensor interface suppliers.
For Market Incumbents: Shield die supply continuity through captive fabrication or preferential foundry allocation agreements at Hsinchu Science Park. Acquire thermal co-design simulation capabilities to address system-in-package analog module complexity. GaN process engineering talent scarcity threatens expansion timelines; secure university partnerships or specialist hiring before competitors.
For New Entrants and Emerging Players: Lead with carbon-verified packaging processes to capture Environmental Protection Administration disclosure advantages ahead of incumbent certification. Target Kaohsiung Industrial Zone aftermarket providers with precision resistor and comparator replacements for industrial instrumentation. Pursue direct qualification with Taipei contract manufacturers bypassing traditional sample-trial-production ramp sequences.
For Investors and Strategic Acquirers: Capital is best deployed toward fabless specialists with validated AEC-Q100 portfolios and established BIS certification pathways. Long-term viability centers on automotive electrification content multiplication rather than consumer electronics volume exposure. Watch NCC spectrum reallocation compliance deadlines as inflection indicators for telecommunications infrastructure component redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Qualification | Enables high-frequency power conversion for server and telecommunications infrastructure efficiency thresholds. |
| AEC-Q100 Certification Investment | Opens battery management system sourcing from Taichung electric vehicle tier-one suppliers. |
| Carbon-Verified Packaging Scale-Up | Captures first-mover advantage under Environmental Protection Administration disclosure requirements. |
| BiCMOS-CMOS Convergence R&D | Integrates precision analog front-ends with digital processing for smart factory sensor nodes. |
| Hsinchu Foundry Partnership | Secures preferential wafer starts for industrial sensor interface products amid capacity constraints. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of foundry utilization reports, Bureau of Standards inspection records, and National Communications Commission certification databases. Semiconductor design engineers, packaging house operations managers, automotive tier-one procurement leads, and Taipei OEM supply chain directors contributed structured interviews. Secondary validation drew from customs wafer import data, Hsinchu Science Park economic bulletins, and Environmental Protection Administration carbon disclosure filings. Bottom-up die demand estimates and top-down fab capacity assessments triangulate market sizing.
Segmentation dimensions modeled span product type, application vertical, process technology, and end-user procurement structure across the projection horizon. Automotive content per vehicle, electric vehicle platform rollout schedules, and NCC electromagnetic compliance revision timelines fed growth trajectory calculations. CAGRs derive from wafer start projections calibrated to foundry capex announcements and packaging house utilization trends.
Underlying assumptions cover sustained electric vehicle electrification, stable BIS-NCC regulatory alignment, and continued 300mm silicon wafer availability, with deviation risk concentrated in compound semiconductor process engineering pipeline gaps. Revision becomes warranted when GaN or SiC substitution rates in high-voltage automotive applications cross thresholds that displace silicon analog IC content.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market