
 Global Application Specific Computer Analog IC Market | 2026-2036
Global Application Specific Computer Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Specific Computer Analog IC Market Foresight
The EU F-Gas Regulation is consolidating the cost-of-entry calculus for analog IC suppliers serving European data infrastructure OEMs. Texas Instruments leverages its captive fab network to sustain margin structures under tightening environmental compliance. Renesas Electronics anchors its competitive position through deep integration with Japanese telecommunications equipment makers. ON Semiconductor competes aggressively in silicon carbide-adjacent power management segments where thermal performance standards are escalating.
Application specific computer analog ICs are integrated circuits engineered for dedicated computing workloads, typically fabricated on CMOS or BiCMOS processes with operating voltages from sub-1V to 48V rails and precision tolerances below 0.1%. These devices manage power conversion, signal conditioning, and data conversion within servers, storage arrays, and networking hardware where general-purpose components fail efficiency or latency requirements. Voltage regulators and interface ICs command the largest revenue pools due to their ubiquity across every computing subsystem. Data converters are expanding fastest as AI training clusters multiply high-speed analog-to-digital channels for thermal and power telemetry. Silicon-On-Insulator technology is displacing conventional bulk CMOS in aerospace systems applications where radiation hardness and isolation integrity justify premium pricing.
FDA oversight of medical-grade computing devices, EPA energy efficiency mandates for data center equipment, and REACH substance restrictions on semiconductor packaging materials collectively shape product roadmaps and qualification timelines. China's MIIT dual carbon goals and GB standards for server energy consumption are redirecting procurement specifications toward lower-power analog architectures. Stakeholders must monitor how regulatory divergence between European ECHA chemical restrictions and US EPA efficiency frameworks fragments design standardization and qualification costs.
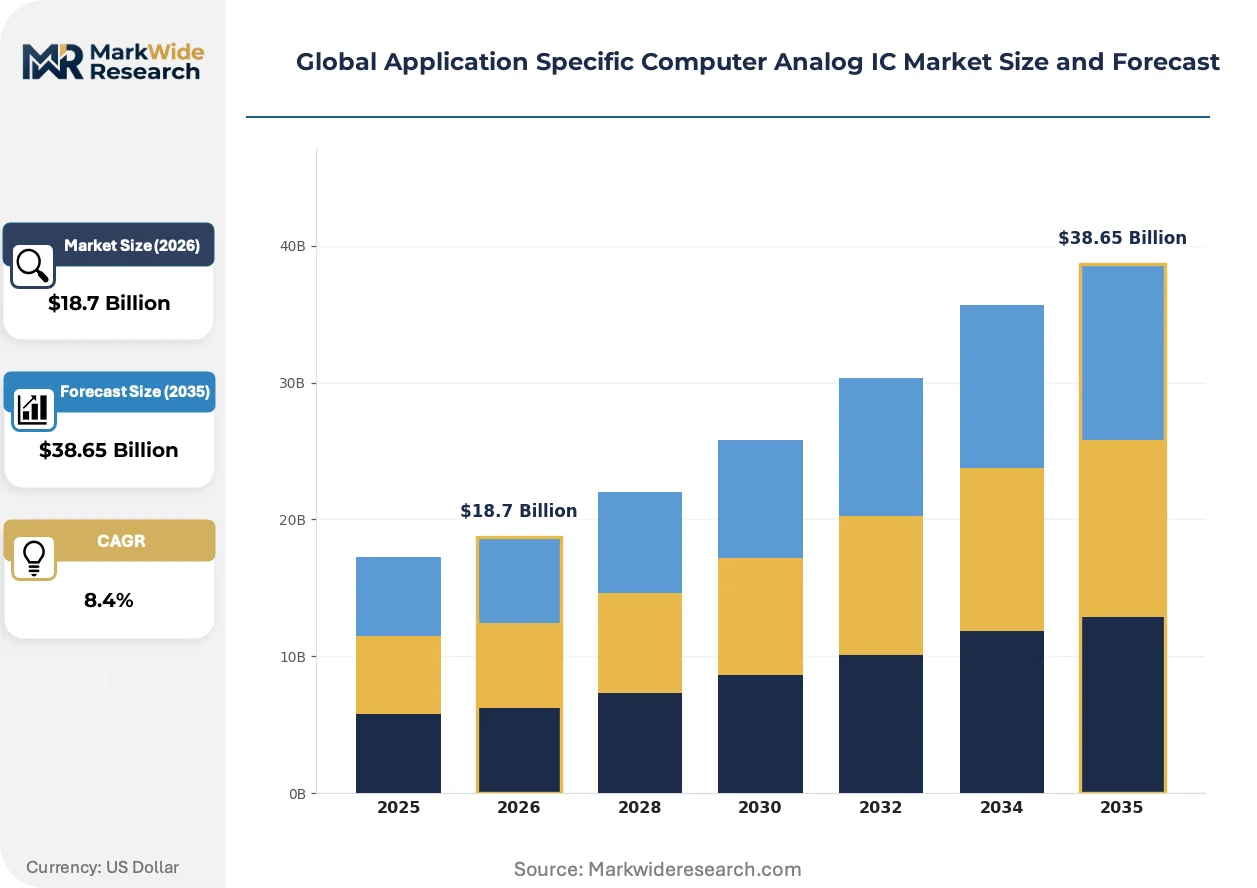
Market Dynamics
Data center power density requirements are compressing voltage regulator tolerances below 0.5% while EU F-Gas Regulation compliance costs escalate qualification timelines for European-bound shipments.
Growth Catalysts
- AI Training Clusters:Hyperscale facilities in China and the US are multiplying high-speed analog-to-digital channels for thermal and power telemetry, expanding data converter demand.
- REACH Compliance:European ECHA substance restrictions on semiconductor packaging materials are forcing design refreshes that favor precision analog IC suppliers with captive environmental testing capabilities.
- Silicon Carbide Adjacency:Thermal performance standards in power management segments are elevating demand for analog signal conditioners capable of 48V rail operation.
Market Restraints
- 300mm Wafer Supply Concentration:Foundry capacity for advanced BiCMOS processes concentrates in Taiwan, creating single-source vulnerability for voltage regulator production.
- Platinum Group Metal Volatility:Wire bonding and plating chemistries face price swings that compress gross margins on high-pin-count interface ICs.
- Optical Interconnect Substitution:Co-packaged optics in AI accelerators threaten to bypass traditional copper-based signal conditioning architectures in high-bandwidth memory interfaces.
Strategic Opportunities
- India Data Center Buildout:Domestic server production scaling under PLI scheme incentives creates demand for locally qualified voltage regulators and power management ICs.
- Satellite Constellation Telemetry:Low-earth orbit networking hardware requires radiation-hardened analog components with isolation integrity specifications that justify premium positioning.
- GB Standard 40879:China's MIIT server energy consumption mandates are redirecting procurement specifications toward lower-power analog architectures in domestic telecommunications equipment.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:The intersection of precision analog layout and digital calibration algorithms requires specialized skill sets concentrated in legacy semiconductor hubs.
- Dual Qualification Burden:Divergent EPA efficiency frameworks and ECHA chemical restrictions fragment design standardization, forcing parallel certification tracks for US and European shipments.
- Legacy System Integration:Retrofitting precision voltage regulators into existing server architectures demands backward compatibility with 12V and 5V legacy rail specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Specific Computer Analog IC Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Data Converters, Voltage Regulators, Interface ICs, Signal Conditioners Technology: CMOS, Bipolar, BiCMOS, Silicon-On-Insulator, Gallium Arsenide Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Control, Instrumentation End User: Original Equipment Manufacturers, Electronics Manufacturing Services, Research Laboratories, Military & Defense |
| Companies Covered | STMicroelectronics, Renesas Electronics, Texas Instruments, Microchip Technology, ON Semiconductor, Analog Devices, NXP Semiconductors, Skyworks Solutions, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Specific Computer Analog IC Market Shifts & Advancements
Silicon-On-Insulator processes are penetrating computing applications where isolation integrity and radiation hardness command pricing power unavailable to bulk CMOS competitors.
Silicon-On-Insulator technology is absorbing market share in aerospace and satellite computing subsystems where single-event upset tolerance justifies 40-60% cost premiums over conventional bulk CMOS. SpaceX and OneWeb constellation suppliers are qualifying SOI-based voltage regulators for orbital telemetry systems. This technology is absorbing design wins that previously defaulted to discrete protection circuitry, compressing board area and component count.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cooling systems out of data center designs, elevating thermal management precision requirements for analog temperature sensors and fan controllers. European OEMs are specifying ICs with extended temperature ranges and calibrated accuracy to support liquid cooling architectures. German and French server manufacturers face the steepest compliance curves, accelerating their analog supplier qualification cycles.
Direct procurement contracts between hyperscale operators and analog IC foundries are disintermediating traditional distribution channels for high-volume voltage regulator programs. Amazon Web Services and Microsoft Azure are negotiating wafer-level agreements that bypass authorized distributors for standard power management SKUs. This pattern is most visible in US and Chinese cloud infrastructure buildouts, where procurement teams prioritize supply security over channel rebates.
Global Application Specific Computer Analog IC Market Segmentation
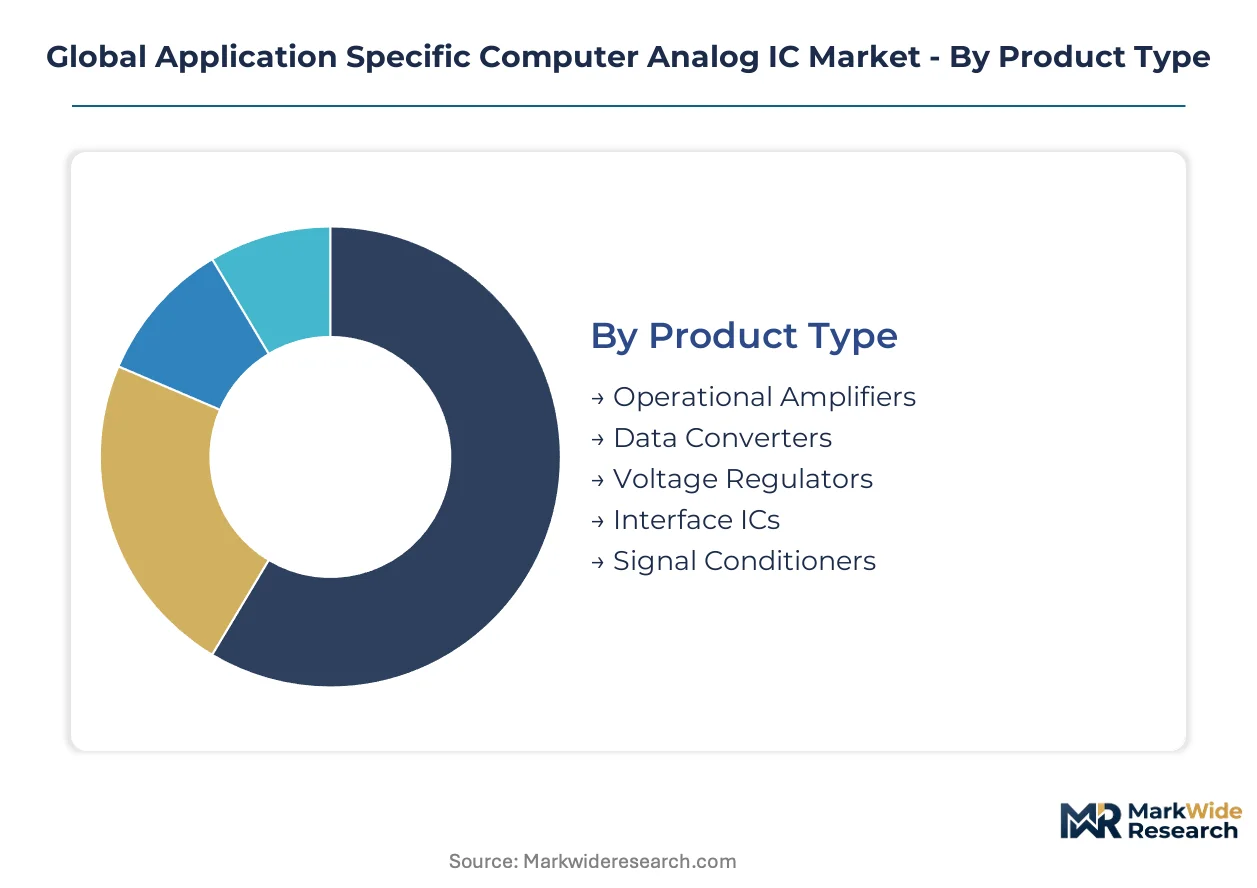
Application specific computer analog ICs fragment across multiple technical and commercial dimensions that determine procurement patterns and margin structures. Voltage regulator and data converter architectures concentrate supply among captive fab operators, while interface IC sourcing disperses across foundry networks. Understanding these segment boundaries clarifies where design qualification costs and supply security risks concentrate for infrastructure OEMs.
Product Type:
Supply concentration for precision analog functions varies sharply by product category, with voltage regulation and data conversion commanding dedicated fab capacity while signal conditioning remains more fragmented.
- Voltage Regulators:These devices manage power rails from sub-1V to 48V with tolerances below 0.5% for AI training clusters. Hyperscale facilities in China and the US are compressing qualification timelines for locally sourced units under MIIT dual carbon procurement mandates.
- Data Converters:High-speed analog-to-digital channels process thermal and power telemetry in server subsystems. Demand is multiplying fastest in China where domestic telecommunications equipment production scales under GB standard 40879 efficiency requirements.
- Operational Amplifiers:Precision amplifiers with sub-millivolt offset voltages serve instrumentation and industrial control applications.
- Interface ICs:High-pin-count signal routing devices face platinum group metal volatility in wire bonding chemistries.
- Signal Conditioners:Analog front-end circuits prepare sensor data for digital processing in aerospace and industrial systems.
Voltage regulators absorb the bulk of installed capacity; data converters are expanding most quickly.
Technology:
Process selection for computer analog ICs trades off isolation performance, radiation hardness, and cost structures across competing substrate technologies.
- Silicon-On-Insulator:Buried oxide layers deliver single-event upset tolerance for orbital computing hardware. SpaceX and OneWeb constellation suppliers are qualifying SOI-based voltage regulators for low-earth orbit telemetry systems where 40-60% cost premiums over bulk CMOS are justified.
- BiCMOS:Combined bipolar and CMOS structures support precision analog functions with digital calibration. Foundry capacity concentrates in Taiwan, creating single-source vulnerability for high-performance regulator production.
- CMOS:Standard bulk processes dominate cost-sensitive consumer electronics and telecommunications applications.
- Bipolar:Pure bipolar fabrication persists in legacy industrial control systems requiring high transconductance.
- Gallium Arsenide:III-V compound semiconductors serve specialized high-frequency instrumentation segments.
BiCMOS carries the heaviest supply concentration risk; SOI is climbing the fastest on satellite constellation demand.
Application:
End-use diversification across computing infrastructure segments determines pricing power and qualification burden for analog IC suppliers.
- Telecommunications Equipment:Baseband processing and optical line termination units require precision voltage references and high-speed data converters. China's domestic server production scaling under MIIT procurement policies is redirecting specifications toward lower-power analog architectures.
- Aerospace Systems:Radiation-hardened computing subsystems demand isolation integrity specifications that justify premium component positioning. ESA and NASA qualification protocols extend design-in cycles but lock in long-term supply agreements.
- Consumer Electronics:Volume-driven personal computing and mobile devices prioritize cost-optimized CMOS implementations.
- Industrial Control:Factory automation systems require extended temperature range specifications and electromagnetic immunity.
- Instrumentation:Test and measurement equipment demands highest-precision data conversion with calibrated accuracy traceability.
Telecommunications equipment captures the largest revenue pool; aerospace systems command the steepest price premiums.
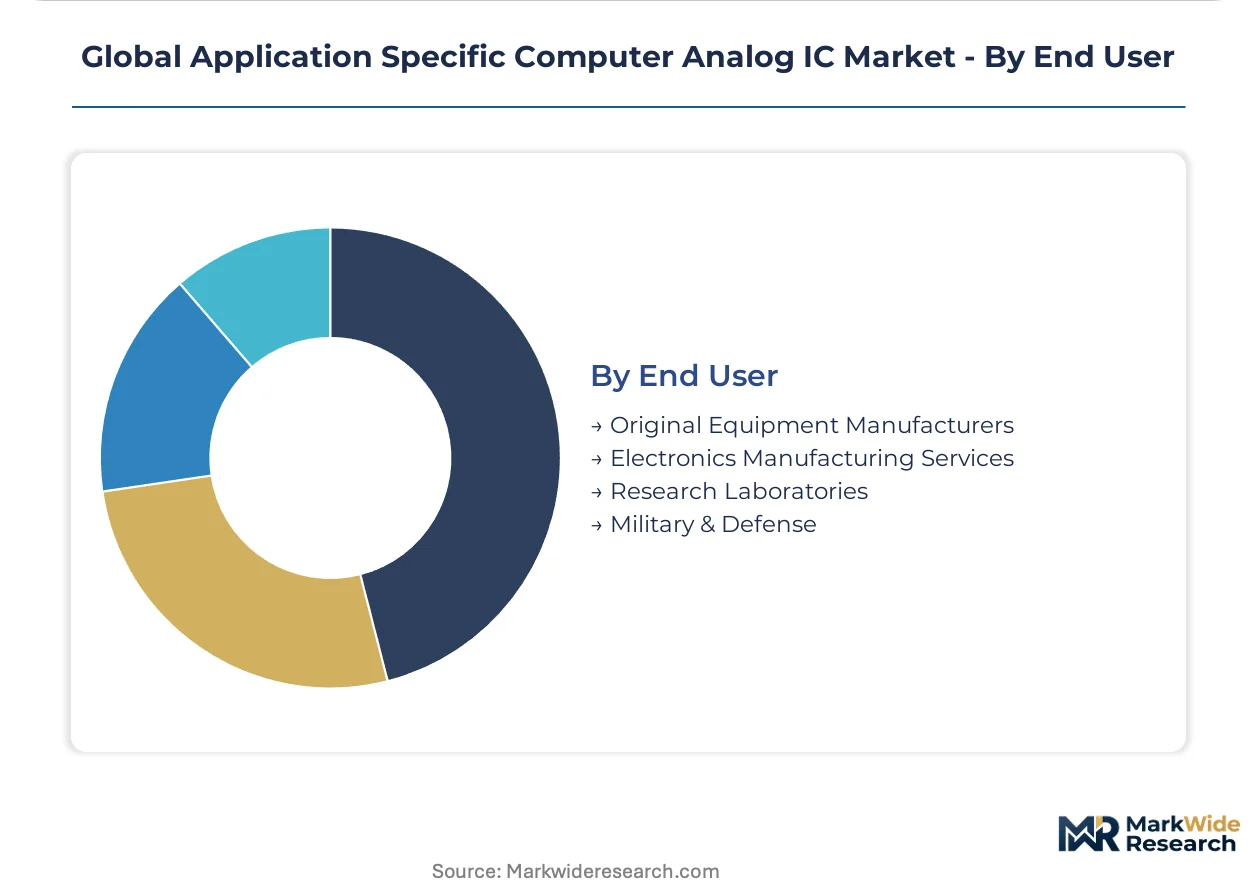
End User:
Customer type shapes procurement channel structure, with direct foundry relationships displacing traditional distribution for the largest volume consumers.
- Original Equipment Manufacturers:Server, storage, and networking hardware builders negotiate wafer-level agreements that bypass authorized distributors. Amazon Web Services and Microsoft Azure procurement teams prioritize supply security over channel rebates for standard power management SKUs.
- Electronics Manufacturing Services:Contract assemblers face margin compression from platinum group metal volatility in high-pin-count interface IC wire bonding.
- Research Laboratories:Low-volume, high-mix procurement patterns favor distribution channel access and technical support intensity.
- Military & Defense:ITAR-controlled programs require domestic sourcing certifications and extended qualification documentation.
Original equipment manufacturers dominate volume absorption; electronics manufacturing services are gaining share fastest on India PLI scheme data center buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives concentrate advanced BiCMOS foundry capacity for voltage regulator production. Domestic server buildouts in China and India redirect procurement specifications under national efficiency mandates. European F-Gas compliance curves accelerate supplier qualification cycles for data center OEMs.
United States
Hyperscale cloud infrastructure in Northern Virginia and Oregon multiplies high-speed data converter channels for AI training telemetry. EPA energy efficiency mandates for data center equipment compress voltage regulator tolerance requirements below 0.5%. Amazon Web Services and Microsoft Azure negotiate direct wafer-level procurement agreements that bypass traditional distribution channels for standard power management SKUs.
China
Domestic telecommunications equipment production scales rapidly under MIIT dual carbon goals and GB standard 40879 server energy consumption mandates. Yangtze River Delta clusters in Shanghai and Suzhou concentrate captive fab capacity for precision analog ICs serving local OEMs. Procurement specifications redirect toward lower-power architectures as state-backed data center buildouts accelerate in Guizhou and Inner Mongolia.
Germany
Frankfurt and Munich data center corridors face the steepest EU F-Gas Regulation phase-down schedules, forcing refrigerant-dependent cooling system redesigns. ECHA REACH substance restrictions on semiconductor packaging materials extend qualification timelines for analog IC shipments. Bavarian server manufacturers specify extended temperature range ICs calibrated for liquid cooling architectures.
Japan
Tokyo-Osaka industrial corridors anchor deep integration between analog IC suppliers and domestic telecommunications equipment makers. METI procurement policies favor precision voltage references for baseband processing and optical line termination units. Renesas Electronics maintains captive relationships with NTT and KDDI infrastructure divisions.
India
Maharashtra and Karnataka data center buildouts under PLI scheme incentives create demand for locally qualified voltage regulators and power management ICs. CEA grid reliability standards elevate specifications for power conversion efficiency in domestic server production. Mumbai and Bengaluru electronics manufacturing services clusters gain share fastest on hyperscale operator procurement localization.
Global Application Specific Computer Analog IC Market Competitive Landscape
United States producers anchor one tier; Japanese specialists hold integrated positions with domestic telecommunications OEMs. The vendor base concentrates among captive fab operators for voltage regulation and data conversion functions, while signal conditioning sourcing remains more fragmented. Three archetypes dominate: diversified analog conglomerates with foundry networks, precision specialists serving aerospace radiation-hardness requirements, and fabless designers outsourcing to Taiwan-based BiCMOS capacity. Competitive moves center on backward integration into wafer supply and geographic expansion through India PLI scheme localization.
Among diversified analog conglomerates, Texas Instruments and Analog Devices exemplify the captive fab archetype sustaining margin structures under tightening environmental compliance. STMicroelectronics occupies a position bridging European automotive and computing analog requirements. ON Semiconductor sits within the power management specialization tier where silicon carbide-adjacent thermal performance standards are escalating. These three companies represent distinct strategic postures without implying specific market share claims or operational details beyond their visible corporate structures.
| Leading Market Players |
|---|
| STMicroelectronics |
| Renesas Electronics |
| Texas Instruments |
| Microchip Technology |
| ON Semiconductor |
| Analog Devices |
| NXP Semiconductors |
| Skyworks Solutions |
| Infineon Technologies |
| Others |
Supply & Pricing Matrix
Mixed-signal design talent scarcity in Hsinchu and Bangalore feeds labor-cost differentials that widen pricing-tier spreads between captive-fab precision suppliers and fabless competitors. Taiwan-based BiCMOS foundry premiums compress margins for voltage regulator producers while SOI radiation-hardened specialists command 40-60% cost premiums over bulk CMOS alternatives.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with hyperscale operators paying premiums for sub-12-week delivery while spot inventory discounts attract electronics manufacturing services with flexible demand profiles. Three-tier pricing structure across radiation-hardened aerospace, industrial-grade telecommunications, and cost-optimized consumer electronics segments separates qualification-intensive applications from commodity volumes. Cost compression in standard voltage regulators intensifies because platinum group metal volatility in wire bonding chemistries erodes gross margins on high-pin-count interface ICs. Electronics manufacturing services exhibit highest price sensitivity due to PLI scheme margin constraints, while aerospace OEMs demonstrate lowest sensitivity given ESA and NASA qualification lock-in effects.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators and defense primes mandate multi-supplier qualification for BiCMOS voltage regulators across Taiwan, Japan, and domestic China foundries. Raw material dependencies center on silicon wafers, platinum group metals for wire bonding, and specialized ceramic packaging substrates. Single-source vulnerability concentrates in Taiwan's 300mm BiCMOS capacity for precision regulator production. Distribution runs through direct wafer-level agreements for original equipment manufacturers, with authorized distributors serving research laboratories and low-volume military programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for advanced BiCMOS processes prop pricing power for captive-fab operators, creating a supply-constrained market structure favoring backward-integrated incumbents.
For Market Incumbents: Anchor competitive position through captive fab network expansion in India under PLI scheme incentives, defending against optical interconnect substitution in AI accelerator memory interfaces. Prioritize ECHA REACH compliance investment to capture European data center OEM qualification cycles accelerated by F-Gas Regulation phase-down schedules. Deepen upstream control over platinum group metal supply through long-term offtake agreements with wire bonding chemistry suppliers. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for liquid-cooling-optimized temperature sensor specialists targeting Bavarian server manufacturers. India's PLI scheme data center buildout presents the most penetrable geography for locally qualified power management IC suppliers. Pursue CEA grid reliability certification as a go-to-market angle for Maharashtra and Karnataka electronics manufacturing services clusters. For Investors and Strategic Acquirers: Re-rating potential sits with SOI-based radiation-hardened specialists given SpaceX and OneWeb constellation telemetry demand acceleration. Long-term viability favors acquisition targets with dual-use aerospace-telecommunications qualification capabilities spanning ESA, NASA, and MIIT certification frameworks. Monitor BiCMOS foundry utilization rates as the inflection indicator for pricing power shifts across voltage regulator supply.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fab Expansion | TI and Analog Devices sustain margin structures under tightening EU REACH compliance requirements. |
| SOI Process Qualification | SpaceX and OneWeb constellation suppliers drive 40-60% cost premiums for radiation-hardened voltage regulators. |
| India PLI Localization | Maharashtra and Karnataka data center buildouts create demand for CEA-certified power management ICs. |
| Direct Wafer Procurement | Amazon Web Services and Microsoft Azure bypass distributors for supply security in standard voltage regulator SKUs. |
| REACH Compliance Investment | German and French server manufacturers accelerate supplier qualification cycles under ECHA substance restrictions. |
Research Methodology
Independent corroboration across analog IC design engineers, hyperscale procurement officers, and foundry operations managers underwrites the qualitative findings in this study. Primary interviews with semiconductor packaging material suppliers, ESA qualification specialists, and India PLI scheme administrators combined with secondary validation from SEC 10-K filings, MIIT GB standard documentation, and ECHA REACH substance restriction databases. Bottom-up demand modeling from voltage regulator and data converter shipment data triangulates against top-down market sizing from foundry capacity disclosures.
Rate-of-change decomposition across product type, technology node, application segment, and end-user procurement channel structures the analytical framework throughout the projection horizon. Segmentation dimensions include voltage regulator precision tiers, SOI versus BiCMOS process selection, telecommunications versus aerospace application requirements, and OEM direct versus distribution channel procurement patterns. CAGRs derive from shipment volume trajectories adjusted for content-per-server growth in AI training clusters and MIIT dual carbon procurement mandate penetration curves.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide-adjacent power management architectures would alter the outlook for analog signal conditioner demand. Forecasts reflect assumptions regarding Taiwan foundry capacity expansion timelines, platinum group metal price stability, and EU F-Gas Regulation enforcement consistency. Deviation in hyperscale operator direct procurement penetration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Standard Logic IC Market