
 Global Polyether Ether Ketone (PEEK) Market | 2026-2036
Global Polyether Ether Ketone (PEEK) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyether Ether Ketone (PEEK) Market Foresight
Metal-to-polymer substitution in aerospace engine architectures is fragmenting traditional supply relationships across the PEEK value chain. Victrex plc dominates high-purity medical resin certification through backward integration into polymerization assets. Evonik Industries AG differentiates via specialty compounding for semiconductor wafer handling applications. Jilin Joinature Polymer Co., Ltd. leverages cost-optimized powder production to anchor pricing pressure in Asian industrial markets.
Polyether ether ketone is a semi-crystalline aromatic thermoplastic with a melting point near 343°C, synthesized through nucleophilic substitution of hydroquinone with 4,4'-difluorobenzophenone in diphenyl sulfone. Its primary industrial purpose centers on replacing metals in load-bearing components that must survive aggressive chemicals, repeated sterilization cycles, or sustained temperatures above 250°C. Carbon-filled PEEK commands the strongest margin pool where stiffness-to-weight ratios determine aerospace fastener and bearing selection. Healthcare applications in spinal implants and dental abutments represent the fastest-expanding end-use channel as OEMs seek radiolucent alternatives to titanium. Natural PEEK retains volume leadership in general industrial sealing and compression molding despite slower value growth.
FDA material master files and EU MDR biocompatibility requirements are elevating entry barriers for medical-grade PEEK resin producers seeking hospital procurement approval. REACH substance registration and RoHS restricted substance limits constrain additive packages and flame-retardant formulations sold into European electronics and automotive channels. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance scrutiny, as process chemistry disclosures could reshape cost structures for fluorinated monomer routes.
Market Dynamics
Metal-to-polymer substitution in aerospace engine architectures is fragmenting traditional supply relationships across the PEEK value chain, while REACH and FDA purity benchmarks are bifurcating resin grades into certified and uncertified tiers.
Growth Catalysts
- FAA airworthiness directives on fuel efficiency:Aerospace OEMs in the United States are substituting titanium fasteners with carbon-filled PEEK to reduce engine weight. This substitution is accelerating qualification timelines for structural brackets and compressor components.
- EU MDR biocompatibility pathways:Medical device manufacturers across Germany, France, and Switzerland are securing radiolucent spinal implant approvals. The regulation is channeling resin demand toward EMA-notified body certification holders.
- Fluorinated monomer process optimization:Diphenyl sulfone synthesis routes are achieving higher molecular weight consistency. This technical advance is expanding film and membrane applications in semiconductor wafer handling.
Market Restraints
- Hydroquinone feedstock volatility:Aromatic diol prices fluctuate with benzene derivative markets. Producers in Asia face margin compression when crude-linked naphtha costs spike.
- Medical-grade polymerization asset concentration:High-purity resin synthesis capacity clusters in the United Kingdom and Germany. Buyers in Japan and South Korea face extended lead times and freight cost premiums.
- PEEK-to-PEI substitution in electronics:Polyetherimide offers comparable heat resistance at lower cost for non-structural connectors. Consumer electronics OEMs are qualifying PEI for housings below 200°C continuous service.
Strategic Opportunities
- Indian medical device manufacturing corridors:CDSCO is harmonizing with ISO 10993 biocompatibility standards. Domestic PEEK implant production can bypass import duties and 90-day customs clearance delays.
- PEEK-carbon fiber thermoplastic composites:Automated fiber placement with in-situ consolidation is enabling aerospace wing rib production. This process convergence targets 40% cycle time reduction versus thermoset autoclave methods.
- Japan METI carbon neutrality incentives:Lightweight polymer substitution in automotive powertrains qualifies for green innovation funding. Hybrid vehicle transmission components represent a high-volume entry point.
Industry Challenges
- Polymerization technician scarcity:Nucleophilic substitution chemistry expertise concentrates among aging workforces in European specialty chemical clusters. Training programs for high-temperature reactor operation lag retirement curves.
- FDA master file amendment timelines:Medical-grade resin modifications require 18-24 month supplemental review cycles. Formulation adjustments for colorant or radiopaque additive packages delay hospital procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyether Ether Ketone (PEEK) Market |
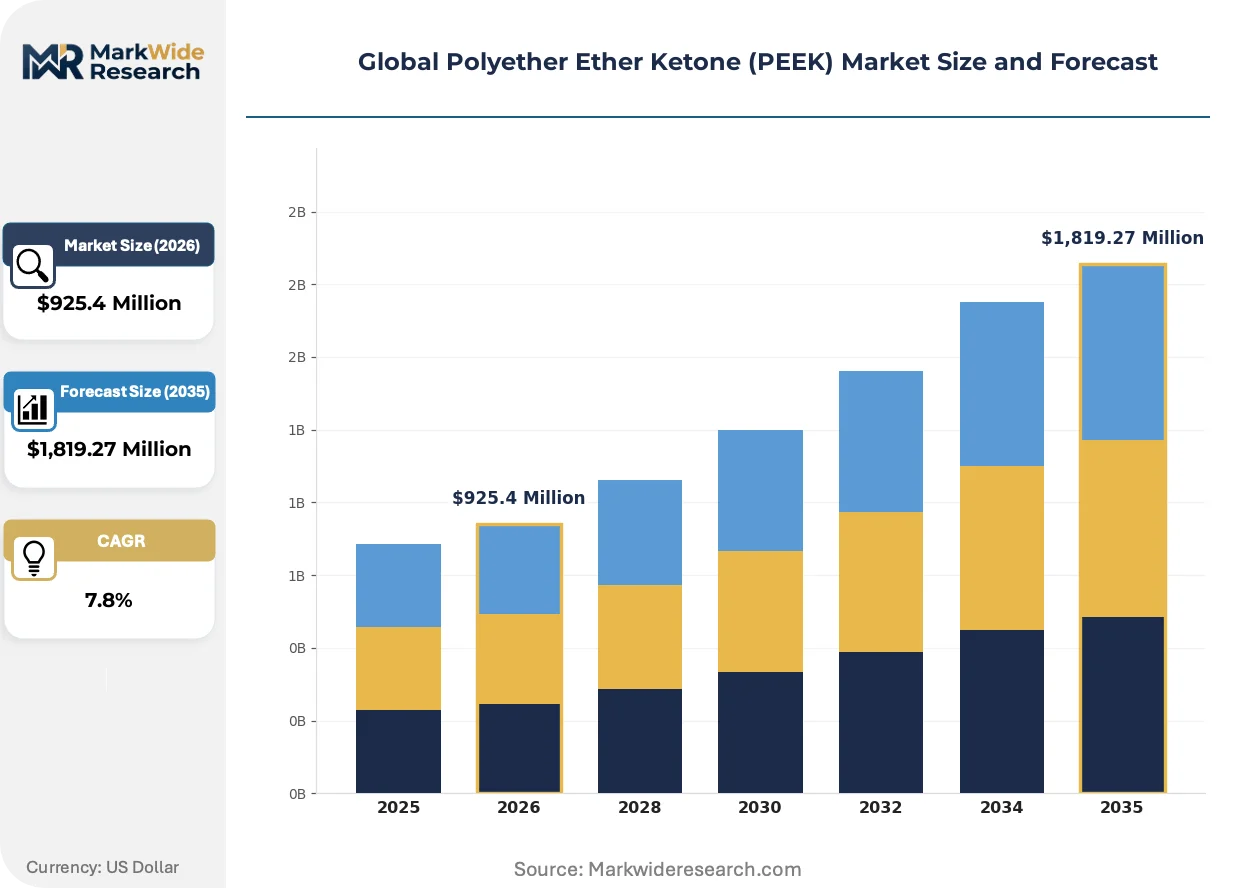
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,819.27 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural PEEK, Glass-Filled PEEK, Carbon-Filled PEEK, Flame-Retardant PEEK End Use Industry: Aerospace, Automotive, Electronics, Healthcare Form: Powder, Rods, Sheets, Films Application: Sealants, Gaskets, Insulators, Components |
| Companies Covered | Jilin Joinature Polymer Co., Ltd., Panjin Zhongrun High Performance Polymers Co., Ltd., Victrex plc, Ensinger GmbH, DuPont, Syensqo, JUNHUA, ZYPEEK, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyether Ether Ketone (PEEK) Market Shifts & Advancements
Process analytical technology and regulatory data integrity requirements are reshaping how PEEK producers validate batch consistency and secure multi-jurisdictional market access.
Continuous flow reactor systems for nucleophilic aromatic substitution are digitizing quality assurance protocols. Victrex and Evonik are deploying in-line spectroscopic monitoring at 343°C melt temperatures. This real-time viscosity tracking is digitizing certificate-of-analysis generation and compressing pharmaceutical customer audit cycles from weeks to days.
REACH substance registration deadlines for polymerization catalyst residues are tightening purity disclosure thresholds. ECHA's 2024 update to Annex XVII restricted substances is forcing reformulation of certain phosphite stabilizer packages. Medical-grade resin producers serving European hospitals are responding by qualifying alternative antioxidant systems through ISO 10993 cytotoxicity panels.
Hospital procurement consortiums in Germany and Switzerland are consolidating spine implant supplier panels around dual-source resin strategies. Device OEMs must now demonstrate qualified secondary polymer sources to maintain GPO contract eligibility. This buyer concentration is most visible in Stuttgart-area precision molding clusters, where mid-tier processors face exclusion without FDA-plus-MDR dual filings.
Global Polyether Ether Ketone (PEEK) Market Segmentation
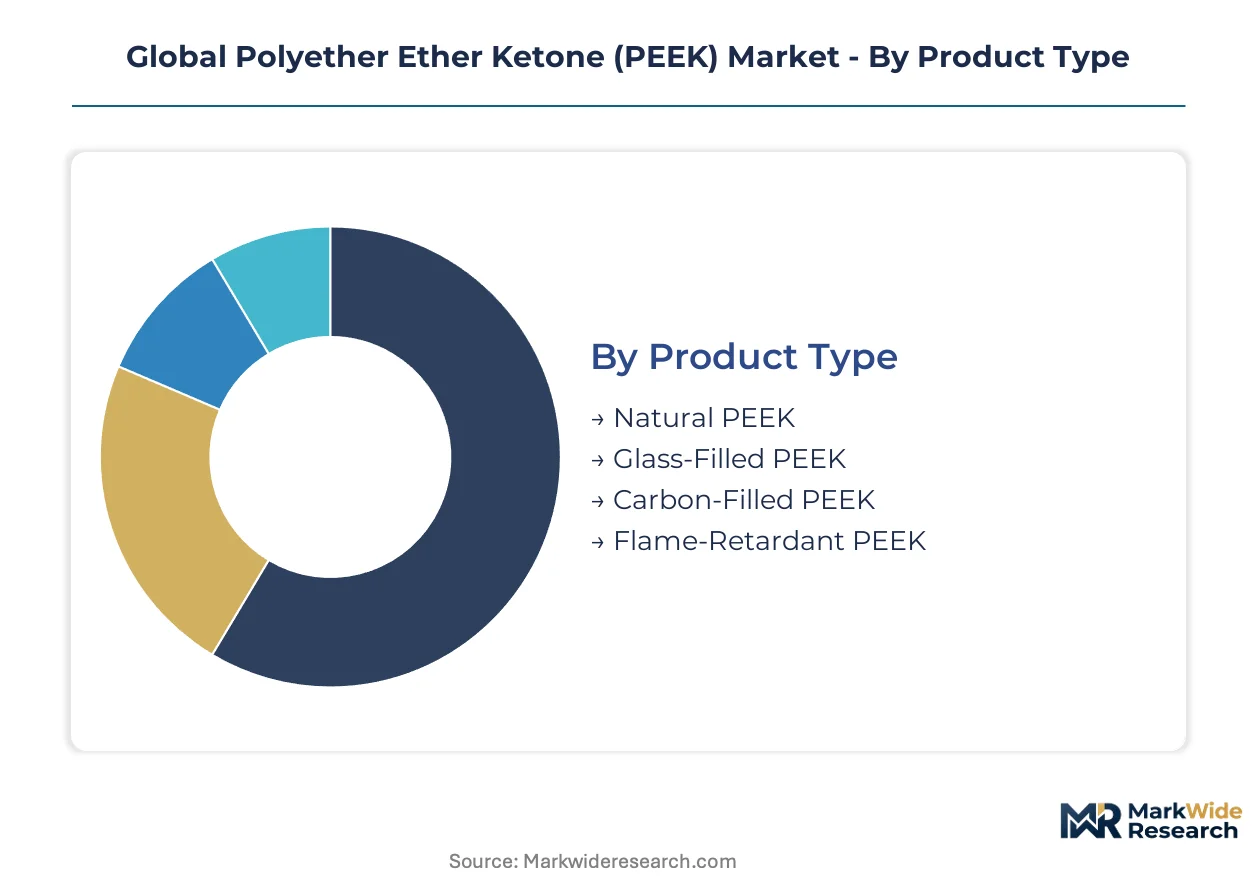
PEEK procurement patterns diverge sharply across product grades and end-use channels, with aerospace and medical buyers demanding certified resin batches while industrial purchasers prioritize cost-optimized powder forms. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
After-sales service intensity escalates with filler complexity, as carbon-filled and medical-grade natural batches require technical support for processing parameter optimization and regulatory documentation retrieval.
- Natural PEEK:Unfilled resin maintains broadest process latitude for injection molders and extrusion houses. General industrial sealing applications in Germany's automotive supply base absorb the largest tonnage, though price competition from Asian powder imports compresses per-kilogram margins.
- Carbon-Filled PEEK:30% carbon fiber loading delivers specific stiffness rivaling aluminum at half the density. Aerospace fastener manufacturers in the United States and France specify this grade for engine bracket qualification programs where FAA airworthiness documentation requires batch traceability.
- Glass-Filled PEEK:E-glass reinforcement improves dimensional stability for electrical connector housings. Automotive under-hood applications in Stuttgart-area OEM supply chains favor this intermediate cost-performance tier.
- Flame-Retardant PEEK:Phosphorus-based additive packages meet UL 94 V-0 ratings for mass transit interior components. REACH Annex XVII restrictions on halogenated systems are forcing reformulation of legacy stabilizer chemistries.
By volume, natural PEEK leads. By growth pace, carbon-filled grades are expanding most quickly.
End Use Industry:
Cost tier stratification separates aerospace and healthcare buyers willing to pay certification premiums from automotive and electronics purchasers optimizing per-part economics.
- Aerospace:Engine manufacturers specify carbon-filled grades for compressor stators and structural brackets. FAA fuel efficiency directives are accelerating metal-to-polymer substitution timelines for narrow-body platform retrofits.
- Healthcare:Spinal implant OEMs require FDA master file resin with ISO 10993 cytotoxicity clearance. EU MDR biocompatibility pathways are channeling demand toward EMA-notified body certification holders in Germany and Switzerland.
- Automotive:Transmission component molders leverage natural PEEK for thrust washers and seal rings. Japan METI carbon neutrality incentives qualify lightweight polymer powertrain parts for green innovation funding.
- Electronics:Wafer handling equipment manufacturers specify ultra-high-purity grades for semiconductor fabrication. PEI substitution threatens non-structural connector applications below 200°C continuous service temperatures.
Healthcare applications command the steepest price premiums. Aerospace volumes are climbing the fastest.
Form:
Geographic supply concentration shapes form availability, with European producers dominating high-value rod and sheet extrusion while Asian capacity clusters on powder production.
- Powder:Fine-ground resin serves compression molders and coating applicators. Jilin Joinature and Chinese competitors anchor pricing pressure in Asian industrial markets through cost-optimized nucleophilic substitution routes.
- Rods:Continuous extruded stock enables precision machining of bearing cages and pump bushings. German compounders around Frankfurt maintain tight diameter tolerances for hydraulic system OEMs.
- Sheets:Press-rolled plate stock supports thermoformed aerospace ducting and chemical tank linings. Thickness consistency requirements favor established European extrusion houses with in-line gauging systems.
- Films:Biaxially oriented webs target capacitor dielectrics and speaker membranes. Semiconductor wafer handling applications demand sub-micron thickness control achievable through diphenyl sulfone solvent casting.
Powder dominates tonnage shipments. Film applications are gaining share fastest on semiconductor capital equipment demand.
Application:
Customer type segmentation separates specification-driven OEM component buyers from maintenance-repair-operations purchasers of standardized seal geometries.
- Components:Load-bearing brackets and structural fasteners require lot-specific mechanical property certificates. Aerospace OEMs in France and the United States mandate full material pedigree documentation.
- Sealants:O-ring and gasket fabricators prioritize chemical resistance over mechanical strength. Oil and gas field service companies in the North Sea specify natural PEEK for downhole packer elements.
- Gaskets:Sheet stock die-cutting serves flange sealing in chemical process equipment. Pharmaceutical manufacturing facilities require FDA-compliant resin grades with extractables testing.
- Insulators:Electrical isolation components in high-temperature connectors specify glass-filled grades. Automotive wire harness producers in Japan qualify materials for hybrid vehicle inverter housings.
Components capture the highest value per kilogram. Sealant applications maintain the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade resin certification and aerospace qualification programs concentrate procurement decisions among buyers in Germany, the United States, Japan, and China. These four countries host the dominant polymerization assets, compounding facilities, and end-use manufacturing clusters that shape global PEEK trade flows.
Germany
EMA-notified body certification holders in Stuttgart and Frankfurt supply spinal implant manufacturers with EU MDR-compliant resin. REACH Annex XVII restrictions on phosphite stabilizers are forcing reformulation of legacy additive packages. The Stuttgart-area precision molding cluster concentrates Europe's highest-volume medical device production.
United States
FAA airworthiness directives on fuel efficiency accelerate carbon-filled PEEK qualification for engine brackets and compressor stators. FDA master file resin producers serve hospital procurement consortiums demanding dual-source supply strategies. Aerospace OEMs in the Pacific Northwest and Southeast specify lot-specific mechanical property certificates.
Japan
METI carbon neutrality incentives qualify lightweight polymer powertrain components for green innovation funding. Hybrid vehicle transmission manufacturers in the Nagoya and Tokyo corridors specify natural PEEK for thrust washers. Domestic semiconductor wafer handling equipment producers demand ultra-high-purity grades with sub-micron film capability.
China
Cost-optimized powder production in Jilin Province anchors pricing pressure across Asian industrial markets. MIIT industrial upgrading policies encourage domestic substitution for imported medical-grade resin. Yangtze River Delta molders consume the region's largest tonnage for general industrial sealing applications.
United Kingdom
High-purity polymerization expertise concentrates among aging workforces in specialty chemical clusters. The country's national pharmaceutical regulator maintains alignment with FDA material master file standards. Backward-integrated producers control captive supply of fluorinated monomer routes for nucleophilic substitution chemistry.
Global Polyether Ether Ketone (PEEK) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across certification tiers. The market structure consolidates around three to five vertically integrated resin producers while fragmenting among downstream compounders and precision molders. Two strategic archetypes dominate: backward-integrated polymerization asset owners and specialty compounding houses. Capacity expansion and regulatory certification acceleration represent the dominant competitive moves.
Among UK-based polymerization specialists, Victrex plc occupies a position exemplifying high-purity medical resin certification through in-house production of polymerization assets. German compounders including Ensinger GmbH and Evonik Industries AG represent the specialty formulation archetype, serving semiconductor and aerospace channels with differentiated additive packages. Chinese powder producers such as Jilin Joinature Polymer Co., Ltd. anchor the cost-optimized industrial tier.
| Leading Market Players |
|---|
| Jilin Joinature Polymer Co., Ltd. |
| Panjin Zhongrun High Performance Polymers Co., Ltd. |
| Victrex plc |
| Ensinger GmbH |
| DuPont |
| Syensqo |
| JUNHUA |
| ZYPEEK |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Hydroquinone feedstock volatility tied to benzene derivative markets determines both the spread between medical-grade and industrial-grade resin pricing and the geographic clustering of polymerization assets. Buyers in Japan and South Korea absorb freight cost premiums when sourcing from United Kingdom and German high-purity synthesis capacity, while Asian powder producers exploit cost-optimized nucleophilic substitution routes to compress industrial-tier margins.
Pricing Analysis
Cost-plus contracts with hydroquinone and 4,4'-difluorobenzophenone indexation dominate long-term aerospace and medical supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA master file resin with ISO 10993 clearance from general industrial powder grades. Cost compression in natural PEEK powder is intensifying because Jilin Joinature and Chinese competitors scale cost-optimized production. Automotive transmission component molders exhibit highest price sensitivity; spinal implant OEMs purchasing certified medical resin demonstrate lowest sensitivity due to regulatory lock-in.
Supply Chain Analysis
Contract manufacturing concentration for high-purity polymerization rests with Victrex plc in the United Kingdom and Evonik Industries AG in Germany, while compounding and extrusion capacity clusters around Frankfurt and Stuttgart. Raw material dependencies draw from hydroquinone aromatic diol suppliers, fluorinated monomer producers, and diphenyl sulfone solvent manufacturers. Single-source vulnerability concentrates in medical-grade resin synthesis assets, where EMA-notified body certification and FDA master file status create switching barriers. Distribution runs through direct mill relationships for aerospace OEMs, regional distributors for industrial sealant fabricators, and hospital procurement consortiums for medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PEEK market functions as a defensive-moat story where regulatory entrenchment in FDA master file and EU MDR certification pathways creates durable switching costs for incumbent resin producers.
For Market Incumbents: Pre-empt PEI substitution in electronics connectors by qualifying glass-filled grades for 200°C-plus continuous service applications. Secure secondary polymer sources for German hospital procurement consortiums demanding dual-source strategies, while accelerating EMA-notified body certification for alternative antioxidant systems ahead of REACH Annex XVII phosphite stabilizer restrictions. For New Entrants and Emerging Players: Pursue CDSCO harmonization with ISO 10993 standards to establish domestic PEEK implant production in Indian medical device manufacturing corridors, bypassing import duties and customs clearance delays. Target semiconductor wafer handling equipment channels in Japan where ultra-high-purity film demand outpaces domestic supply, leveraging automated fiber placement process partnerships as entry credential. For Investors and Strategic Acquirers: EU MDR biocompatibility pathway acceleration reshapes the acquisition landscape toward EMA-notified body certification holders with existing hospital GPO contracts. Over the projection horizon, prioritize backward-integrated polymerization asset owners over pure-play compounders. Monitor FDA master file amendment timeline compression as inflection signal for medical-grade resin margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Monomer Production | Victrex plc's captive supply of 4,4'-difluorobenzophenone secures cost visibility against benzene derivative volatility. |
| EMA-Notified Body Certification Acceleration | Ensinger GmbH's EU MDR pathway expansion captures Stuttgart-area spinal implant OEM panel consolidation. |
| Automated Fiber Placement Process Convergence | PEEK-carbon fiber thermoplastic composite qualification targets 40% cycle time reduction versus thermoset autoclave methods. |
| Continuous Flow Reactor Digitization | In-line spectroscopic monitoring at 343°C melt temperatures compresses pharmaceutical customer audit cycles from weeks to days. |
| Indian Domestic Manufacturing Corridor Entry | CDSCO harmonization enables bypass of 90-day customs clearance delays for implant resin imports. |
Research Methodology
Operator-level perspectives from polymerization plant managers, aerospace OEM procurement leads, spinal implant regulatory affairs directors, and hospital GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA material master file databases, EMA notified body certification registries, SEC 10-K filings of listed resin producers, and customs trade data for hydroquinone and fluorinated monomer flows. Bottom-up segment sizing triangulated against top-down industry association tonnage estimates from specialty chemical federations.
Scenario-bracketing around hydroquinone price volatility bands and REACH regulatory amendment timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating aerospace metal-to-polymer substitution rates and healthcare radiolucent implant adoption curves.
Macroeconomic conditions sit as an overlay; deviation in crude-linked naphtha costs, benzene derivative pricing, or central bank rate cycles would shift the trajectory. Forecasts reflect documented assumptions regarding EMA MDR implementation pace and FAA airworthiness directive enforcement. Quarterly review of hydroquinone futures curves, FDA master file submission backlogs, and Asian powder import duty adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Plastisols Market
Polymers & Resins
North America and Europe Phenolic Resin Market