
 Modified Alkyd Resin Market | 2026-2036
Modified Alkyd Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Alkyd Resin Market Outlook
Waterborne alkyd technology is tilting coating formulation away from conventional solvent-heavy systems toward lower-VOC architectures. BASF SE leverages its integrated resin-pigment position to supply modified alkyd precursors directly into European automotive coating lines. Dow anchors North American supply through its epoxy-alkyd hybrid programs for protective industrial finishes. Mitsui Chemicals specializes in high-solids modified alkyds serving Japanese electronics and precision equipment manufacturers.
Modified alkyd resin denotes a polyester-based binder synthesized from polyols, polybasic acids, and fatty acid-modified components, subsequently engineered with vinyl, silicone, or phenolic grafts to enhance weatherability, drying speed, or chemical resistance; these resins function primarily as film-forming vehicles in protective and decorative coatings. Water-based formulations now lead product type demand as regulatory pressure on solvent emissions intensifies, while solvent-based grades retain margin pools in marine and heavy-industrial segments where performance specifications remain stringent. Industrial coatings and automotive applications represent the fastest-growing end-use channels, driven by OEM specification shifts and refinishing volume recovery.
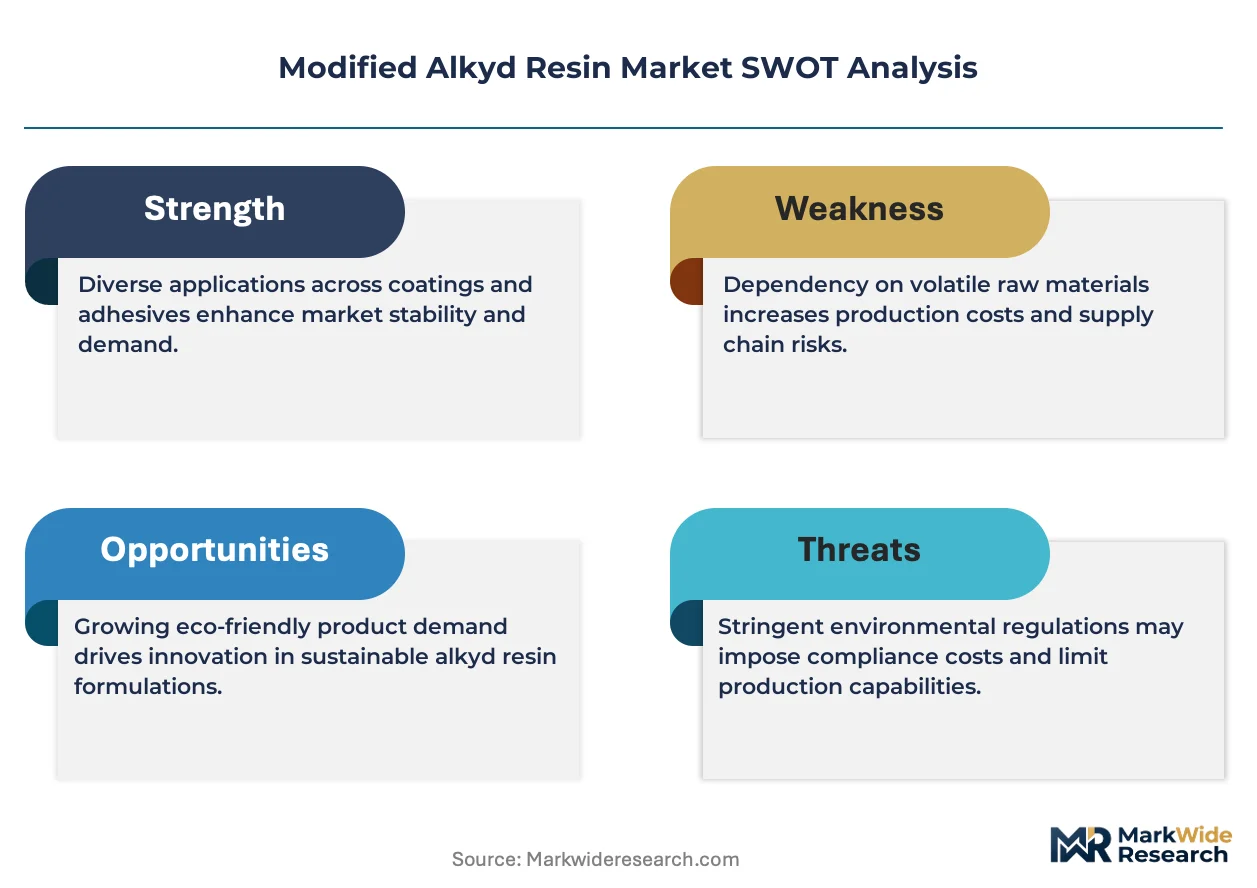
EPA VOC regulations and REACH substance restrictions shape permissible solvent content and hazard classification across major demand centers, directly influencing reformulation investment cycles. ECHA evaluations on dibutyltin catalyst residues and FDA indirect food-contact coatings standards further constrain additive selection and crosslinker chemistry for packaging and specialty applications. Stakeholders must monitor evolving bio-based feedstock certification schemes and regional carbon border adjustments to secure long-term formulation competitiveness.
Market Dynamics
REACH substance restrictions and EPA VOC regulations are forcing simultaneous reformulation of solvent-based coating systems across multiple industrial end-uses. Waterborne alkyd technology is compressing the performance gap with conventional solvent architectures while bio-based feedstock certification schemes add new compliance layers to raw material sourcing.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:REACH Phase 2 restrictions on volatile organic compounds in decorative coatings are accelerating water-based modified alkyd adoption in German and French architectural applications.
- Automotive refinishing volume recovery:Collision repair shops and OEM touch-up operations are specifying low-VOC alkyd systems to meet EPA NESHAP compliance deadlines without sacrificing drying speed.
- Silicone grafting technology maturation:Enhanced weatherability from phenolic and silicone modifications is opening specification windows in exterior coil coatings and infrastructure protection.
Market Restraints
- Tall oil fatty acid supply concentration:Nordic pulp-byproduct availability constrains bio-based alkyd feedstock scaling outside Scandinavian production clusters.
- Waterborne drying kinetic limitations:Humidity-sensitive cure profiles restrict water-based modified alkyd deployment in high-throughput industrial bake lines where solvent systems retain cycle-time advantages.
- Epoxy-urethane hybrid substitution pressure:Two-component polyurethane systems are capturing specification share in chemical-resistant industrial maintenance coatings.
Strategic Opportunities
- Indian protective coatings underpenetration:Infrastructure investment under the PLI scheme for specialty chemicals is creating formulation partnerships between European resin suppliers and domestic Indian coating manufacturers.
- Food-contact packaging certification gap:FDA indirect food-contact compliance for modified alkyd can coatings remains limited to a narrow supplier base, creating first-mover margin pools.
- Silicone-alkyd UV-curable convergence:Electron-beam and UV-initiated cure mechanisms are hybridizing with alkyd backbones to enable energy-efficient wood furniture finishing.
Industry Challenges
- Formulation chemist specialization shortage:Expertise in waterborne alkyd colloidal stability and surfactant selection is concentrating among aging technical workforces in Ludwigshafen and Leverkusen industrial clusters.
- Crosslinker requalification timelines:ECHA evaluations on dibutyltin catalyst residues are forcing 18-24 month reformulation cycles for marine and protective coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Alkyd Resin Market |
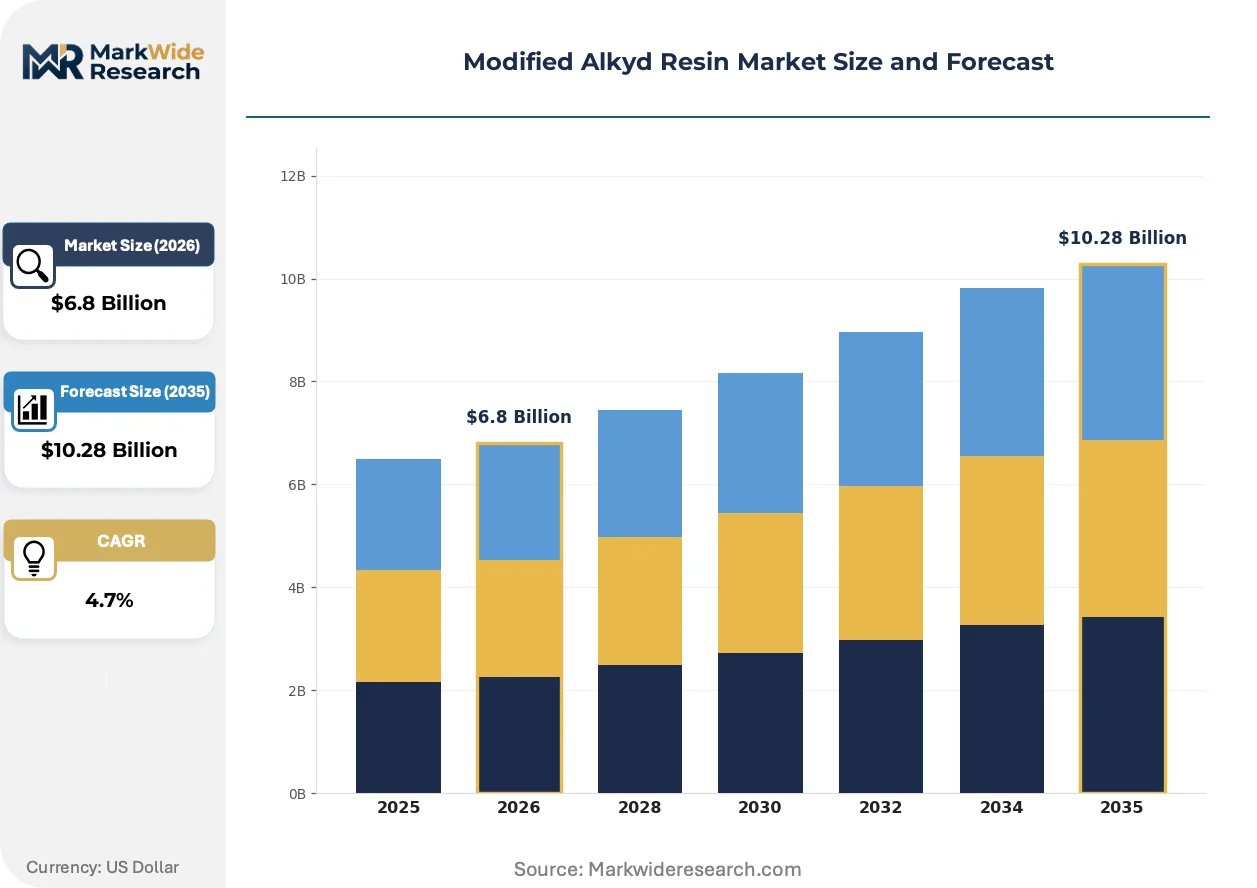
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, High Solids, Crosslinking End Use Industry: Decorative Coatings, Industrial Coatings, Wood Coatings, Marine Coatings Application: Automotive, Furniture, Construction, Electronics Formulation Type: Bulk, Powder, Granular, Liquid |
| Companies Covered | Wacker Chemie AG, Mitsui Chemicals, BASF SE, Arakawa Chemical Industries, MACRO POLYMERS, Dow, PPG Industries, Eternal Materials Co., Ltd., Polynt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Alkyd Resin Market Strategic Shifts
Coating chemistry is converging on hybrid architectures that merge alkyd film-forming characteristics with specialty performance grafts. Three developmental trajectories are compressing traditional formulation boundaries while regulatory pressure accelerates commercialization timelines.
Waterborne alkyd-polyurethane hybrid dispersions are hybridizing the segment boundary between decorative and industrial coating categories. Japanese electronics manufacturers are specifying these systems for precision equipment housings where humidity resistance and aesthetic finish must coexist. The technology is compressing the addressable market for pure acrylic dispersions in light-duty industrial applications.
EPA NESHAP amendments for surface coating operations are mandating HAP content reductions in automotive and aerospace finishing lines. Industrial coating applicators in Michigan and Ohio are retrofitting spray booths to accommodate higher-solids alkyd formulations that maintain transfer efficiency. The regulation is compressing solvent-based alkyd margins in transportation OEM specifications while expanding waterborne qualified supplier lists.
Coating procurement through integrated resin-pigment supply contracts is consolidating specification authority among large automotive OEMs. Tier-1 suppliers in Germany are negotiating direct alkyd precursor supply agreements that bypass traditional distributor channels. The pattern is most visible in Stuttgart and Munich manufacturing corridors where just-in-time coating delivery aligns with assembly line sequencing requirements.
Modified Alkyd Resin Market Segmentation
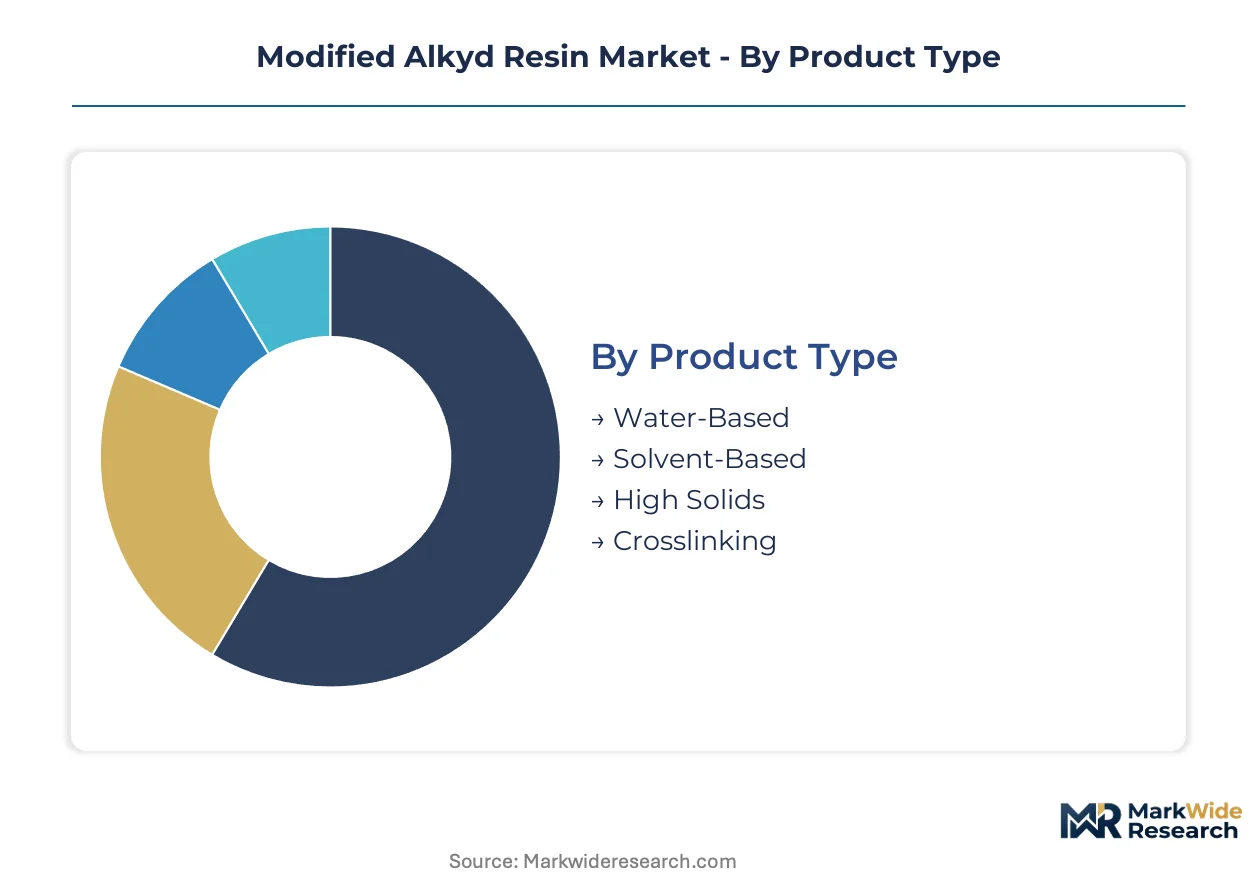
Modified alkyd resin formulation strategies diverge sharply across end-use specifications, with regulatory pressure and performance requirements dictating technology selection. Segment boundaries are blurring as hybrid systems capture specification share formerly held by pure resin categories.
Product Type:
Cost tier determines raw material sourcing flexibility and capital intensity for resin manufacturing operations.
- Water-Based:Polyurethane-alkyd hybrid dispersions dominate architectural specifications where EPA VOC limits and EU REACH Phase 2 restrictions mandate emission reductions. German coating applicators in Stuttgart industrial corridors are retrofitting lines to accommodate these slower-cure systems despite humidity sensitivity.
- Solvent-Based:Conventional mineral spirit-cut alkyds retain margin pools in marine and heavy-industrial segments where bake-line throughput requirements exceed waterborne drying kinetics. Japanese shipyards and Nordic offshore infrastructure projects specify these systems for chemical resistance and film build.
- High Solids:Reduced solvent content alkyds serve automotive refinishing operations balancing transfer efficiency with EPA NESHAP compliance.
- Crosslinking:Phenolic and silicone graft architectures enable exterior coil coating durability for infrastructure protection.
Water-Based holds installed capacity. High Solids is rotating up the share rankings.
End Use Industry:
Application maturity separates established decorative markets from specification-driven industrial channels.
- Industrial Coatings:Protective maintenance specifications for chemical plants and power generation infrastructure demand silicone-modified alkyds with enhanced weatherability. Indian infrastructure investment under PLI scheme incentives is creating formulation partnerships between European resin suppliers and domestic manufacturers.
- Decorative Coatings:Architectural interior and exterior wall finishes represent volume concentration in European coating clusters around Ludwigshafen and Leverkusen.
- Wood Coatings:Furniture and flooring applications specify UV-curable alkyd hybrids for energy-efficient finishing lines.
- Marine Coatings:ECHA evaluations on dibutyltin catalyst residues are forcing extended requalification timelines for antifouling and protective systems.
Decorative Coatings holds installed capacity. Industrial Coatings is rotating up the share rankings.
Application:
Customer type differentiation separates OEM specification authority from aftermarket procurement patterns.
- Automotive:Collision repair shops and OEM touch-up operations specify low-VOC alkyd systems to meet compliance deadlines without sacrificing drying speed. Tier-1 suppliers negotiate direct precursor supply agreements bypassing traditional distributor channels.
- Construction:Infrastructure and architectural applications concentrate demand in German industrial coating clusters.
- Furniture:Electron-beam and UV-initiated cure mechanisms are hybridizing with alkyd backbones for energy-efficient wood finishing.
- Electronics:Japanese precision equipment manufacturers specify humidity-resistant finishes where aesthetic and protective requirements coexist.
Construction holds installed capacity. Automotive is rotating up the share rankings.
Formulation Type:
Supply concentration shapes logistics economics and customer handling requirements.
- Liquid:Standard drum and tote delivery dominates coating manufacturer procurement for immediate processing.
- Powder:Solid resin grades serve specialty compounders and remote application sites with extended storage stability.
- Bulk:Tanker delivery to large automotive OEM coating lines aligns with just-in-time sequencing requirements.
- Granular:Intermediate physical form enables precise metering in automated compounding systems.
Liquid holds installed capacity. Powder is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German resin manufacturers export modified alkyd precursors to automotive coating lines in the United States and industrial finishers in India, establishing a transatlantic-Asian trade corridor that channels European formulation expertise into high-growth demand centers.
Germany
Automotive OEM refinishing and industrial maintenance specifications drive demand concentration. REACH Phase 2 restrictions on volatile organic compounds in decorative coatings accelerate water-based system adoption. Coating clusters around Ludwigshafen and Leverkusen anchor European consumption, with resin-pigment integrated supply contracts consolidating procurement authority.
United States
Collision repair volume recovery and aerospace finishing line retrofits expand alkyd system uptake. EPA NESHAP amendments mandate HAP content reductions in surface coating operations. Industrial applicators in Michigan and Ohio retrofit spray booths to accommodate higher-solids formulations that maintain transfer efficiency under compliance deadlines.
China
Infrastructure investment and construction coating demand concentrate consumption in eastern manufacturing corridors. Dual carbon goals and MEE emissions standards pressure solvent-based formulation transitions. Yangtze River Delta coating manufacturers source modified alkyd precursors for architectural and protective applications serving domestic build-out programs.
India
Protective coatings penetration remains limited despite infrastructure expansion under PLI scheme incentives for specialty chemicals. BIS standards and central environmental ministry directives shape permissible solvent content for industrial finishes. Formulation partnerships between European resin suppliers and domestic coating manufacturers concentrate in Gujarat and Maharashtra industrial zones.
Japan
Precision equipment housing and electronics finishing specifications demand humidity-resistant alkyd-polyurethane hybrids. METI industrial decarbonization guidelines and JIS standards constrain additive selection for specialty applications. Electronics manufacturers in Kanto and Kansai regions specify these systems where aesthetic and protective requirements must coexist.
Modified Alkyd Resin Market Competitive Environment
On the supply side, the industry is moderately consolidated around integrated chemical conglomerates with backward control over polyol and fatty acid feedstocks. Specialty resin houses and diversified coating material suppliers occupy distinct tier positions. Two strategic archetypes dominate: integrated petrochemical-resin producers leveraging captive raw material access, and focused alkyd specialists concentrating on high-performance graft modifications. Competitive moves center on direct precursor supply agreements with automotive OEMs and capacity alignment with waterborne technology transitions.
Among European integrated producers, BASF SE anchors the resin-pigment supply tier, while Wacker Chemie AG occupies a position within silicone-graft specialization. Dow exemplifies the North American hybrid-technology vector. These three entities represent the geographic and technological span of competitive positioning, with each sitting within distinct regulatory and demand environments that shape their strategic options.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Mitsui Chemicals |
| BASF SE |
| Arakawa Chemical Industries |
| MACRO POLYMERS |
| Dow |
| PPG Industries |
| Eternal Materials Co., Ltd. |
| Polynt |
| Others |
Value Chain & Pricing Dynamics
Nordic tall oil fatty acid concentration in Scandinavian pulp-byproduct clusters funnels margin pools toward German resin manufacturers with captive polyol integration, while downstream coating formulators face asymmetric feedstock access.
Pricing Analysis
Waterborne alkyd systems command premium positioning over solvent-based grades and high-solids intermediates. Three-tier pricing structure across premium silicone-graft formulations, standard water-based dispersions, and economy solvent-cut grades reflects certification tier and volume scale differentiation. Cost compression in conventional solvent alkyds is intensifying because REACH Phase 2 compliance investments are eroding legacy margin pools. Automotive OEM procurement teams exhibit lowest price sensitivity due to specification lock-in, while Indian protective coating formulators remain most cost-responsive.
Supply Chain Analysis
EU dual-use export controls on silicone-graft catalyst technologies limit technology transfer to non-aligned manufacturing jurisdictions. Supply concentrates in Germany, China, and Japan, with raw material dependencies spanning Nordic tall oil fatty acids, Saudi petrochemical-derived polyols, and Japanese specialty silicone intermediates. Single-source vulnerability runs through dibutyltin catalyst suppliers facing ECHA requalification timelines. Distribution runs through integrated resin-pigment supply contracts directly into automotive OEM lines, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs negotiating direct precursor supply agreements, fragmenting specification authority away from traditional coating distributors.
For Market Incumbents: Pre-empt epoxy-urethane hybrid substitution by accelerating silicone-alkyd UV-curable convergence for furniture finishing applications. Backward integration into bio-based tall oil feedstock certification secures long-term formulation competitiveness against REACH-mandated reformulation cycles. For New Entrants and Emerging Players: Establish a beachhead in Indian protective coatings under the PLI scheme for specialty chemicals, where infrastructure investment outpaces domestic resin supply capability. FDA indirect food-contact certification for can coatings offers first-mover margin pools with limited qualified supplier competition. For Investors and Strategic Acquirers: Capital is best deployed toward waterborne alkyd specialists with colloidal stability expertise concentrated in Ludwigshafen and Leverkusen industrial clusters. Long-term viability hinges on regulatory compliance bandwidth across REACH, EPA NESHAP, and emerging carbon border adjustment mechanisms. Monitor ECHA catalyst requalification timelines as inflection indicators for forced consolidation among solvent-dependent formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Tall oil fatty acid certification secures REACH-compliant raw material positioning against Nordic supply concentration. |
| Waterborne Technology Capacity Expansion | Stuttgart and Munich automotive corridors demand qualified suppliers for EPA NESHAP-compliant coating lines. |
| Silicone-Graft Specialization Partnership | Wacker Chemie AG's expertise enables exterior coil coating durability specifications for infrastructure protection. |
| Indian Joint Venture Formation | Gujarat and Maharashtra industrial zones require European formulation expertise for PLI scheme infrastructure projects. |
| UV-Curable Hybrid Platform Launch | Electron-beam cure mechanisms address humidity-sensitive drying limitations in Japanese electronics finishing. |
Study Parameters
The analysis maps waterborne alkyd dispersions, solvent-based conventional grades, high-solids automotive formulations, and silicone-graft specialty resins, each validated through coating formulator procurement leads, automotive OEM specification engineers, industrial maintenance contractors, and resin plant technical directors. Primary interview intelligence triangulates against customs trade data, Cefic sector reports, EPA regulatory filings, and SEC disclosures from integrated chemical conglomerates. Bottom-up volume builds from end-use consumption patterns cross-check against top-down resin production capacity assessments.
Fixed assumptions across the projection horizon include sustained REACH Phase 2 enforcement stringency, continued Nordic tall oil fatty acid supply concentration, and stable automotive OEM specification authority consolidation. Segmentation dimensions modeled span product type technology tier, end-use industry application maturity, and regional regulatory cluster alignment. CAGRs derive from regression analysis against historical formulation substitution elasticities, with industry-specific inputs incorporating EPA NESHAP compliance deadline schedules and ECHA substance evaluation timelines.
Stress conditions across feedstock price volatility, regulatory acceleration scenarios, and hybrid technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding coating line retrofit investment cycles and OEM qualification timeline durations. Material shifts in EU carbon border adjustment implementation or ECHA catalyst restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Indonesia Polypropylene Market