
 Medical 3D Printing Plastics Market | 2026-2036
Medical 3D Printing Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical 3D Printing Plastics Market Intelligence
Buyer concentration across hospital systems and contract manufacturers is broadening as point-of-care 3D printing expands beyond academic medical centers into regional hospitals. Stratasys Ltd. leverages its installed base of PolyJet systems to sustain service revenue from dental laboratories across North America. Evonik Industries AG anchors high-performance PEEK filament supply for cranial implant producers, while 3D Systems, Inc. competes in biocompatible resin formulations for surgical planning models.
Medical 3D printing plastics encompass thermoplastic and photopolymer materials engineered for biocompatibility, sterilization resistance, and layer adhesion precision in additive manufacturing of patient-matched devices. These polymers must meet ISO 10993 cytotoxicity standards and withstand gamma or steam sterilization cycles without dimensional distortion. Orthopedics and dentistry command the largest volume positions, with PEEK and PEKK polymers capturing premium margin pools in spinal and cranial implant applications. FDM technology dominates filament-based production for provisional surgical guides, while SLA resin systems lead in dental aligner manufacturing where surface finish precision drives adoption.
FDA 510(k) and EU MDR frameworks govern material qualification, mandating lot traceability and mechanical validation for implant-grade polymers. The EPA monitors volatile organic compound emissions from resin-based printing operations, while ISO 13485 quality management requirements shape supplier certification thresholds. Stakeholders must monitor evolving FDA guidance on point-of-care device manufacturing as decentralized production challenges traditional audit and liability structures.
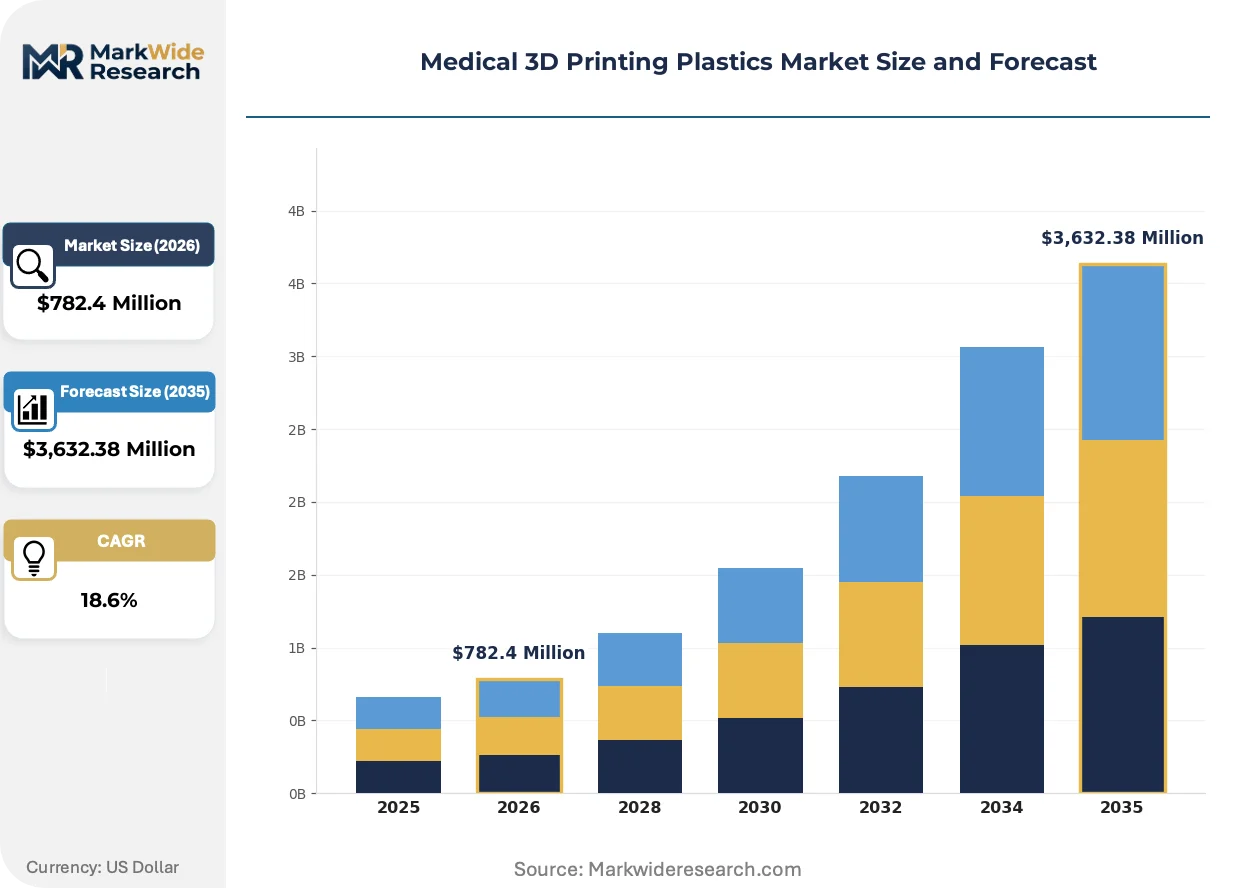
Market Dynamics
Point-of-care manufacturing is fragmenting traditional supply chains as hospital systems install in-house polymer extrusion and resin printing capabilities, bypassing centralized device manufacturers for patient-matched surgical tools.
Growth Catalysts
- FDA 510(k) Pathway Expansion:Material qualification frameworks for photopolymer resins are accelerating device approvals, enabling faster commercialization of dental aligners and cranial implants.
- Germany's Precision Cluster:Munich and Freiburg host concentrated medical device engineering talent, drawing filament producers and sterilization validation labs into geographic proximity.
- PEEK Polymer Performance:High-temperature thermoplastics meeting ISO 10993 cytotoxicity standards are displacing titanium in spinal fusion cages due to radiolucency and modulus matching.
Market Restraints
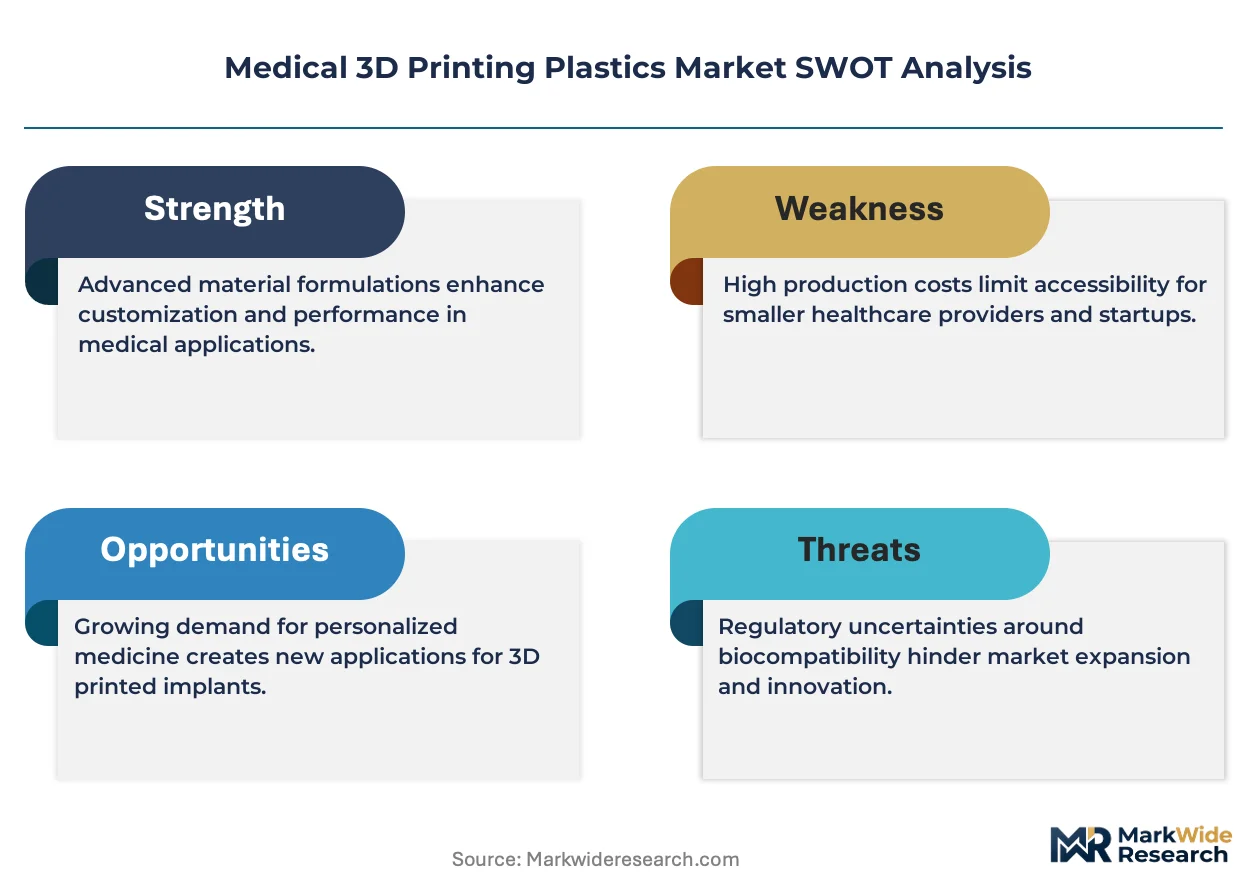
- Specialized Resin Cost Volatility:Photopolymer feedstock prices fluctuate with acrylate monomer supply, squeezing margins for dental laboratory service providers.
- Filament Supply Concentration:Medical-grade PEEK and PEKK filament production clusters in Germany and Switzerland, creating single-source vulnerability for North American implant manufacturers.
- Steam Sterilization Compatibility:Layer adhesion degradation in repeated autoclave cycles limits reusable surgical guide applications, constraining addressable procedure volume.
Strategic Opportunities
- Brazil's Regulatory Opening:ANVISA is streamlining 3D-printed device registration, creating first-mover advantage for biocompatible resin suppliers in Latin America's largest healthcare market.
- AI-Integrated Print Planning:Machine learning segmentation of CT/MRI datasets is converging with automated support generation, reducing design labor for patient-specific osteotomy guides.
- EU MDR Technical Documentation:Stricter post-market surveillance requirements are favoring suppliers with established ISO 13485 quality systems and lot traceability infrastructure.
Industry Challenges
- Biomedical Engineer Shortage:Cross-trained professionals fluent in both DICOM segmentation and polymer rheology remain scarce, slowing point-of-care facility staffing.
- Gamma Sterilization Validation:Polymer chain scission testing for implant-grade materials extends certification timelines, delaying revenue recognition for new material launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical 3D Printing Plastics Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $3,632.38 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, ABS, PVA, PETG End Use: Orthopedics, Dentistry, Implants, Prosthetics Technology: FDM, SLA, SLS, DLP Form: Filament, Powder, Resin, Sheet |
| Companies Covered | Victrex plc, Stratasys Ltd., Solvay, SABIC, Evonik Industries AG, DSM, Arkema, 3D Systems, Inc., ENVISIONTEC, INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical 3D Printing Plastics Market Strategic Shifts & Innovations
Material science advances and decentralized production architectures are compressing the gap between diagnostic imaging and finished patient-matched devices, altering where value accumulates in the supply chain.
Multi-material PolyJet systems are expanding into soft-tissue surgical modeling, enabling simultaneous printing of rigid bone analogs and compliant vascular structures. Academic medical centers in the United States are adopting these platforms for complex oncologic resection planning. The technology is expanding into reimbursement pathways as CMS evaluates Category III codes for pre-surgical 3D-printed models.
REACH regulation amendments on microplastic release are pressuring resin formulators to reformulate photopolymer constituents, particularly in dental aligner manufacturing where single-use thermoforming molds dominate volume. European formulators are accelerating bio-based acrylate development to preempt restriction schedules. Dental laboratories in Germany and the Netherlands are piloting closed-loop resin recovery systems to demonstrate environmental compliance.
Hospital procurement departments are consolidating vendor relationships around suppliers offering both material qualification documentation and sterilization validation services. Contract manufacturers with captive polymer testing laboratories are displacing pure-play filament distributors in North American academic medical center supply agreements. This concentration is most visible in California and Texas hospital systems where capital budgets for point-of-care installations exceeded fifty units annually.
Medical 3D Printing Plastics Market Segmentation
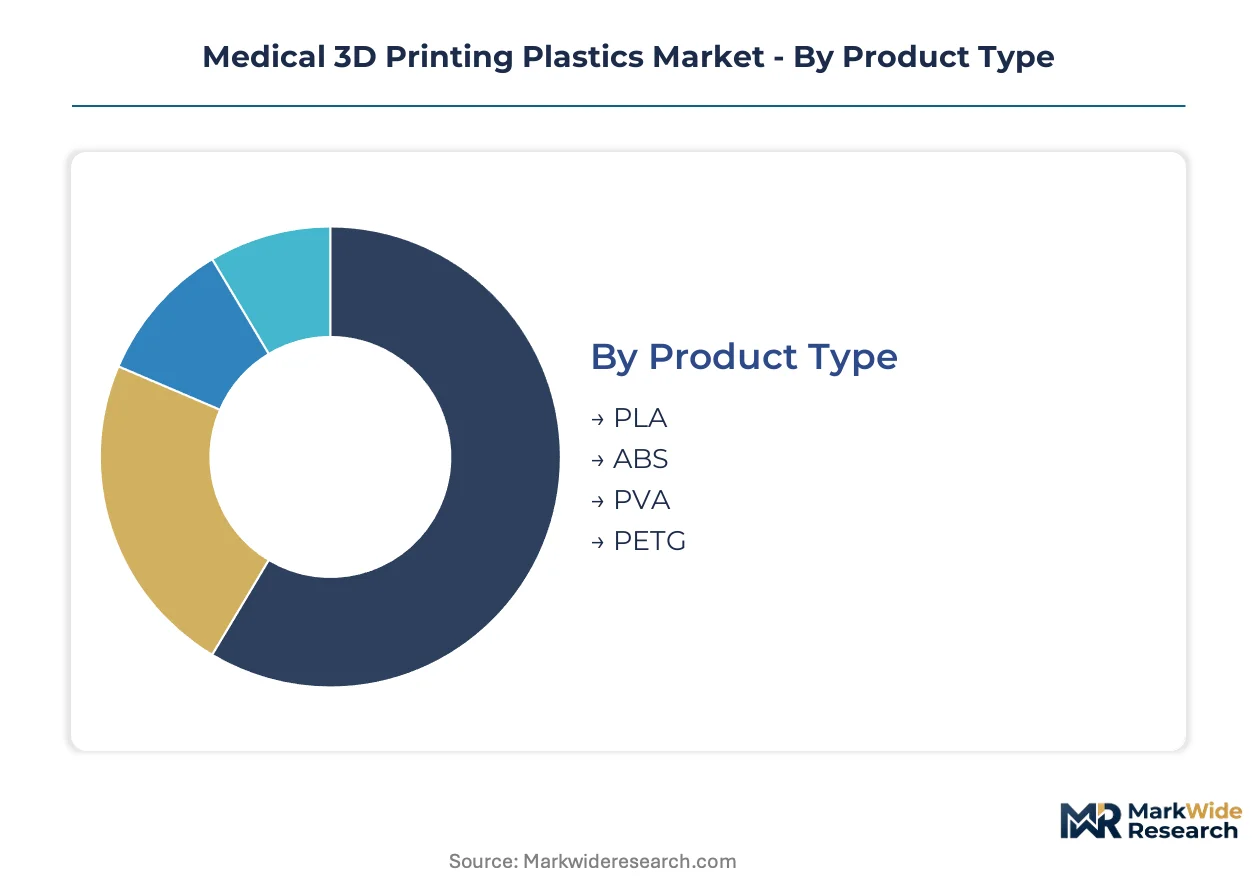
Material selection in medical 3D printing hinges on sterilization compatibility and mechanical performance requirements. Each segment category reflects distinct trade-offs between biocompatibility certification costs and production throughput.
Product Type:
Customization intensity varies sharply across this category, from commodity thermoplastics for surgical planning models to implant-grade polymers requiring extensive biocompatibility validation.
- PLA:Derived from corn starch or sugarcane, this biodegradable thermoplastic offers low-temperature printability ideal for disposable surgical guides. Demand concentrates in North American dental laboratories seeking cost-effective aligner thermoforming molds, though its glass transition temperature limits steam sterilization reuse.
- ABS:Acrylonitrile butadiene styrene delivers impact resistance and dimensional stability for durable anatomical models. German hospital systems favor ABS for pre-surgical planning in complex oncologic resections where repeated handling durability matters.
- PVA:Water-soluble support material enabling complex geometries in multi-material prints. Primarily consumed by contract manufacturers serving orthopedic device prototyping.
- PETG:Glycol-modified polyester combines chemical resistance with FDA food-contact approvals, bridging into medical packaging applications. Swiss filament producers dominate medical-grade PETG supply.
Leading the category by volume: PLA. Expanding most quickly: PETG.
End Use:
Application maturity spans from established dental workflows to emerging point-of-care implant production, with reimbursement pathways determining commercial viability.
- Orthopedics:Patient-specific cutting guides for knee and hip arthroplasty represent the most validated reimbursement category. Munich-area hospitals process the highest European volume of polymer guides for complex revision surgeries.
- Dentistry:Clear aligner thermoforming molds dominate resin consumption, with SLA systems running continuous production in outsourced dental laboratories. FDA 510(k) clearances for direct-printed aligners are accelerating material qualification.
- Implants:Cranial and spinal applications demand ISO 10993 certified PEEK and PEKK with lot traceability. Gamma sterilization validation extends certification timelines for new material entrants.
- Prosthetics:Socket liners and cosmetic covers prioritize comfort and aesthetics over load-bearing performance. Veterans Affairs hospitals in the United States represent concentrated demand for customized lower-limb prosthetics.
Orthopedics generates the largest revenue pool. Implants show the steepest expansion trajectory as PEEK displaces titanium in spinal fusion.
Technology:
Process selection determines surface finish precision, build speed, and material compatibility, with dental volume driving resin system adoption.
- FDM:Fused deposition modeling dominates filament-based production for provisional surgical guides and anatomical models. Lower capital costs enable regional hospital adoption outside academic centers.
- SLA:Stereolithography leads dental aligner manufacturing where layer resolution below 50 microns drives clinical acceptance. Post-processing resin washing stations create EPA VOC compliance burdens.
- SLS:Selective laser sintering processes nylon and PEEK powders for durable, sterilizable instruments. Limited powder bed recycling ratios constrain cost efficiency.
- DLP:Digital light projection offers faster layer curing than SLA for same-resolution outputs. Emerging in chairside dental applications requiring same-day turnaround.
SLA commands the largest installed base. DLP is gaining share fastest in time-sensitive clinical workflows.
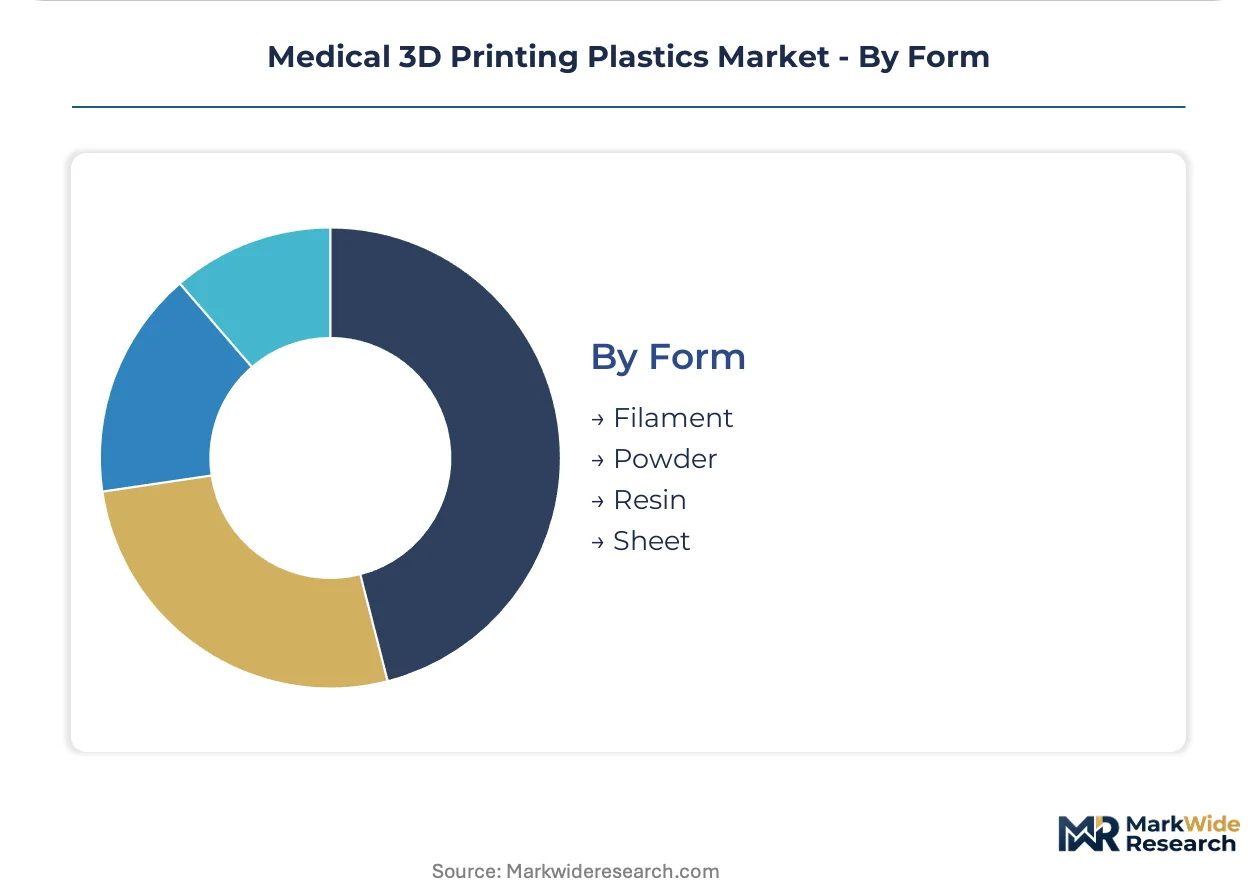
Form:
Feedstock format dictates supply chain logistics and point-of-care inventory requirements, with filament benefiting from ambient storage stability.
- Filament:Spooled thermoplastics enable FDM production with minimal environmental controls. Evonik Industries anchors high-performance PEEK filament supply for cranial implant producers.
- Powder:Polyamide and PEEK powders require inert atmosphere handling and sieving recovery systems. SLS powder aging limits reuse cycles, constraining per-part economics.
- Resin:Photopolymer liquids demand UV-blocking packaging and temperature-controlled shipping. REACH microplastic amendments are pressuring acrylate formulation changes.
- Sheet:Laminated thermoplastic stock for high-temperature compression molding of dental appliances. Limited to legacy manufacturing workflows outside additive mainstream.
Filament leads by volume. Resin climbs fastest, propelled by dental aligner production scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks in the United States and Germany currently absorb the highest volumes of medical-grade polymer feedstock, while Brazil's regulatory opening and Japan's precision manufacturing base are accelerating new capacity commitments.
United States
Veterans Affairs hospitals and academic medical centers in Texas and California drive concentrated demand for patient-specific prosthetics and surgical planning models. FDA 510(k) clearances for point-of-care 3D-printed devices are expanding material qualification pathways for photopolymer resins. The Greater Boston cluster anchors contract manufacturing capacity serving orthopedic device innovators with captive sterilization validation laboratories.
Germany
Munich and Freiburg host Europe's densest concentration of medical device engineering talent and PEEK filament production facilities. EU MDR technical documentation requirements and ISO 13485 quality mandates favor suppliers with established lot traceability infrastructure. Bavarian hospital systems process the highest European volume of polymer surgical guides for complex revision arthroplasties.
Switzerland
Swissmedic's stringent device registration standards attract cranial implant producers seeking premium certification credentials. Swiss filament producers dominate medical-grade PETG supply chains serving dental laboratory networks across Western Europe. The Lake Geneva corridor concentrates precision polymer extrusion capacity for implant-grade thermoplastics.
Brazil
ANVISA's streamlined 3D-printed device registration protocols are creating first-mover advantage for biocompatible resin suppliers in Latin America's largest healthcare market. São Paulo hospital systems are piloting point-of-care manufacturing installations for patient-matched surgical instruments. Southeast Brazil's medical device distribution infrastructure supports rapid clinical adoption of imported polymer feedstocks.
Japan
PMDA's structured approval pathways for patient-matched devices are accelerating dental aligner production scaling in the Osaka-Kobe manufacturing belt. METI's industrial policy supports domestic filament production for orthopedic applications to reduce import dependency. The Nagoya medical device cluster integrates precision machining expertise with additive manufacturing polymer processing capabilities.
Medical 3D Printing Plastics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized high-performance polymer formulations and point-of-care service models. The market structure reflects moderate consolidation among filament extruders and resin formulators, with fragmentation persisting in regional distribution channels. Three archetypes dominate: diversified chemical conglomerates with medical polymer divisions, pure-play additive manufacturing material specialists, and integrated device manufacturers with captive feedstock operations. Competitive intensity centers on sterilization validation bundling and geographic proximity to hospital procurement networks.
Among diversified chemical producers, Victrex plc and Solvay exemplify the premium-tier archetype focused on implant-grade PEEK and PEKK polymers with extensive biocompatibility certification. Stratasys Ltd. and 3D Systems, Inc. occupy positions bridging hardware installation and consumable supply, leveraging installed printer bases to sustain recurring material revenue. Evonik Industries AG represents the specialized filament producer archetype, anchoring high-performance polymer supply for cranial implant manufacturers with rigorous lot traceability systems.
| Leading Market Players |
|---|
| Victrex plc |
| Stratasys Ltd. |
| Solvay |
| SABIC |
| Evonik Industries AG |
| DSM |
| Arkema |
| 3D Systems, Inc. |
| ENVISIONTEC, INC. |
| Others |
Cost & Logistics Intelligence
Acrylate monomer costs cascade through photopolymer resin pricing tiers, with European REACH compliance expenses layering onto premium-grade formulations while commodity dental resins absorb spot-market volatility in North American laboratory procurement.
Pricing Analysis
Volume-margin splits separate implant-grade PEEK filament commanding certification premiums from commodity PLA surgical guides competing on throughput. Pricing stratifies across ISO 10993-certified implant polymers, FDA 510(k)-validated dental resins, and provisional thermoplastics for single-use applications. Cost compression in dental aligner thermoforming molds intensifies as outsourced laboratories consolidate purchasing power. Hospital procurement committees exhibit lowest price sensitivity for spinal fusion cage materials, while independent dental laboratories face acute margin pressure from resin feedstock volatility.
Supply Chain Analysis
Temperature-controlled freight for photopolymer resins adds logistics premiums to landed costs, particularly for Brazilian hospital systems importing from European formulators. Medical-grade PEEK and PEKK filament production clusters in Germany and Switzerland, with Swiss producers dominating PETG supply chains. Raw material dependencies encompass acrylate monomers, high-purity polymer powders, and specialty extrusion additives. Single-source vulnerability concentrates in cranial implant filament supply, where Evonik Industries anchors European production. Distribution runs through hospital procurement networks and contract manufacturing aggregators serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation requirements and ISO 13485 certification thresholds are forcing consolidation among regional filament distributors unable to fund quality system investments.
For Market Incumbents: Deepen backward integration into polymer powder production to secure PEEK supply chains against German-Swiss concentration risk. Expand captive sterilization validation laboratories in Texas and California hospital corridors. Defensive positioning requires bundling material qualification documentation with point-of-care installation support to displace pure-play distributors. For New Entrants and Emerging Players: Dental laboratories in São Paulo represent the most penetrable channel partner type for biocompatible resin suppliers seeking first-mover advantage under ANVISA's streamlined registration protocols. Target AI-integrated surgical planning software partnerships to bypass capital-intensive hardware installation barriers. White-space capture favors Latin American resin distribution before incumbent formulators establish local blending capacity. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for point-of-care devices is the leading indicator that hospital-installed manufacturing capacity will consolidate around integrated material-hardware-service providers. Long-term viability favors acquiring contract manufacturers with captive polymer testing laboratories and established GPO relationships. Watch for gamma sterilization validation bottlenecks delaying new material launches as a signal of supply constraint premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality system infrastructure satisfies EU MDR post-market surveillance mandates for implant-grade polymer suppliers. |
| Hospital System Partnership | Direct procurement agreements with Veterans Affairs networks secure volume commitments for patient-matched prosthetic applications. |
| Backward Integration into Polymer Extrusion | In-house filament production reduces dependency on German-Swiss supply concentration for PEEK cranial implant feedstock. |
| AI-Integrated Print Planning Development | Machine learning segmentation tools reduce design labor costs for patient-specific osteotomy guide production. |
| Reimbursement Strategy Execution | CMS Category III code pursuit for pre-surgical models expands addressable market for PolyJet soft-tissue applications. |
Research Approach
Independent corroboration across FDA 510(k) filing databases, EU MDR technical documentation registries, and hospital procurement contract records underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, dental laboratory operations directors, and sterilization validation specialists combined with secondary validation from SEC filings, customs trade data, and CMS reimbursement databases. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across material type, end-use application, and technology platform dimensions.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled encompass product type, end-use application, technology platform, feedstock form, and geographic production cluster. CAGRs derive from trend extrapolation of installed base expansion, procedure volume growth, and material substitution dynamics. Industry-specific forecast inputs include FDA clearance velocity for point-of-care devices and ANVISA registration pipeline progression.
Caveats apply where gamma sterilization validation delays, REACH microplastic regulatory amendments, or acrylate monomer supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about hospital capital budget allocation and dental aligner production scaling. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market