
 Middle East Polycarbonate (PC) Market | 2026-2036
Middle East Polycarbonate (PC) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Polycarbonate (PC) Market Insights
Commodity-grade resin trading is narrowing as regional producers deepen captive offtake into downstream extrusion and compounding. SABIC leverages its Yanbu and Jubail manufacturing complexes to dominate feedstock-integrated polycarbonate supply across the Gulf. Borouge anchors high-performance grades for infrastructure and automotive specifications through its Abu Dhabi operations. Covestro AG competes on optical-grade and medical-device-certified resin lines, sustaining premium positioning despite logistics costs from European production bases.
Polycarbonate is a high-performance thermoplastic polymer derived from bisphenol A and phosgene, characterized by glass-like optical clarity, impact resistance exceeding 250 times that of standard glass, and service temperatures up to 135°C; manufacturers employ interfacial polycondensation or melt transesterification processes to produce it for demanding optical, protective, and structural applications. Injection molded components command the largest volume share as automotive manufacturers specify PC for headlamp lenses and interior trim requiring dimensional stability under thermal cycling. Extruded sheets represent the fastest-expanding product category as construction firms specify multi-wall and solid PC panels for stadium roofing, greenhouse cladding, and facade systems across the Gulf's extreme solar exposure environments.
Saudi Arabia's SFDA and the UAE's MOHAP enforce biocompatibility and sterilization-resistance standards that shape medical-device-grade polycarbonate import requirements and local qualification protocols. REACH-equivalent chemical registration frameworks under Gulf Standardization Organization harmonization are tightening monomer traceability and additive disclosure obligations for resin suppliers seeking market access across member states. Stakeholders must monitor feedstock cost volatility from regional crude differentials and assess backward integration economics before committing to greenfield compounding investments.
Market Dynamics
Feedstock-integrated petrochemical complexes across the Gulf Cooperation Council are compressing resin supply chains, locking construction and automotive offtake into localized polycarbonate sourcing networks.
Growth Catalysts
- Energy-efficiency mandates:Gulf Standardization Organization building codes now specify polycarbonate glazing for thermal performance in commercial envelopes, accelerating multi-wall sheet specification across Saudi Arabia's industrial cities.
- Automotive localization:Headlamp lens and interior trim manufacturing is clustering near Jubail and Yanbu resin supply, reducing logistics exposure for tier-one suppliers serving regional OEM assembly.
- Qatar and Kuwait infrastructure pipelines:Stadium roofing and transportation hub projects are specifying solid and corrugated polycarbonate panels for durability under extreme solar loading and sand abrasion.
Market Restraints
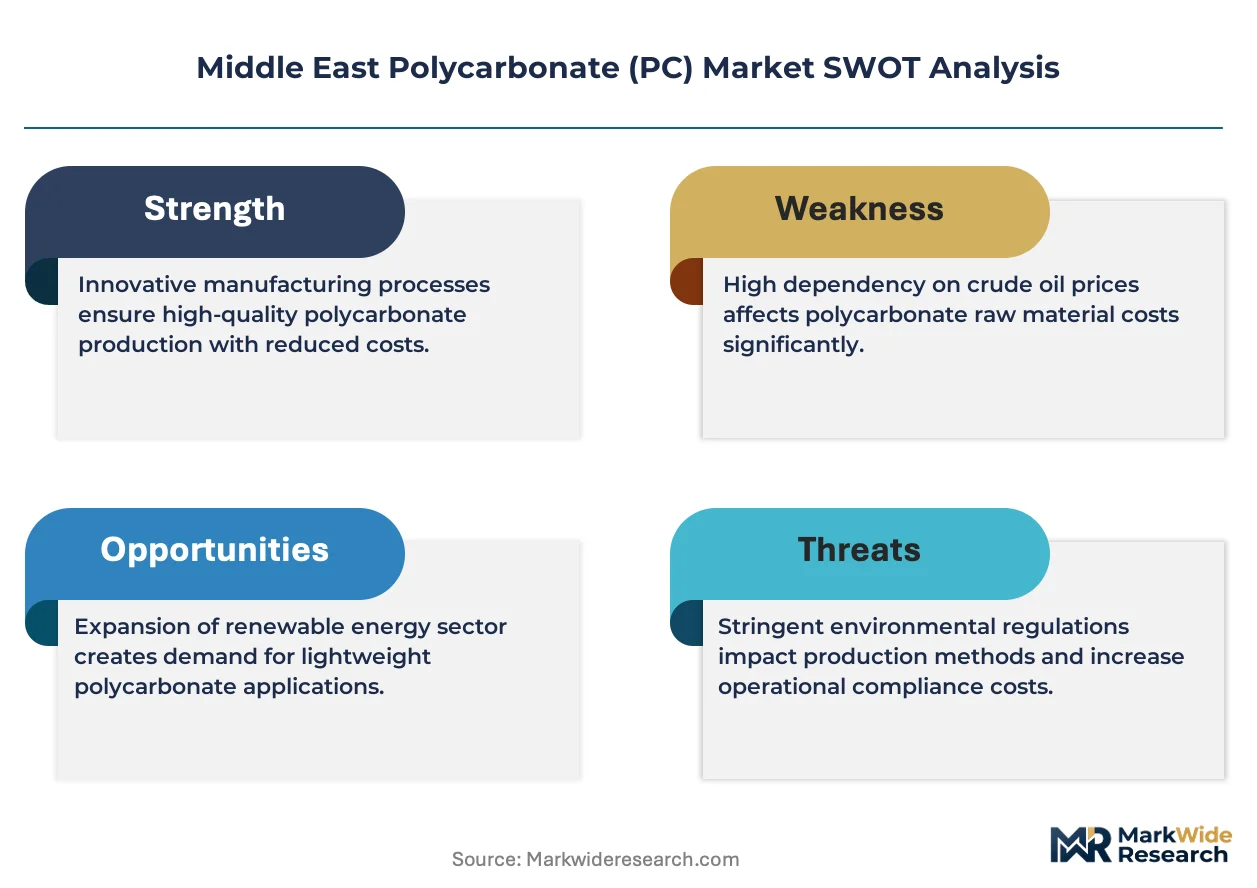
- Bisphenol A feedstock volatility:Crude differential swings and phenol supply tightness from European crackers transmit directly into polycarbonate resin cost structures, compressing extruder margins during feedstock spikes.
- Single-source supply concentration:SABIC's Yanbu and Jubail complexes control the majority of Gulf resin capacity, creating qualification risk for compounders dependent on captive offtake allocations.
- Acrylic substitution in optical applications:PMMA grades are displacing polycarbonate in cost-sensitive signage and lighting diffusers where impact resistance is secondary to price.
Strategic Opportunities
- Medical-device grade localization:SFDA biocompatibility protocols and MOHAP sterilization-resistance standards create qualification pathways for resin suppliers establishing Gulf-based compounding and certification.
- Photovoltaic integration:BIPV module manufacturers are specifying UV-stabilized polycarbonate front sheets as glass alternatives for weight-constrained rooftop installations across the UAE's solar parks.
- Recycling infrastructure gaps:Post-industrial and post-consumer polycarbonate collection networks remain underdeveloped, offering first-mover positioning for mechanical recycling and chemical depolymerization ventures.
Industry Challenges
- Specialized extrusion technician scarcity:Multi-wall sheet production and co-extrusion layer control require skills concentrated in European and Asian equipment corridors, constraining Gulf-based line commissioning.
- REACH-equivalent registration timelines:Gulf Standardization Organization monomer traceability and additive disclosure obligations are extending resin qualification cycles for suppliers without existing GCC regulatory dossiers.
- Legacy compounding asset integration:Brownfield extrusion lines from acquired regional players require retrofit for optical-grade cleanliness standards, delaying high-margin product ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Polycarbonate (PC) Market |
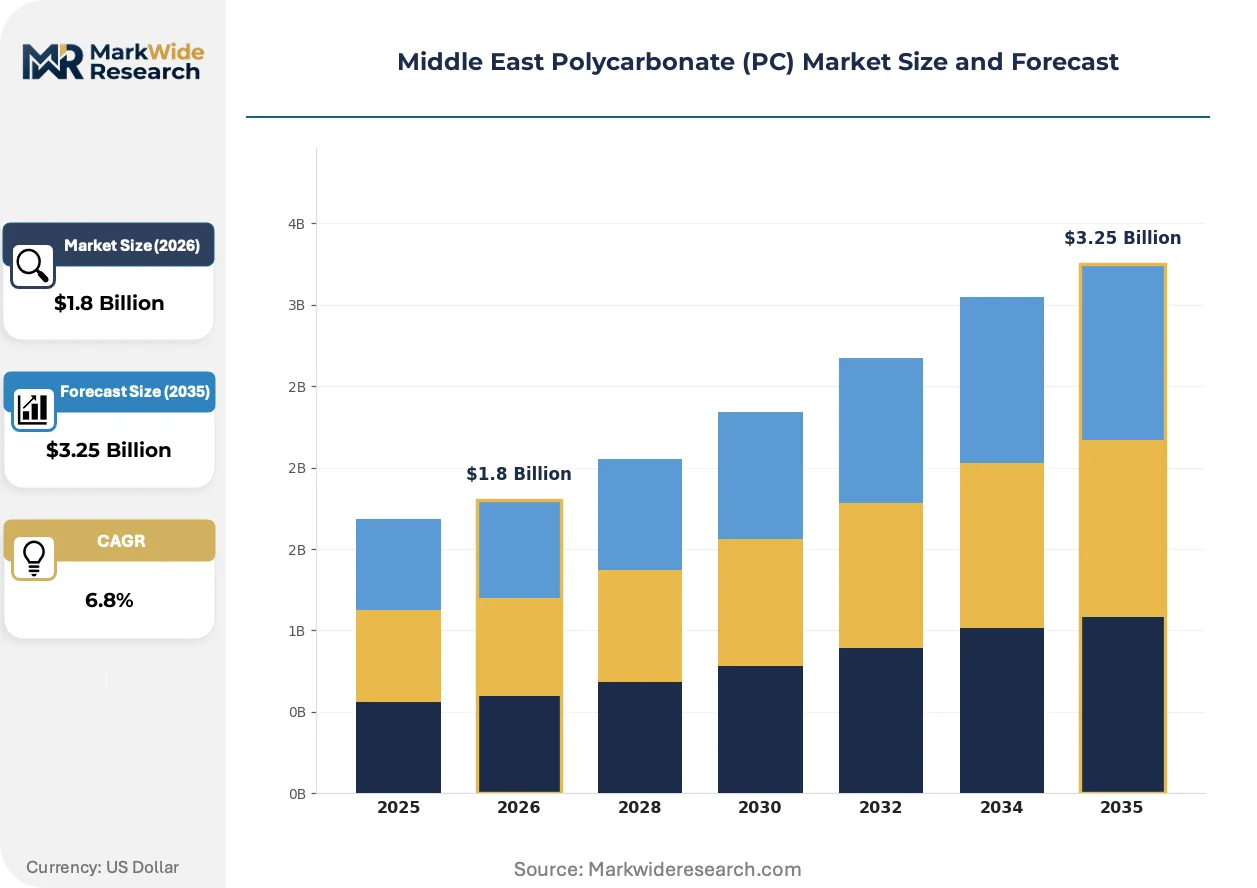
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molded, Extruded Sheets, Optical Lenses, Films Application: Automotive Components, Electronics, Construction, Medical Devices End User: Consumer Electronics, Automotive Manufacturers, Healthcare Providers, Construction Firms Technology: Thermoplastic Processing, Coating, Reinforcement, 3D Printing |
| Companies Covered | Covestro AG, SABIC, LG Chem, Sumitomo Chemical Co., Ltd., Teijin Limited, Mitsubishi Gas Chemical Company, BASF, Borouge, DuPont, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Polycarbonate (PC) Market Trends and Innovations
Digital manufacturing integration and regulatory harmonization are compressing product development cycles while reshaping how polycarbonate specifications propagate from resin producers to end-use fabricators.
Co-extrusion with nano-ceramic infrared-blocking layers is digitizing thermal management capabilities in building envelope applications. Façade engineers in Dubai and Abu Dhabi are specifying these functionalized sheets for solar heat gain coefficient targets. The technology is digitizing how construction procurement teams evaluate lifecycle energy performance against first-cost alternatives.
REACH-equivalent chemical registration frameworks under Gulf Standardization Organization harmonization are tightening monomer traceability obligations for bisphenol A and phosgene-derived intermediates. Resin suppliers must now disclose additive packages and stabilizer chemistries to maintain market access across Saudi Arabia, the UAE, Kuwait, Qatar, Bahrain, and Oman. Medical-device-grade polycarbonate imports face the steepest compliance burden, with SFDA and MOHAP biocompatibility protocols layering atop base chemical registration.
Consolidated procurement by mega-project developers is compressing supplier qualification cycles and unbundling after-sales technical service from resin supply contracts. EPC firms managing Saudi giga-project construction are centralizing polycarbonate specification authority, displacing traditional distributor relationships. The UAE's Dubai and Abu Dhabi corridors exhibit the most concentrated buyer power, with single-source awards for stadium and transportation glazing packages.
Middle East Polycarbonate (PC) Market Segmentation
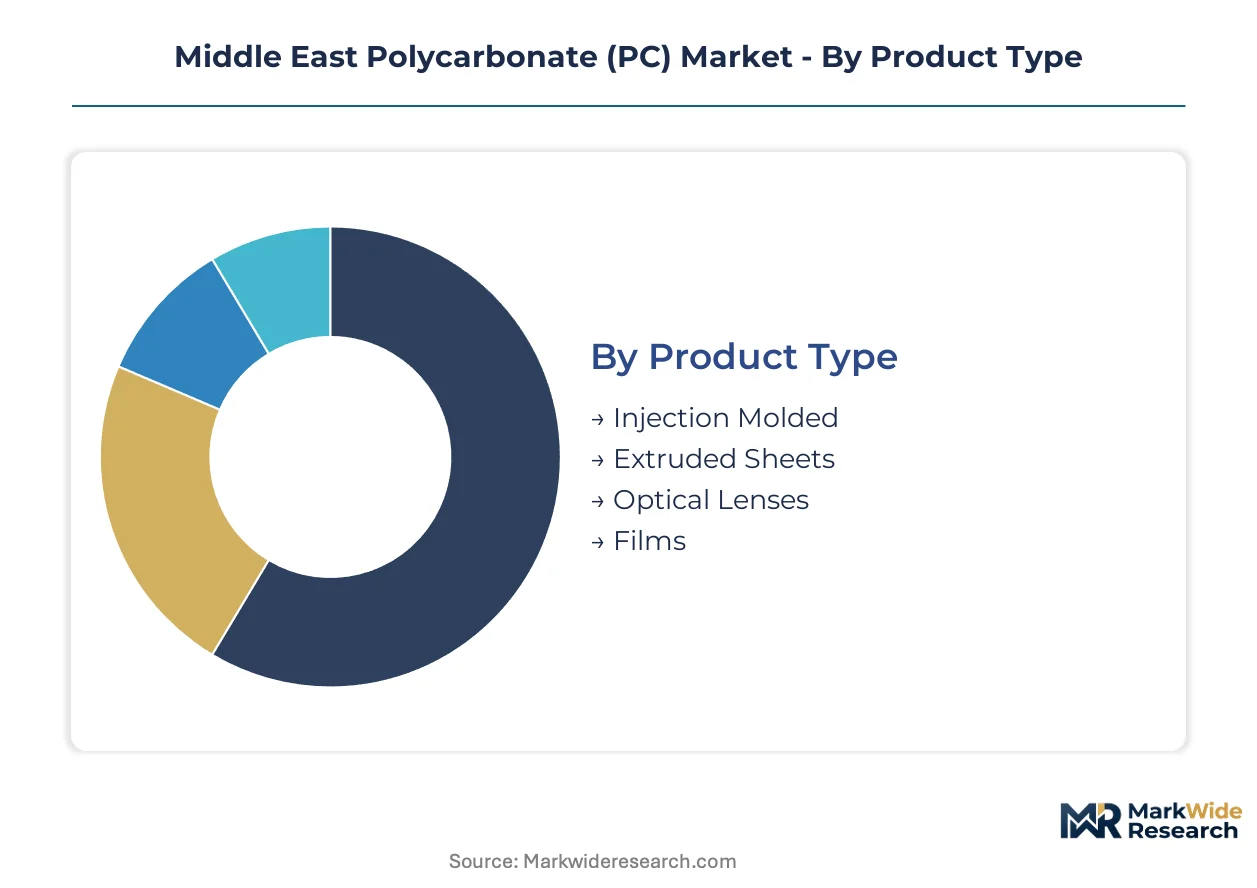
Polycarbonate demand across the Middle East fragments across processing technologies and end-use specifications that reshape procurement priorities for resin suppliers. Construction firms, automotive assemblers, and healthcare providers each impose distinct performance thresholds that determine grade selection and supplier qualification pathways.
Product Type:
Mature injection molding formats dominate established automotive supply chains while extruded sheet technologies accelerate into building envelope applications across Gulf construction corridors.
- Injection Molded:High-pressure molding of molten resin produces complex geometries with tight dimensional tolerances for under-hood components and interior trim. Saudi Arabia's Yanbu and Jubail automotive supplier clusters specify these grades for headlamp housings and instrument panel substrates requiring thermal cycling resistance.
- Extruded Sheets:Continuous roll-forming creates multi-wall and solid panels with UV-stabilized surfaces for stadium roofing and greenhouse cladding. Dubai and Abu Dhabi façade engineers specify these for solar heat gain coefficient compliance under Gulf Standardization Organization building codes.
- Optical Lenses:Ultra-pure resin grades achieve glass-like clarity for LED lighting diffusers and safety eyewear.
- Films:Thin-gauge calendered or cast products serve graphic overlay and membrane switch applications in electronics manufacturing.
Injection molded components retain volume leadership; extruded sheets hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity construction grades from certified medical and automotive specifications that command qualification premiums.
- Automotive Components:Headlamp lenses, panoramic roof modules, and interior trim require impact resistance and optical clarity under thermal stress. Tier-one suppliers near Jubail resin complexes reduce logistics exposure for regional OEM assembly plants.
- Construction:Multi-wall panels and solid glazing systems deliver thermal insulation and daylighting for commercial envelopes. Qatar stadium projects and UAE transportation hubs specify these for durability under extreme solar loading and sand abrasion.
- Electronics:Housing and connector applications leverage flame-retardant compounded grades for device miniaturization.
- Medical Devices:SFDA biocompatibility protocols and sterilization-resistance standards govern dialyzer housings and surgical instrument handles.
Construction applications command the largest volume position; medical device qualification unlocks the highest margin tier.
End User:
Customer type concentration determines technical service intensity and contract structure, with project developers consolidating procurement authority.
- Construction Firms:EPC contractors managing Saudi giga-projects and UAE mega-developments centralize polycarbonate specification authority, displacing traditional distributor relationships for stadium and transportation glazing packages.
- Automotive Manufacturers:Regional OEM assembly plants and tier-one suppliers cluster near feedstock-integrated resin complexes to secure captive offtake allocations.
- Healthcare Providers:Hospital networks and medical device assemblers demand SFDA and MOHAP-certified grades with full additive disclosure.
- Consumer Electronics:Smartphone and appliance manufacturers specify flame-retardant grades for housing applications.
Construction firms drive aggregate volume; healthcare providers impose the most stringent qualification barriers.
Technology:
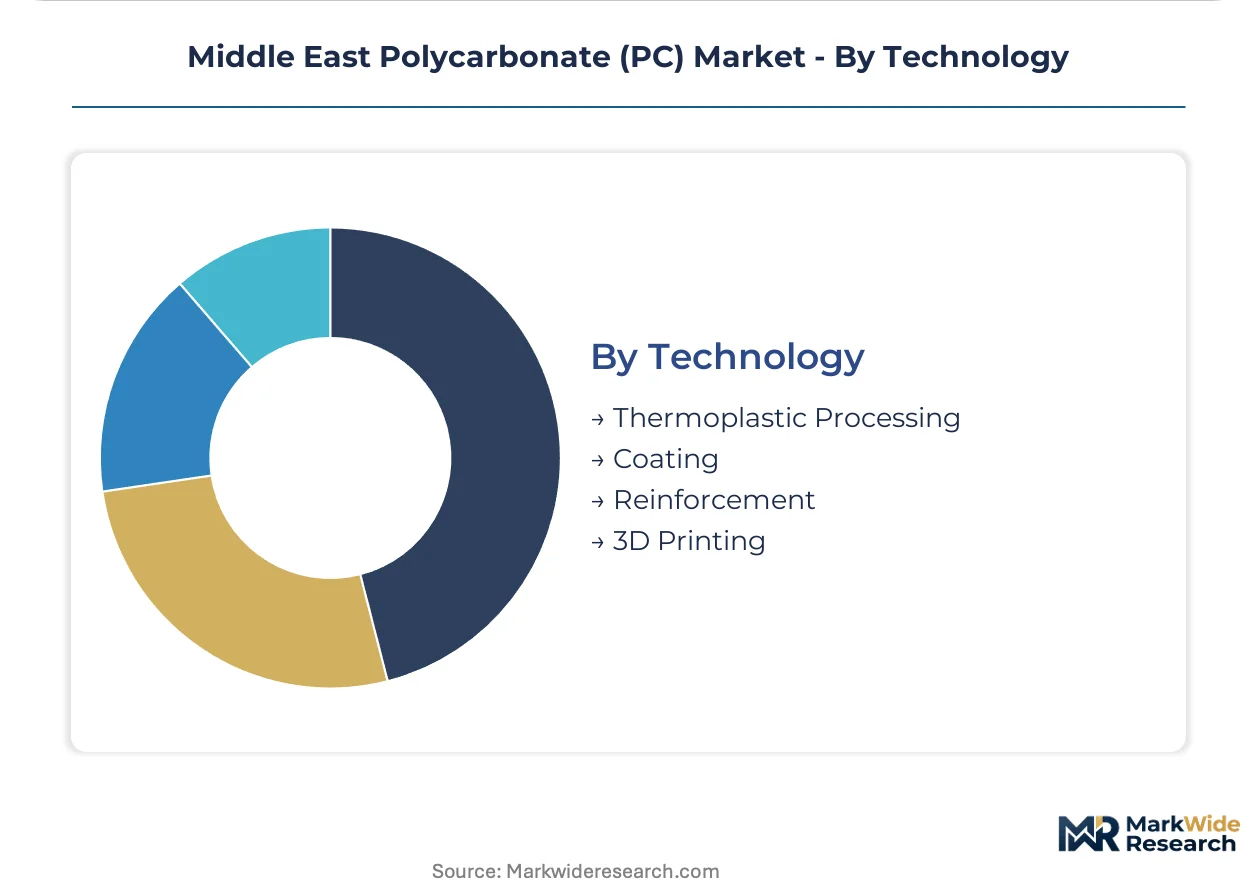
Supply concentration in thermoplastic processing contrasts with emerging capability gaps in additive manufacturing and functional coating integration.
- Thermoplastic Processing:Injection molding and extrusion dominate regional fabrication, with SABIC's Yanbu and Jubail complexes supplying feedstock-integrated resin to captive downstream operations.
- Coating:Nano-ceramic infrared-blocking layers and hardcoat treatments differentiate premium sheet products for Dubai and Abu Dhabi façade specifications targeting solar heat gain coefficient performance.
- Reinforcement:Glass fiber and mineral-filled compounds enhance stiffness for structural automotive applications.
- 3D Printing:Fused filament fabrication with PC-ABS and pure PC filaments remains nascent, constrained by specialized technician scarcity and equipment import dependencies.
Thermoplastic processing anchors current supply; coating functionalization is climbing the fastest toward specification-critical status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Qatar and Kuwait demonstrate the highest price elasticity for commodity-grade polycarbonate sheet, while Saudi Arabia's automotive and medical-device sectors absorb feedstock-driven cost fluctuations with minimal demand destruction. Construction procurement teams across the Gulf Cooperation Council negotiate aggressively on standard multi-wall glazing specifications.
Saudi Arabia
SFDA biocompatibility protocols and sterilization-resistance standards govern medical-device-grade polycarbonate imports and local qualification pathways. The country's national pharmaceutical regulator enforces additive disclosure obligations that extend resin approval timelines for new suppliers. Yanbu and Jubail industrial cities concentrate feedstock-integrated resin production and captive downstream extrusion operations serving regional automotive assembly.
United Arab Emirates
MOHAP certification requirements for healthcare-grade polycarbonate create qualification barriers that favor established suppliers with existing regulatory dossiers. Dubai and Abu Dhabi construction corridors centralize procurement authority for stadium and transportation glazing packages through consolidated EPC contracts. The emirates' building codes under Gulf Standardization Organization harmonization specify polycarbonate glazing for thermal performance compliance in commercial envelopes.
Qatar
Stadium roofing and transportation hub projects specify solid and corrugated polycarbonate panels for durability under extreme solar loading and sand abrasion. The country's national standardization body implements REACH-equivalent chemical registration frameworks that tighten monomer traceability obligations for resin suppliers. Doha-based mega-project developers unbundle after-sales technical service from resin supply contracts, compressing supplier qualification cycles.
Kuwait
Infrastructure pipelines for educational and healthcare facilities specify multi-wall polycarbonate panels for daylighting and thermal insulation performance. The national construction regulator enforces energy-efficiency mandates that accelerate polycarbonate glazing specification across public sector projects. Kuwait City procurement teams leverage regional feedstock-integrated supply chains to minimize logistics exposure for large-format sheet deliveries.
Middle East Polycarbonate (PC) Market Competitive Landscape
Capability concentration sits with feedstock-integrated petrochemical complexes; scale advantage sits with downstream extrusion and compounding operations locked into localized sourcing networks. The market structure tiers into three strategic archetypes: Gulf-based resin producers with backward integration into crude derivatives, European and Asian specialty-grade suppliers competing on optical and medical certification, and regional compounders serving construction and automotive fabrication. Dominant competitive moves include capacity expansion at Yanbu and Jubail complexes and strategic partnerships between resin producers and EPC contractors for mega-project supply.
Among Gulf-based integrated producers, SABIC anchors feedstock-advantaged supply across Saudi Arabia's industrial corridor, while Borouge occupies a position serving high-performance infrastructure and automotive specifications through Abu Dhabi operations. Covestro AG represents the specialty-grade archetype, sustaining premium positioning on optical and medical-device-certified resin lines despite logistics costs from European production bases.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| LG Chem |
| Sumitomo Chemical Co., Ltd. |
| Teijin Limited |
| Mitsubishi Gas Chemical Company |
| BASF |
| Borouge |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
SABIC's Yanbu and Jubail complexes command feedstock-integrated resin supply across Saudi Arabia's industrial corridor, anchoring margin pools in captive downstream extrusion and compounding operations rather than commodity-grade spot trading.
Pricing Analysis
After-sales technical service bundling drives lifetime value for EPC contractors managing Saudi giga-projects and UAE mega-developments. Three-tier pricing structure across medical-device-certified, optical-grade, and commodity construction tiers separates SFDA-qualified resin from standard multi-wall sheet. Price differentiation hinges on certification depth and volume scale, with healthcare providers absorbing premium tiers while Qatar stadium procurement teams negotiate aggressively on standard specifications. Cost compression in commodity extruded sheet is intensifying because acrylic substitution in signage applications constrains polycarbonate pricing power.
Supply Chain Analysis
Extended payment terms from EPC contractors and supply-chain finance facilities are reshaping working capital requirements for regional compounders. Feedstock-integrated production draws from Saudi Arabia, the UAE, and Kuwait, with bisphenol A and phosgene derivatives resting on European phenol supply and regional crude differentials. Single-source vulnerability concentrates in SABIC's captive offtake allocations, creating qualification risk for extruders dependent on Jubail and Yanbu resin supply. Distribution runs through direct mill relationships with mega-project developers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East polycarbonate market sits in early-cycle expansion as energy-efficiency mandates under Gulf Standardization Organization building codes accelerate multi-wall sheet specification across commercial construction.
For Market Incumbents: Insulate margin pools by deepening backward integration into bisphenol A feedstock and securing captive offtake allocations for automotive tier-one clusters near Jubail. Acrylic substitution in cost-sensitive optical applications threatens commodity-grade positioning; counter through co-extrusion capability investments for nano-ceramic infrared-blocking layers that Dubai façade engineers now specify. For New Entrants and Emerging Players: Build out mechanical recycling and chemical depolymerization infrastructure to capture first-mover positioning in post-industrial and post-consumer polycarbonate collection networks. Medical-device-grade compounding with SFDA biocompatibility certification offers the most penetrable white-space target; pursue hospital system partnerships and GPO contract pathways as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional compounders with existing GCC regulatory dossiers and optical-grade cleanliness standards, as REACH-equivalent registration timelines extend qualification cycles for new suppliers. Long-term viability across the projection horizon rests on feedstock-advantaged positioning and certification depth; watch for inflection in photovoltaic integration demand as BIPV module manufacturers specify UV-stabilized polycarbonate front sheets for UAE solar parks.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | SABIC's Yanbu and Jubail complexes deepen feedstock integration into downstream extrusion. |
| Backward Integration | Regional compounders secure captive bisphenol A supply to compress margin exposure to phenol volatility. |
| Medical-Device Certification | SFDA and MOHAP qualification pathways unlock premium pricing tiers for healthcare-grade resin. |
| Co-Extrusion Technology Investment | Nano-ceramic infrared-blocking layers meet Dubai and Abu Dhabi solar heat gain coefficient specifications. |
| Recycling Infrastructure Buildout | Mechanical recycling ventures capture underdeveloped post-industrial collection networks across the Gulf. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPC procurement directors, automotive tier-one supplier plant managers, resin technical sales leads, and healthcare device assemblers. Secondary validation drew from Gulf Standardization Organization regulatory filings, customs and trade data for polycarbonate resin imports, SABIC and Borouge disclosure documents, and hospital procurement databases. Bottom-up volume modeling across grade tiers and end-use applications was triangulated against top-down petrochemical capacity assessments.
Calibration against historical resin price movements and construction project award volumes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user category, and technology platform. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization trajectories. Forecast inputs incorporated feedstock cost volatility assumptions and regulatory harmonization timelines under Gulf Standardization Organization frameworks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian specialty-grade suppliers or European optical resin producers would shift outcomes. Macroeconomic deviation in crude differentials, regulatory acceleration in chemical registration requirements, or technological disruption in photovoltaic front-sheet materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Molding and Trim Materials Market