
 Global VAE Emulsion Market | 2026-2036
Global VAE Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Global VAE Emulsion Market Foresight
Specialized polymer chemist availability is collapsing across Western Europe and North America, forcing emulsion producers to automate batch control systems or relocate technical centers. Wacker Chemie leverages its integrated vinyl acetate supply chain to sustain margin stability in European adhesive grades. Dow Chemical anchors North American construction coating demand through captive ethylene feedstock access. Celanese competes in Asia-Pacific textile binder applications with tailored low-formaldehyde VAE grades.
Vinyl acetate ethylene copolymer emulsion comprises 40-60% vinyl acetate and 15-30% ethylene by weight, polymerized via free-radical emulsion polymerization in aqueous medium to yield particles of 0.1-5.0 micrometers for film-forming adhesion and flexibility. The primary industrial purpose centers on water-based binding, coating, and laminating applications where solvent emission reduction meets performance requirements. Paints and coatings applications command the largest value pool due to architectural renovation cycles and OEM automotive primer demand, while adhesives segments exhibit the fastest structural expansion driven by packaging lamination and woodworking assembly shifts away from hot-melt alternatives. Emulsion polymerization technology dominates manufacturing economics through continuous reactor designs that minimize energy intensity versus bulk or suspension alternatives.
EPA TSCA Section 5 premanufacture notifications govern new VAE copolymer introductions in the United States, while REACH registration dossiers in Europe mandate full toxicological profiling for monomer residuals above 0.1% concentration. China's MEE enforces GB standards on volatile organic compound content in architectural coatings, directly constraining solvent-based competitor formulations and expanding VAE emulsion addressable market. Japan's METI chemical substance control law adds another compliance layer for producers serving electronics and consumer goods laminating segments. Stakeholders must monitor polymerization catalyst cost trajectories and bio-based vinyl acetate feedstock pilot projects to anticipate margin structure shifts.
Market Dynamics
Water-based formulation mandates across major industrial economies are compressing solvent-based coating and adhesive volumes, forcing raw material substitution toward vinyl acetate ethylene copolymers with lower volatile organic compound profiles.
Growth Catalysts
- EU Green Deal industrial decarbonization:REACH enforcement and F-Gas Regulation phase-downs eliminate solvent-based competitors in European architectural coatings, expanding VAE emulsion addressable demand.
- China's dual carbon goals:MEE GB standards on VOC content in construction materials mandate water-based systems for interior finishes and wood adhesives.
- Packaging lamination conversion:Food contact safety requirements and recycling compatibility needs displace solvent polyurethane adhesives with VAE-based alternatives in flexible packaging.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas price swings transmit directly to VAE copolymer production economics, compressing margin stability for non-integrated producers.
- Specialized polymer chemist scarcity:Western Europe and North America face collapsing availability of emulsion polymerization technologists, constraining batch optimization and new grade development.
- Hot-melt adhesive residual demand:High-speed packaging lines and moisture-sensitive applications retain solvent and reactive hot-melt systems, limiting VAE penetration in premium performance tiers.
Strategic Opportunities
- India construction chemicals underpenetration:BIS standards adoption and PLI scheme incentives for domestic chemical manufacturing create greenfield VAE emulsion demand in architectural adhesives and waterproofing membranes.
- Bio-based vinyl acetate pilot scaling:Renewable acetic acid and ethylene feedstock routes from agricultural waste streams offer carbon intensity reduction for sustainability-positioned coating brands.
- Digital formulation platforms:AI-driven emulsion property prediction and automated reactor control reduce development cycle time for customized textile binder and carpet backing grades.
Industry Challenges
- Emulsion polymerization scale-up complexity:Translating laboratory particle size distributions and glass transition temperatures to continuous reactor consistency demands rare process engineering expertise.
- Multi-jurisdiction registration burden:EPA TSCA Section 5 notifications, REACH dossier updates, and China's MEE chemical substance inventories create overlapping compliance timelines for new copolymer introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VAE Emulsion Market |
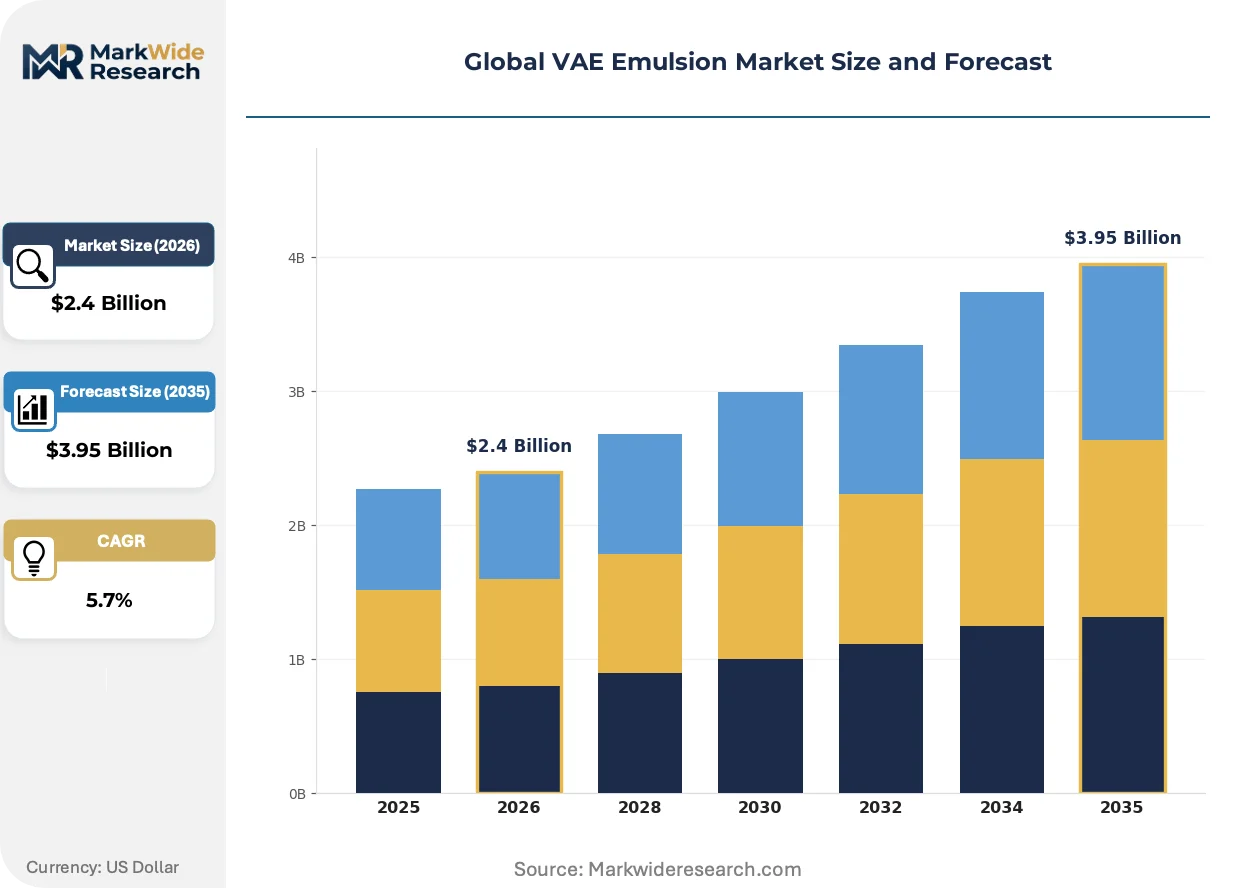
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Acetate Ethylene, Ethylene-Vinyl Acetate, Polyvinyl Acetate, Acrylic Emulsion, Styrene-Butadiene, Others Technology: Emulsion Polymerization, Suspension Polymerization, Bulk Polymerization, Solution Polymerization Application: Adhesives, Paints & Coatings, Textiles, Paper Coating, Construction, Leather Finishing End User: Building & Construction, Packaging, Consumer Goods, Personal Care, Industrial Manufacturing |
| Companies Covered | Wacker Chemie, Dow Chemical, BASF, Celanese, Sinopec, Eastman Chemical, Arkema, Sumitomo Seika, ICC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VAE Emulsion Market Shifts & Advancements
Polymer architecture innovation and regulatory chemistry restrictions are fragmenting traditional application boundaries, creating specialized VAE grades that trade off adhesion strength, flexibility, and environmental resistance for targeted end-uses.
Core-shell particle morphology engineering is fragmenting competitive positioning between commodity and specialty emulsion tiers. Manufacturers now synthesize vinyl acetate-rich shells around ethylene-dense cores to deliver controlled film formation for low-temperature coating application. Automotive OEM primer formulators in Germany and Japan adopt these structured particles to replace solvent-borne epoxy systems in corrosion-resistant base coats.
REACH authorization requirements for residual monomer content are tightening toxicological scrutiny across European adhesive and coating supply chains. ECHA dossier updates now mandate full exposure assessments for vinyl acetate residuals above 0.1 percent concentration in consumer-contact applications. Textile binder producers serving EU apparel brands are accelerating low-formaldehyde and ultra-low-VOC VAE grade certification to maintain retail channel access.
Buyer concentration among multinational coating and adhesive formulators is compressing supplier negotiation leverage and accelerating specification consolidation. Procurement teams at major European and North American construction chemical companies now mandate cradle-to-gate carbon footprint disclosures alongside traditional technical performance metrics. VAE emulsion producers with captive bio-based feedstock pilots or renewable energy-integrated polymerization assets capture preferred supplier status in sustainability-indexed tender processes.
Global VAE Emulsion Market Segmentation
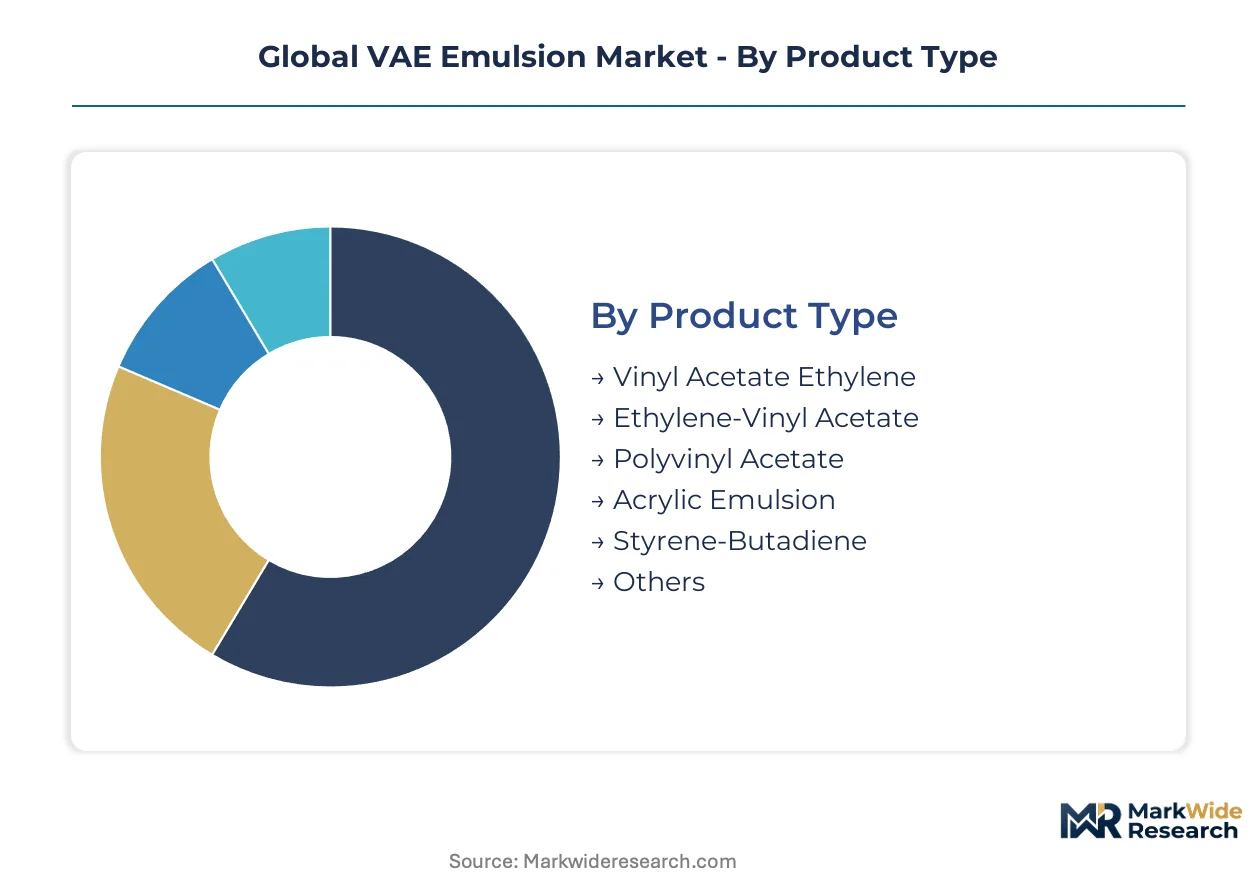
VAE emulsion segmentation reveals how regulatory chemistry restrictions and application-specific performance requirements fragment manufacturing strategies across copolymer architectures, polymerization technologies, and end-use specifications. Distinct formulation tiers emerge where REACH-mandated low-VOC grades command premium positioning against commodity construction adhesives.
Product Type:
REACH authorization thresholds and China's MEE GB standards on residual monomer content differentiate product tiers by toxicological compliance burden and feedstock integration economics.
- Vinyl Acetate Ethylene:Comprising 40-60% vinyl acetate and 15-30% ethylene by weight, this copolymer dominates water-based architectural coatings and packaging adhesives where EU Green Deal mandates eliminate solvent alternatives. German and Chinese construction chemical formulators specify this grade for interior finish applications requiring sub-0.1% residual monomer certification.
- Ethylene-Vinyl Acetate:Higher ethylene content (up to 40%) delivers enhanced flexibility and low-temperature film formation for automotive OEM primers and textile laminating. Japanese electronics manufacturers source this variant under METI chemical substance control law for consumer goods bonding applications demanding thermal stability.
- Polyvinyl Acetate:Homopolymer emulsions serve cost-sensitive woodworking adhesives and paper sizing where moisture resistance requirements remain moderate.
- Acrylic Emulsion:Competing water-based chemistry captures exterior architectural coatings requiring UV durability beyond VAE performance envelopes.
- Styrene-Butadiene:Synthetic rubber emulsions retain carpet backing and paper coating share through superior filler acceptance and binding economics.
- Others:Niche copolymers including vinyl versatate modifications address specialized waterproofing membrane specifications in European infrastructure projects.
Vinyl Acetate Ethylene handles the majority of throughput; Ethylene-Vinyl Acetate is the fastest mover on share.
Technology:
Capital intensity and batch consistency requirements concentrate production economics around continuous reactor designs versus batch alternatives.
- Emulsion Polymerization:Aqueous free-radical polymerization yielding 0.1-5.0 micrometer particles dominates manufacturing economics through energy-efficient continuous reactor operation. Dow Chemical and Wacker Chemie deploy this technology for North American and European construction adhesive supply.
- Suspension Polymerization:Bead-forming process serves high-molecular-weight grades for specialty adhesive applications where particle morphology control exceeds emulsion method capabilities.
- Bulk Polymerization:Solvent-free mass polymerization captures low-volume, high-purity grades for medical and food-contact laminating segments requiring minimal residual surfactant content.
- Solution Polymerization:Organic solvent-based process retains limited VAE production for hydrophobic coating modifications where aqueous compatibility is not required.
Emulsion Polymerization commands installed capacity; Bulk Polymerization is climbing the fastest as medical-grade specifications proliferate.
Application:
Formulation performance thresholds and VOC regulatory stringency segment demand by film-forming requirements and adhesion substrate compatibility.
- Adhesives:Packaging lamination and woodworking assembly applications displace solvent polyurethane systems with VAE-based alternatives meeting food contact safety and recycling compatibility needs. China's dual carbon goals accelerate this substitution in domestic flexible packaging supply chains.
- Paints & Coatings:Architectural renovation cycles and OEM automotive primer demand concentrate the largest value pool, with German and Japanese automakers adopting structured particle VAE grades for corrosion-resistant base coats replacing solvent-borne epoxy systems.
- Textiles:Low-formaldehyde binder grades for EU apparel brands require ECHA dossier compliance for vinyl acetate residuals above 0.1% concentration.
- Paper Coating:Surface sizing and pigment binding applications prioritize cost efficiency over performance differentiation in Asian printing paper manufacturing.
- Construction:Waterproofing membranes and tile adhesives in India's emerging BIS standards environment create specification expansion opportunities.
- Leather Finishing:Niche topcoat applications in Italian and Spanish tanneries demand specialized soft-handle film formation.
Paints & Coatings generates the dominant revenue share; Adhesives is gaining share fastest on packaging conversion momentum.
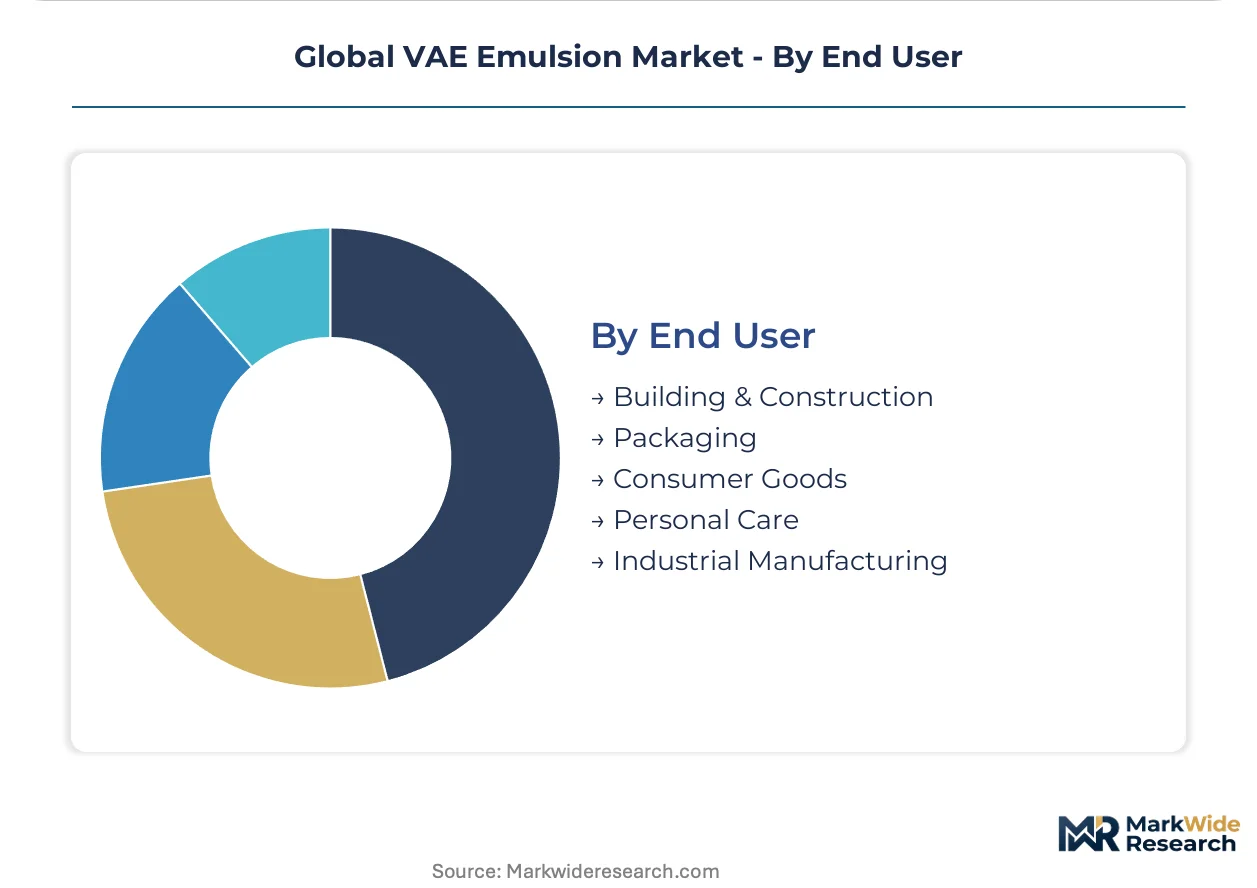
End User:
Procurement sophistication and sustainability indexing differentiate customer tiers between multinational specification consolidation and regional price competition.
- Building & Construction:Multinational construction chemical companies mandate cradle-to-gate carbon footprint disclosures alongside technical performance metrics, favoring VAE producers with renewable energy-integrated polymerization assets.
- Packaging:Food contact safety requirements and recycling compatibility specifications drive flexible packaging lamination demand, with major European and North American converters consolidating supplier bases around certified low-VOC grades.
- Consumer Goods:Electronics laminating and furniture assembly applications in Japan and South Korea require METI and MFDS chemical substance compliance layers.
- Personal Care:Cosmetic and hygiene product binding specifications demand pharmaceutical-grade residual control exceeding industrial adhesive standards.
- Industrial Manufacturing:Diverse OEM specifications for automotive, appliance, and industrial equipment coatings fragment procurement across performance tiers.
Building & Construction absorbs the greatest volume; Packaging is expanding most quickly on sustainability-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement of GB standards on VOC content in architectural coatings positions China as the dominant geography for VAE emulsion demand expansion. Regulatory chemistry restrictions in Europe and North America compress solvent-based alternatives while construction renovation cycles sustain volume absorption.
China
Packaging lamination and woodworking adhesive applications drive VAE emulsion consumption as domestic flexible packaging converters displace solvent polyurethane systems. MEE GB standards mandate water-based formulations for interior construction finishes. Yangtze River Delta chemical clusters around Shanghai host scaled emulsion polymerization capacity serving regional coating manufacturers.
Germany
Automotive OEM primer specifications and architectural coating renovation demand concentrate European VAE consumption. REACH authorization thresholds and EU Green Deal industrial decarbonization mandates eliminate solvent-borne competitors. Industrial chemical production concentrates in North Rhine-Westphalia and Bavaria where integrated producers leverage captive feedstock access.
United States
Construction adhesive formulators and architectural coating manufacturers absorb North American VAE volume amid EPA TSCA Section 5 governance of new copolymer introductions. IRA incentives for low-carbon building materials accelerate water-based system specification. Gulf Coast petrochemical corridors anchor ethylene feedstock integration for domestic emulsion production.
India
BIS standards adoption and PLI scheme incentives for domestic chemical manufacturing create greenfield demand in architectural adhesives and waterproofing membranes. Construction chemical underpenetration relative to per-capita developed market benchmarks offers expansion headroom. Gujarat and Maharashtra industrial corridors attract emulsion polymerization investment to serve regional coating formulators.
Japan
Electronics laminating and consumer goods bonding applications require METI chemical substance control law compliance for thermal stability specifications. Automotive OEM supply chains source specialized ethylene-vinyl acetate grades for corrosion-resistant primer systems. Kanto and Kansai industrial regions concentrate precision coating manufacturing for export-oriented electronics assembly.
Global VAE Emulsion Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in VAE emulsion manufacturing. Three structural archetypes define competitive positioning: petrochemical conglomerates with captive ethylene supply, diversified chemical specialists with polymerization technology depth, and regional producers serving construction chemical formulators with specification-tailored grades. Capacity expansion and backward integration into vinyl acetate monomer production represent the dominant competitive moves as feedstock volatility compresses margin stability for non-integrated participants.
Among European integrated chemical producers, Wacker Chemie and BASF occupy positions that exemplify feedstock-integrated competitive advantage, while Celanese represents the specialized copolymer technology archetype with tailored grade development capabilities. Dow Chemical anchors North American market presence through Gulf Coast petrochemical integration. These named entities serve as reference points for understanding how geographic feedstock access and regulatory compliance capabilities stratify competitive positioning across construction adhesive and coating supply chains.
| Leading Market Players |
|---|
| Wacker Chemie |
| Dow Chemical |
| BASF |
| Celanese |
| Sinopec |
| Eastman Chemical |
| Arkema |
| Sumitomo Seika |
| ICC Industries |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated petrochemical producers and construction chemical formulators lock in ethylene feedstock access while providing quarterly price visibility against crude oil indexation. This contract structure concentrates pricing power with Wacker Chemie and Dow Chemical, whose captive vinyl acetate supply insulates margins from spot monomer volatility that compresses non-integrated competitors.
Pricing Analysis
Contract-based long-term offtake dominates VAE emulsion procurement, with pricing stratifying across REACH-certified premium grades, standard industrial adhesives, and economy construction tiers. Price differentiation hinges on residual monomer certification levels and volume scale commitments, with multinational coating formulators commanding steepest discounts through consolidated tender processes. Cost compression in standard adhesive grades is intensifying because ethylene feedstock volatility transmits directly to copolymer economics. Regional construction chemical distributors exhibit highest price sensitivity, while automotive OEM primer specifications demonstrate least elasticity due to qualification barriers.
Supply Chain Analysis
Inventory cycles at Yangtze River Delta emulsion polymerization facilities run 4-6 weeks against just-in-time delivery commitments to European coating manufacturers. Geographic supply concentration centers on China, Germany, and the United States, where integrated producers anchor capacity. Manufacturing draws from vinyl acetate monomer, ethylene feedstock, and specialty surfactant packages. Single-source vulnerability in European vinyl acetate supply creates structural exposure to force majeure disruptions. Distribution runs through regional chemical distributors serving construction adhesive and coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VAE emulsion sits in early-cycle expansion as water-based formulation mandates across China, Europe, and North America displace solvent systems faster than polymerization capacity can fully respond.
For Market Incumbents: Compound feedstock integration advantages by accelerating backward integration into bio-based vinyl acetate pilot scaling, while automating batch control systems to offset collapsing polymer chemist availability in Western Europe. Celanese and Wacker Chemie should prioritize low-formaldehyde grade certification to defend against acrylic emulsion substitution in textile binder applications. For New Entrants and Emerging Players: Lead with specification-tailored grades targeting India's underpenetrated construction chemicals market, where BIS standards adoption and PLI scheme incentives create greenfield demand in waterproofing membranes and tile adhesives. Partner with Gujarat-based regional coating formulators to bypass multinational procurement consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap emulsion polymerization specialists with demonstrated continuous reactor expertise and existing REACH dossier compliance, positioned for acquisition by petrochemical conglomerates seeking technology depth. The inflection signal to monitor is sustained ethylene price volatility that forces non-integrated producers into distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate | Captive monomer supply insulates Wacker Chemie and Dow Chemical from feedstock volatility compressing competitor margins. |
| Continuous Reactor Automation | Automated batch control systems offset specialized polymer chemist scarcity constraining Western European and North American producers. |
| REACH-Certified Low-VOC Grade Development | ECHA dossier compliance for sub-0.1% residual monomer content secures preferred supplier status with EU apparel brands. |
| Bio-Based Feedstock Pilot Scaling | Renewable acetic acid routes from agricultural waste streams position producers for sustainability-indexed tender processes. |
| Regional Capacity Expansion in India | Gujarat and Maharashtra industrial corridors attract investment to serve domestic coating formulators under BIS standards adoption. |
Research Methodology
A standing panel of emulsion polymerization plant managers, procurement leads at construction chemical OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration across the primary research phase. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings, and MEE enforcement bulletins on GB standards. Bottom-up segment sizing triangulated against top-down macroeconomic absorption models.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation by copolymer grade tier, end-use industry, polymerization technology, and regional production hub. CAGRs derived from trend extrapolation of historical capacity utilization and forward-looking demand elasticity estimates, incorporating ethylene feedstock price trajectories and regulatory enforcement intensity as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement of VOC standards, stable ethylene supply economics, and continued REACH authorization stringency would require recalibration. Forecasts reflect documented assumptions on substitution rates and capacity expansion timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Bio-Polybutadiene Market