
 Polyethylene Furanoate Market | 2026-2036
Polyethylene Furanoate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Furanoate Market Intelligence
Beverage Industry procurement is collapsing toward bio-based bottle resins as carbonated soft drink and bottled water brands abandon conventional PET commitments. TOYOBO CO., LTD. leverages its polymerization expertise to anchor Japanese supply chains for high-purity PEF resins. Origin Materials sustains a distinct position through its proprietary biomass conversion platform that transforms wood residues into furan dicarboxylic acid feedstock. Avantium leads European commercialization via its YXY technology, controlling pilot-to-scale manufacturing pathways in the Netherlands.
Polyethylene Furanoate is a 100% bio-based polyester synthesized from furan-2,5-dicarboxylic acid and monoethylene glycol, exhibiting oxygen barrier properties approximately six times superior to conventional PET and enabling thinner-walled packaging designs. The polymer serves primarily as a drop-in replacement for fossil-derived polyesters in rigid packaging and technical textile applications where barrier performance and end-of-life biodegradability carry premium value. Bottles command the dominant product type position because beverage brands require scalable formats compatible with existing filling infrastructure, while Films represent the fastest-growing category as flexible food packaging converters test PEF's moisture and gas barrier advantages against multilayer incumbent structures. Resins concentrate margin pools at the upstream synthesis stage where proprietary catalyst systems and FDCA purity thresholds create defendable technology moats.
The European Chemicals Agency enforces REACH registration requirements for novel bio-based monomers, compelling PEF producers to complete full substance dossiers before commercial volume placement. The EU Green Deal's packaging and packaging waste regulation mandates recycled and renewable content thresholds that directly expand addressable demand for certified bio-based polyesters. The US FDA maintains food contact notification protocols that PEF resin suppliers must satisfy for beverage bottle approvals, creating a dual-track compliance burden for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions where bio-based content accounting rules and compostability certification standards remain unsettled.
Market Dynamics
Beverage brands are abandoning conventional PET commitments en masse, forcing resin suppliers to retool polymerization assets for bio-based furan chemistry. This demand-side pivot compresses development timelines and concentrates investment around FDCA synthesis pathways.
Growth Catalysts
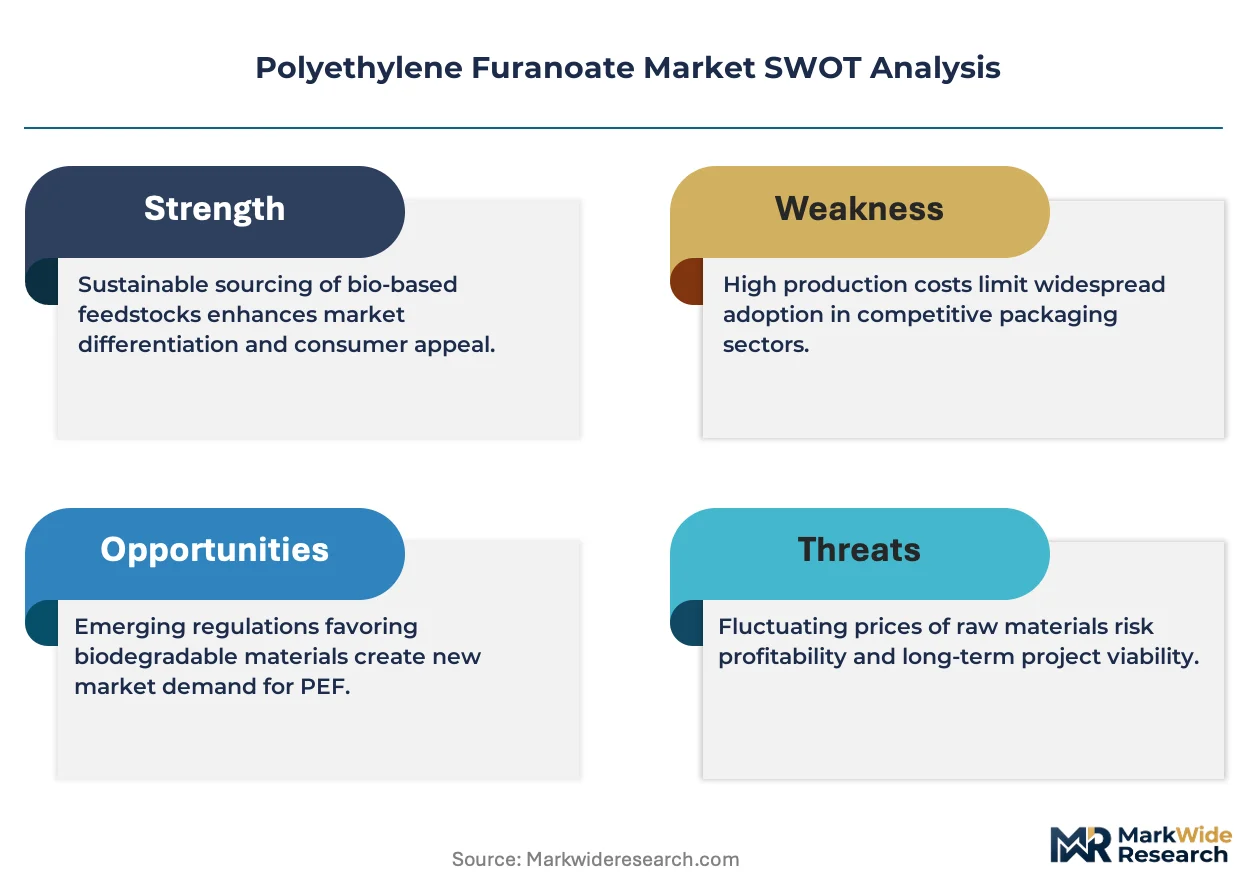
- EU Green Deal packaging mandates:Renewable content thresholds for rigid containers expand certified bio-based polyester procurement pools. German bottlers now specify PEF in technical tenders.
- Barrier performance premiums:Oxygen transmission rates six times lower than conventional PET enable thinner-walled bottle designs. Carbonated soft drink brands capture material cost savings.
- Netherlands chemical cluster density:Pilot-to-scale manufacturing infrastructure at Rotterdam-Antwerp corridor accelerates commercialization timelines for novel furan resins.
Market Restraints
- FDCA feedstock cost volatility:Fructose and C6 sugar price swings transmit directly to PEF resin economics. Agricultural commodity hedging remains underdeveloped.
- European synthesis concentration:Commercial-scale FDCA production clusters in the Netherlands and Belgium. Single-region dependency creates supply disruption exposure.
- REACH registration timelines:ECHA substance dossier requirements for novel bio-based monomers delay volume placement by 18-24 months.
Strategic Opportunities
- Japanese technical textile penetration:METI carbon-neutral material roadmaps prioritize bio-based polyesters for industrial fiber applications. Domestic converters seek drop-in PET replacements.
- US food contact notification pathway:FDA clearance for beverage bottle applications remains pending. First-mover resin suppliers capture brand qualification advantages.
- Flexible packaging film migration:Multilayer barrier structures face end-of-life disposal restrictions. PEF monolayer films displace incumbent EVOH-nylon laminates.
Industry Challenges
- Catalysis engineering talent scarcity:Proprietary FDCA synthesis requires rare organometallic chemistry expertise. European universities produce insufficient graduates.
- Compostability certification fragmentation:Industrial composting standards diverge between TÜV Austria, BPI, and Din Certco. Multi-jurisdiction brand rollouts require redundant testing.
- Legacy PET filling line adaptation:Stretch blow molding parameter windows differ for PEF. Converter retraining and equipment calibration consume operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Furanoate Market |
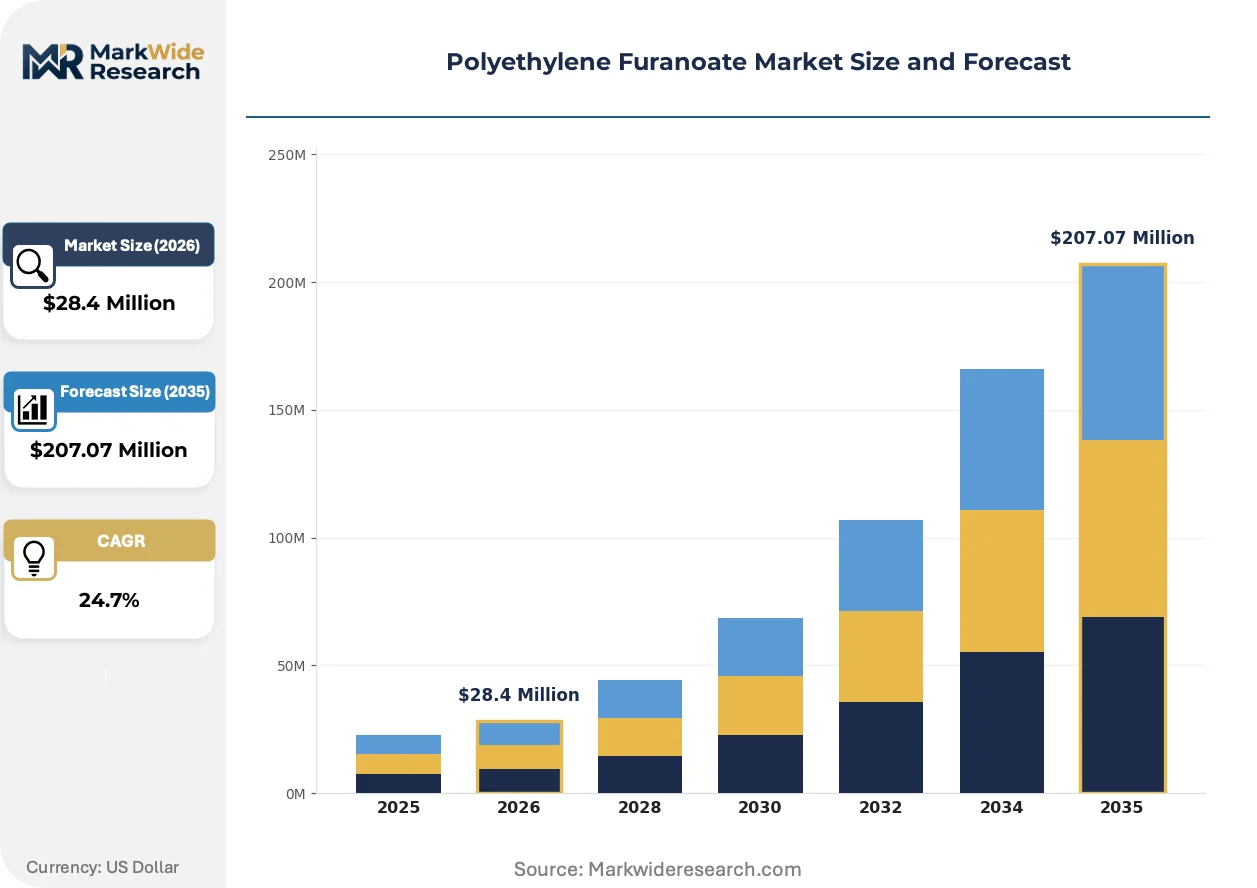
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $207.07 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Films, Fibers, Bottles Application: Packaging, Textiles, Automotive, Electronics End User: Food Industry, Beverage Industry, Consumer Goods, Industrial Sector Form: Granules, Sheets, Coatings, Pellets |
| Companies Covered | TOYOBO CO., LTD., Origin Materials, Avantium, Swicofil AG, BASF, ALPLA, AVA Biochem AG, Zhejiang Sugar Energy Technology Co., Ltd., Sulzer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Furanoate Market Strategic Shifts & Innovations
Biomass conversion platforms are maturing from pilot demonstrations to commercial-scale deployments, altering feedstock economics for bio-based polyesters. Three interconnected developments define this transition.
Catalytic oxidation of HMF to FDCA is displacing traditional petrochemical PTA routes in pilot installations. Beverage bottlers in Northern Europe now specify furan-based resins for premium product lines. This chemistry shift compresses the cost gap between bio-based and fossil-derived barrier polymers.
REACH registration requirements for novel bio-based monomers tightened substance dossier standards across the European Economic Area. ECHA now demands full toxicological profiles before commercial volume placement. Resin suppliers divert technical resources from R&D toward regulatory compliance, slowing formulation iteration cycles.
Brand sustainability procurement criteria now prioritize end-of-life biodegradability alongside carbon intensity metrics. Retail private-label bottled water programs in Germany and France specify certified compostable packaging. This specification cascade forces converters to qualify PEF alternatives ahead of multilayer incumbent structures.
Polyethylene Furanoate Market Segmentation
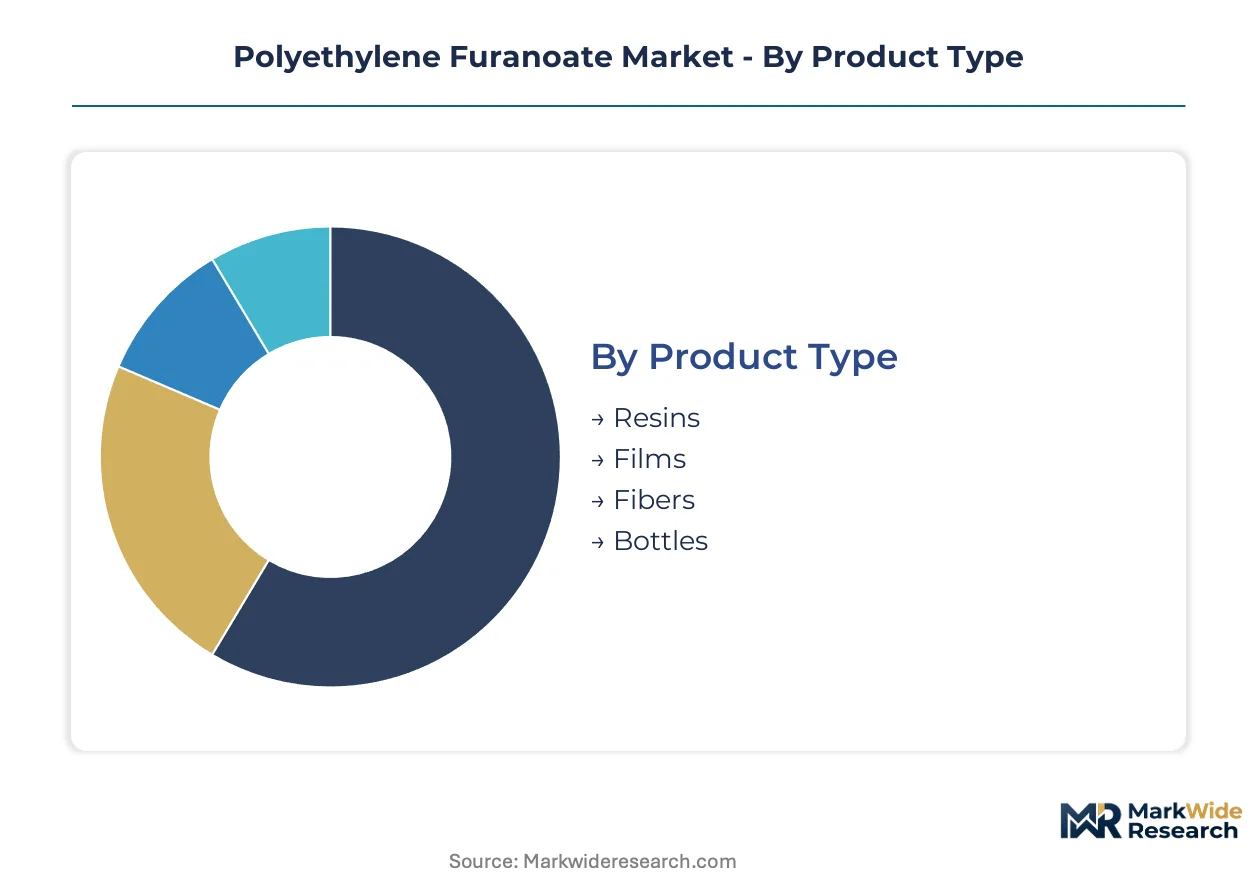
Segmentation reveals where PEF commercialization concentrates value capture. Each dimension exposes distinct margin architectures and competitive chokepoints.
Product Type:
Margin pools concentrate at the upstream synthesis stage where proprietary catalyst systems and FDCA purity thresholds create defendable technology moats.
- Resins:PEF resin production demands high-purity FDCA feedstock and specialized polycondensation equipment. Beverage bottlers in Germany and the Netherlands anchor procurement volumes as brands seek drop-in PET replacements for carbonated soft drink packaging.
- Bottles:Stretch blow-molded PEF bottles exploit six-fold oxygen barrier superiority over conventional PET, enabling thinner-wall designs. Technical tenders from Northern European bottlers now specify furan-based resins for premium product lines.
- Films:Monolayer PEF films displace multilayer EVOH-nylon laminates in flexible food packaging where end-of-life compostability carries premium value.
- Fibers:Technical textile applications leverage PEF's biodegradability profile for industrial fiber deployments under Japan's METI carbon-neutral material roadmaps.
Resins hold installed capacity. Films is rotating up the share rankings.
Application:
Volume concentration tracks regulatory pressure intensity across end-use sectors.
- Packaging:Rigid and flexible packaging converters drive PEF adoption under EU Green Deal mandates for renewable content thresholds. German and French retail private-label programs specify certified compostable bottle formats.
- Textiles:Industrial fiber applications in Japan prioritize bio-based polyester replacements for technical nonwovens and engineered fabrics.
- Automotive:Interior trim and under-hood components test PEF's thermal stability against incumbent bio-based polyamides.
- Electronics:Barrier films for flexible circuit substrates exploit PEF's moisture resistance in specialty coating applications.
Packaging dominates volume placement. Textiles is gaining share fastest.
End User:
Procurement authority concentrates with sustainability-mandated brand owners.
- Beverage Industry:Carbonated soft drink and bottled water brands abandon conventional PET commitments en masse. Northern European bottlers now specify PEF in technical tenders for premium product lines.
- Food Industry:Flexible packaging converters test PEF monolayer films against multilayer incumbent structures facing end-of-life disposal restrictions.
- Consumer Goods:Personal care and household product brands evaluate PEF bottles for shelf differentiation and circularity claims.
- Industrial Sector:Technical textile and specialty coating applications leverage PEF's barrier performance in non-packaging deployments.
Beverage Industry holds qualification pipelines. Food Industry is rotating up the share rankings.
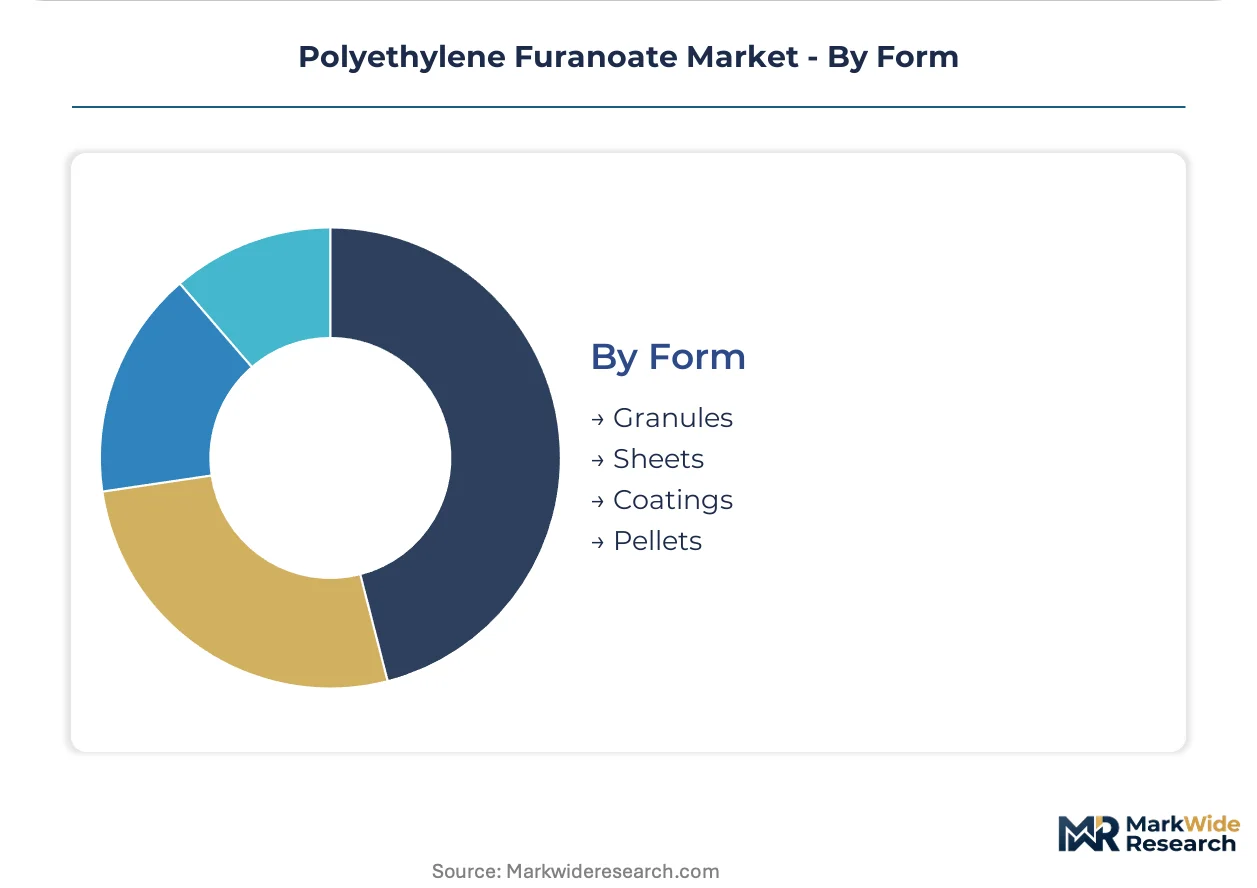
Form:
Processing economics favor formats compatible with existing converter infrastructure.
- Pellets:Standardized pellet form enables direct feed into conventional extrusion and injection molding equipment without material handling modifications.
- Granules:Larger particle size granules suit bulk resin handling systems at scale polymerization facilities.
- Sheets:Extruded sheet stock serves thermoforming operations for tray and clamshell packaging formats.
- Coatings:Solution-grade PEF enables barrier coating deposition via roll-to-roll processing for flexible substrate applications.
Pellets hold installed capacity. Coatings is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based Avantium ships pilot-scale PEF resins to German beverage bottlers under offtake agreements, establishing the Rotterdam-Antwerp corridor as the primary trade-flow channel for European bio-based polyester commercialization.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia specify PEF in technical tenders for carbonated soft drink packaging. The EU Green Deal's packaging waste regulation mandates renewable content thresholds that expand procurement pools for certified bio-based polyesters. Chemical clusters around Leverkusen and Ludwigshafen host converter networks retooling stretch blow molding lines for furan-based resin processing.
Netherlands
Avantium's YXY technology platform anchors pilot-to-scale manufacturing at the Chemelot industrial site in Geleen. ECHA REACH registration requirements for novel bio-based monomers enforce full substance dossiers before commercial volume placement. The Rotterdam port complex enables feedstock import logistics for fructose-derived FDCA precursors serving Northern European resin demand.
Japan
TOYOBO CO., LTD. leverages polymerization expertise to supply high-purity PEF resins for technical textile applications. METI carbon-neutral material roadmaps prioritize bio-based polyester replacements for industrial fiber deployments. The Nagoya chemical corridor hosts domestic converters testing drop-in PET alternatives for engineered fabric specifications.
United States
Origin Materials operates biomass conversion platforms transforming wood residues into furan dicarboxylic acid feedstock. FDA food contact notification protocols for beverage bottle applications remain pending, creating first-mover qualification advantages for cleared resin suppliers. The Pacific Northwest timber belt provides lignocellulosic biomass proximity for integrated FDCA production economics.
Belgium
Flexible packaging converters in the Flanders region test PEF monolayer films against multilayer EVOH-nylon laminates facing end-of-life disposal restrictions. The EU Green Deal's compostability certification standards drive specification cascades for certified biodegradable barrier materials. The Port of Antwerp handles bulk resin distribution to French and German food industry buyers.
Polyethylene Furanoate Market Key Industry Players
Listed leaders compete with private specialists across technology licensing and feedstock integration dimensions. The supplier base concentrates around three to five integrated players controlling FDCA synthesis pathways, with specialty chemical houses and packaging converters occupying downstream formulation tiers. Two strategic archetypes dominate: catalysis-focused technology licensors and biomass-integrated feedstock controllers. Competitive moves center on capacity expansion at Rotterdam-Antwerp corridor sites and strategic partnerships with Northern European beverage bottlers.
Within the technology licensor tier, Avantium and TOYOBO CO., LTD. exemplify divergent geographic anchoring strategies for furan chemistry commercialization. Origin Materials occupies a distinct position among feedstock-integrated players through its wood-residue biomass conversion platform. BASF represents the diversified chemical incumbent archetype, leveraging existing polyester polymerization infrastructure for bio-based resin line extensions. These three company types illustrate how competitive positioning stratifies between proprietary catalysis control and backward biomass integration.
| Leading Market Players |
|---|
| TOYOBO CO., LTD. |
| Origin Materials |
| Avantium |
| Swicofil AG |
| BASF |
| ALPLA |
| AVA Biochem AG |
| Zhejiang Sugar Energy Technology Co., Ltd. |
| Sulzer Ltd |
| Others |
Cost & Logistics Intelligence
EU REACH registration requirements for novel bio-based monomers gate both supply qualification timelines and price differentiation tiers simultaneously, as ECHA substance dossiers delay commercial volume placement while certified renewable content commands procurement premiums from sustainability-mandated beverage brands.
Pricing Analysis
Pilot-scale PEF resin generation commands price multiples over commercial-scale next-generation volumes, while incumbent fossil-derived PET sits at the prior-generation cost floor. Three-tier pricing structure across premium certified-bio-based, standard renewable-content, and economy fossil-derived tiers separates procurement pools. Price differentiation hinges on FDCA purity grades and EU Green Deal renewable content certification levels. Cost compression in standard-tier PEF is intensifying because fructose feedstock hedging instruments remain underdeveloped. Beverage Industry buyers exhibit highest price sensitivity due to thin carbonated soft drink margins, while technical textile converters in Japan accept premium positioning for carbon-neutral material roadmaps.
Supply Chain Analysis
Rotterdam-Antwerp corridor port infrastructure underwrites European PEF resin distribution, creating single-region chokepoint exposure for Northern European beverage bottlers. Commercial-scale FDCA production concentrates in the Netherlands and Belgium, with pilot facilities in Japan and the United States. Raw material dependencies center on fructose and C6 sugar streams for catalytic HMF oxidation, monoethylene glycol co-monomer supply, and proprietary organometallic catalyst systems. Single-source vulnerability runs through Netherlands-based synthesis clusters where ECHA regulatory delays compound supply disruption risks. Distribution runs through chemical converter networks at Leverkusen and Ludwigshafen hosting stretch blow molding line adaptations for furan-based resin processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for stretch blow molding parameter optimization and filling line calibration represent a recurring-revenue layer expanding faster than resin volume placement, as beverage converters demand operational bandwidth support alongside material supply.
For Market Incumbents: Secure backward integration into fructose-derived FDCA feedstock to defend margin position against agricultural commodity price volatility. Anchor catalyst engineering talent through partnerships with European universities where organometallic chemistry graduate pipelines remain insufficient. Prioritize REACH registration resource allocation to accelerate ECHA substance dossier timelines ahead of commercial volume competitors. For New Entrants and Emerging Players: Anchor in Japanese technical textile applications where METI carbon-neutral material roadmaps prioritize bio-based polyester replacements and domestic converter networks seek drop-in PET alternatives. Target flexible packaging film migration as multilayer EVOH-nylon laminates face EU Green Deal end-of-life disposal restrictions. Pursue toll manufacturing partnerships with Netherlands chemical cluster assets to bypass capital-intensive synthesis buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pilot-to-scale manufacturing transitions as Avantium-style YXY technology platforms achieve commercial replication. Long-term viability frames around five-to-ten-year renewable content mandate acceleration across EU packaging regulations. Acquisition targets should feature integrated biomass conversion platforms controlling lignocellulosic feedstock pathways. The signal to watch is FDA food contact notification clearance timing for beverage bottle applications, which will trigger brand qualification cascades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FDCA Feedstock | Origin Materials' wood-residue biomass conversion platform demonstrates captive supply economics insulating against fructose price volatility. |
| REACH Registration Acceleration | ECHA substance dossier completion timelines determine eighteen-to-twenty-four-month commercial volume placement advantages. |
| Technical Service Contract Expansion | Stretch blow molding parameter optimization services capture recurring revenue alongside resin supply relationships. |
| Japanese Textile Market Penetration | METI carbon-neutral roadmaps prioritize bio-based polyester replacements for industrial fiber specifications. |
| Flexible Packaging Film Qualification | Monolayer PEF films displace multilayer EVOH-nylon laminates under EU compostability certification mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage industry procurement directors, flexible packaging converter technical leads, FDCA synthesis plant managers, and EU regulatory affairs specialists. Secondary validation drew from ECHA REACH registration databases, EU Green Deal packaging waste regulation filings, SEC 10-K disclosures from listed chemical companies, and Cefic bio-based polyester trade flow reports. Bottom-up volume modeling triangulated against top-down addressable market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type tier, application end-use, beverage versus food industry buyer archetype, and regional chemical cluster concentration. CAGRs were derived from volume placement trajectories anchored to pilot-scale commercialization milestones and regulatory clearance timelines. Industry-specific forecast inputs incorporated fructose feedstock price correlation models and stretch blow molding line adaptation rates at German converter networks.
Material uncertainties — FDCA feedstock cost volatility, REACH registration timeline extensions, FDA food contact notification delays — sit outside the modeled envelope. Forecasts reflect assumptions around EU renewable content mandate enforcement intensity and brand sustainability procurement criteria evolution. Practitioners should keep alternative scenarios live as bio-based polyester certification standards and compostability protocols diverge between jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Casting Resin Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Orthophthalic Resins Market