
 Europe Expanded Polystyrene (EPS) Market | 2026-2036
Europe Expanded Polystyrene (EPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Expanded Polystyrene (EPS) Market Foresight
The EU Green Deal is recalibrating the cost-of-entry calculus for EPS suppliers targeting European construction markets. BASF SE leverages its integrated styrene monomer operations to secure feedstock continuity across German manufacturing sites. Sunpor Kunststoff GmbH anchors its position through specialized high-density block production serving alpine and Nordic thermal insulation specifications. TotalEnergies SE competes by extending its petrochemical network into circular EPS streams aligned with EU circular economy mandates.
Expanded polystyrene consists of rigid cellular plastic containing 98% air by volume, manufactured through suspension polymerization of styrene monomer followed by pre-expansion of polystyrene beads using pentane blowing agents. The material delivers thermal resistance values near 0.035 W/m·K, making it indispensable for building envelope insulation and protective packaging systems. Block and sheet configurations dominate volume throughput across European distribution channels, while moulded parts command premium positioning in automotive component trays and electronics protective housing. Density gradation from low through extra high categories stratifies margin pools, with medium and high density grades capturing disproportionate value in structural insulation applications where compressive strength requirements exceed 100 kPa.
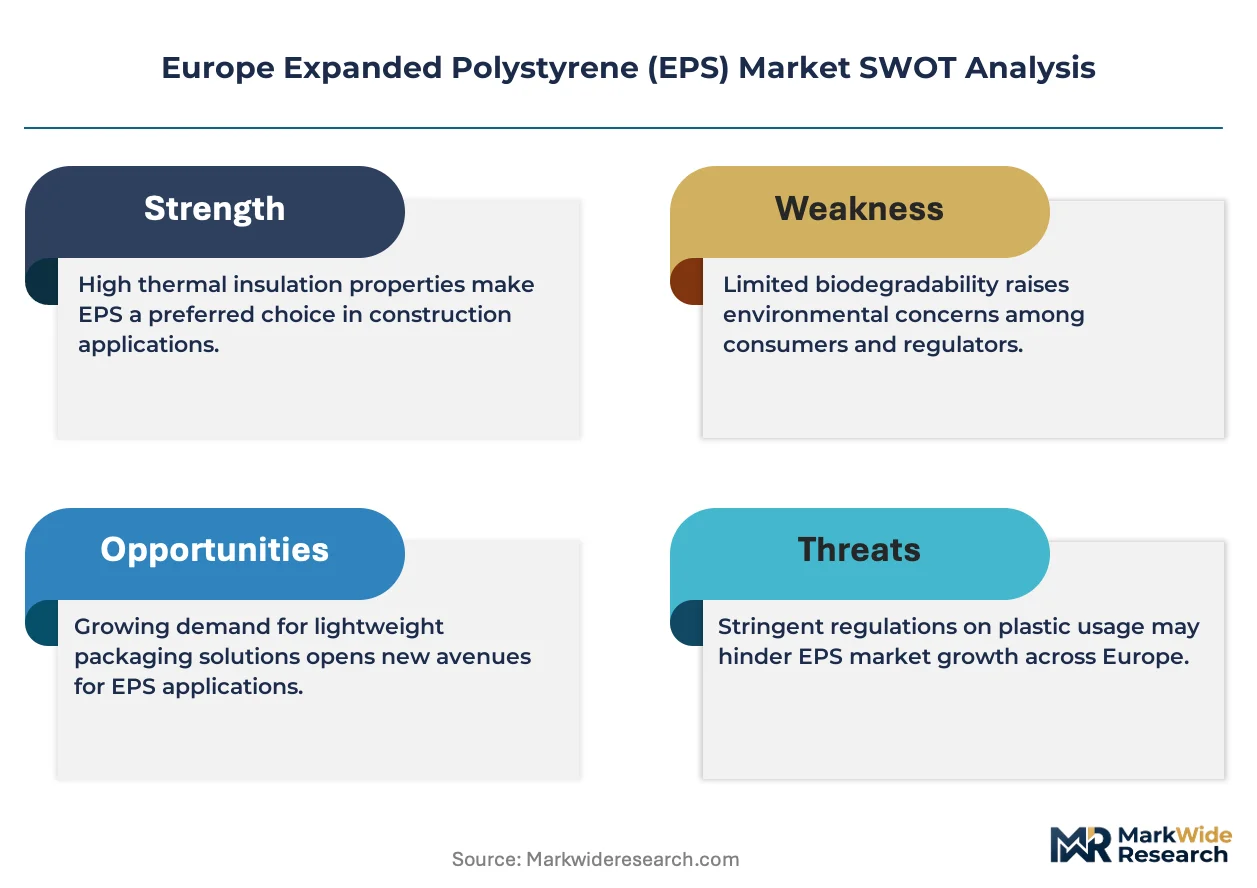
REACH compliance through ECHA and CE marking under the Construction Products Regulation govern material composition disclosure and fire performance classification across EU member states. The F-Gas Regulation indirectly shapes competitive dynamics by restricting alternative blowing agents, reinforcing pentane-based EPS formulations in European manufacturing. National building codes in Germany, France, and Poland are tightening U-value requirements for wall and roof assemblies, embedding EPS deeper into renovation specifications. Stakeholders must monitor the interplay between Ecodesign framework expansions and national transposition timelines to anticipate specification shifts before they harden into procurement mandates.
Market Dynamics
The EU Green Deal's building renovation targets are compressing specification timelines and forcing EPS suppliers to requalify products against tightening thermal performance thresholds before national procurement mandates lock in.
Growth Catalysts
- EU Green Deal renovation mandates:Binding targets for residential energy retrofits are pulling medium and high-density EPS into wall and roof assemblies across Germany, France, and Poland.
- Pentane blowing agent continuity:The F-Gas Regulation restricts hydrofluorocarbon alternatives, reinforcing the cost position of European EPS manufacturing against imported insulation substitutes.
- National recovery fund deployment:France and Italy are channeling public investment into residential insulation upgrades, concentrating near-term demand for thermal boards in these markets.
Market Restraints
- Styrene monomer price volatility:Feedstock costs tied to benzene-ethylene cracker output create margin compression for non-integrated EPS producers.
- Combustibility classification barriers:CE marking under the Construction Products Regulation imposes fire performance testing costs that disadvantage smaller compounders serving niche applications.
- Mineral wool substitution:Stone wool and glass wool insulation are capturing specification share in high-rise construction where stricter fire codes limit EPS penetration.
Strategic Opportunities
- Polish construction acceleration:EU cohesion fund absorption and residential building permits are outpacing Western European markets, creating capacity expansion incentives for block producers.
- Circular EPS stream development:EU circular economy mandates are opening collection and regranulation infrastructure gaps that integrated petrochemical networks can fill.
- Alpine and Nordic high-density specialization:Compressive strength requirements above 150 kPa for below-grade insulation are segmenting premium margin pools away from commodity grades.
Industry Challenges
- REACH dossier maintenance burden:ECHA substance evaluation updates require ongoing toxicological data submissions that strain regulatory affairs capacity at mid-scale manufacturers.
- Pre-expansion equipment retooling cycles:Pentane recovery system upgrades to meet volatile organic compound limits demand capital deployment amid uncertain retrofit subsidy continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Expanded Polystyrene (EPS) Market |
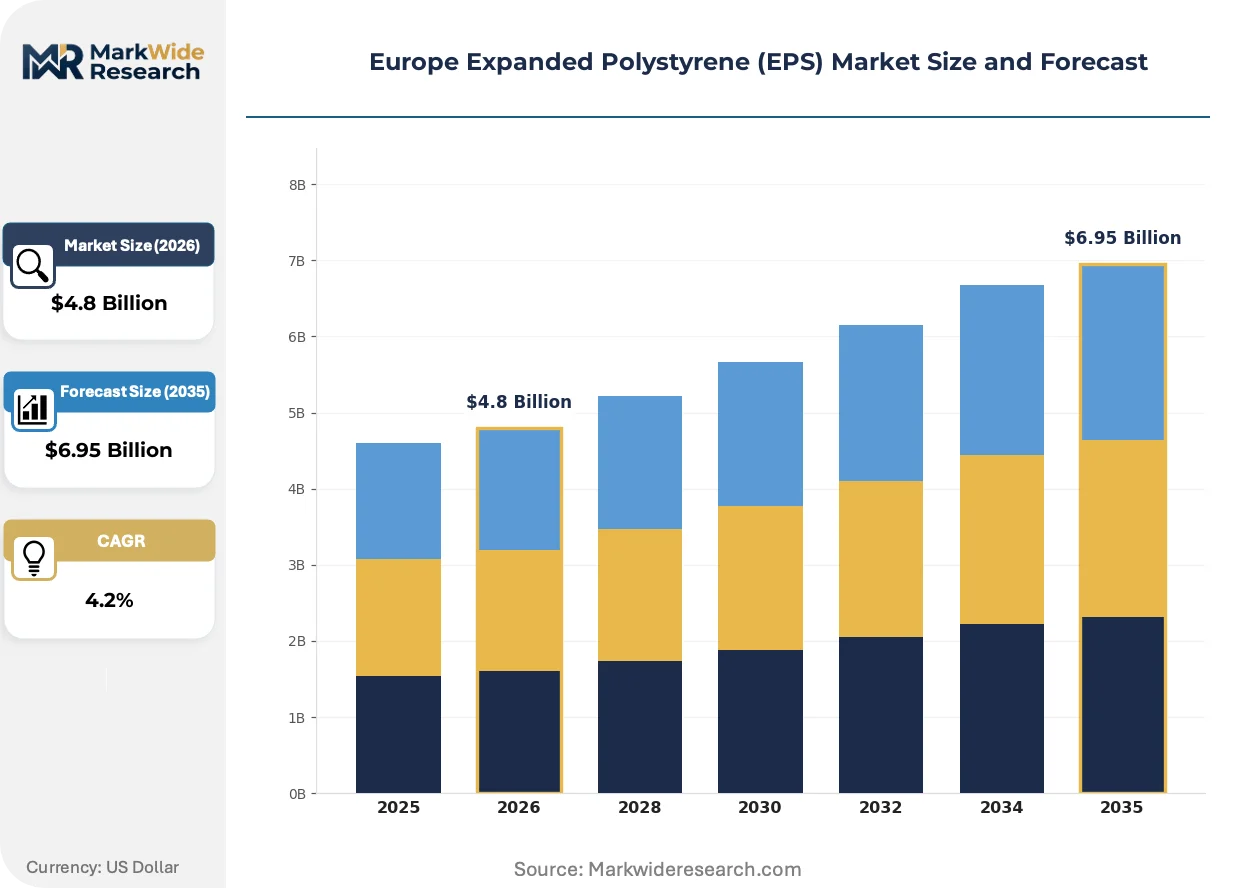
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blocks, Sheets, Beads, Moulded Parts End User: Construction, Packaging, Automotive, Electronics Density: Low Density, Medium Density, High Density, Extra High Density Application: Thermal Insulation, Void Fill, Cushioning, Lightweight Fill |
| Companies Covered | Sunpor Kunststoff GmbH, TotalEnergies SE, BASF SE, Ravago Group, Versalis S.p.A., BEWi ASA, Alpek S.A.B. de C.V., SABIC, Synthos S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Expanded Polystyrene (EPS) Market Shifts & Advancements
Automation of bead processing and tightening fire performance hierarchies are reconfiguring how EPS manufacturers compete on cost and specification compliance across European construction supply chains.
Advanced pre-expansion control systems is automating density consistency in block production, reducing material giveaway in high-volume thermal insulation grades. German and Austrian building envelope specialists are adopting these systems fastest, compressing acceptable tolerance bands from ±5% to ±2% in competitive tenders. This precision is automating the displacement of manual batch adjustment protocols and raising the capital threshold for new block manufacturing entrants.
The EU Green Deal's building performance standards are embedding lifecycle carbon metrics into public procurement criteria for insulation materials. Ecodesign framework expansions are forcing suppliers to disclose embodied carbon data before qualifying for national renovation subsidies. French and Italian social housing operators are responding earliest, inserting carbon footprint clauses into multi-year thermal board supply agreements.
Specification consolidation around density-performance bands is shortening the buying cycle for renovation contractors. Mid-size installers in Poland and Germany are shifting from project-by-project sourcing to annual framework agreements with compounders who stock certified grades. This consolidation is most visible in residential retrofit clusters where subsidy pre-approval timelines compress material ordering windows to four-week lead times.
Europe Expanded Polystyrene (EPS) Market Segmentation
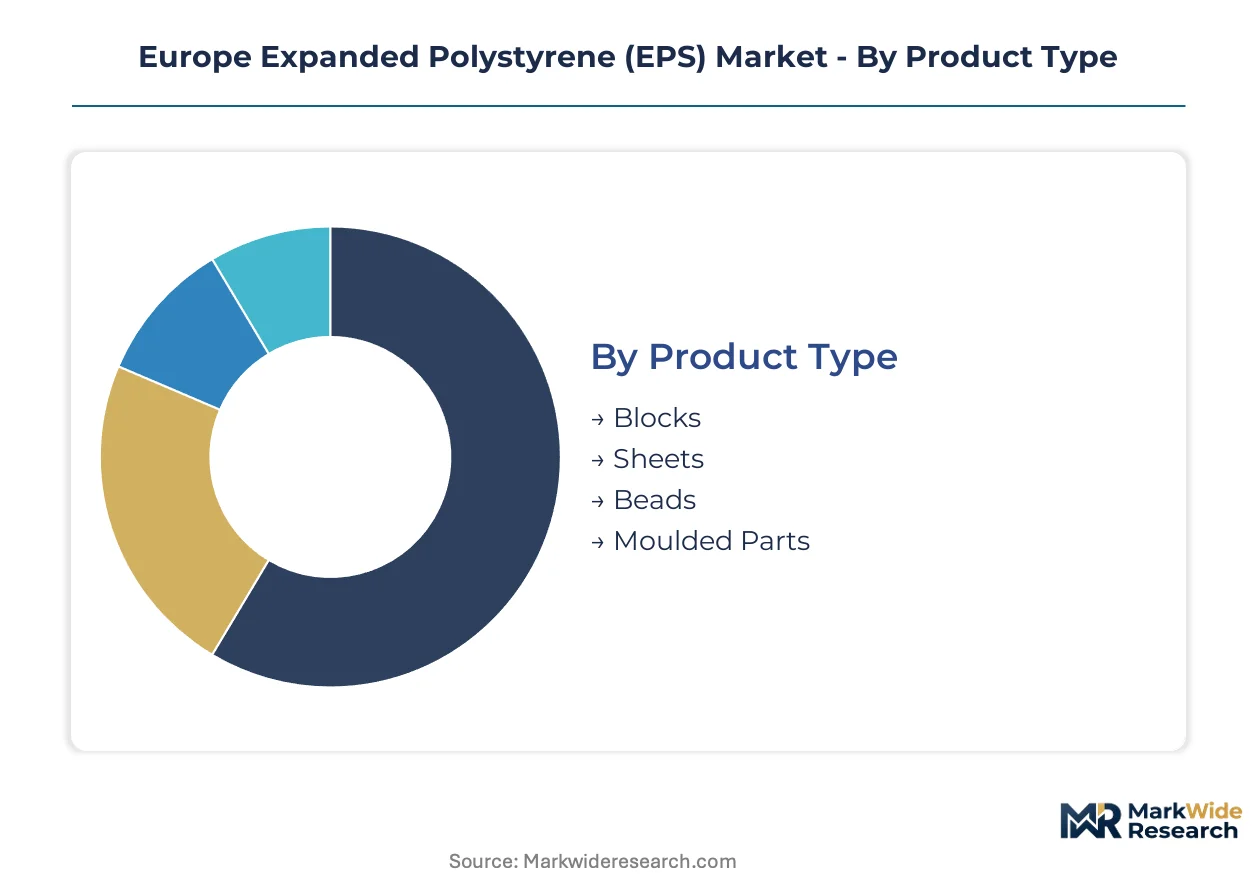
EPS product configurations stratify sharply between bulk thermal insulation formats and precision-moulded components, with density gradation determining compressive strength thresholds that lock suppliers into distinct specification tiers across European building codes.
Product Type:
Block and sheet formats serve standalone installation in building envelopes, while beads and moulded parts embed into downstream manufacturing processes or protective packaging systems.
- Blocks:Rigid cellular slabs manufactured through continuous pre-expansion and block moulding deliver thermal resistance values near 0.035 W/m·K for wall and roof assemblies. German and Polish construction markets absorb the highest block volumes as national renovation subsidies accelerate energy-efficient retrofits.
- Sheets:Cut from expanded blocks or extruded directly, sheet configurations enable rapid installation in timber-frame construction and flooring systems. French social housing operators specify certified sheet grades under tightening U-value mandates from the EU Green Deal.
- Beads:Pre-expanded polystyrene spheres serve as loose-fill insulation and lightweight concrete aggregate.
- Moulded Parts:Precision-shaped components protect automotive parts and electronics during transit.
Volume placements concentrate in Blocks; the faster expansion belongs to Moulded Parts.
End User:
Construction dominates absolute tonnage while packaging, automotive, and electronics segments compete on margin per kilogram and specification precision.
- Construction:Thermal insulation boards for residential and commercial building envelopes constitute the primary demand sink. France and Italy channel national recovery funds into residential upgrades, concentrating near-term procurement for medium and high-density grades.
- Packaging:Protective cushioning for consumer goods and industrial equipment leverages EPS shock absorption at low unit cost. Ecodesign framework expansions are forcing disclosure of embodied carbon data before qualification for public procurement.
- Automotive:Component trays and protective housings for assembly-line logistics.
- Electronics:Anti-static moulded packaging for semiconductors and precision instruments.
Construction captures the largest volume share; packaging climbs the fastest as e-commerce protective shipping demand intensifies.
Density:
Density bands segment the market into commodity insulation at the low end and structural load-bearing grades commanding premium positioning in below-grade and high-compression applications.
- Medium Density:Grades offering compressive strength between 70-150 kPa satisfy standard wall and roof insulation across German and Austrian building codes. Alpine and Nordic specifications increasingly require the upper bound of this range for frost protection.
- High Density:Formulations exceeding 150 kPa compressive strength enable below-grade insulation and heavy-load flooring systems. Polish infrastructure projects specify these grades for road embankments and railway substructures.
- Low Density:Lightweight grades for non-structural cushioning and void fill.
- Extra High Density:Specialized formulations for extreme load-bearing conditions in civil engineering.
Medium Density commands the broadest placement; High Density gains share fastest as below-grade building codes tighten across EU member states.
Application:
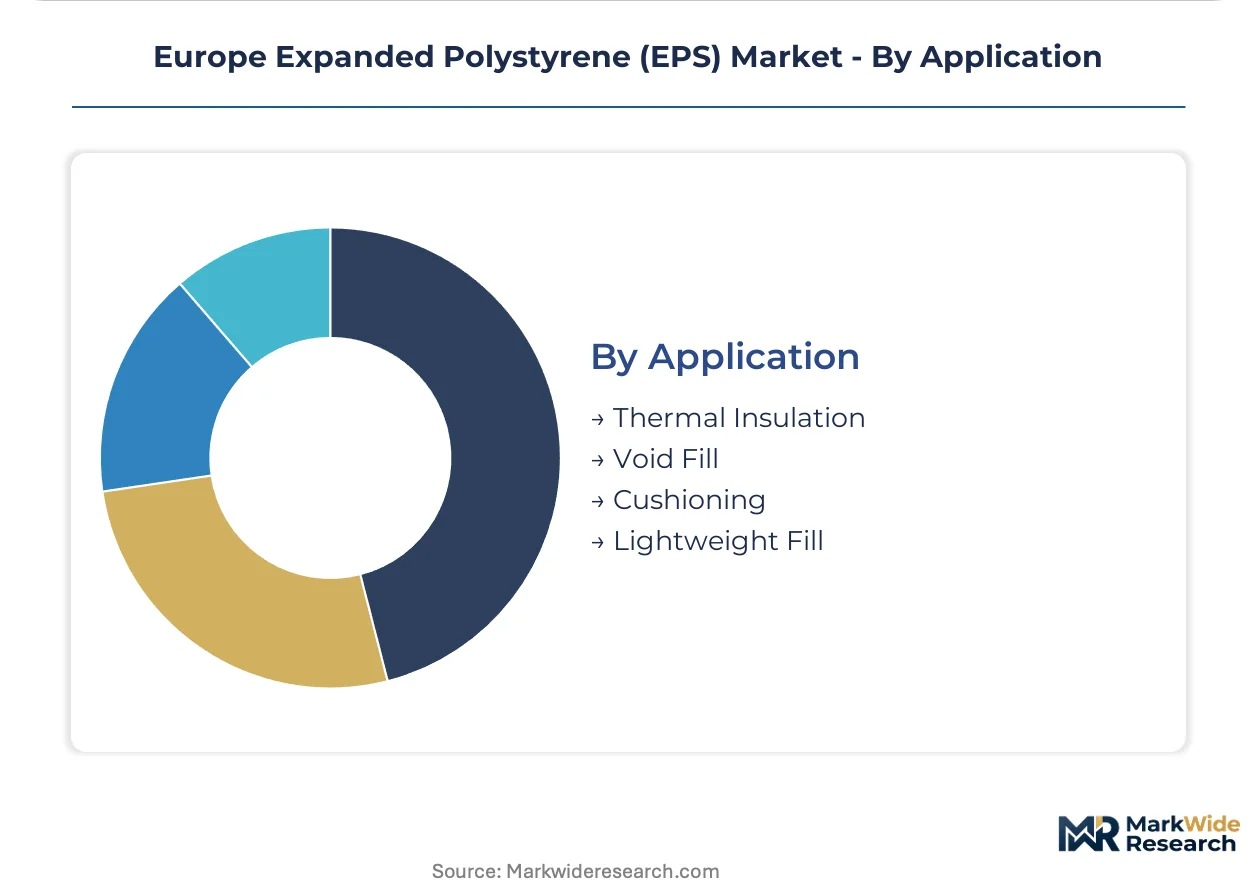
Application segments diverge between thermal performance mandates in construction and protective functional requirements in logistics and civil engineering.
- Thermal Insulation:Building envelope applications exploit EPS cellular structure containing 98% air by volume to achieve thermal resistance. CE marking under the Construction Products Regulation and national U-value requirements embed this application into renovation procurement mandates.
- Cushioning:Impact absorption for fragile goods in transit combines energy dissipation with low material cost. F-Gas Regulation restrictions on hydrofluorocarbon alternatives reinforce pentane-blown EPS cost positioning against substitute materials.
- Void Fill:Loose beads or pre-formed shapes eliminate empty space in packaging and construction cavities.
- Lightweight Fill:Geofoam applications reduce dead loads in embankments and retaining wall backfill.
Thermal Insulation anchors volume demand; Lightweight Fill expands most quickly as civil engineering specifications adopt cellular concrete alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Central and Eastern Europe are concentrating EPS block manufacturing capacity near raw material pipelines and export corridors. The EU Green Deal's renovation mandates are redistributing demand across member states with varying subsidy absorption rates and building stock ages.
Germany
Energy-efficient retrofit subsidies under the Federal Funding for Efficient Buildings program are accelerating specification upgrades to high-density thermal boards. The Construction Products Regulation's CE marking requirements enforce rigorous fire performance testing that favors established compounders with in-house laboratories. The Rhine-Ruhr industrial corridor hosts pre-expansion facilities serving renovation contractors across North Rhine-Westphalia and Hesse.
Poland
EU cohesion fund absorption for residential insulation is outpacing Western European markets, pulling medium-density block volumes into Warsaw and Kraków metropolitan construction zones. The national building code's tightening U-value requirements for wall assemblies are embedding EPS deeper into multi-family renovation specifications. The Silesian Voivodeship anchors manufacturing clusters with captive styrene supply from Płock petrochemical complexes.
France
MaPrimeRénov grant schemes are channeling national recovery funds into social housing insulation upgrades concentrated in Île-de-France and Auvergne-Rhône-Alpes. Ecodesign framework expansions are forcing embodied carbon disclosure before qualification for public procurement. Lyon-based building envelope specialists are consolidating annual framework agreements with compounders stocking certified medium-density grades.
Italy
Superbonus 110% tax incentives drove historic demand spikes for thermal insulation boards before program modifications compressed installation timelines. The Construction Products Regulation's harmonized standards govern fire classification acceptance across Lombardy and Veneto regional building departments. Milan-area distributors are shifting from project-by-project sourcing to bonded inventory arrangements with Austrian block producers.
Austria
Alpine building codes specifying compressive strength above 150 kPa for below-grade frost protection are segmenting premium margin pools toward specialized high-density block manufacturers. The F-Gas Regulation's pentane continuity reinforces domestic EPS cost positioning against imported mineral wool substitutes. Vorarlberg and Tyrol construction markets absorb disproportionate volumes of extra-high-density grades for mountain infrastructure.
Europe Expanded Polystyrene (EPS) Market Competitive Landscape
German producers anchor one tier; Austrian and Polish specialists hold differentiated positions in high-density and cost-optimized segments respectively. The vendor base stratifies between integrated petrochemical networks with captive styrene supply and independent compounders purchasing monomer on spot markets. Three archetypes dominate: backward-integrated chemical conglomerates, regional block manufacturing specialists, and circular-economy-focused reprocessors. Capacity expansion in Poland and strategic partnerships for recycling infrastructure represent the dominant competitive vectors.
Within the integrated chemical tier, BASF SE exemplifies backward-integrated positioning through its styrene monomer operations. Sunpor Kunststoff GmbH represents specialized high-density block production serving alpine thermal specifications. TotalEnergies SE occupies a position extending petrochemical networks into circular EPS streams aligned with EU mandates.
| Leading Market Players |
|---|
| Sunpor Kunststoff GmbH |
| TotalEnergies SE |
| BASF SE |
| Ravago Group |
| Versalis S.p.A. |
| BEWi ASA |
| Alpek S.A.B. de C.V. |
| SABIC |
| Synthos S.A. |
| Others |
Supply & Pricing Matrix
Benzene-ethylene cracker spreads cascading through European petrochemical networks segment EPS pricing into contract-indexed and spot-responsive tiers, with integrated producers capturing margin buffers unavailable to monomer-dependent compounders serving renovation contractors in Germany and Poland.
Pricing Analysis
Lead-time premiums compress as Polish and German contractors shift toward annual framework agreements with bonded inventory clauses, while spot purchasers absorb volatility from styrene monomer swings. Pricing stratifies across premium certified grades for public procurement, standard CE-marked blocks for residential retrofits, and economy loose-fill for packaging applications. Cost compression in medium-density thermal boards intensifies as Sunpor and BEWi expand block capacity near Silesian feedstock pipelines. Small-scale compounders serving alpine niche specifications exhibit lowest price sensitivity due to specification lock-in for compressive strength above 150 kPa.
Supply Chain Analysis
Single-source vulnerability sits with pentane blowing agent supply concentrated in Belgian and Dutch petrochemical corridors feeding pre-expansion facilities across the Rhine-Ruhr industrial cluster. Styrene monomer, pentane, and flame-retardant additives constitute the critical input trinity for European EPS manufacturing. Tariff exposure on imported benzene derivatives threatens margin structures for non-integrated producers in Italy and France. Distribution runs through regional building-material distributors holding consignment stock for renovation contractors, with direct mill relationships emerging among large Polish and German envelope specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive styrene supply and circular regranulation infrastructure represent the decisive upstream and downstream levers separating sustainable margin pools from commodity erosion.
For Market Incumbents: Anchor defensible positions through backward integration into styrene monomer or forward control of construction-channel distribution in high-growth Polish metropolitan zones. Mineral wool substitution in high-rise fire-code jurisdictions and REACH dossier maintenance burdens threaten mid-scale compounders lacking regulatory affairs scale. Prioritize certification investment for CE-marked high-density grades qualifying for French and Italian public renovation subsidies. For New Entrants and Emerging Players: Automated pre-expansion control systems enabling ±2% density tolerance present a technology-first wedge into German and Austrian competitive tenders displacing manual batch protocols. White-space targets concentrate in Polish civil engineering lightweight-fill applications and circular-EPS collection infrastructure gaps across France and Italy. Pursue equipment-leasing partnerships with regional distributors to bypass capital-intensive block-moulding facility requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Polish block producers with cohesion-fund order backlogs but strained working capital from styrene price volatility. Long-term viability hinges on positioning within EU circular economy mandates where integrated regranulation capabilities compound competitive moats. Watch Ecodesign framework expansion timelines as the inflection signal for embodied-carbon disclosure requirements reshaping qualification criteria for national subsidy programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | BASF's captive supply model insulates margin compression from benzene-ethylene cracker volatility across German manufacturing sites. |
| High-Density Block Capacity Expansion | Polish infrastructure specifications for compressive strength above 150 kPa redirect investment toward Silesian Voivodeship production clusters. |
| Circular EPS Collection Infrastructure | EU circular economy mandates open regranulation gaps that TotalEnergies' petrochemical network can fill through dedicated collection partnerships. |
| CE Marking Fire Performance Certification | Construction Products Regulation testing costs disadvantage smaller compounders, consolidating specification share among established laboratories. |
| Annual Framework Agreement Structuring | French social housing operators bind Lyon-based envelope specialists to multi-year thermal board supply with carbon footprint disclosure clauses. |
Research Methodology
Multi-period observation of styrene monomer pricing spreads, EU cohesion fund absorption rates, and national building permit volumes anchored the trend analysis, supplemented by interviews with plant managers at German and Polish block manufacturing facilities, procurement leads at French social housing operators, distribution channel partners in Italian Lombardy, and technical R&D directors specializing in pre-expansion automation. Secondary validation drew from Cefic chemical industry reports, Eurostat construction statistics, ECHA substance evaluation updates, and national recovery fund deployment disclosures. Bottom-up volume estimates from facility-level capacity utilization triangulated against top-down demand projections from renovation subsidy program budgets.
Input-output matrices mapping styrene monomer supply through pre-expansion, block moulding, and distribution stages generated segment-level value projections across the analysis window. Segmentation dimensions modeled include density grade tier, end-use application across construction and packaging, product configuration format, and regional production hub clustering. CAGRs emerged from curve-fitting historical volume trajectories against policy-mandated renovation targets and infrastructure investment cycles. Industry-specific forecast inputs incorporated REACH compliance cost trajectories and F-Gas Regulation continuity assumptions for pentane blowing agent formulations.
Several conditions sit outside the modeled scope, including abrupt modifications to French Superbonus or German Federal Funding for Efficient Buildings subsidy rates, unforeseen ECHA substance restriction listings affecting flame-retardant additives, and geopolitical disruptions to benzene-ethylene feedstock flows through Rotterdam-Antwerp pipeline corridors. Forecasts embed assumptions about EU Green Deal building renovation target continuity and national transposition timelines for Ecodesign framework expansions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Global Alpha Olefins Market