
 Molding and Trim Materials Market | 2026-2036
Molding and Trim Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Molding and Trim Materials Market Foresight
Residential renovation contractors is redrawing procurement patterns away from traditional new-build developers. Flex-N-Gate Corporation leverages its automotive-grade extrusion expertise to transfer precision molding capabilities into architectural trim applications. Saint-Gobain anchors European supply through specialized glass-reinforced and polymer-composite profile lines. Magna International competes by extending lightweight materials science from vehicle interiors into commercial building finishes.
Molding and trim materials encompass shaped profiles fabricated from wood, PVC, polystyrene, MDF, and engineered composites, produced through extrusion, injection molding, or CNC machining to provide decorative transitions, edge protection, and surface finishing in built environments. PVC dominates volume in moisture-prone commercial applications due to dimensional stability and lower maintenance burden, while engineered and pre-finished product forms capture expanding margin pools as contractors seek labor-saving installation. MDF maintains strength in residential interiors where paint-grade finishes predominate, though CARB-compliant and NAF-certified variants now command specification preference.
EPA TSCA Title VI formaldehyde standards, California CARB ATCM regulations, and EU REACH chemical restrictions collectively constrain adhesive formulations and resin systems across the supply base. These frameworks elevate compliance costs for commodity producers while creating market access advantages for certified low-emission manufacturers. Stakeholders must monitor evolving state-level adoption of CARB-equivalent standards and the trajectory of bio-based binder technologies that could reset material cost structures.
Market Dynamics
Residential renovation contractors now drive specification authority, redirecting procurement flows away from traditional new-build developers as homeowners prioritize aesthetic upgrades over full rebuilds. This structural power shift compresses order cycles and elevates demand for pre-finished, labor-saving profiles that reduce on-site installation time.
Growth Catalysts
- EPA TSCA Title VI formaldehyde standards:The regulation accelerates specification of low-emitting MDF and engineered wood products, creating market access advantages for certified manufacturers over commodity suppliers.
- Sun Belt metropolitan construction clusters:Phoenix, Houston, and Atlanta outpace national remodeling averages, concentrating demand for moisture-resistant PVC and composite trim in high-humidity climates.
- Pre-finished product adoption:Paint-grade-ready profiles eliminate on-site finishing labor, appealing to contractor segments facing skilled painter shortages and compressed project timelines.
Market Restraints
- Resin input cost volatility:Urea-formaldehyde and phenolic adhesive prices fluctuate with natural gas and methanol markets, squeezing margins for commodity MDF producers.
- Supply concentration in Southeast Asian petrochemical feedstocks:PVC resin production clusters in Thailand and Vietnam create geographic vulnerability for North American extrusion-dependent manufacturers.
- Dimensional stability limitations of solid wood:Natural expansion-contraction cycles restrict specification in commercial buildings with strict HVAC tolerance requirements.
Strategic Opportunities
- CARB Phase 2 equivalent standards adoption:Northeastern and Midwestern states implementing California-aligned emission rules create first-mover advantage for NAF-certified product lines.
- 3D printing convergence with CNC machining:Hybrid fabrication enables mass-customized architectural profiles for historic restoration and bespoke residential applications.
- Direct-to-contractor digital channels:E-commerce platforms bypass traditional distributor markups, capturing margin in the professional renovator segment.
Industry Challenges
- CNC programming talent scarcity:Complex profile geometries require specialized CAD-CAM operators, constraining capacity expansion at mid-sized fabrication facilities.
- Multi-certification timeline compression:Simultaneous EPA, CARB, and FSC chain-of-custody audits extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molding and Trim Materials Market |
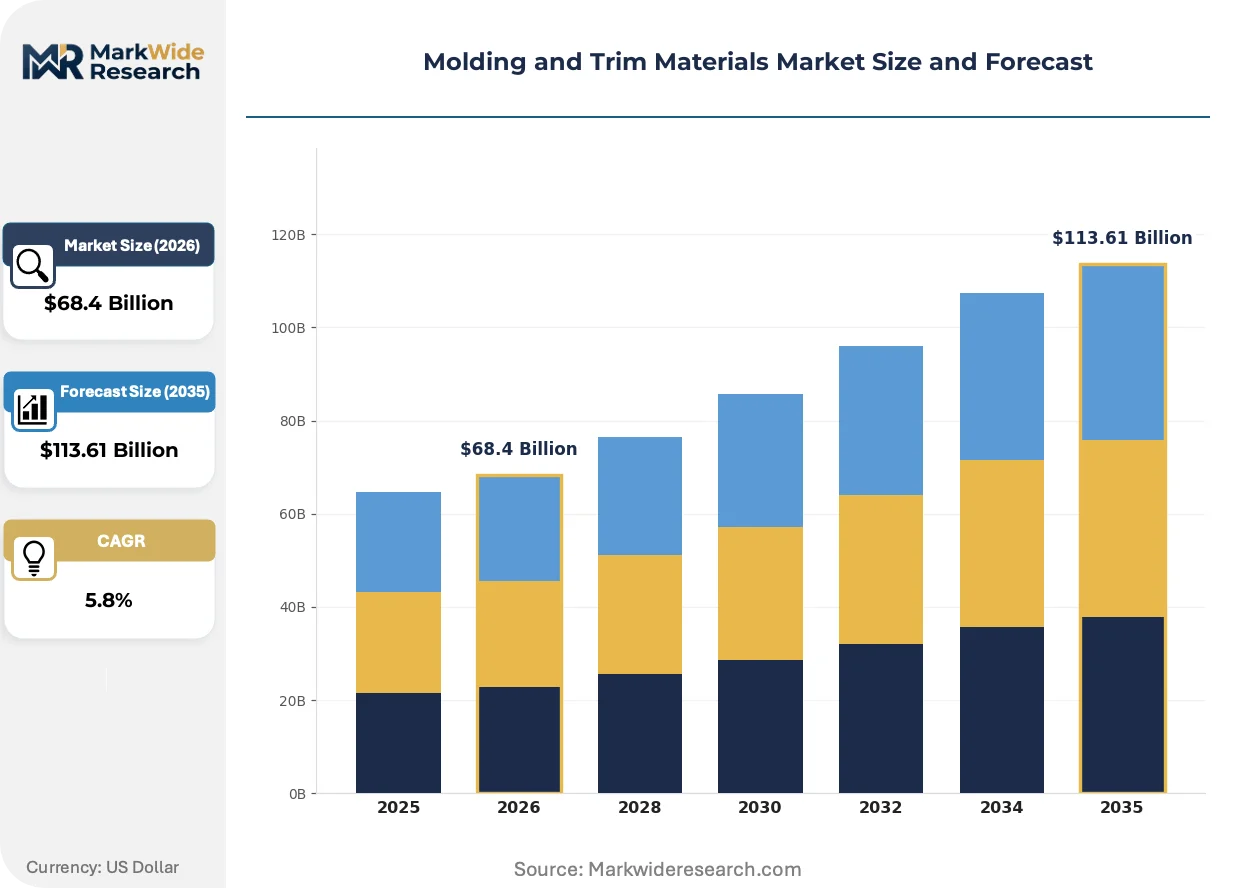
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, PVC, Polystyrene, MDF Application: Residential Interiors, Commercial Spaces, Renovation, New Construction Product Form: Pre-finished, Raw, Engineered, Custom Finish Type: Painted, Stained, Laminated, Textured |
| Companies Covered | Flex-N-Gate Corporation, Forvia SA, Saint-Gobain, Toyoda Gosei, Aisin Corporation, Magna International, Samvardhana Motherson Group, Associated Materials, Plastic Omnium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molding and Trim Materials Market Shifts & Advancements
Digital fabrication and low-emission chemistry are converging to reshape how architectural profiles are specified, produced, and installed. These shifts compress traditional supply hierarchies while elevating performance standards across residential and commercial end-uses.
Glass-reinforced polymer composite extrusion is fragmenting the moisture-prime commercial segment. Facility managers in healthcare and hospitality specify these profiles for wash-down durability. The technology compresses PVC's historical dominance in high-humidity applications while enabling thinner wall sections that reduce freight costs.
California CARB ATCM Phase 2 enforcement is tightening adhesive formulation standards across North American MDF supply. Manufacturers reformulate with soy-based and PMDI binders to maintain market access. Paint-grade residential interiors face the steepest compliance cost escalation, accelerating specification migration toward pre-finished alternatives.
Professional renovators now consolidate purchasing through contractor-exclusive digital platforms. Traditional two-step distribution through lumberyards loses specification influence in the single-family remodeling channel. Sun Belt metropolitan contractors lead this behavioral shift, leveraging same-day delivery networks to compress project material lead times.
Molding and Trim Materials Market Segmentation
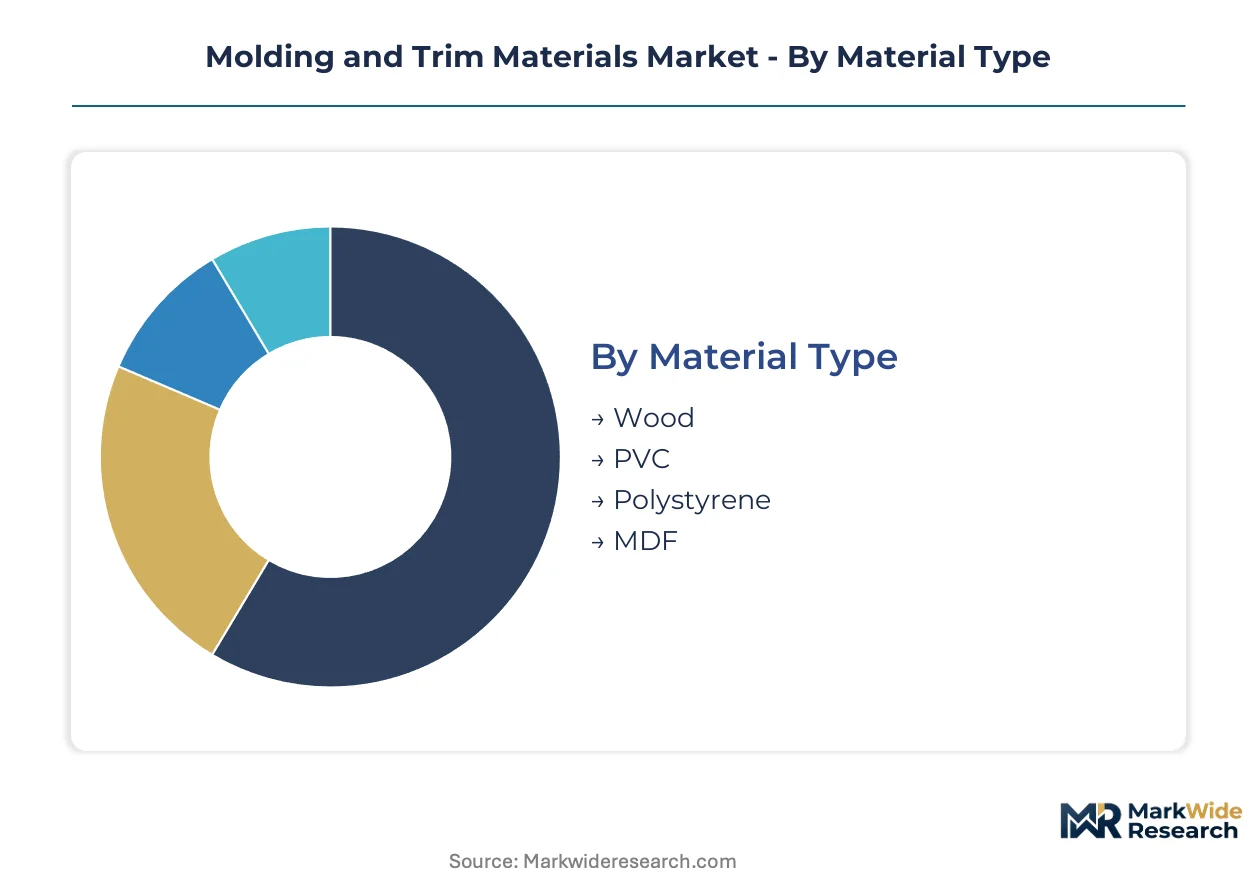
Molding and trim materials fragment across material chemistry, installation context, and finishing requirements. Each segmentation axis carries distinct regulatory exposure and margin architecture that shapes supplier positioning.
Material Type:
EPA TSCA Title VI formaldehyde standards and California CARB Phase 2 compliance create divergent compliance burdens across substrate categories, elevating certified low-emission variants while penalizing commodity formulations.
- Wood:Solid hardwood and softwood profiles retain specification in heritage restoration and premium residential applications where natural grain aesthetics command price premiums. Demand concentrates in New England and Pacific Northwest metropolitan areas where historic preservation codes restrict synthetic substitutes. Dimensional instability during humidity cycling limits commercial HVAC-controlled environments.
- PVC:Chlorinated polymer extrusions deliver moisture immunity and dimensional stability for high-humidity commercial interiors. Sun Belt healthcare and hospitality facilities specify PVC baseboards and casing in wash-down environments. Southeast Asian resin concentration creates supply vulnerability for North American extruders.
- Polystyrene:Expanded and extruded foam profiles serve lightweight decorative applications where cost minimization dominates specification.
- MDF:Medium-density fiberboard dominates paint-grade residential interiors through machinability and surface uniformity. NAF-certified and CARB-compliant variants now command procurement preference as emission standards tighten.
Established volume favors MDF; emerging adoption favors PVC.
Application:
Customer type now dictates procurement rhythm more than project scale, with renovation contractors compressing order cycles compared to traditional new-build developers.
- Residential Interiors:Single-family and multifamily dwelling trim specifications prioritize paint-grade finishes and rapid installation. Pre-finished profiles eliminate on-site painter dependency.
- Commercial Spaces:Healthcare, hospitality, and office facilities specify moisture-resistant materials with wash-down durability. Glass-reinforced composites fragment PVC's historical dominance in this segment.
- Renovation:Existing structure retrofit work now drives specification authority, redirecting procurement flows toward labor-saving profiles that reduce on-site installation time.
- New Construction:Greenfield residential and commercial development maintains volume concentration but loses influence over material selection to renovation channels.
Renovation channels are climbing the fastest; new construction maintains volume concentration.
Product Form:
Supply chain configuration separates captive fabrication from distributed finishing, with pre-finished alternatives capturing margin through labor substitution.
- Pre-finished:Factory-applied coatings eliminate on-site finishing labor and painter scheduling constraints. Contractors facing skilled trades shortages specify these profiles to compress project timelines.
- Raw:Unfinished substrates require field finishing, retaining cost advantage where labor arbitrage remains viable.
- Engineered:Composite and laminated constructions combine substrate performance with surface durability for demanding commercial environments.
- Custom:CNC-machined bespoke profiles serve historic restoration and architect-specified residential applications where standard catalogs prove insufficient.
Pre-finished products gain specification share fastest; raw forms retain cost-sensitive volume.
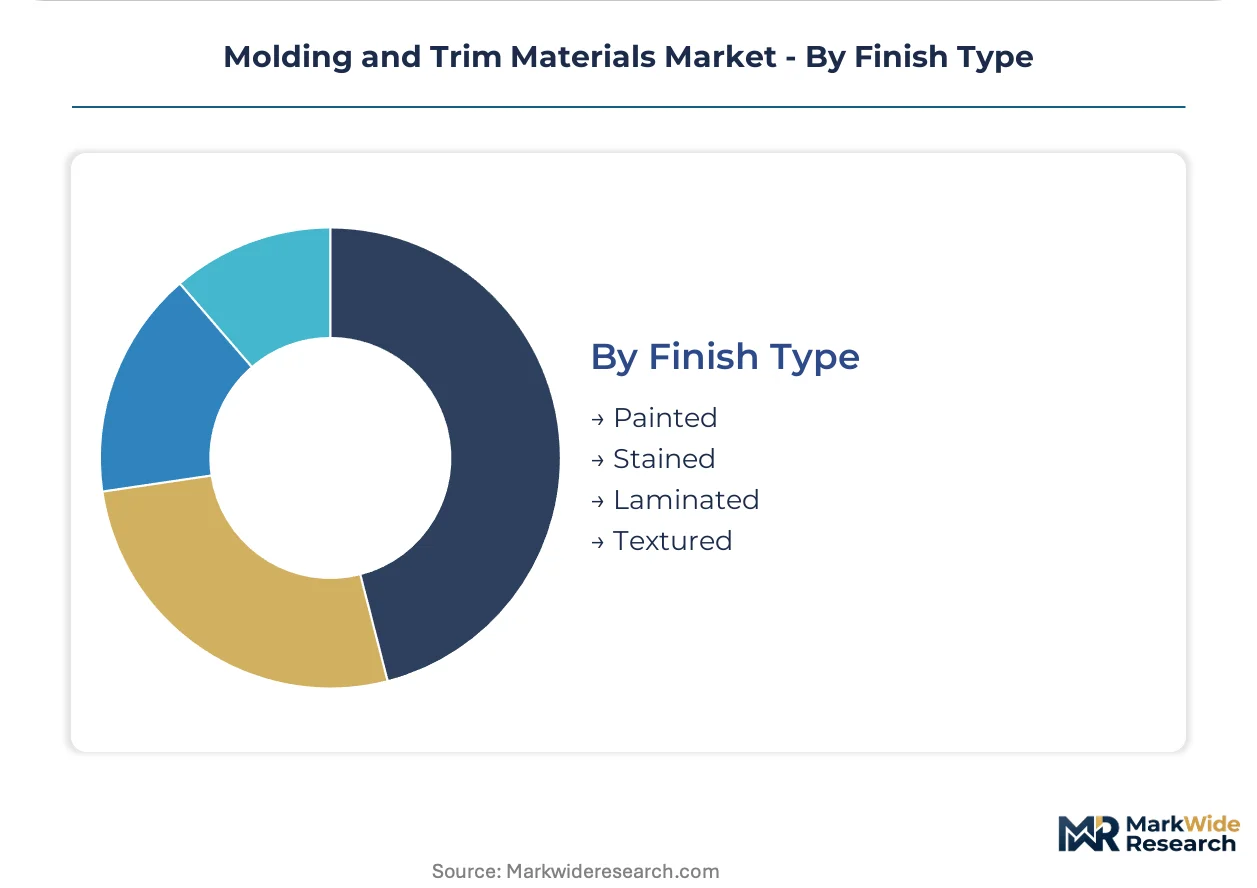
Finish Type:
Surface treatment chemistry faces converging regulatory pressure from EPA emission standards and occupational exposure limits.
- Painted:Waterborne and low-VOC coating systems dominate residential interiors as EPA standards restrict solvent-based formulations.
- Stained:Transparent and semi-transparent finishes showcase natural wood grain in premium residential applications.
- Laminated:Thermally fused surface films provide durability and chemical resistance for commercial high-traffic environments.
- Textured:Embossed and three-dimensional surface treatments simulate wood grain or architectural detail on engineered substrates.
Painted finishes anchor residential volume; laminated surfaces expand in commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American import flows for PVC resin and engineered composite feedstocks, while Rotterdam's Europoort terminal handles comparable volume for European extrusion manufacturers.
United States
Sun Belt metropolitan construction clusters in Phoenix, Houston, and Atlanta outpace national remodeling averages, concentrating demand for moisture-resistant profiles. EPA TSCA Title VI formaldehyde standards accelerate specification of low-emitting MDF and engineered wood products. Dallas-Fort Worth contractors lead adoption of pre-finished profiles through same-day delivery networks.
Germany
Premium residential renovation in Bavaria and Baden-Württemberg sustains demand for paint-grade MDF and hardwood alternatives. ECHA REACH chemical restrictions constrain adhesive formulations across the supply base. The Rhine-Ruhr industrial corridor hosts specialized glass-reinforced polymer composite extrusion for commercial healthcare applications.
China
Urban renewal programs in the Yangtze River Delta and Pearl River Delta generate specification volume for architectural trim in retrofit construction. MIIT industrial standards govern PVC resin quality and emission profiles for interior applications. Guangdong Province extrusion facilities supply both domestic commercial projects and Southeast Asian export markets.
Japan
Seismic retrofit mandates in Tokyo and Osaka drive replacement demand for lightweight, dimensionally stable trim systems. METI energy efficiency guidelines influence material selection in commercial building renovation. The Kansai region maintains concentration of precision CNC machining capacity for bespoke architectural profiles.
Canada
Cross-border supply integration with US manufacturers shapes procurement patterns in Ontario and British Columbia residential construction. Health Canada indoor air quality guidelines align with California CARB-equivalent emission thresholds for imported MDF products. Vancouver's moisture-prone climate elevates PVC and composite specification over solid wood alternatives.
Molding and Trim Materials Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing extrusion and materials science capabilities. The vendor base spans automotive suppliers pivoting into architectural applications, specialized building materials manufacturers, and regional fabrication specialists. Three archetypes dominate: automotive-grade precision extruders, glass-reinforced composite specialists, and pre-finished profile distributors. Competitive moves center on technology licensing agreements and backward integration into resin compounding.
Among automotive-derived fabricators, Flex-N-Gate Corporation, Magna International, and Saint-Gobain exemplify the transfer of precision molding expertise into architectural trim applications. These entities occupy positions where vehicle interior materials science converges with commercial building finish requirements. Saint-Gobain anchors European supply positioning through specialized profile lines, while Magna International represents the lightweight materials extension strategy from transportation into built environments.
| Leading Market Players |
|---|
| Flex-N-Gate Corporation |
| Forvia SA |
| Saint-Gobain |
| Toyoda Gosei |
| Aisin Corporation |
| Magna International |
| Samvardhana Motherson Group |
| Associated Materials |
| Plastic Omnium |
| Others |
Supply & Pricing Matrix
EPA TSCA Title VI formaldehyde standards gate both supplier qualification and price tiering simultaneously, as NAF-certified and CARB-compliant variants command procurement premiums while commodity MDF faces margin compression from reformulation costs. Certification burden stratifies the supply base between low-emission premium tiers and cost-driven standard offerings, with residential renovation contractors arbitraging between labor-saving pre-finished profiles and raw substrate alternatives.
Pricing Analysis
Volume-discount tiering structures separate contractor-direct procurement from distributor-mediated channels, with three-tier pricing stratification across premium certified, standard compliant, and economy commodity grades. Price differentiation centers on emission certification level and pre-finished versus raw form factors, with paint-grade-ready profiles capturing margin through painter labor substitution. Pricing pressure stems from resin input volatility in urea-formaldehyde and phenolic adhesive markets, squeezing commodity MDF producers most acutely while certified manufacturers defend position through specification lock-in.
Supply Chain Analysis
Inventory lead times stretch from Southeast Asian petrochemical clusters through North American extrusion facilities, with PVC resin production concentrated in Thailand and Vietnam creating geographic vulnerability for US-based manufacturers. Raw material dependencies center on chlorinated polymer feedstocks, engineered wood adhesives, and glass-reinforced composite resins. Supply chain risk manifests in single-source vulnerability for Southeast Asian resin supply, with tariff exposure compounding cost structures. Distribution runs through contractor-exclusive digital platforms and traditional lumberyard channels in parallel, with direct-to-contractor e-commerce capturing specification influence from renovation professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as pre-finished profile adoption penetrates the professional renovator segment, with labor scarcity and compressed project timelines accelerating specification migration away from on-site finishing. The convergence of digital procurement channels and low-emission chemistry creates durable tailwinds for certified manufacturers.
For Market Incumbents: Secure backward integration into resin compounding and NAF-certified substrate production to defend margin position against commodity MDF price erosion. Anchor specification authority through exclusive contractor platform partnerships, while investing in CNC machining capacity to capture custom profile demand from historic restoration channels. Threats from automotive-derived precision extruders require technology licensing responses rather than price competition.
For New Entrants and Emerging Players: Lead with direct-to-contractor digital channels targeting Sun Belt metropolitan renovation clusters, where same-day delivery networks and pre-finished product penetration remain underdeveloped. White-space opportunities concentrate in glass-reinforced polymer composite extrusion for healthcare and hospitality wash-down environments, and in 3D-printed hybrid fabrication for bespoke residential applications. Go-to-market positioning should emphasize CARB Phase 2 equivalent compliance ahead of anticipated Northeastern and Midwestern state adoption.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pre-finished profile manufacturing as factory coating equipment and certification infrastructure requirements escalate. Long-term viability favors vertically integrated specialists with captive resin supply and multi-certification audit capabilities. Acquisition targets should display NAF-certified product lines and contractor-direct digital penetration. The signal to watch is state-level CARB-equivalent standard adoption velocity as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive adhesive supply hedges input cost volatility and secures NAF certification pathways. |
| Contractor-Exclusive Digital Platform Launch | Bypasses traditional lumberyard markups while capturing specification authority from renovation professionals. |
| NAF-Certified Product Line Expansion | Preempts EPA and anticipated state-level emission standard tightening with compliant substrate offerings. |
| Hybrid 3D Printing and CNC Machining Investment | Enables mass-customized architectural profiles for historic restoration and bespoke residential channels. |
| Glass-Reinforced Polymer Composite Capacity Addition | Fragments PVC dominance in moisture-prime commercial segments through wash-down durability. |
Research Methodology
A spread of perspectives from residential renovation contractors, MDF plant managers, extrusion facility operators, and distributor procurement leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement documentation, CARB compliance databases, customs and trade flow data, and SEC filings from diversified industrial conglomerates. Bottom-up demand modeling from end-use segments triangulated against top-down supply capacity assessments across material chemistry categories.
Segmentation dimensions modeled include material type, application context, product form, and finish type, with additional granularity on emission certification tier and geographic construction cluster. CAGRs were derived from installation volume trajectories and value-per-unit escalation patterns across the projection horizon. Industry-specific forecast inputs incorporated Sun Belt metropolitan construction permit data and state-level regulatory adoption timelines for CARB-equivalent standards.
The analysis sits within stated boundaries; outcomes outside sustained renovation contractor channel expansion or accelerated emission standard adoption would require recalibration. Forecasts reflect documented assumptions regarding resin cost trajectories and certification timeline compression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Thermoplastic Starch (TPS) Market